
 Distributed Acoustic Sensing (DAS) Market | 2026-2036
Distributed Acoustic Sensing (DAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Acoustic Sensing (DAS) Market Intelligence
Modular interrogator packaging is expanding buyer choice by letting operators scale channel counts without replacing entire fiber optic sensor arrays. Schlumberger Limited leverages its integrated solutions portfolio to bundle DAS hardware with reservoir analytics, anchoring premium positioning in oil and gas exploration. Silixa Ltd competes through specialized high-channel-count interrogators, while OptaSense dominates security surveillance applications with hardened field-deployable systems.
Distributed Acoustic Sensing deploys fiber optic cables as continuous acoustic arrays, using Rayleigh backscatter principles to detect strain and vibration events along tens of kilometers with spatial resolution down to one meter. The technology serves industrial monitoring, subsurface imaging, and perimeter security by converting standard telecom-grade fiber into dense sensor networks. Integrated Solutions command margin pools through software-defined analytics layers that reduce raw data into actionable alerts for pipeline operators. Fiber Optic Sensors represent the fastest-growing hardware category as interrogator miniaturization cuts deployment costs for structural health monitoring of bridges and railways.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration mandates leak detection performance standards that directly shape DAS procurement specifications for interstate pipelines. The EU Green Deal's methane reduction framework and the EPA's updated greenhouse gas reporting rules are forcing energy sector operators to replace point sensors with continuous fiber-based monitoring. Stakeholders must weigh interrogator refresh cycles against emerging phase-sensitive optical time-domain reflectometry advances that promise sharper event classification.
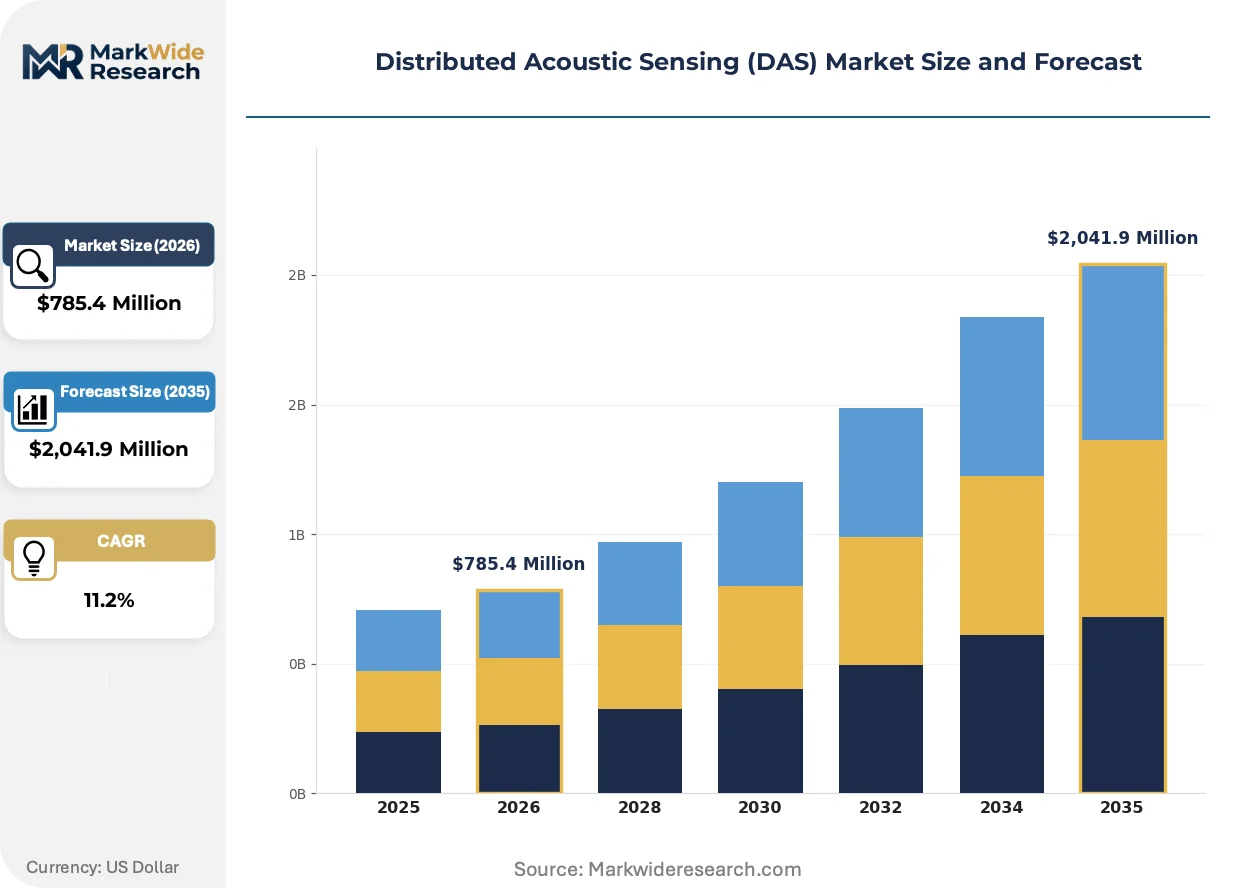
Market Dynamics
The EU Green Deal's methane emission reduction mandates are forcing pipeline operators to replace discrete point sensors with continuous fiber-based monitoring networks, compressing refresh cycles for legacy interrogator hardware.
Growth Catalysts
- EPA Greenhouse Gas Reporting Rules:Updated disclosure requirements compel midstream operators to install kilometer-scale DAS coverage along interstate infrastructure, expanding hardware procurement volumes.
- Permian Basin Infrastructure Investment:Concentrated drilling activity and midstream expansion in West Texas and New Mexico generate concentrated demand for leak detection and third-party intrusion monitoring.
- Interrogator Miniaturization:Advances in photonic integrated circuits reduce field deployment costs for structural health monitoring of bridges and rail corridors.
Market Restraints
- Specialized Photonic Component Supply:Narrow supplier base for high-sensitivity avalanche photodiodes concentrates in German and Japanese precision optics manufacturers, creating single-source vulnerability.
- Technical Spatial Resolution Limits:Rayleigh backscatter physics impose fundamental constraints on event localization precision below one-meter intervals, restricting certain subsurface imaging applications.
- Telecom Fiber Compatibility Constraints:Standard single-mode fiber specifications vary across installed base vintages, forcing costly array replacements or signal conditioning hardware additions.
Strategic Opportunities
- India Rail Corridor Modernization:Dedicated Freight Corridor Corporation and Indian Railways track expansion create untapped demand for continuous track condition and trespass monitoring across 3,000+ kilometer routes.
- Phase-Sensitive Optical Time-Domain Reflectometry Convergence:Integration of φ-OTDR signal processing with conventional DAS interrogators promises sharper event classification and reduced false-positive rates.
- EU Carbon Border Adjustment Mechanism:Impending carbon intensity verification requirements for imported natural gas incentivize European terminals to document methane containment through certified continuous monitoring.
Industry Challenges
- Distributed Acoustic Data Science Talent Gap:Shortage of specialists capable of training machine learning classifiers on Rayleigh backscatter signatures slows deployment of automated threat detection algorithms.
- Multi-Vendor System Integration Complexity:Interoperability gaps between proprietary interrogator firmware and third-party analytics platforms extend commissioning timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Acoustic Sensing (DAS) Market |
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $2,041.9 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Solutions, Fiber Optic Sensors, Monitoring Equipment Technology: Rayleigh Backscatter, Brillouin Scattering, Time-Domain Reflectometry, Phase Shift Application: Structural Health Monitoring, Oil & Gas Exploration, Pipeline Leak Detection, Security Surveillance End User: Telecommunications, Energy Sector, Transportation, Public Safety |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, OptaSense, Silixa Ltd, Fotech Solutions, Omnisens SA, Bandweaver, Hifi Engineering Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Acoustic Sensing (DAS) Market Strategic Shifts & Innovations
Software-defined signal processing architectures are absorbing functionality previously locked in hardware, while regulatory pressure and buyer procurement evolution compress traditional equipment refresh cycles.
Phase-sensitive optical time-domain reflectometry is absorbing the event-detection workloads of conventional coherent detection schemes in high-channel-count deployments. Permian Basin operators and North Sea platform engineers are adopting φ-OTDR modules at twice the pace of standard upgrades. The technology is absorbing margin from legacy interrogator manufacturers by collapsing the distinction between seismic-grade and security-grade hardware tiers.
The EU Green Deal's methane reduction framework mandates continuous emission monitoring for all transmission infrastructure above defined throughput thresholds. Energy sector procurement specifications now embed fiber-based coverage requirements as default technical standards. Midstream operators in the Netherlands and Denmark are responding by bundling DAS hardware tenders with decade-long analytics service agreements.
Buyers are unbundling after-sales service contracts from initial hardware procurement, treating interrogator maintenance and algorithm updates as separately negotiated spend categories. Equipment vendors face compressed attach rates for multi-year service agreements as procurement teams centralize monitoring operations. This pattern is most visible among United States-based master limited partnerships with standardized vendor qualification processes.
Distributed Acoustic Sensing (DAS) Market Segmentation
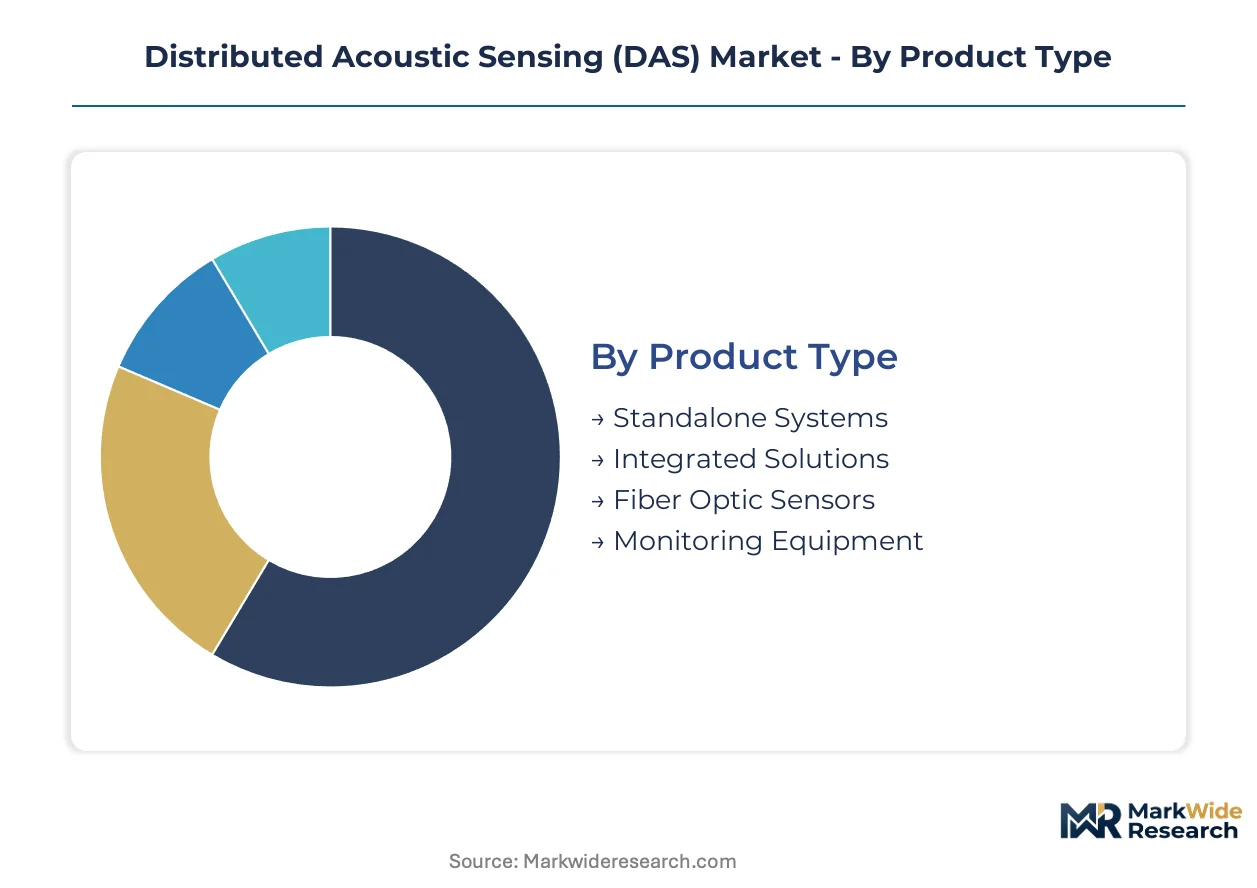
DAS procurement splits across hardware tiers, signal physics, and operational use cases. Buyers weigh interrogator refresh cycles against fiber compatibility and analytics integration depth.
Product Type:
Capital allocation separates buyers pursuing turnkey coverage from those building modular sensor networks.
- Integrated Solutions:Bundled hardware-software platforms embed reservoir analytics or threat classification algorithms directly into interrogator firmware. Permian Basin operators and North Sea platform engineers concentrate procurement here, prioritizing reduced commissioning timelines and unified vendor accountability for kilometer-scale deployments.
- Fiber Optic Sensors:Telecom-grade single-mode fiber converted into continuous acoustic arrays through Rayleigh backscatter interrogation. Demand concentrates in bridge and rail corridor structural health monitoring, where interrogator miniaturization is cutting field deployment costs and enabling dense sensor networks without dedicated infrastructure builds.
- Standalone Systems:Discrete interrogator units requiring separate analytics layer integration.
- Monitoring Equipment:Auxiliary hardware including signal conditioners and array termination assemblies.
Volume sits with Integrated Solutions; growth tilts toward Fiber Optic Sensors.
Technology:
Signal processing physics determines spatial resolution limits and false-positive rates in field conditions.
- Rayleigh Backscatter:Dominant detection mechanism exploiting intrinsic fiber density fluctuations to capture strain and vibration events along tens of kilometers. Pipeline operators across the United States and EU member states standardize on this approach for leak detection, though one-meter spatial resolution floors restrict certain subsurface imaging applications.
- Phase Shift:Emerging φ-OTDR architectures promising sharper event classification through coherent detection of optical phase changes. North Sea engineers and Permian Basin operators are adopting these modules at twice standard upgrade pacing, collapsing distinctions between seismic-grade and security-grade hardware tiers.
- Brillouin Scattering:Temperature-strain discrimination through acoustic phonon interaction with pump pulses.
- Time-Domain Reflectometry:Conventional OTDR for fiber integrity verification and break localization.
Rayleigh Backscatter anchors current installed base; Phase Shift is climbing the fastest.
Application:
Operational environment dictates interrogator specifications for environmental hardening and data throughput.
- Pipeline Leak Detection:Kilometer-scale continuous monitoring for methane emission containment and third-party intrusion alerts. EU Green Deal mandates and EPA greenhouse gas reporting rules are compressing refresh cycles for legacy point-sensor networks across Netherlands, Denmark, and United States interstate infrastructure.
- Oil & Gas Exploration:Subsurface imaging and hydraulic fracture monitoring through borehole-deployed fiber arrays. West Texas and New Mexico drilling activity generates concentrated demand for high-channel-count interrogators capable of real-time reservoir analytics integration.
- Structural Health Monitoring:Bridge deck and rail track condition assessment through surface-mounted fiber.
- Security Surveillance:Perimeter and border monitoring through hardened field-deployable interrogator systems.
Pipeline Leak Detection commands procurement volume; Oil & Gas Exploration shows steepest expansion trajectory.
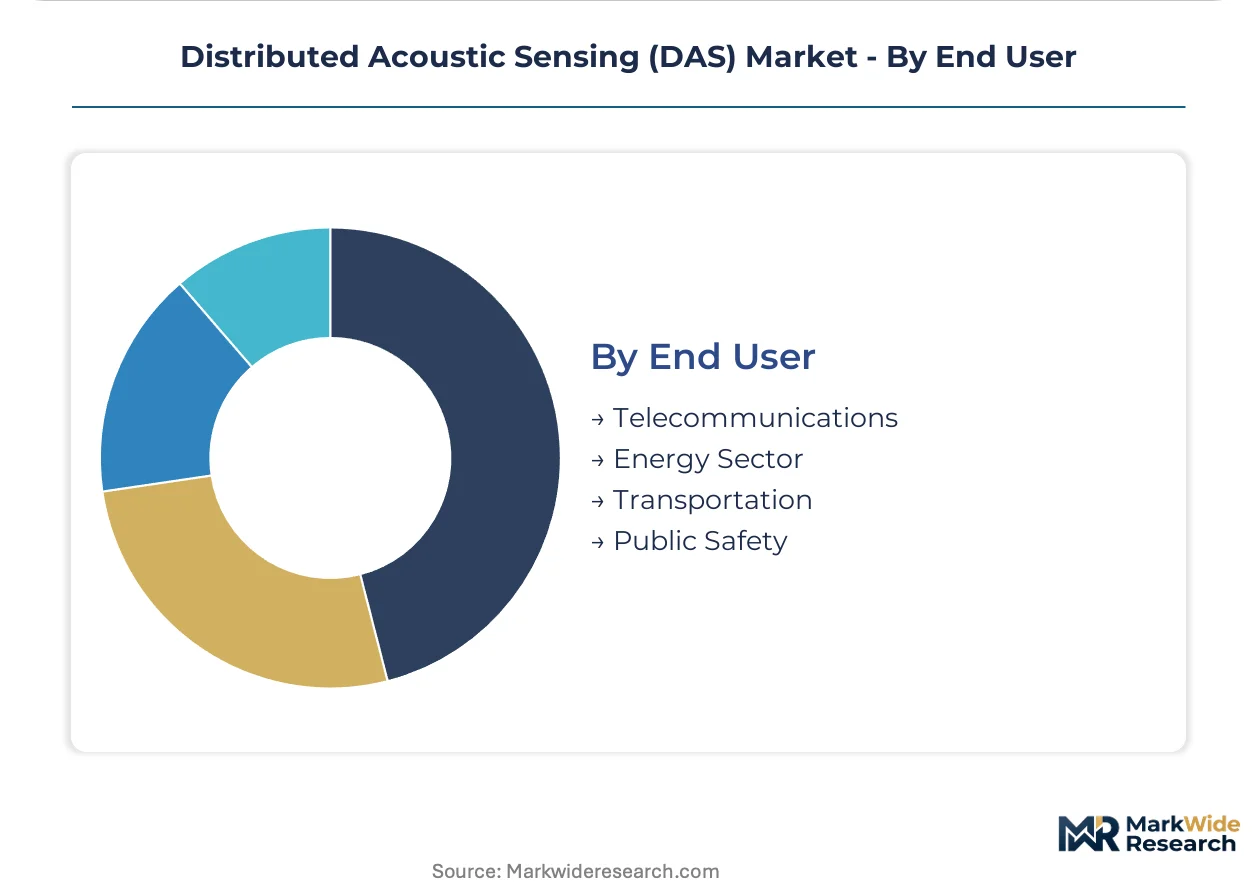
End User:
Industry verticals impose distinct certification requirements and maintenance contract structures.
- Energy Sector:Midstream pipeline operators and upstream exploration companies dominating hardware procurement. United States-based master limited partnerships and European transmission system operators are unbundling after-sales service contracts from initial hardware tenders, treating interrogator maintenance as separately negotiated spend categories.
- Transportation:Rail corridor operators and bridge authorities adopting DAS for track condition and trespass monitoring. India's Dedicated Freight Corridor Corporation and Indian Railways track expansion is creating demand across 3,000-plus kilometer routes for continuous infrastructure assessment.
- Telecommunications:Dark fiber leaseholders repurposing installed cable for sensing applications.
- Public Safety:Border security and critical infrastructure protection agencies.
Energy Sector holds installed base dominance; Transportation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese precision optics manufacturers supplying avalanche photodiodes, while consumption tilts toward United States pipeline operators and European transmission networks upgrading under methane mandates.
United States
Permian Basin midstream expansion and West Texas drilling activity generate hardware procurement for kilometer-scale leak detection networks. EPA greenhouse gas reporting rules compel interstate pipeline operators to replace point sensors with continuous fiber monitoring. Master limited partnerships in Texas and New Mexico are unbundling service contracts from hardware tenders.
Germany
High-sensitivity photonic component manufacturing anchors supply-side concentration for avalanche photodiodes and precision optics. EU Green Deal methane reduction mandates force transmission operators to upgrade legacy interrogator systems across Ruhr industrial corridors. Bavaria-based precision manufacturers face single-source vulnerability risks from concentrated component demand.
Netherlands
North Sea platform engineers adopt phase-sensitive optical time-domain reflectometry modules at accelerated refresh cycles for subsurface imaging. EU Green Deal continuous monitoring requirements apply to Groningen gas field infrastructure and Rotterdam terminal networks. Midstream operators bundle DAS tenders with decade-long analytics service agreements.
India
Dedicated Freight Corridor Corporation and Indian Railways track expansion creates demand across 3,000-plus kilometer routes for structural health monitoring. The country's national railway infrastructure programs prioritize continuous track condition and trespass detection systems. Western Dedicated Freight Corridor segments through Gujarat and Maharashtra represent initial deployment concentrations.
United Kingdom
North Sea decommissioning and remaining production platforms drive adoption of borehole-deployed fiber arrays for reservoir monitoring. The country's offshore regulatory framework emphasizes continuous infrastructure integrity verification. Aberdeen-based engineering clusters integrate DAS hardware with seismic analytics for enhanced oil recovery operations.
Distributed Acoustic Sensing (DAS) Market Key Industry Players
The competitive structure tilts toward integrated energy service conglomerates bundling hardware with reservoir analytics. Three tiers separate these full-stack providers from specialized interrogator manufacturers and regional system integrators. Dominant competitive moves include vertical integration into photonic component supply and geographic expansion through state-level procurement certifications.
Within the integrated solutions tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company represent the energy service archetype that bundles DAS hardware with subsurface analytics. These conglomerates occupy positions anchored by unified vendor accountability for kilometer-scale deployments. Silixa Ltd and OptaSense exemplify contrasting specialists—high-channel-count interrogator engineering versus hardened field-deployable security systems—each carving defensible positions through technical differentiation rather than portfolio breadth.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| OptaSense |
| Silixa Ltd |
| Fotech Solutions |
| Omnisens SA |
| Bandweaver |
| Hifi Engineering Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up interrogator specialists in Germany and Japan anchor component supply discipline, translating narrow avalanche photodiode availability into sustained pricing power for high-sensitivity photonic tiers while compressing margins for standard-grade hardware.
Pricing Analysis
Margin tightening in standard-grade interrogators reflects interrogator miniaturization and photonic integrated circuit commoditization. Three-tier pricing structure across premium, standard, and economy levels separates seismic-grade φ-OTDR modules from security-grade field systems and basic structural health units. Cost-down pressure on economy tiers accelerates because Indian rail authorities and bridge operators prioritize deployment scale over precision specifications. Energy sector buyers in the United States and Netherlands show lowest price sensitivity, accepting decade-long bundled service agreements.
Supply Chain Analysis
Avalanche photodiode supply rests on German and Japanese precision optics manufacturers, with secondary concentration in Taiwanese photonic integrated circuit foundries. High-sensitivity detector arrays, specialty pump lasers, and telecom-grade single-mode fiber constitute critical input dependencies. Single-source vulnerability concentrates in Bavaria-based component houses serving both seismic and security interrogator tiers. Distribution runs through direct OEM relationships for integrated solutions and regional system integrators for standalone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side concentration in precision photonic components props pricing power for tier-one interrogator manufacturers, creating durable margin pools even as standard-grade hardware faces commoditization pressure.
For Market Incumbents: Deploy backward integration into photonic integrated circuit design to capture margin from miniaturization trends. Schlumberger Limited and Halliburton Company should consolidate high-channel-count interrogator engineering talent before φ-OTDR architectures collapse hardware tier distinctions. Locking decade-long analytics service agreements with European transmission operators insulates revenue from hardware refresh cycle compression. For New Entrants and Emerging Players: Digital-channel partnerships with Indian rail infrastructure project offices offer lowest-friction entry paths. The Dedicated Freight Corridor Corporation's 3,000-plus kilometer expansion represents the most penetrable white-space target, with track condition monitoring specifications still fluid. Positioning around interrogator miniaturization for bridge and rail applications avoids direct confrontation with energy-sector incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized φ-OTDR module developers in Netherlands and United Kingdom North Sea clusters. Long-term viability hinges on software-defined signal processing capabilities that transcend hardware tier boundaries. Watch for EPA enforcement acceleration on interstate pipeline leak detection as inflection indicator for integrated solutions demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photonic Components | Captures margin from German and Japanese precision optics suppliers. |
| φ-OTDR Module Development | Collapses seismic-security hardware distinctions for North Sea engineers. |
| Decade-Long Service Agreement Bundling | Locks Netherlands and Denmark midstream operators into recurring revenue. |
| Indian Rail Corridor Certification | Opens 3,000-plus kilometer routes for structural health monitoring deployment. |
| Machine Learning Classifier Investment | Addresses Rayleigh backscatter data science talent gaps slowing automated threat detection. |
Research Approach
Independent corroboration across pipeline operator procurement directors, photonic component manufacturing executives, and rail infrastructure project engineers underwrites the qualitative findings. Primary fieldwork with Schlumberger Limited reservoir analytics teams, Silixa Ltd interrogator engineering leads, and OptaSense security deployment specialists combined with secondary validation through EPA greenhouse gas reporting rulemakings, EU Green Deal methane framework documentation, and FERC interstate pipeline safety filings. Bottom-up channel checks across United States master limited partnerships and top-down regulatory impact modeling triangulate volume estimates.
Comparable-period anchoring to pre-mandate baseline years established reference points for EU Green Deal and EPA rule-driven refresh cycle compression. The analytical framework segments across hardware tier, signal physics mechanism, operational use case, and end-user vertical throughout the projection horizon. CAGRs derive from interrogator shipment trajectories, fiber deployment linear footage, and analytics attachment rate assumptions. Permian Basin drilling activity curves and North Sea platform decommissioning timelines feed energy sector demand modeling.
The model holds under sustained regulatory enforcement of methane emission mandates; deviation in EPA rule delay or EU carbon border adjustment mechanism suspension would shift upgrade pacing. Forecasts reflect assumptions on photonic component supply continuity and machine learning classifier deployment velocity. A small set of named triggers warrants ongoing watch: German avalanche photodiode export restrictions, Indian rail tender award timing, and phase-sensitive optical time-domain reflectometry patent litigation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Pressure Sensor Market