
 Sensor Cable Market | 2026-2036
Sensor Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Cable Market Analytics
Industrial-grade shielding specifications is unwinding legacy commodity positioning across the Sensor Cable Market. TE Connectivity Ltd. leverages deep vertical integration in connector-cable assemblies to command premium positioning in aerospace and automotive channels. Prysmian Group anchors European supply through advanced fiber-optic sensor cable manufacturing for energy infrastructure monitoring. Belden Inc. differentiates via precision-engineered signal transmission solutions that serve industrial automation and broadcast applications.
Sensor cables are engineered conductors with integrated sensing elements or signal transmission pathways, typically incorporating shielded copper alloys, fluoropolymer insulation, or silica-based optical fibers to ensure electromagnetic immunity and thermal stability across operational temperatures spanning negative fifty-five to positive three hundred degrees Celsius. These assemblies serve as the physical layer enabling real-time data acquisition from transducers to control systems in mission-critical environments. Optical sensor cables are capturing disproportionate investment as distributed acoustic sensing expands in oilfield and perimeter security deployments, while piezoelectric sensor technology leads high-frequency vibration monitoring in precision manufacturing. The wireless sensors segment remains constrained by power delivery and latency limitations, though it carves niche traction in retrofit industrial environments where cabling retrofit costs prove prohibitive.
FCC equipment authorization requirements govern electromagnetic emissions for sensor cables deployed in US industrial and consumer electronics applications, while EU CE marking under the Machinery Directive and RoHS substance restrictions shape product compliance thresholds for European market access. ISO/IEC standards for electromagnetic compatibility and functional safety provide cross-border design benchmarks that reduce certification fragmentation for multinational OEMs. Stakeholders must weigh the capital intensity of optical fiber sensor cable capacity against the margin compression risk in analog sensor commodity segments as specification tiers diverge.
Market Dynamics
Smart factory deployments are compressing specification cycles across the Sensor Cable Market, forcing suppliers to pre-certify cable assemblies for multiple industrial automation protocols before buyer engagement rather than responding to post-bid technical queries.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for functional safety are mandating shielded sensor cable upgrades in European industrial equipment, pulling demand toward certified assemblies.
- Automotive OEMs:Electric vehicle battery management systems require temperature-stable sensor cables with fluoropolymer insulation for thermal runaway monitoring in high-density pack architectures.
- Distributed acoustic sensing:Fiber-optic sensor cables are displacing electromechanical alternatives in oilfield monitoring and perimeter security installations.
Market Restraints
- Copper price volatility:Shielded conductor raw material costs swing with commodity markets, compressing margins on analog sensor cable contracts with fixed pricing terms.
- Optical fiber capacity concentration:Advanced silica-based sensor cable manufacturing clusters in Germany and China, creating supply vulnerability for buyers outside these geographies.
- Wireless substitution:Battery-harvested sensor nodes eliminate cabling in retrofit industrial environments where installation labor exceeds hardware cost.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for manufacturing automation are creating first-mover advantage for sensor cable suppliers establishing local certification capabilities.
- Medical device convergence:ISO 13485-compliant sensor cables for patient monitoring equipment represent an adjacent expansion path from industrial-grade product platforms.
- Channel integration:Direct specification relationships with system integrators are displacing distributor-led sales in large smart factory deployments.
Industry Challenges
- EMC certification timelines:FCC equipment authorization and EU notified body assessments extend product launch cycles by six to twelve months for multi-protocol sensor cables.
- Legacy protocol integration:Fieldbus-to-Ethernet-IP transition requires backward-compatible cable designs that increase BOM complexity without corresponding price premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Cable Market |
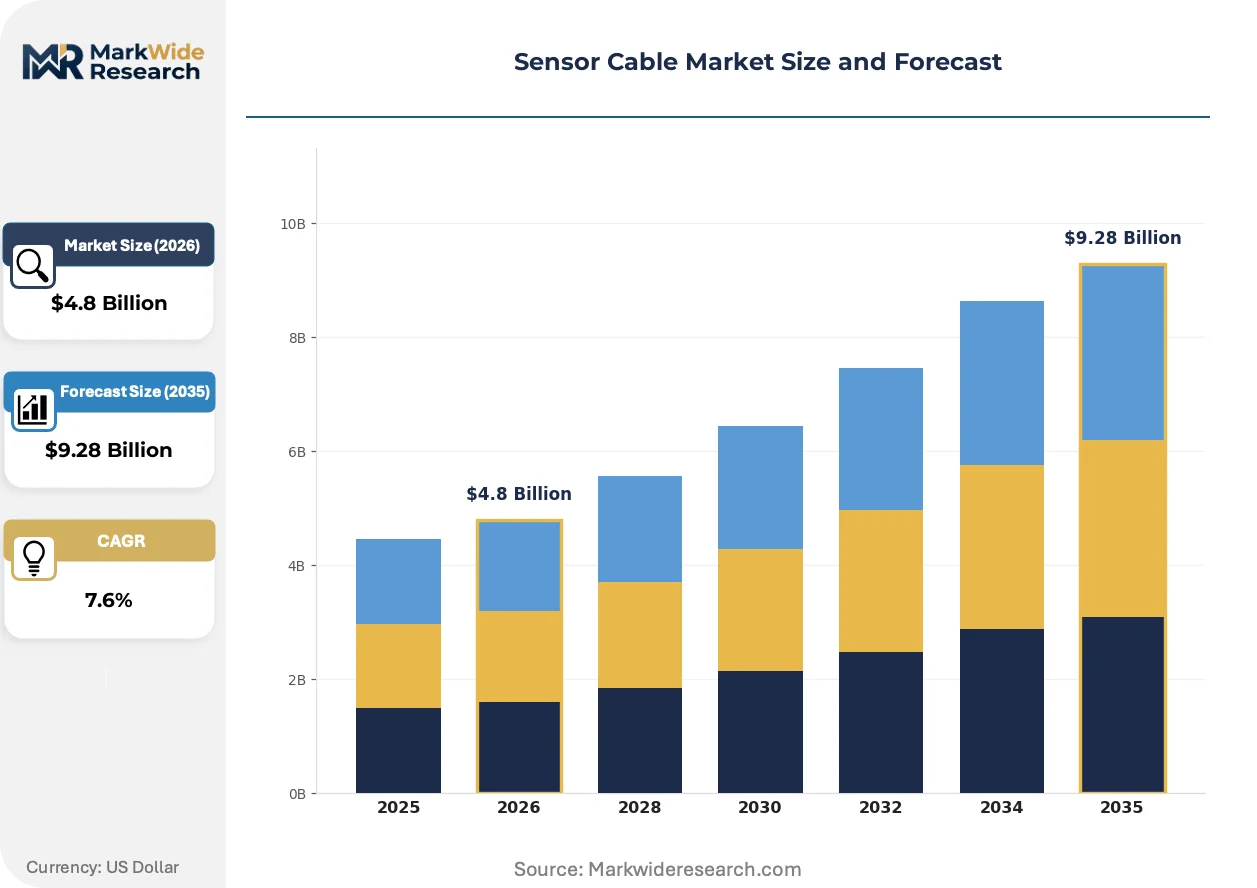
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, Pressure Sensors, Optical Sensors, Humidity Sensors Technology: Analog Sensors, Digital Sensors, Wireless Sensors, Piezoelectric Sensors End User: Automotive Industry, Aerospace Sector, Consumer Electronics, Industrial Automation Application: Temperature Monitoring, Pressure Control, Environmental Sensing, Motion Detection |
| Companies Covered | TE Connectivity Ltd., Schneider Electric SE, Prysmian Group, Corning Incorporated, NKT Photonics A/S, Silixa Ltd., Yokogawa Electric Corporation, Leoni AG, Belden Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Cable Market Evolving Landscape
Material science advances and regulatory tightening are bifurcating the Sensor Cable Market into specification-intensive premium tiers and cost-optimized commodity segments with diverging competitive requirements.
Polyimide-based thin-film sensor cable insulation is miniaturizing conductor footprints for medical imaging and aerospace applications where weight and bend radius constrain design. Diagnostic equipment manufacturers in Switzerland and Massachusetts are qualifying these assemblies for MRI gradient coil integration. The technology is compressing traditional PTFE-insulated cable volumes in premium specification tiers.
REACH substance restrictions are phasing out legacy halogenated flame retardants in European-market sensor cables, forcing reformulation of PVC and PE jacket compounds. Compound suppliers in the Netherlands and Germany are commercializing phosphorus-nitrogen alternatives at 15-20% cost premiums. Automotive harness manufacturers are absorbing these increases rather than risking CE marking withdrawal.
Buyer engineering teams are consolidating vendor panels to single-source sensor cable specifications across multiple plant locations, compressing qualification cycles and raising switching costs. System integrators in Michigan and Bavaria are driving this consolidation to simplify spare parts logistics. The pattern is most pronounced in automotive tier-one supplier networks where OEM audit requirements propagate down the supply chain.
Sensor Cable Market Segmentation
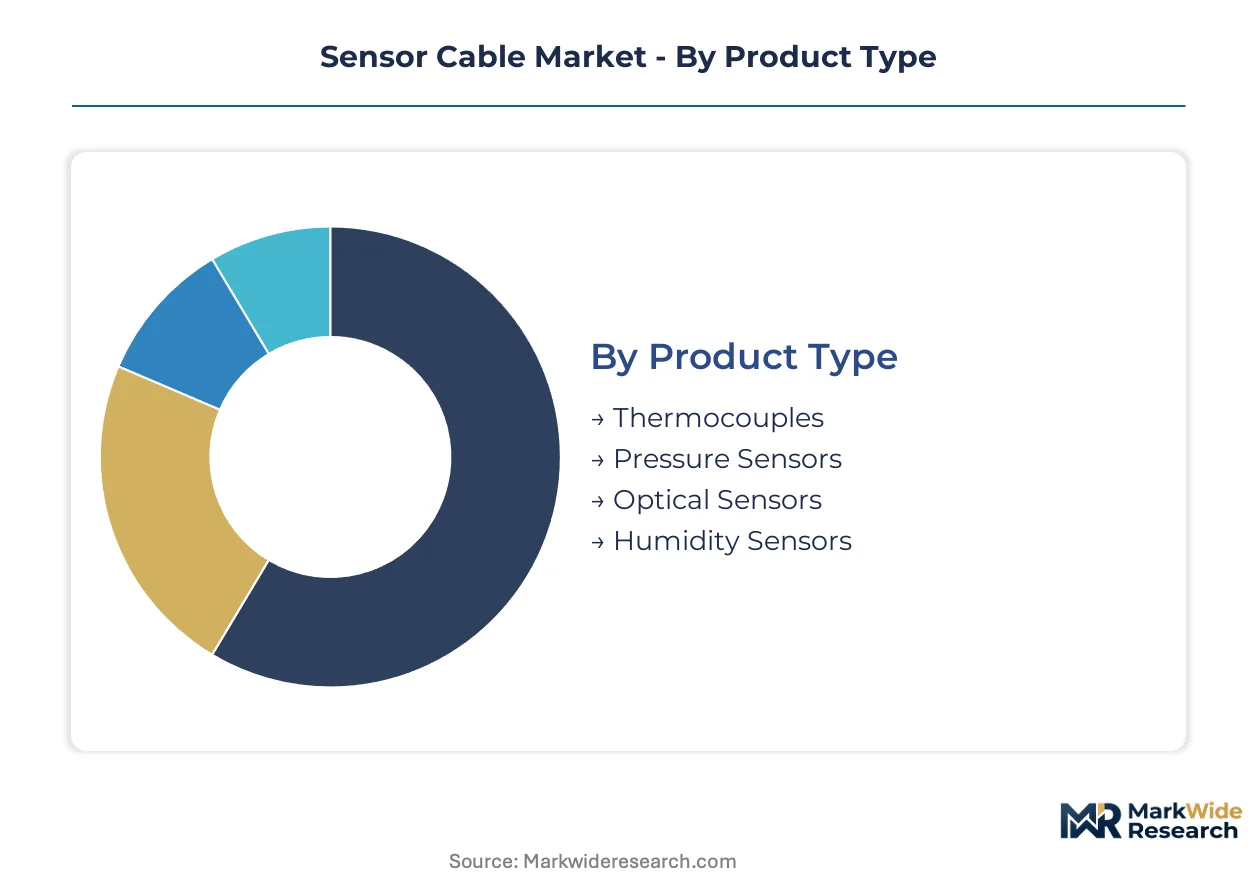
Sensor cable procurement decisions bifurcate sharply between specification-intensive applications where certification drives vendor selection and cost-optimized deployments where interchangeability dominates. The report examines four primary segmentation dimensions that capture this divergence in buyer behavior and supplier positioning.
Product Type:
CE marking under the EU Machinery Directive and RoHS substance restrictions create divergent compliance burdens across product categories, with fluoropolymer-insulated assemblies facing stricter thermal stability testing than commodity PVC-jacketed alternatives.
- Optical Sensors:Silica-based fiber-optic cables with distributed acoustic sensing capability serve oilfield monitoring and perimeter security installations. Demand concentrates in Germany and Texas where energy infrastructure operators displace electromechanical alternatives for kilometer-scale coverage without signal degradation.
- Thermocouples:Shielded copper-nickel alloy conductors with mineral insulation withstand temperatures spanning negative two hundred to positive twelve hundred degrees Celsius in furnace and exhaust monitoring. Automotive OEMs in Stuttgart and Detroit specify these for electric vehicle battery thermal runaway detection.
- Pressure Sensors:Piezoresistive elements bonded to stainless steel diaphragms transmit strain signals through fluoropolymer-insulated cables.
- Humidity Sensors:Polymer capacitive elements with polyimide cable insulation serve cleanroom and pharmaceutical storage applications.
Established volume favors thermocouples in industrial heat monitoring; emerging adoption favors optical sensors in distributed sensing networks.
Technology:
Cost tiers separate legacy analog implementations from digital and wireless alternatives, with piezoelectric assemblies commanding premium positioning in vibration analysis where frequency response requirements exclude cheaper technologies.
- Piezoelectric Sensors:Quartz or ceramic crystal elements generate charge signals proportional to mechanical stress, requiring low-noise coaxial cable with copper-braid shielding. Precision manufacturers in Switzerland and Japan deploy these for spindle condition monitoring in CNC machining centers where sub-micron vibration detection prevents tool failure.
- Digital Sensors:Integrated ADC architectures with Ethernet-IP or PROFINET protocol compatibility reduce wiring complexity in smart factory retrofits. System integrators in Michigan and Bavaria specify these for brownfield deployments where analog-to-digital conversion at the sensor eliminates separate I/O modules.
- Analog Sensors:Voltage or current loop outputs dominate legacy fieldbus installations with 4-20mA signaling.
- Wireless Sensors:Battery-harvested nodes with LoRa or Bluetooth Low Energy radios eliminate cabling in retrofit environments where installation labor exceeds hardware cost.
Procurement patterns favor analog sensors in mature process industries; specification cycles favor digital sensors in new smart factory deployments.
End User:
Customer type determines certification intensity, with automotive and aerospace buyers imposing vendor audit requirements that propagate through tier-one supplier networks while consumer electronics procurement prioritizes cost scale over technical documentation depth.
- Automotive Industry:Temperature-stable sensor cables with fluoropolymer insulation serve battery management systems and powertrain monitoring. OEMs in Germany anchor premium specification sourcing, with harness manufacturers absorbing REACH-driven material cost premiums to maintain CE marking compliance.
- Aerospace Sector:AS9100-certified assemblies with polyimide insulation and lightweight aluminum shielding meet FAA airworthiness requirements for flight control and engine monitoring. Manufacturers in Toulouse and Seattle specify these for weight-constrained avionics bays.
- Industrial Automation:Multi-protocol shielded cables serve programmable logic controller networks and robotic workcells.
- Consumer Electronics:Cost-optimized unshielded cables with PVC jackets serve appliance and wearable device applications.
Margin structures favor aerospace sector certification premiums; volume scale favors automotive industry procurement consolidation.
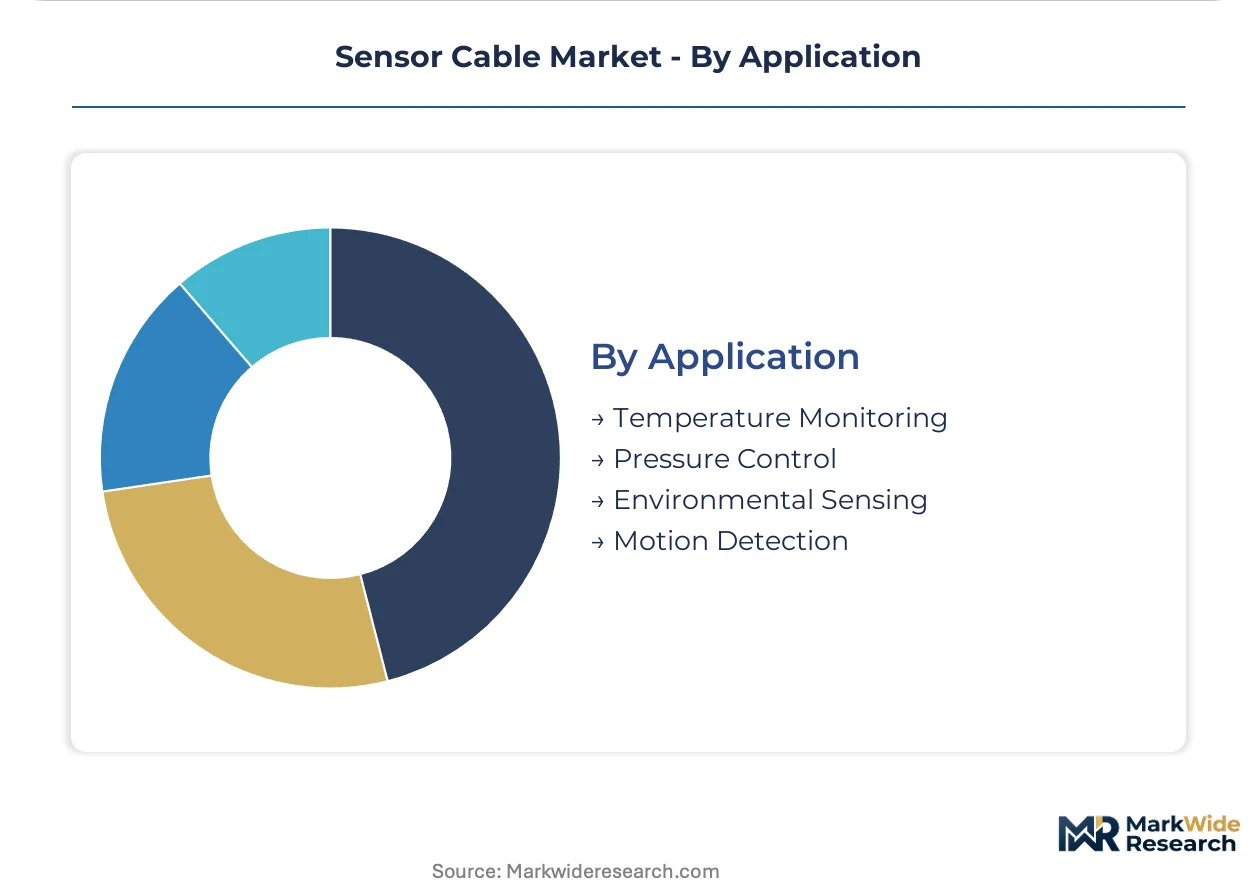
Application:
Functional requirements drive material selection divergence, with temperature monitoring demanding thermal stability that environmental sensing and motion detection specifications rarely require.
- Temperature Monitoring:Mineral-insulated metal-sheathed cables withstand thermal cycling and mechanical abuse in furnace, exhaust, and battery pack applications. Energy infrastructure operators in Texas and North Dakota specify these for pipeline and compressor station monitoring where flame resistance mandates override cost considerations.
- Pressure Control:Oil-filled cable assemblies with stainless steel armor protect silicon strain gauges from corrosive process media.
- Environmental Sensing:Low-cost PVC-jacketed cables serve humidity and gas detection in building automation.
- Motion Detection:Flexible stranded conductors with high-bend-radius insulation serve accelerometer and gyroscope connections in robotics.
Specification intensity favors temperature monitoring in safety-critical deployments; commoditization pressure favors environmental sensing in building automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor cable exports flow primarily to automotive assembly plants in the United States and Mexico, while Chinese manufacturers supply cost-optimized volumes to Southeast Asian industrial automation projects.
Germany
Automotive OEMs in Stuttgart and Munich drive fluoropolymer-insulated cable procurement for electric vehicle battery monitoring. CE marking under the EU Machinery Directive mandates shielded assemblies for functional safety compliance. The Baden-Württemberg industrial corridor anchors premium specification sourcing for tier-one harness manufacturers.
United States
Texas oilfield operators deploy distributed acoustic sensing cables for pipeline monitoring across Permian Basin infrastructure. FCC equipment authorization governs electromagnetic emissions for industrial automation deployments. Houston energy clusters concentrate fiber-optic sensor cable demand for perimeter security and subsea applications.
China
Smart factory retrofits in the Yangtze River Delta consume multi-protocol shielded cables for robotic workcell integration. GB standards and MIIT regulations shape electromagnetic compatibility certification for domestic equipment. Shenzhen electronics manufacturers source cost-optimized sensor assemblies for consumer device and appliance production.
India
PLI scheme incentives for manufacturing automation accelerate sensor cable procurement across Gujarat and Maharashtra industrial corridors. BIS certification requirements create localization pressure for foreign suppliers entering the market. Pune automotive clusters drive specification-intensive sourcing for electric vehicle component testing.
Japan
Precision manufacturers in Nagoya and Osaka deploy piezoelectric sensor cables for CNC spindle condition monitoring. METI industrial standards govern signal integrity requirements for smart factory equipment. The Chubu region concentrates high-frequency vibration sensing demand among machine tool builders and semiconductor equipment makers.
Sensor Cable Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with public companies leveraging balance sheet capacity for multi-protocol pre-certification while private fabricators exploit agility in custom shielding specifications. The vendor base fragments across three capability layers: integrated connector-cable assemblers, standalone conductor specialists, and optical fiber sensing technology developers. Dominant competitive moves include backward integration into fluoropolymer compounding and strategic partnerships with system integrators for smart factory specification capture.
Within the integrated assembly tier, TE Connectivity Ltd. and Prysmian Group exemplify vertical control over connector-cable combinations. Belden Inc. occupies a position among precision signal transmission specialists serving industrial automation channels. Corning Incorporated anchors the optical fiber sensor cable segment through silica-based manufacturing capabilities. These three listed entities represent divergent strategic archetypes: TE Connectivity Ltd. leverages aerospace and automotive channel depth, Prysmian Group concentrates European energy infrastructure supply, and Belden Inc. differentiates through protocol-specific engineering for factory floor deployments.
| Leading Market Players |
|---|
| TE Connectivity Ltd. |
| Schneider Electric SE |
| Prysmian Group |
| Corning Incorporated |
| NKT Photonics A/S |
| Silixa Ltd. |
| Yokogawa Electric Corporation |
| Leoni AG |
| Belden Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German fluoropolymer compounding facilities shapes both supply concentration and price floors for specification-intensive sensor cable tiers. Scale economies in silica-based fiber manufacturing anchor premium positioning while marginal producers in Southeast Asia absorb cost compression in commodity analog segments.
Pricing Analysis
Current-generation optical sensor cables with distributed acoustic sensing capability command substantial premiums over prior-generation electromechanical alternatives and next-generation wireless prototypes. Three-tier pricing structure across premium fluoropolymer-insulated, standard PVC-jacketed, and economy unshielded tiers reflects certification intensity and thermal stability ratings. Pricing pressure stems from copper price volatility compressing margins on fixed-contract analog sensor cable volumes. Automotive OEMs exhibit lowest price sensitivity due to CE marking compliance mandates, while building automation integrators drive commoditization in environmental sensing applications.
Supply Chain Analysis
Just-in-time inventory strategies dominate German automotive harness manufacturing, while Texas oilfield operators maintain strategic stockpiles of fiber-optic sensing cables for kilometer-scale deployment contingencies. Manufacturing concentrates in Germany, China, and the United States for advanced assemblies. Raw material flows draw from Chilean copper mining, Japanese fluoropolymer resin production, and Chinese optical fiber preform manufacturing. Single-source vulnerability concentrates in German silica-based fiber drawing capacity. Distribution runs through tier-one harness manufacturers and system integrators rather than traditional electrical distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated automotive OEM procurement committees and system integrator specification panels, compressing vendor counts and raising switching costs across the Sensor Cable Market.
For Market Incumbents: Secure backward integration into fluoropolymer compounding to defend margin position against REACH-driven material cost inflation. Pre-certify cable assemblies for multiple industrial automation protocols before buyer engagement to compress qualification cycles. Channel control through direct specification relationships with Bavarian and Michigan-based system integrators offsets distributor displacement risk.
For New Entrants and Emerging Players: BIS certification fast-track programs for India PLI scheme beneficiaries create white-space entry points before established players localize production. Target medical device convergence opportunities requiring ISO 13485-compliant sensor cable platforms. Pursue brownfield smart factory retrofit segments where digital sensor protocol compatibility commands specification premiums over legacy analog alternatives.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors optical fiber sensing specialists with captive silica manufacturing capabilities over analog commodity assemblers facing margin compression. Long-term viability across the analysis window rests on protocol-agnostic engineering capacity and multi-regional certification infrastructure. Monitor distributed acoustic sensing deployment rates in Permian Basin and North Sea infrastructure as inflection indicators for fiber-optic cable demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Pre-Certification | TE Connectivity and Belden leverage pre-certified assemblies to compress smart factory procurement cycles. |
| Backward Integration into Fluoropolymer Compounding | Prysmian Group's captive resin production insulates margin position from REACH substance restriction cost shocks. |
| Medical Device Platform Extension | Polyimide insulation specialists in Switzerland expand from aerospace into MRI gradient coil sensor cable qualification. |
| India Localization Partnership | Leoni AG and emerging entrants establish Pune manufacturing to capture PLI scheme automation incentives. |
| Distributed Acoustic Sensing Capacity Expansion | Corning Incorporated and Silixa Ltd. scale silica fiber drawing for oilfield and perimeter security kilometer-scale deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive OEM procurement directors, industrial automation system integrators, tier-one harness manufacturing engineers, and optical fiber sensing technology developers. Secondary validation drew from FCC equipment authorization databases, EU Machinery Directive notified body assessments, SEC 10-K filings of listed cable assemblers, and customs trade data for fluoropolymer resin and copper alloy imports. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology generation, end-user industry, and application function dimensions.
Across the projection horizon, analytical frameworks modeled volume and value trajectories by disaggregating procurement patterns across thermocouple, optical sensor, pressure sensor, and humidity sensor product categories. Segmentation dimensions incorporated piezoelectric versus digital versus analog versus wireless technology tiers, automotive versus aerospace versus industrial automation versus consumer electronics end-user concentrations, and temperature monitoring versus pressure control versus environmental sensing versus motion detection applications. CAGRs were derived from regression analysis of historical procurement data against industrial automation capex cycles and electric vehicle production ramp rates.
Underlying assumptions cover sustained EU Machinery Directive enforcement, stable copper price corridors, and optical fiber capacity expansion timelines, with deviation risk concentrated in wireless substitution acceleration and geopolitical trade restriction escalation. Forecasts reflect these documented assumptions with sensitivity bands for commodity volatility and regulatory amendment scenarios. Revision becomes warranted when battery-harvested sensor node cost-performance ratios cross thresholds competitive with cabled alternatives in brownfield retrofit environments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
North America Wire and Cable Market
Cables
High Voltage Cables Market
Cables
United States Cable Accessories Market
Cables
Polyurethane Cable Market
Cables
Latin America Wire and Cable Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
Direct Attach Cable Market
Cables
Cable Management Accessories Market
Cables
UK Cables Market
Cables
Cable Fault Locator Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Low-Temperature Cable Market
Cables
Power and Signal Cables Market
Cables
Underground Cable Market
Cables
Electric Vehicle Cables Market
Cables
Power Cable Accessories Market