
 XLPE Cables Market | 2026-2036
XLPE Cables Market Size, Share, and Industry Trends Forecast 2026-2036
XLPE Cables Market Intelligence
Project finance tied to long-term power purchase agreements is narrowing the field of cable suppliers capable of underwriting multi-year offshore wind and interconnection projects. LS Cable & System leverages its integrated submarine and land cable manufacturing footprint to anchor large-scale renewable tenders across Asia-Pacific. Prysmian Group sustains competitive positioning through vertical control over compound formulation and extrusion capacity. Nexans differentiates via specialized high-voltage direct current XLPE systems for subsea transmission corridors.
Cross-linked polyethylene cables utilize thermoset insulation created through peroxide or silane crosslinking of polyethylene, yielding operating temperatures up to 90°C continuous and 250°C short-circuit tolerance for transmission and distribution networks. Medium voltage and high voltage product types command the dominant share of project value, with extra high voltage segments representing the fastest-growing margin pool as utilities deploy 220 kV to 500 kV systems for long-haul renewable integration. Within application segments, renewable energy and power transmission deployments are outpacing industrial plant installations, while flame retardant and water-resistant insulation material grades are gaining preference in subsea and tunnel installations where failure costs are catastrophic.
China's GB standards and NMPA-equivalent cable certification requirements, alongside the EU's CE marking and RoHS material restrictions, are elevating compliance costs for manufacturers seeking cross-border market access. The US National Electrical Code and FERC interconnection standards further shape product specifications for North American utility procurement. Stakeholders must monitor how evolving carbon border adjustment mechanisms and recycled content mandates will reshape compound sourcing and manufacturing location decisions.
Market Dynamics
State grid procurement in China is compressing supplier margins while EU F-Gas Regulation mandates accelerate replacement cycles for legacy insulated networks, forcing manufacturers to absorb compound cost volatility or lose tender eligibility.
Growth Catalysts
- Offshore wind interconnection mandates:Renewable energy developers in Germany, Denmark, and the United Kingdom require 220 kV to 500 kV submarine XLPE systems for North Sea grid integration.
- REACH and RoHS material restrictions:The European Union's chemical compliance frameworks are phasing out PVC and oil-impregnated paper insulation in favor of halogen-free cross-linked polyethylene alternatives.
- Silane crosslinking process improvements:Steam-cure and dry-silane methods are reducing manufacturing cycle times and energy consumption for medium voltage cable production.
Market Restraints
- Ethylene and peroxide input volatility:Petrochemical feedstock price swings compress compound margins and destabilize long-term project bidding.
- Submarine cable supply concentration:Only three European and two Asian manufacturers possess integrated vertical lighthouses capable of extruding and armoring high voltage submarine cores.
- EPR and HPTE insulation substitution:Ethylene propylene rubber and high performance thermoplastic elastomers are capturing niche applications requiring extreme flexibility or rapid installation.
Strategic Opportunities
- India transmission grid expansion:The Central Electricity Authority's Green Energy Corridors program requires thousands of kilometers of 132 kV and 220 kV XLPE for solar and wind evacuation.
- HVDC-XLPE hybrid systems:Converter station developers are specifying extruded DC insulation for subsea interconnectors previously reserved for mass-impregnated paper technology.
- Direct utility e-procurement platforms:State Grid Corporation of China and TenneT are migrating tender processes to digital exchanges, reducing distributor intermediation.
Industry Challenges
- Compound formulation chemist scarcity:The specialized knowledge required for peroxide-initiated crosslinking kinetics and tree-retardant additive packages is concentrated among retiring specialists in Japan and Germany.
- Type test and pre-qualification timelines:IEC 62067 and CIGRE TB 303 long-term testing protocols extend product validation to 24-36 months, freezing working capital.
- Legacy oil-filled cable decommissioning coordination:Utilities face parallel obligations to remove asbestos-served lead sheaths while installing replacement XLPE circuits in constrained urban duct banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | XLPE Cables Market |
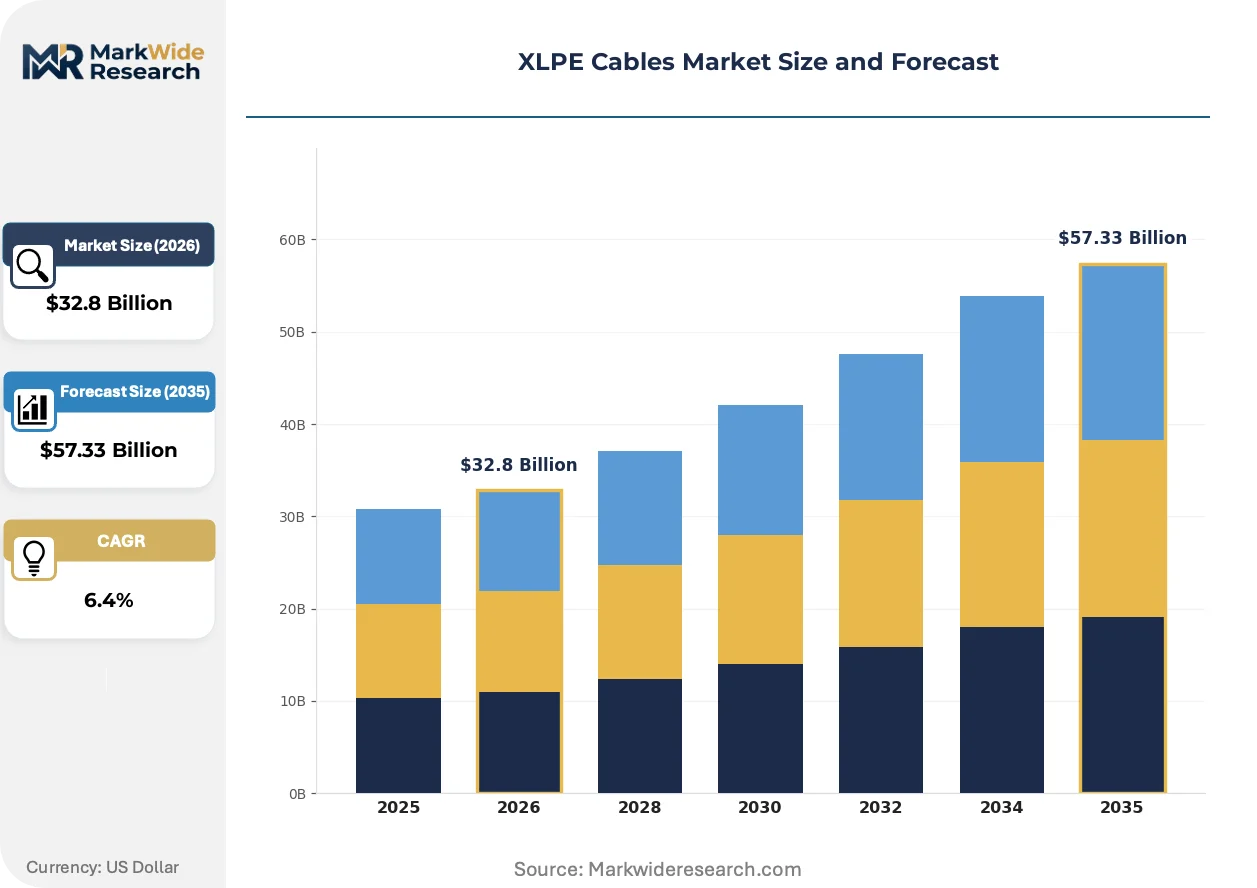
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Application: Power Transmission, Power Distribution, Renewable Energy, Industrial Plants, Telecommunications Insulation Material Grade: Standard Grade, Heat-Resistant Grade, Flame Retardant Grade, Water-Resistant Grade End User Industry: Utilities, Manufacturing Plants, Data Centers, Infrastructure Developers, Construction Firms |
| Companies Covered | LS Cable & System, Southwire Company, Prysmian Group, ABB, Furukawa Electric, Nexans, NKT, ZTT International, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
XLPE Cables Market Strategic Shifts & Innovations
Extrusion and compound formulation are converging with digital process control and sustainable material sourcing, compressing the gap between laboratory qualification and field deployment while elevating performance thresholds for thermal and electrical stress tolerance.
Super-clean polyethylene compounds with sub-50-micron contamination control are virtualizing the reliability margins previously achieved through thicker insulation walls. Japanese utilities and European TSOs are specifying these materials for 500 kV systems with reduced radial thickness. The technology is virtualizing traditional design safety factors and enabling more compact cable geometries without sacrificing dielectric strength.
The EU F-Gas Regulation and accompanying national implementation laws are banning sulfur hexafluoride in switchgear and accelerating cable-based substation designs. This regulatory pressure is expanding addressable market volume for gas-insulated line alternatives using XLPE-insulated bus ducts. German network operators are responding with accelerated tender schedules for 420 kV underground transmission corridors.
Long-term power purchase agreements are consolidating procurement authority into a handful of offshore wind developers and interconnector consortia. These buyers are unbundling installation and maintenance service contracts from cable supply agreements, forcing manufacturers to compete on pure material and extrusion value. The shift is most visible in the North Sea and Baltic Sea zones where TenneT and Energinet dominate project origination.
XLPE Cables Market Segmentation
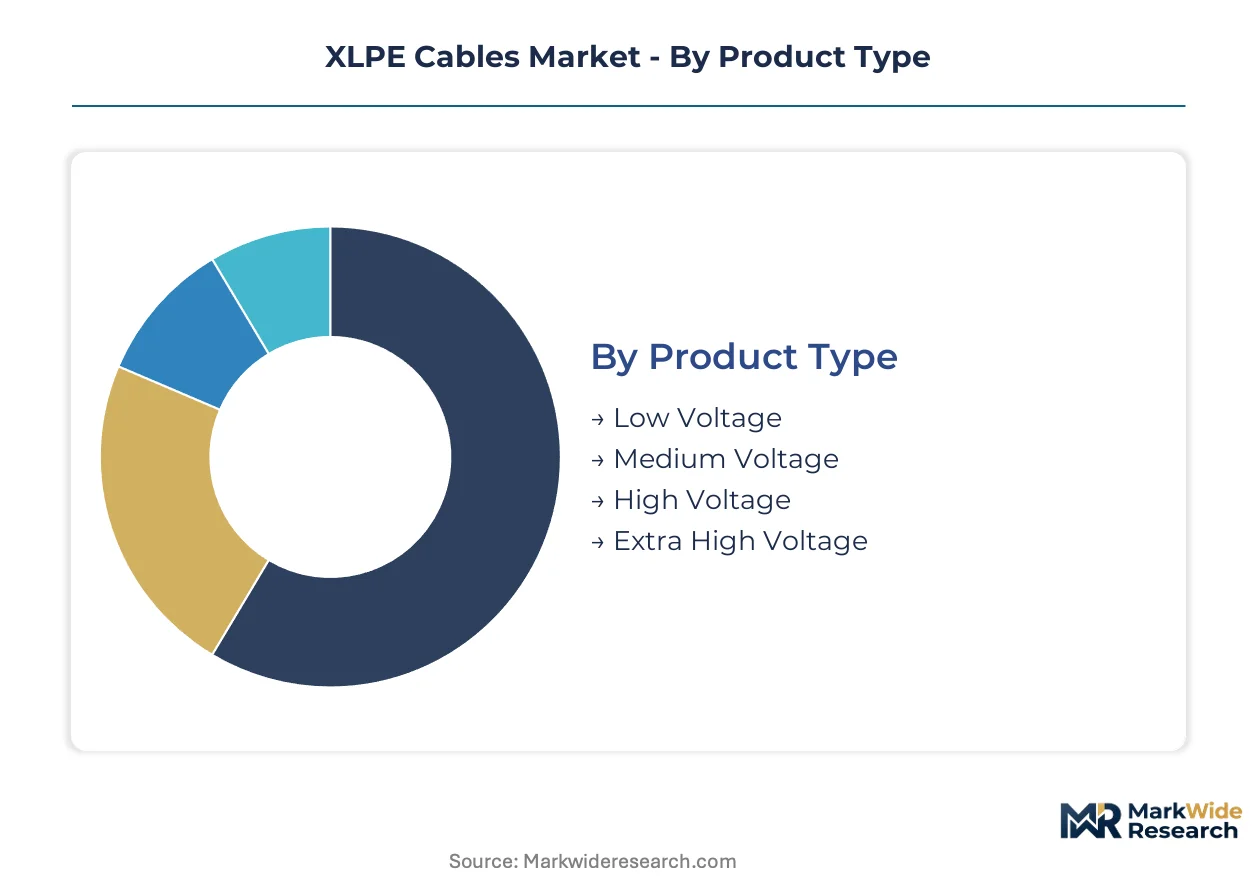
Voltage tier and application specificity determine procurement authority, compound formulation, and qualification timelines across XLPE cable markets. Segment boundaries harden around certification regimes, with IEC 62067 pre-qualification separating high voltage suppliers from commodity manufacturers.
Product Type:
Grid modernization and renewable interconnection projects span voltage classes from distribution feeder replacement to 500 kV long-haul transmission corridors.
- Low Voltage:Cross-linked polyethylene insulation rated up to 1 kV serves building wire, residential distribution, and secondary network cables. Demand concentrates in India's urban electrification programs and Southeast Asian infrastructure builds where aluminum conductor XLPE dominates cost-sensitive tenders.
- Medium Voltage:6 kV to 35 kV systems utilize three-layer co-extruded insulation with semi-conductive screens. European distribution utilities are accelerating procurement of dry-cure silane crosslinked variants to replace oil-impregnated paper in secondary substations under F-Gas Regulation pressure.
- High Voltage:66 kV to 220 kV extruded insulation requires super-clean compounds with sub-50-micron contamination control. Offshore wind developers in Germany and the United Kingdom specify these systems for export cable circuits from North Sea converter platforms.
- Extra High Voltage:330 kV to 500 kV cables demand the thickest insulation walls and longest factory acceptance testing protocols. State Grid Corporation of China consumes the dominant share of global EHV XLPE output for ultra-high voltage transmission corridors.
Established volume favors Medium Voltage; emerging adoption favors Extra High Voltage.
Application:
End-use concentration shapes compound specification, with subsea and tunnel installations demanding specialized material grades against standard overhead or buried terrestrial circuits.
- Power Transmission:Long-haul overhead and underground circuits above 66 kV require tree-retardant additives and longitudinal water-blocking tapes. China's GB/T 11017 standard and IEC 60840 govern qualification for these projects.
- Power Distribution:Secondary networks and primary distribution feeders below 35 kV represent the highest volume deployment. Indian utilities under CEA mandates are replacing PVC-insulated legacy cables with XLPE alternatives in urban load centers.
- Renewable Energy:Offshore wind and solar farm collector systems require flexible medium voltage designs with enhanced UV and ozone resistance. North Sea developers specify armored submarine variants with lead-sheath moisture barriers.
- Industrial Plants:Petrochemical facilities and heavy manufacturing sites specify heat-resistant and oil-resistant insulation grades. Japanese industrial standards JIS C 3605 govern compound selection for these hazardous location installations.
- Telecommunications:Fiber optic power feeding and hybrid fiber-power cables utilize low voltage XLPE sheathing. Data center campus developments in Singapore and Frankfurt are specifying halogen-free flame retardant grades for tunnel routing.
Power Distribution maintains volume leadership; Renewable Energy climbs the fastest on offshore wind procurement acceleration.
Insulation Material Grade:
Performance tiering separates standard utility procurement from specialized applications where failure costs justify material premiums.
- Standard Grade:Peroxide crosslinked polyethylene with base antioxidant packages serves conventional underground and aerial installations. Chinese domestic manufacturers dominate supply for State Grid standard tenders.
- Heat-Resistant Grade:Enhanced thermal stabilizers permit 105°C continuous operation in industrial environments with elevated ambient temperatures. Japanese utilities specify these materials for geothermal power plant interconnections.
- Flame Retardant Grade:Halogen-free formulations with aluminum trihydrate or magnesium hydroxide fillers meet IEC 60332-3 vertical flame spread requirements. London Underground and Paris Metro tunnel specifications mandate this grade for fire safety compliance.
- Water-Resistant Grade:Swellable powders and laminated aluminum moisture barriers prevent treeing degradation in submarine and waterlogged terrestrial installations. North Sea offshore wind export cables require this specification for 25-year design life.
Standard Grade anchors procurement volume; Water-Resistant Grade expands most quickly on subsea renewable interconnection demand.
End User Industry:
Buyer concentration and technical sophistication fragment procurement patterns across regulated utilities, private infrastructure, and industrial self-generation.
- Utilities:Transmission system operators and distribution network operators specify full type-tested cables with IEC 62067 pre-qualification. TenneT in the Netherlands and National Grid in the United Kingdom unbundle installation from supply in large tender packages.
- Manufacturing Plants:Automotive, steel, and chemical producers procure medium voltage feeders for captive substations. German industrial clusters specify VDE-certified heat-resistant grades for furnace and kiln proximity routing.
- Data Centers:Hyperscale cloud operators demand redundant medium voltage supply with low smoke zero halogen specifications. Ashburn, Virginia and Frankfurt am Main campus developments are specifying flame retardant XLPE for underground vault installations.
- Infrastructure Developers:Airport, port, and rail project consortia bundle cable procurement with electrification contracts. India's Dedicated Freight Corridor Corporation specifies 25 kV traction feeder cables with enhanced mechanical protection.
- Construction Firms:Commercial and residential contractors procure low voltage building wire through distributor channels. Cost pressure drives preference for domestic Chinese and Indian manufacturers over European imports.
Utilities command premium pricing through qualification barriers; Data Centers gain share fastest on hyperscale facility construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grid interconnection mandates and carbon neutrality deadlines are redrawing procurement maps across major economies. State-backed transmission programs and offshore wind auctions now determine where XLPE cable demand concentrates.
China
State Grid Corporation's ultra-high voltage corridors consume the dominant share of global EHV XLPE output. GB standards and NMPA-equivalent certification requirements elevate compliance costs for cross-border manufacturers. The Yangtze River Delta and Pearl River Delta clusters host vertically integrated compound-to-cable production facilities serving domestic tender volumes.
Germany
North Sea offshore wind auctions through Bundesnetzagentur require 220 kV to 500 kV submarine systems for TenneT and 50Hertz grid integration. The EU F-Gas Regulation accelerates replacement of SF6-dependent switchgear with XLPE-insulated alternatives. Industrial demand clusters in Bavaria and North Rhine-Westphalia specify VDE-certified heat-resistant grades for manufacturing plant feeders.
United States
FERC interconnection standards and National Electrical Code provisions shape utility procurement specifications for renewable energy evacuation. The PJM and ERCOT interconnection queues are driving medium and high voltage cable demand for solar and wind projects. Data center construction in Ashburn and Dallas-Fort Worth specifies flame retardant XLPE for underground vault installations.
India
The Central Electricity Authority's Green Energy Corridors program requires thousands of kilometers of 132 kV and 220 kV XLPE for solar and wind evacuation. CEA mandates are replacing PVC-insulated legacy cables with XLPE alternatives in urban load centers. Manufacturing demand concentrates in Gujarat and Maharashtra where industrial clusters specify BIS-certified medium voltage feeders.
United Kingdom
Contracts for Difference auctions and National Grid's offshore transmission owner framework are procuring armored submarine cables for North Sea wind farms. The UK RoHS enforcement and REACH compliance frameworks are phasing out halogen-containing insulation in favor of cross-linked polyethylene. Scottish and English North Sea port clusters are emerging as installation and staging hubs for export cable deployment.
XLPE Cables Market Key Industry Players
Channel-controlling players compete with product-specialist players across voltage tiers and application segments. The market structure consolidates around compound formulation mastery and extrusion scale, with pre-qualification barriers freezing out commodity manufacturers. Three archetypes dominate: integrated petrochemical-to-cable conglomerates, submarine-specialist fabricators with armoring capabilities, and regional champions serving state grid procurement. Competitive moves center on backward integration into compound production and strategic partnerships with offshore wind developers.
Within the integrated conglomerate tier, LS Cable & System and Prysmian Group occupy positions defined by captive supply of super-clean polyethylene compounds and multi-voltage extrusion capacity. Nexans exemplifies the submarine-specialist archetype through its positioning in HVDC-XLPE hybrid systems for subsea interconnectors. Southwire Company and Furukawa Electric represent regional manufacturing anchors serving North American and Japanese utility procurement respectively.
| Leading Market Players |
|---|
| LS Cable & System |
| Southwire Company |
| Prysmian Group |
| ABB |
| Furukawa Electric |
| Nexans |
| NKT |
| ZTT International |
| Sumitomo Electric Industries |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock concentration in South Korea and Saudi Arabia directly determines where compound margin pools accumulate downstream, with peroxide and ethylene cost volatility transmitting unevenly across voltage tiers and buyer archetypes.
Pricing Analysis
Certification level creates the primary spread between IEC 62067 pre-qualified suppliers and commodity manufacturers lacking type-test documentation. Three-tier pricing structure across super-clean compound premium, standard utility-grade, and economy aluminum-conductor tiers reflects qualification investment recovery timelines. Cost compression in medium voltage segments is intensifying because State Grid Corporation tenders prioritize domestic suppliers with captive polyethylene production. Distribution utilities under EU F-Gas mandates exhibit lowest price sensitivity, while construction contractors procuring low voltage building wire through distributor channels drive aggressive unit-cost negotiation.
Supply Chain Analysis
Ethylene and peroxide feedstock production centers on South Korea, Saudi Arabia, and the US Gulf Coast, with Asian cable manufacturers drawing from regional naphtha cracking capacity. Super-clean polyethylene compounds, tree-retardant additive packages, and semi-conductive screen materials constitute critical input dependencies. Single-source vulnerability concentrates in Japanese and German compound formulation chemist expertise approaching generational transition. Distribution runs through direct e-procurement platforms for utility-scale procurement and electrical distributor networks for construction and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
XLPE cable procurement is consolidating into platform-economics dynamics where TenneT and State Grid digital exchanges unbundle installation from supply, creating interoperability requirements that favor compound-to-cable integrated manufacturers.
For Market Incumbents: Insulate margin pools by securing captive super-clean polyethylene production and accelerating IEC 62067 pre-qualification for 500 kV systems before compound chemist retirement peaks. EPR and HPTE substitution threats in flexible installation niches demand counter-positioning through enhanced tree-retardant additive R&D. Backward integration into peroxide-initiated crosslinking compound production anchors cost visibility for multi-year offshore wind tenders.
For New Entrants and Emerging Players: Pursue India's Green Energy Corridors program as the most penetrable geography, where CEA mandates are displacing PVC-insulated legacy cables with XLPE alternatives and domestic manufacturing capacity lags demand. Water-resistant grade specialization for submarine renewable interconnections offers white-space positioning against entrenched European armoring specialists. Direct utility e-procurement registration provides the essential go-to-market pathway bypassing distributor intermediation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cable fabricators lacking compound formulation capabilities but holding armoring and installation service contracts. Long-term viability across the analysis window hinges on super-clean compound access and HVDC-XLPE hybrid system qualification progress. The signal to watch is Bundesnetzagentur offshore wind auction timing and converter station developer specification shifts from mass-impregnated paper to extruded DC insulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Production | Captive super-clean polyethylene supply secures margin visibility for TenneT and State Grid multi-year tenders. |
| HVDC-XLPE Hybrid System Qualification | Converter station developer specifications for subsea interconnectors displace mass-impregnated paper technology. |
| Direct E-Procurement Platform Registration | State Grid Corporation and TenneT digital exchanges reduce distributor intermediation and accelerate tender access. |
| Tree-Retardant Additive Package Development | Japanese utilities and European TSOs specify enhanced materials for 500 kV systems with reduced radial thickness. |
| Submarine Cable Armoring Capacity Expansion | North Sea offshore wind export cable demand exceeds current European and Asian integrated vertical lighthouse capacity. |
Research Approach
Initial hypotheses were tested against primary input from transmission system operator procurement officers, compound formulation chemists, offshore wind project developers, and electrical distributor category managers and refined through secondary validation. Primary fieldwork drew from IEC and CIGRE technical committee participation, utility tender document analysis, and EPC contractor project pipeline disclosure. Secondary sources encompassed customs and trade data for ethylene and polyethylene resin flows, SEC filings from listed cable manufacturers, and Bundesnetzagentur offshore wind auction records. Bottom-up project pipeline aggregation and top-down petrochemical feedstock demand modeling were triangulated against voltage-tier shipment estimates.
Demand-supply balance dynamics across the modeling period were assessed through renewable energy interconnection queue analysis, grid modernization program budget allocation, and compound production capacity utilization tracking. Segmentation dimensions encompassed voltage tier, application specificity, insulation material grade, and end-user industry buyer concentration. CAGRs were derived from regression analysis of historical project award volumes against policy mandate implementation timelines and feedstock cost trajectory assumptions. Forecast inputs incorporated F-Gas Regulation replacement cycle modeling and Green Energy Corridors kilometer procurement schedules.
Sensitivities concentrate around ethylene price volatility, compound chemist availability constraints, and IEC 62067 type-test timeline extensions. Forecasts reflect documented assumptions regarding state grid procurement continuity and offshore wind auction award conversion rates. Cross-checking against IEA renewable energy grid integration investment benchmarks and CIGRE working group technical deployment surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Organisers Market
Cables
Cable Fault Locator Market
Cables
Copper Cabling Systems Market
Cables
Instrumentation Cables Market
Cables
North America HVAC Cables Market
Cables
Submarine Data Cables Market
Cables
Cable Management System Market
Cables
Cable Material Market
Cables
UK Cables Market
Cables
Cable Tags Market
Cables
High Voltage Cables Market
Cables
Electric Submersible Cable Sales Market
Cables
United States Cable Accessories Market
Cables
Global Cable Tie Market
Cables
Submarine Cabling Systems Market
Cables
Middle East Cable Market