
 Cable Testing Market | 2026-2036
Cable Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Testing Market Outlook
Digital twin integration is reshaping how cable testing workflows are architected, enabling virtual pre-certification before physical validation. DEKRA leverages its laboratory network across industrial corridors to anchor premium testing services for high-voltage energy infrastructure. SGS competes through marine and offshore cable specialization, where salt corrosion and dynamic load profiles demand customized protocols. Bureau Veritas differentiates via building wire certification tied to green building codes, extending its reach as sustainability mandates tighten.
Cable testing encompasses electrical, mechanical, and environmental validation of insulated conductors to verify ampacity, dielectric strength, and structural integrity under rated thermal and mechanical stress. Methods span high-potential withstand tests, partial discharge detection, and tensile elongation measurement to ensure compliance with IEC 60502 and UL 1072 specifications for power distribution and industrial control applications. Optical time-domain reflectometry leads technology adoption for fiber optic trunk verification, while automated testing gains share in manufacturing units pursuing throughput optimization without manual operator dependency. Smart cable testing represents the fastest-growing technology segment as embedded sensors enable real-time impedance monitoring and predictive fault localization in data center interconnects.
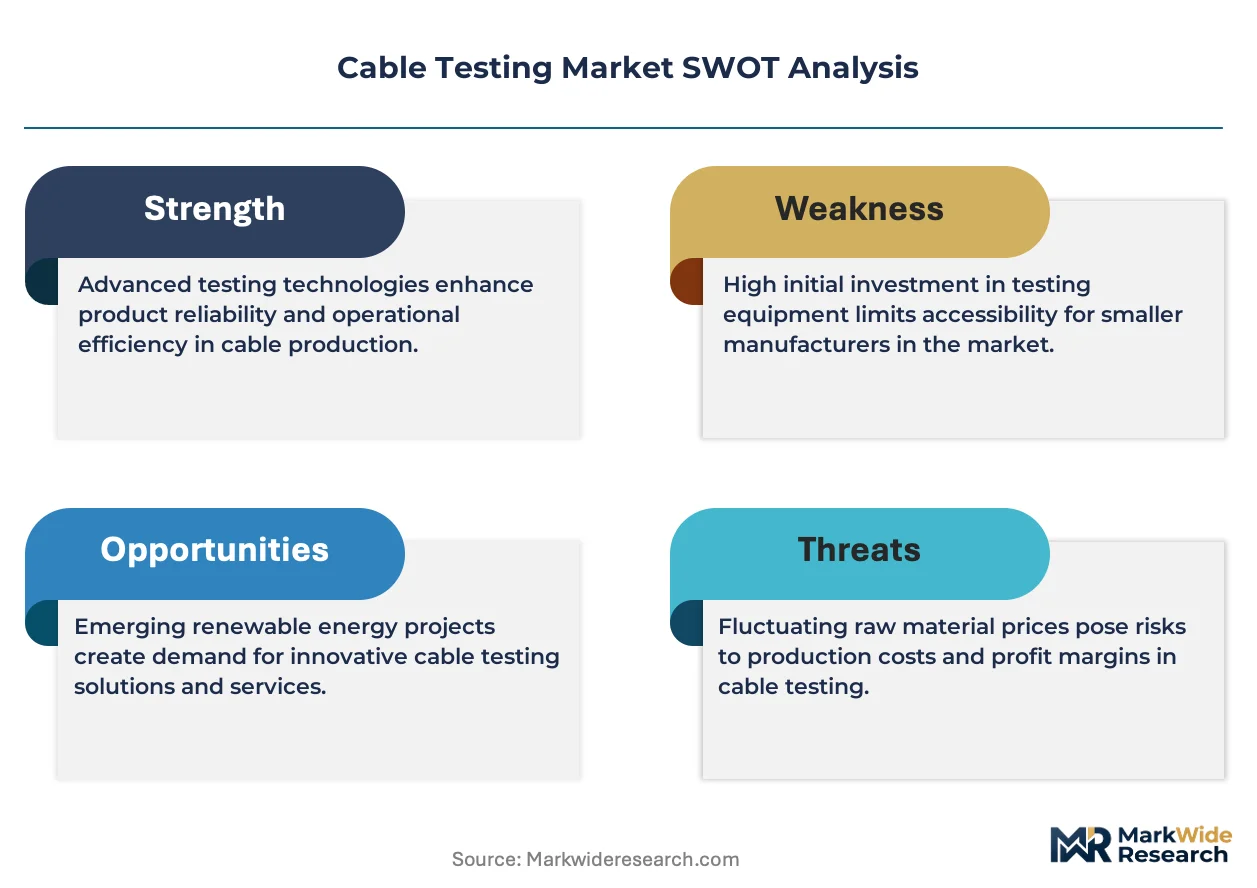
IEC standards, UL safety certifications, and the EU Construction Products Regulation collectively govern cable market access, with fire reaction class requirements under CPR directly shaping test scope and laboratory accreditation demand. The US National Electrical Code and OSHA electrical safety mandates further compel contractor-level field verification, sustaining recurring revenue for portable tester deployments. Stakeholders must weigh capital allocation between automated in-line testing systems and third-party laboratory outsourcing as volume thresholds and liability exposure evolve across end-use verticals.
Market Dynamics
Digital twin adoption is collapsing the traditional boundary between virtual validation and physical certification, forcing testing providers to restructure service architectures around predictive simulation workflows that compress project timelines for hyperscale data center deployments.
Growth Catalysts
- EU CPR fire classification mandates:The Construction Products Regulation's reaction-to-fire classes are elevating third-party laboratory accreditation demand across member states, particularly for building wire and power distribution cables.
- Industrial automation in Germany:Automotive electrification and precision manufacturing clusters around Stuttgart and Wolfsburg are driving validation protocols for high-flexibility control cables.
- OTDR fiber verification:Optical time-domain reflectometry adoption is accelerating in submarine and terrestrial trunk deployments as bandwidth density requirements tighten.
Market Restraints
- Copper price volatility:Raw material cost swings in conductor metals are compressing margins for testing equipment manufacturers dependent on precision signal calibration hardware.
- Laboratory capacity concentration:DEKRA, SGS, and Bureau Veritas control premium high-voltage testing infrastructure across Western Europe, creating bottlenecks for urgent certification timelines.
- Partial discharge detection limits:Conventional offline testing methods fail to capture intermittent insulation defects in dynamic load environments such as offshore wind interconnects.
Strategic Opportunities
- Smart cable embedded sensors:Real-time impedance monitoring in data center interconnects creates recurring revenue streams beyond one-time certification events.
- India's renewable transmission buildout:Central Electricity Authority mandates for 765kV and 1200kV UHVDC lines are opening laboratory partnership opportunities for foreign testing providers.
- Green building code convergence:LEED and BREEAM certification pathways are expanding demand for low-smoke zero-halogen cable validation tied to sustainability scoring.
Industry Challenges
- Field technician calibration expertise:Portable tester deployment requires skilled operators capable of interpreting OTDR traces and TDR impedance profiles without laboratory backup.
- Multi-standard harmonization delays:Divergence between IEC 60502, UL 1072, and GB/T standards forces manufacturers to maintain parallel testing protocols for market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Testing Market |
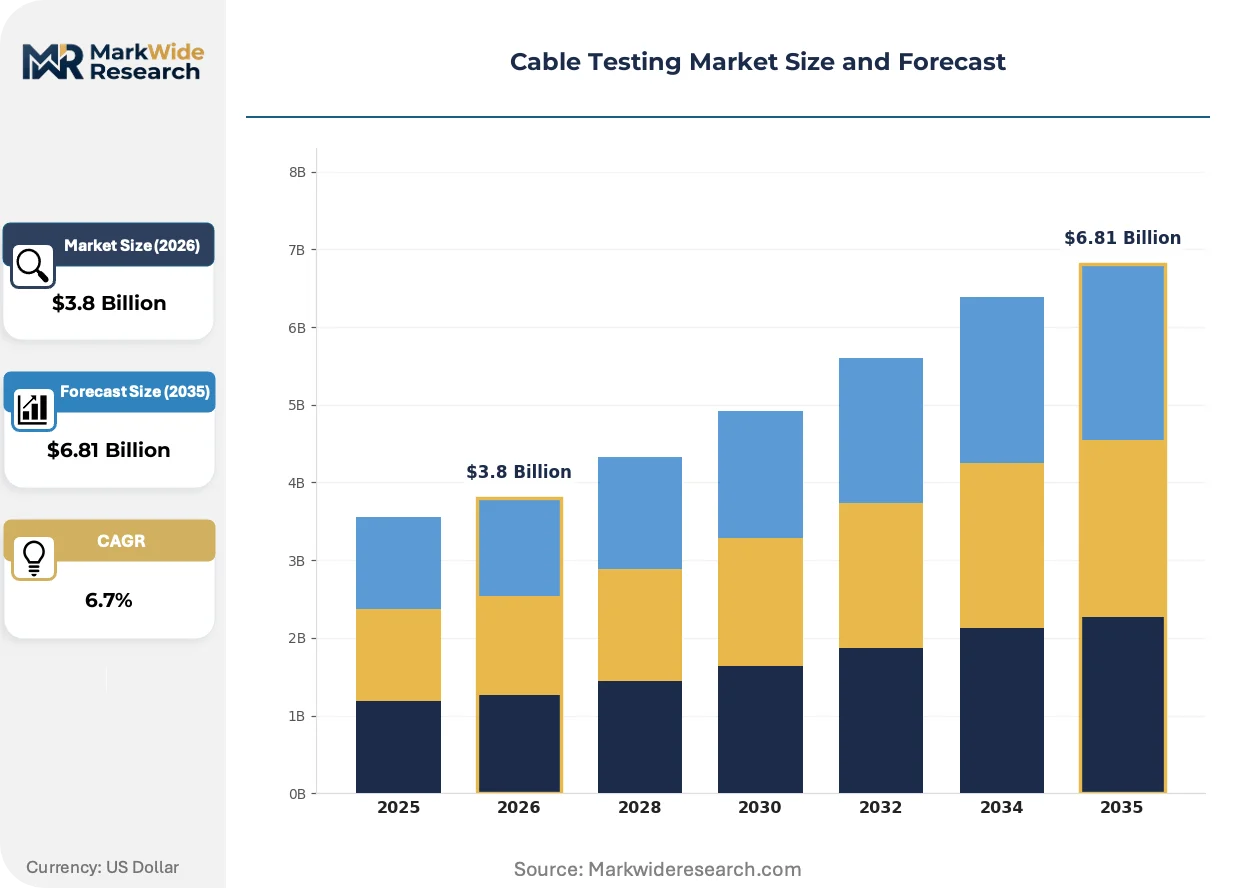
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Testers, Multimeters, Cable Fault Locators, Signal Generators Technology: Optical Time-Domain Reflectometry, Time Domain Reflectometry, Smart Cable Testing, Automated Testing End User: Telecom Companies, Electrical Contractors, Data Centers, Manufacturing Units Application: Network Installation, Maintenance Services, Quality Assurance, Research & Development |
| Companies Covered | DEKRA, SGS, Bureau Veritas, Intertek Group plc, TÜV Rheinland, TÜV SÜD, TÜV NORD GROUP, Underwriters Laboratories, British Approvals Service for Cables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Testing Market Strategic Shifts
Automated in-line testing architectures are displacing manual inspection stations across high-volume cable manufacturing, compressing cycle times while embedding quality verification directly into extrusion and jacketing workflows.
Machine vision systems with sub-millimeter defect resolution are collapsing the economics of 100% inspection for medium-voltage power cables. Tier-one automotive harness suppliers in Mexico and Eastern Europe are retrofitting extrusion lines with laser micrometer and spark-test integration. This convergence is eliminating offline sampling protocols that previously added 12-18 hours to batch release cycles.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated testing systems deployed in safety-critical infrastructure. Laboratory information management systems must now document decision pathways for neural-network-based partial discharge pattern recognition. German notified bodies are requiring supplementary human-in-the-loop verification for AI-augmented dielectric withstand assessments.
Hyperscale data center operators are unbundling certification from equipment procurement, establishing direct relationships with testing laboratories independent of cable vendors. Amazon Web Services and Microsoft Azure infrastructure teams in Northern Virginia and Frankfurt are specifying pre-shipment witness testing at manufacturer facilities. This disintermediation is compressing vendor margins while elevating laboratory brand equity in supplier selection criteria.
Cable Testing Market Segmentation
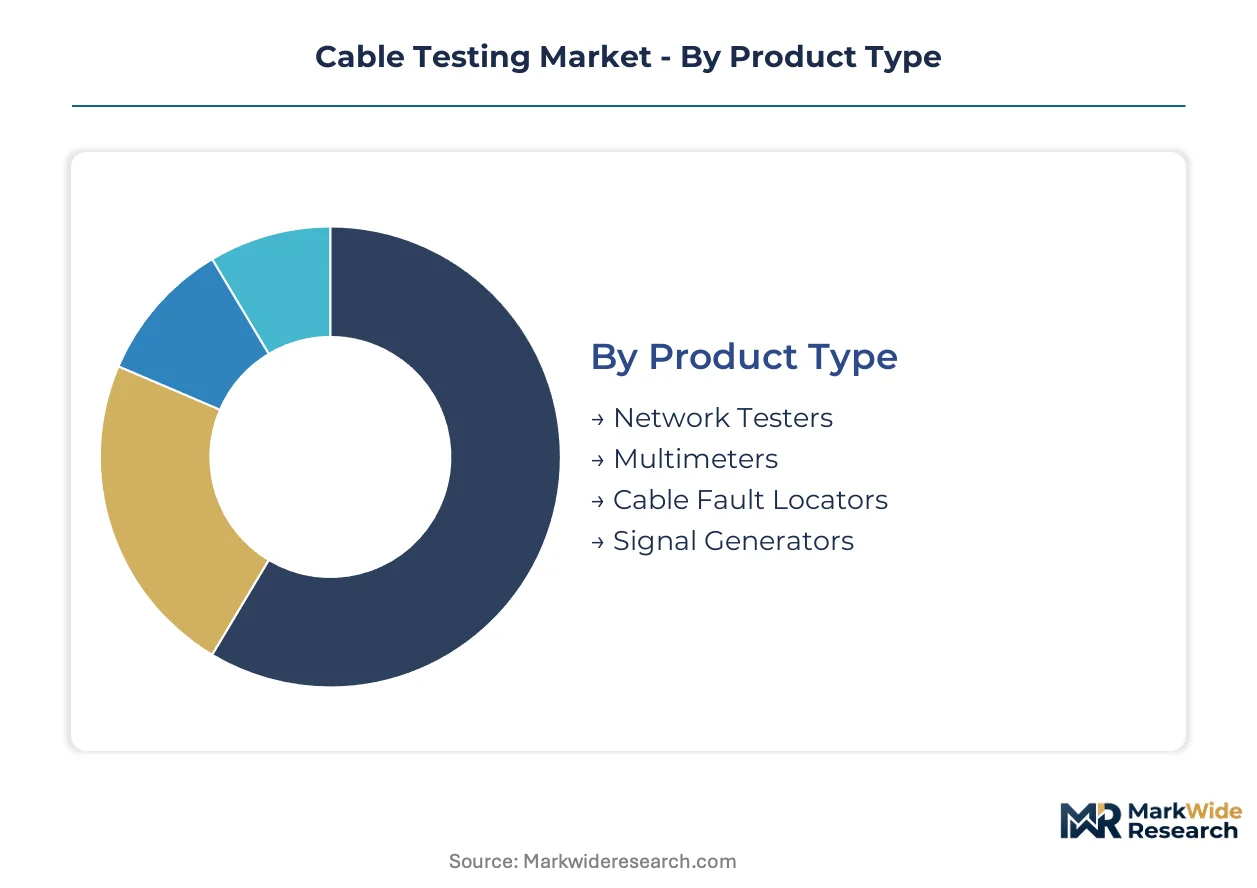
Cable testing equipment and services fragment across multiple technical and commercial dimensions. Understanding these divisions reveals where capital concentrates and where emerging specifications are reshaping procurement priorities.
Product Type:
Use-case spectrum spans from handheld field diagnostics to laboratory-grade precision instruments, with each product class serving distinct operational environments and certification requirements.
- Network Testers:Portable units verify copper and fiber connectivity, PoE load capacity, and transmission performance per TIA-568 standards. Data center operators in Northern Virginia and Frankfurt deploy these for pre-commissioning validation of hyperscale interconnects, where certification speed directly impacts facility energization timelines.
- Multimeters:Handheld and benchtop devices measure voltage, current, resistance, and continuity across low-voltage control and power distribution cables. Electrical contractors across Germany's industrial automation corridors rely on calibrated multimeters for field verification of machine tool cabling under VDE 0100 requirements.
- Cable Fault Locators:TDR-based systems pinpoint impedance discontinuities and insulation breaches in buried and aerial distribution networks. Utilities in India deploy these for 765kV transmission line diagnostics under Central Electricity Authority mandates.
- Signal Generators:Laboratory instruments produce calibrated waveforms for dielectric withstand and partial discharge testing of medium-voltage power cables. High-voltage laboratories in Western Europe use these for type approval testing under IEC 60502.
Established volume favors multimeters; emerging adoption favors network testers.
Technology:
Cost tier stratification separates capital-intensive automated systems from portable field instruments, with middleware solutions capturing growth in manufacturing quality control.
- Optical Time-Domain Reflectometry:Laser-based pulse analysis maps fiber attenuation, splice losses, and connector reflectance across single-mode and multimode installations. Submarine cable consortia deploying transatlantic and transpacific trunks specify OTDR verification at 1550nm and 1625nm wavelengths for post-lay acceptance.
- Time Domain Reflectometry:Electrical pulse propagation identifies impedance mismatches and discontinuities in coaxial and twisted-pair copper cabling. Telecom infrastructure teams in Japan use TDR for metallic access network maintenance under NTT technical standards.
- Smart Cable Testing:Embedded sensor networks enable continuous impedance monitoring and predictive fault localization in critical interconnects. Hyperscale data center operators specify smart cable systems for real-time thermal and mechanical stress tracking.
- Automated Testing:In-line extrusion monitoring with laser micrometer and spark-test integration eliminates offline sampling in high-volume manufacturing. Automotive harness suppliers in Mexico retrofit production lines with automated architectures to compress batch release cycles.
Mature deployment concentrates in OTDR; steepest expansion trajectory belongs to smart cable testing.
End User:
Customer type determines procurement scale, with enterprise operators pursuing direct laboratory relationships while contractors prioritize portable equipment fleets.
- Telecom Companies:National operators and mobile network providers specify cable testing for outside plant construction, central office interconnects, and 5G fronthaul deployment. Field teams in South Korea verify fiber-to-the-home installations under KT and SK Telecom quality protocols.
- Electrical Contractors:Installation firms perform field verification of building wire, industrial control cables, and power distribution circuits per NEC and local electrical codes. OSHA electrical safety mandates compel recurring portable tester deployment across US commercial construction.
- Data Centers:Hyperscale and colocation operators establish direct testing laboratory relationships independent of cable vendors. AWS and Azure infrastructure teams specify pre-shipment witness testing at manufacturer facilities.
- Manufacturing Units:Cable producers and harness assemblers integrate in-line testing for 100% inspection without manual operator dependency. Tier-one automotive suppliers in Eastern Europe deploy machine vision systems with sub-millimeter defect resolution.
Contractor volume dominates equipment sales; data center direct procurement is climbing fastest.
Application:
Margin structure varies sharply between one-time installation certification and recurring maintenance revenue streams.
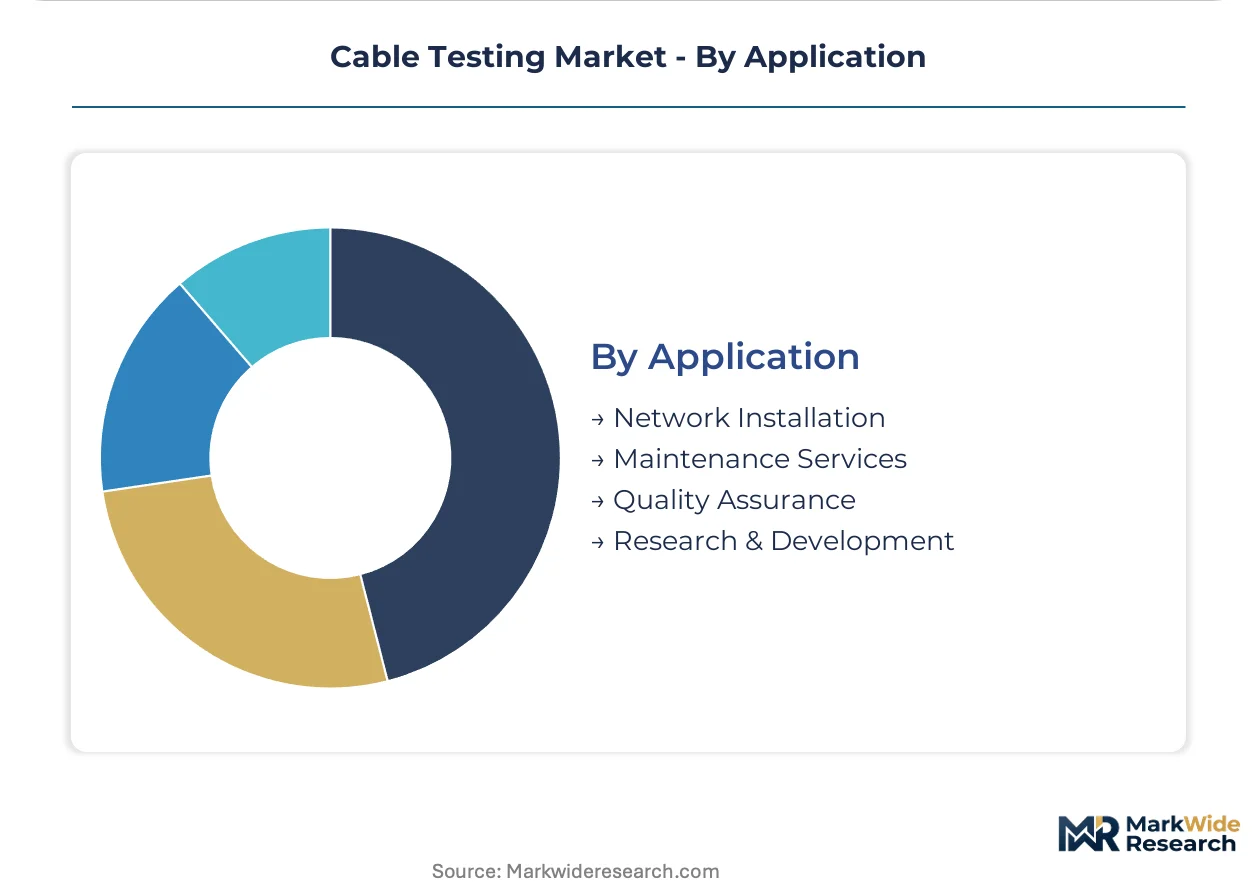
- Network Installation:Pre-commissioning verification ensures copper and fiber infrastructure meets transmission specifications before service activation. Installation contractors in Brazil perform acceptance testing under ANATEL technical requirements for telecom infrastructure.
- Maintenance Services:Periodic diagnostics and fault location sustain recurring revenue for service providers with field technician networks. Utilities in Australia deploy maintenance testing for aging distribution assets under Essential Energy reliability programs.
- Quality Assurance:In-process and final inspection protocols verify dimensional, electrical, and mechanical conformance to IEC, UL, and customer specifications. Cable manufacturers in China implement GB/T standard compliance testing for domestic and export market access.
- Research & Development:Laboratory characterization of novel insulation materials, conductor geometries, and fire performance properties supports next-generation product development. Materials scientists in Switzerland evaluate low-smoke zero-halogen compounds for green building code alignment.
Installation commands the largest addressable base; maintenance services deliver the most durable revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented cable testing equipment flows from Germany, Japan, and the United States toward infrastructure buildouts in India, Brazil, and Southeast Asia. Import dependence for high-voltage laboratory services concentrates in markets lacking domestic accreditation capacity.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives pre-commissioning fiber certification demand. OSHA electrical safety mandates compel field verification protocols for commercial construction nationwide. AWS and Azure infrastructure teams specify direct laboratory relationships independent of cable vendors.
Germany
Industrial automation clusters around Stuttgart and Wolfsburg require precision validation for high-flexibility control cables. The EU Construction Products Regulation elevates third-party fire performance testing for building wire across member states. DEKRA leverages its laboratory network across industrial corridors for premium high-voltage energy infrastructure services.
China
Domestic cable manufacturers implement GB/T standard compliance testing for export market access to Europe and North America. The MIIT oversees telecommunications infrastructure quality protocols for 5G deployment. Yangtze River Delta production bases integrate automated in-line testing to compress batch release cycles.
India
Central Electricity Authority mandates for 765kV and 1200kV UHVDC transmission lines open laboratory partnership opportunities for foreign testing providers. Renewable energy buildout requires specialized validation for solar and wind interconnects. Maharashtra and Gujarat host the primary manufacturing clusters seeking international accreditation.
Japan
NTT technical standards govern metallic access network maintenance with time-domain reflectometry protocols. Submarine cable consortia deploying transpacific trunks specify optical time-domain reflectometry verification at multiple wavelengths. METI oversees national quality frameworks for telecommunications and power infrastructure.
Cable Testing Market Competitive Environment
On the supply side, the industry is consolidating around accredited laboratory networks with multi-country presence. Testing providers compete through specialization vectors rather than price alone. Three archetypes dominate: premium-tier multinational laboratories, regional specialists with sector focus, and equipment manufacturers with service extensions. Capacity expansion and strategic partnerships represent the primary competitive moves as providers seek to anchor client relationships beyond one-time certification events.
Within the premium-tier laboratory segment, DEKRA, SGS, and Bureau Veritas exemplify the network-scale archetype. DEKRA represents European-origin laboratory consolidation across industrial corridors. SGS occupies a position within marine and offshore cable specialization. Bureau Veritas anchors building wire certification tied to green building codes. These three sit within the tier where brand equity directly influences hyperscale operator procurement decisions.
| Leading Market Players |
|---|
| DEKRA |
| SGS |
| Bureau Veritas |
| Intertek Group plc |
| TÜV Rheinland |
| TÜV SÜD |
| TÜV NORD GROUP |
| Underwriters Laboratories |
| British Approvals Service for Cables |
| Others |
Value Chain & Pricing Dynamics
Copper price volatility in conductor metals determines both pricing tier spreads and supply chain shape across cable testing equipment manufacturing, compressing margins for precision signal calibration hardware while forcing procurement teams toward long-term offtake contracts with Chilean and Peruvian mining consortia.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with premium tiers capturing UL/IEC dual-certification compliance and embedded smart sensor diagnostics. Price differentiation hinges on certification grade and volume scale, with hyperscale data center operators commanding standard-tier discounts through direct laboratory relationships. Cost compression in economy-tier portable testers is intensifying because of Chinese manufacturing overcapacity. Electrical contractors in commercial construction prove most price-sensitive, while submarine cable consortia demonstrate minimal elasticity given failure-cost exposure.
Supply Chain Analysis
Upstream feedstock flows for precision testing equipment concentrate in Germany, Japan, and the United States, where specialized semiconductor fabs and precision optics manufacturers cluster. Critical inputs include high-purity copper conductors, laser diodes for OTDR modules, and FPGA chipsets for signal processing. Single-source vulnerability sits with Japanese suppliers of 1550nm laser sources for fiber verification systems. Distribution runs through authorized distributor networks serving industrial corridors, with direct OEM relationships capturing hyperscale operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from embedded smart cable systems that displace periodic third-party certification with continuous monitoring, requiring defensive repositioning around predictive analytics capabilities.
For Market Incumbents: Build data moats through predictive failure analytics platforms that integrate OTDR trace histories with thermal load profiles. DEKRA, SGS, and Bureau Veritas should deepen backward integration into sensor manufacturing to control smart cable component supply. Laboratory networks must anchor client relationships through multi-year service contracts that bundle traditional certification with real-time monitoring subscriptions, neutralizing pure-play sensor vendors. For New Entrants and Emerging Players: Establish a beachhead in India's 765kV and 1200kV UHVDC transmission testing market, where Central Electricity Authority mandates outpace domestic laboratory capacity. Foreign testing providers can partner with Maharashtra and Gujarat manufacturing clusters seeking international accreditation. Target automotive electrification corridors in Eastern Europe with automated in-line testing retrofit services, leveraging machine vision expertise from adjacent industrial automation sectors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors accredited laboratory networks with multi-country presence and smart cable technology integration. Long-term viability rests on recurring revenue capture beyond one-time certification events. Acquisition targets should demonstrate embedded sensor partnerships or predictive analytics platforms. Watch hyperscale operator procurement disintermediation trends as the inflection signal—vendor-direct laboratory relationships that bypass traditional cable suppliers indicate accelerating value capture by testing providers.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Cable Technology Partnership | Embedded sensor integration enables recurring revenue streams beyond one-time certification events. |
| Automated In-Line Testing Deployment | Machine vision retrofit eliminates offline sampling for automotive harness suppliers in Mexico. |
| India Laboratory Joint Venture | CEA mandates for UHVDC lines create partnership opportunities for foreign testing providers. |
| Green Building Certification Alignment | LEED and BREEAM pathways expand demand for low-smoke zero-halogen cable validation services. |
| Predictive Analytics Platform Launch | Digital twin integration compresses project timelines for hyperscale data center deployments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of IEC standards documentation, UL safety certification databases, EU Construction Products Regulation filings, and customs trade data for testing equipment flows. Interviews with laboratory operations directors, hyperscale data center infrastructure planners, automotive harness procurement leads, and electrical contractor fleet managers informed demand-side validation. Secondary sources include SEC 10-K filings from listed testing providers, notified body accreditation registers, and national electrical code adoption tracking. Bottom-up equipment shipment analysis triangulates against top-down service revenue aggregation across the analysis window.
Forecast inputs span voltage class segmentation, end-user procurement scale, technology adoption curves for OTDR versus smart cable systems, and regional regulatory enforcement intensity. The analytical framework models product type, technology tier, end-user category, and application purpose across the projection horizon. CAGRs derive from regression analysis against infrastructure capex cycles and certification mandate implementation timelines. Hyperscale data center buildout schedules and renewable transmission project pipelines provide industry-specific demand anchors.
Stress conditions across copper price bands, laboratory capacity expansion rates, and smart cable penetration thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU CPR enforcement consistency and OSHA electrical safety mandate continuity. Cross-checking against national electrical code adoption timelines and hyperscaler capex disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Usb Data Cable Market
Cables
Cable Market
Cables
USB Cable Market
Cables
Copper Cabling Systems Market
Cables
Power Cable Accessories Market
Cables
Cable Assembly Market
Cables
North America Patch Cable Market
Cables
Anti-Static Space Wires Market
Cables
Aluminium Battery Cable Market
Cables
High-Speed Interconnects Market
Cables
Underground Cable Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Twisted Pair Cable Market
Cables
India Wire and Cable Market
Cables
Control Cable Market
Cables
Fiber Optic Cable Materials Market