
 Instrumentation Cables Market | 2026-2036
Instrumentation Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Instrumentation Cables Market Analysis
The EU Green Deal is repositioning demand toward low-smoke, halogen-free instrumentation cables across European process industries. Prysmian Group leverages its vertically integrated compound manufacturing to sustain cost advantages in fluoropolymer-insulated products. Nexans dominates submarine and offshore project channels, while Belden specializes in precision-engineered shielded cables for interference-critical control systems.
Instrumentation cables transmit low-power electrical signals between sensors, controllers, and monitoring equipment in industrial process environments, typically constructed with twisted conductor pairs, metallic or foil shielding layers, and thermoplastic or fluoropolymer jackets rated for temperatures from minus forty to over two hundred degrees Celsius. Multi-core configurations lead volume demand by consolidating multiple signal paths into single cable runs, reducing installation labor and tray congestion in crowded plant environments. Shielded cables command premium positioning where electromagnetic interference from variable frequency drives and power distribution threatens signal integrity in manufacturing and oil and gas facilities.
REACH and RoHS frameworks in Europe restrict hazardous substance content in cable compounds, while IEC 61508 and ATEX directives mandate flame-retardant and explosion-proof performance for hazardous area installations. The US National Electrical Code and OSHA electrical safety standards shape product certification requirements and installation practices across North American industrial sites. Stakeholders must monitor evolving PFAS restrictions and copper sourcing regulations that threaten to disrupt established supply chains and compound formulations.
Market Dynamics
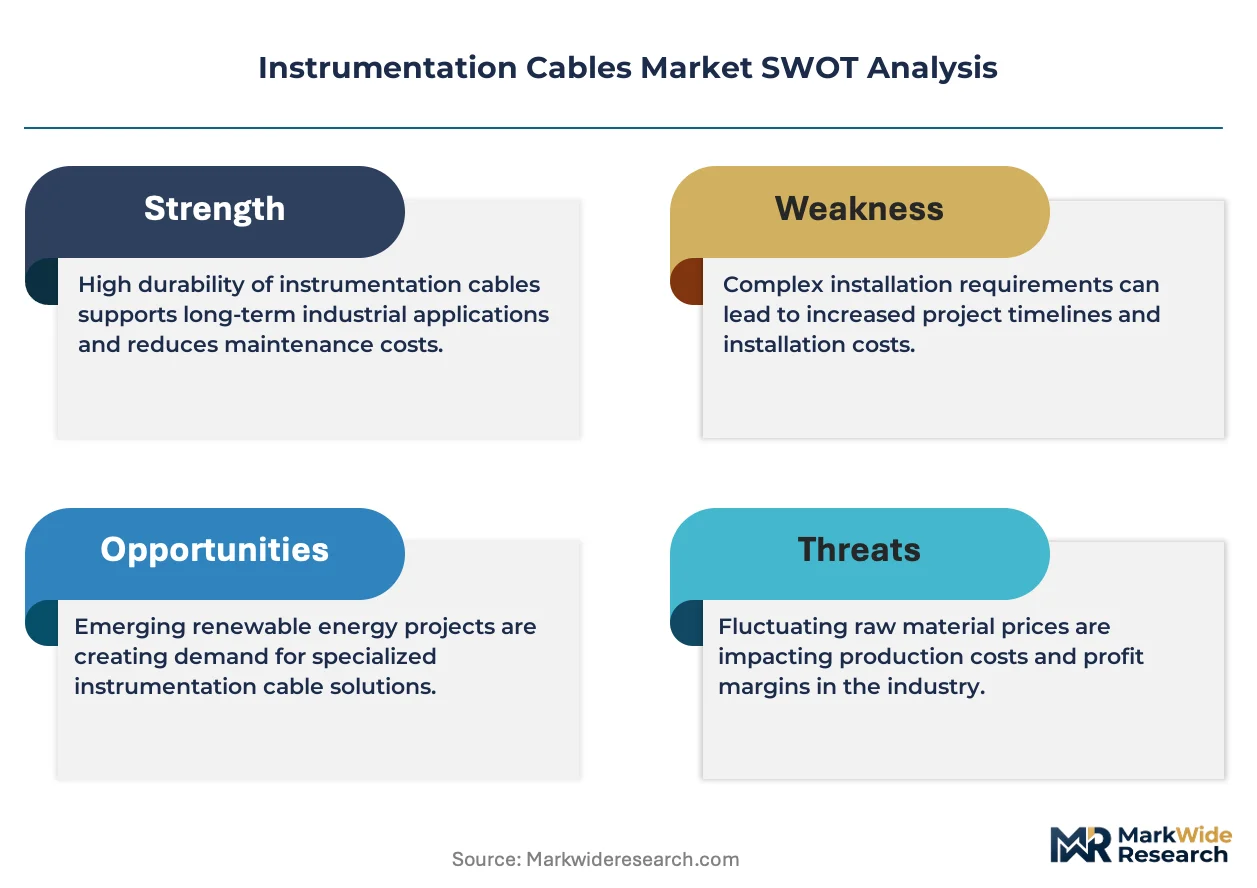
PFAS compound restrictions under REACH are forcing cable manufacturers to reformulate halogen-free jacketing materials, compressing supplier margins while opening substitution windows for silicone and thermoplastic elastomer alternatives.
Growth Catalysts
- IEC 61508 functional safety mandates:Process industries in Germany and France now require certified cables for SIL-rated safety instrumented systems, expanding specification-grade procurement.
- India's petrochemical corridor expansion:Gujarat and Maharashtra refineries are deploying dense sensor networks for predictive maintenance, driving multi-core shielded cable demand.
- Variable frequency drive proliferation:Manufacturing facilities across Southeast Asia face escalating electromagnetic interference, accelerating migration from unshielded to braided-shield configurations.
Market Restraints
- Copper price volatility:LME copper fluctuations above historical baselines compress compound margin structures for stranded conductor producers.
- Fluoropolymer supply concentration:ETFE and FEP resin production clusters in China and Japan create geographic chokepoints for high-temperature cable insulation.
- Legacy PVC substitution friction:RoHS-compliant low-smoke zero-halogen compounds carry 15-25% material cost premiums versus conventional jacketing.
Strategic Opportunities
- Subsea umbilical integration:Offshore wind developers in the North Sea are consolidating power and fiber-optic instrumentation into single cable architectures.
- EU Green Deal procurement mandates:Public tender scoring now weights circular material content, favoring suppliers with verified recycled copper traceability.
- Digital twin convergence:Smart cable designs embedding distributed temperature sensing are enabling real-time thermal monitoring in chemical processing plants.
Industry Challenges
- ATEX certification timeline compression:Hazardous area cable approvals now average 14-18 months, delaying project revenue recognition for specialized manufacturers.
- Cross-functional skill scarcity:Compound chemists with simultaneous fluoropolymer formulation and flame-retardant additive expertise command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrumentation Cables Market |
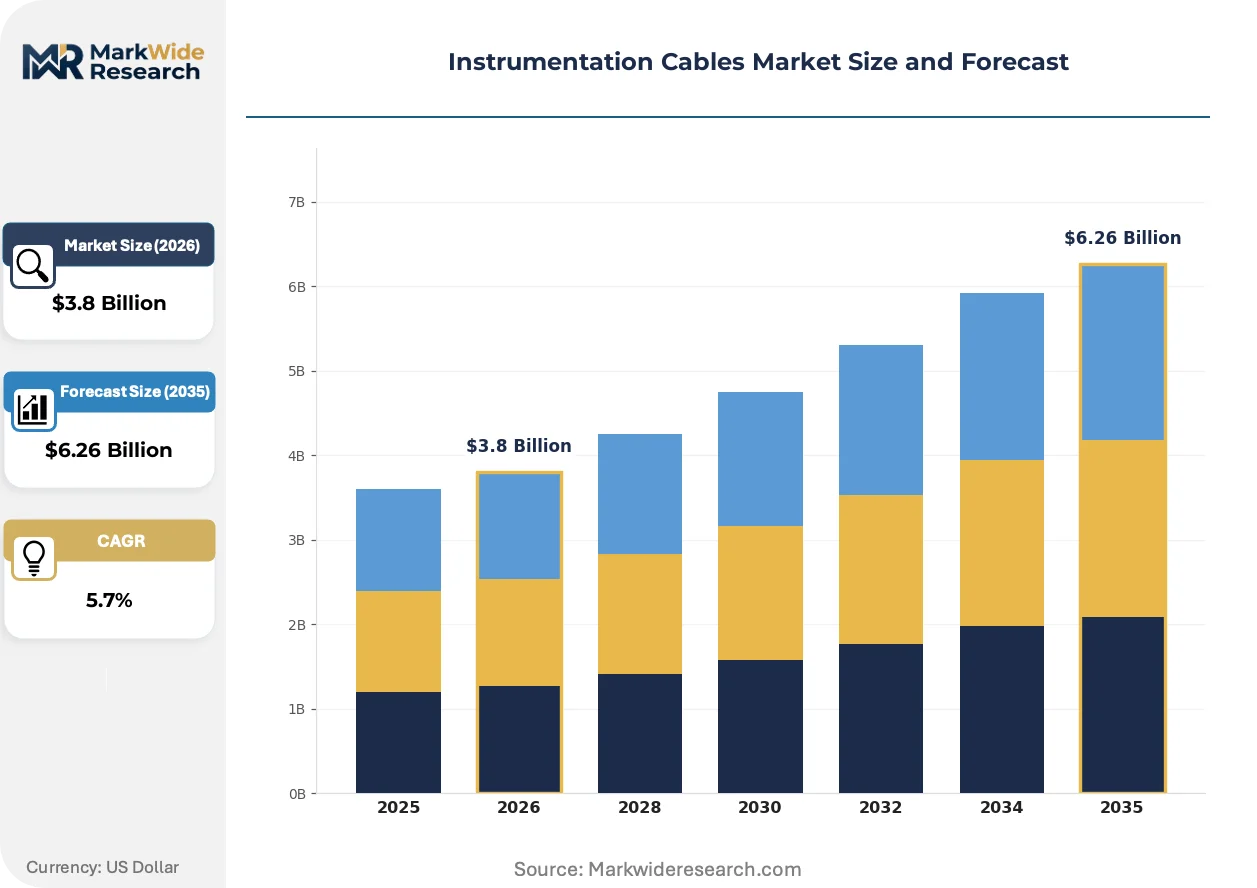
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Cables, Round Cables, Multi-core Cables, Shielded Cables Installation Method: Conduit, Direct Buried, Ladder Tray, Aerial End User: Oil & Gas, Power Generation, Manufacturing, Aerospace Material: Copper, Aluminum, PVC, Teflon |
| Companies Covered | Southwire Company, LS Cable & System, Prysmian Group, CommScope, Fujikura, Nexans, Sumitomo Electric, TE Connectivity, Belden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrumentation Cables Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry constraints are converging to reshape cable architecture decisions, with performance specifications now inseparable from environmental compliance obligations.
Silicone rubber insulation is electrifying high-temperature process applications previously dominated by fluoropolymer alternatives. Chemical processors in the US Gulf Coast are specifying silicone-jacketed multi-pairs for steam tracing environments up to 200°C. The technology is electrifying competitive positioning by decoupling thermal performance from PFAS-dependent supply chains.
REACH Annex XVII PFAS restrictions are prohibiting long-chain fluorinated compounds in cable sheathing across EU member states. Compounders must validate alternative chemistries through accelerated aging protocols without established historical performance data. German automotive suppliers and French nuclear operators are most affected, driving joint development programs with material science partners.
Consolidated procurement through engineering-procurement-construction contractors is compressing direct manufacturer relationships. Oil and gas majors now mandate single-source accountability for cable, termination, and commissioning packages. This pattern is most visible in Middle Eastern downstream projects, where lump-sum turnkey contracts absorb instrumentation scope into broader electrical packages.
Instrumentation Cables Market Segmentation
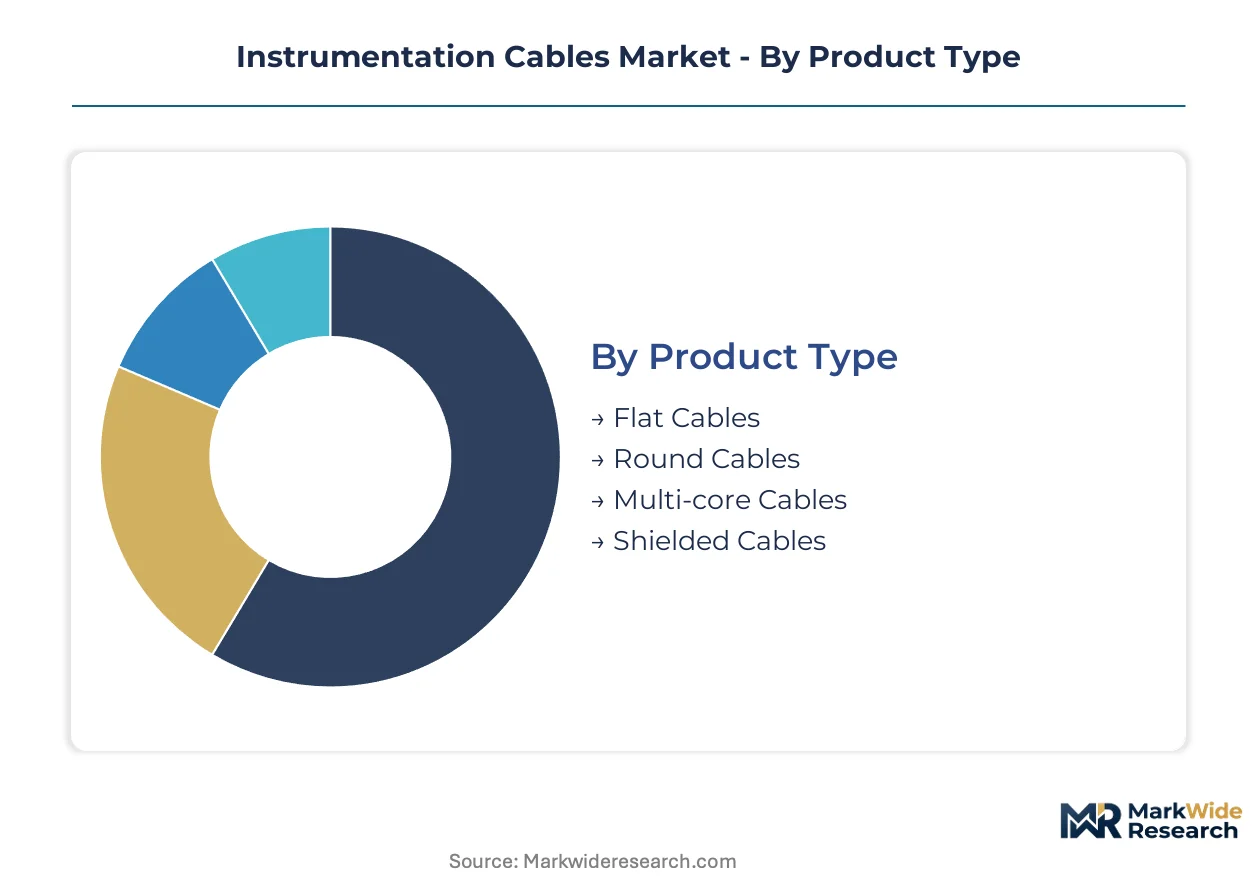
Instrumentation cable specification directly determines signal integrity, installation economics, and regulatory compliance across industrial environments. Each segmentation axis reveals distinct procurement patterns, with technical performance requirements diverging sharply between process control applications and power transmission monitoring.
Product Type:
Technical architecture choices govern electromagnetic compatibility, thermal endurance, and space utilization in crowded plant environments.
- Multi-core Cables:These configurations consolidate multiple twisted conductor pairs within a single jacket, reducing tray congestion and installation labor in dense sensor networks. Demand concentrates across India's petrochemical corridors in Gujarat and Maharashtra, where refineries deploy thousands of measurement points for predictive maintenance systems.
- Shielded Cables:Braided copper or aluminum foil layers block electromagnetic interference from variable frequency drives and power distribution equipment. Manufacturing facilities across Southeast Asia face escalating noise environments, accelerating procurement of braided-shield configurations over unshielded alternatives.
- Round Cables:Standard circular cross-sections dominate general-purpose industrial applications with moderate flexing requirements.
- Flat Cables:Ribbon-style conductors enable compact routing in space-constrained control panels and mobile equipment.
Multi-core cables lead on scale; shielded cables lead on momentum.
Installation Method:
Deployment environment dictates mechanical protection, accessibility for maintenance, and fire safety compliance requirements.
- Ladder Tray:Open metallic support systems dominate process plant construction, enabling thermal dissipation and future circuit expansion. Power generation utilities across Southeast Asia specify tray-rated cables for grid monitoring sensor networks, balancing accessibility with protection from physical damage.
- Direct Buried:Armored constructions with moisture barriers serve pipeline monitoring and tank farm applications where aerial or surface routing proves impractical.
- Conduit:Rigid or flexible metallic tubing provides maximum mechanical protection and electromagnetic shielding in heavy industrial zones.
- Aerial:Self-supporting or messenger-wire configurations bridge between structures in mining, quarrying, and outdoor material handling operations.
Ladder tray dominates procurement volume; direct buried commands premium pricing for harsh-environment specifications.
End User:
Industry-specific safety standards, signal density requirements, and operating conditions create divergent specification profiles.
- Oil & Gas:Offshore platforms and downstream refineries demand flame-retardant, mud-resistant constructions rated for hazardous area installation under ATEX and IECEx frameworks. North Sea operators now consolidate power and fiber-optic instrumentation into single umbilical architectures, reshaping procurement specifications.
- Power Generation:Nuclear and conventional plants require cables rated for radiation exposure, steam environments, and seismic qualification. French nuclear operators face acute pressure from REACH Annex XVII PFAS restrictions, forcing joint development programs with material science partners for validated alternative chemistries.
- Manufacturing:Automotive and electronics assembly lines prioritize flexible, high-flex-cycle constructions for robotic and motion control applications.
- Aerospace:Aircraft and spacecraft applications demand extreme weight optimization and outgassing control for vacuum environments.
Oil & gas anchors specification-grade procurement; power generation drives materials innovation under regulatory pressure.
Material:
Conductor and insulation chemistry selections balance electrical performance, thermal endurance, environmental compliance, and supply chain risk.
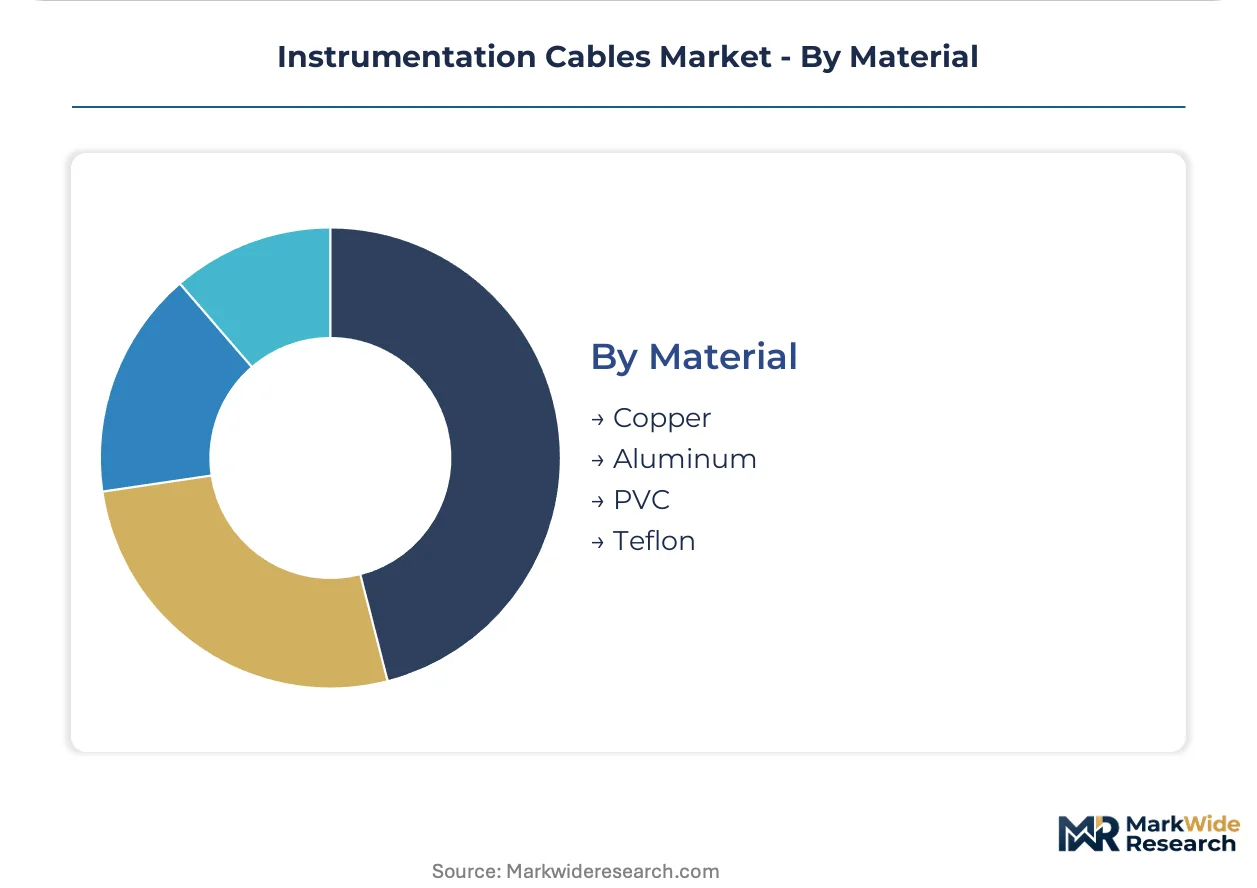
- Copper:Oxygen-free high-conductivity copper dominates signal transmission applications, with stranded configurations optimizing flex life. LME price volatility above historical baselines compresses compound margin structures for producers dependent on virgin metal sourcing.
- Teflon:Fluoropolymer insulation delivers exceptional thermal and chemical resistance for high-temperature process environments. ETFE and FEP resin production clusters in China and Japan create geographic chokepoints threatening supply security.
- Aluminum:Lower conductivity and lighter weight suit long-span aerial installations and cost-sensitive power distribution monitoring.
- PVC:Conventional thermoplastic jacketing faces substitution pressure from RoHS-compliant low-smoke zero-halogen compounds carrying material cost premiums.
Copper leads on installed base; Teflon faces reformulation pressure from REACH chemistry constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrumentation cable manufacturing first scaled in Germany and the United States during the 1960s industrial automation wave, with European process industries establishing the foundational specifications still referenced worldwide. Regional demand patterns now diverge sharply between mature replacement markets and greenfield industrialization corridors.
Germany
Process automation OEMs in Baden-Württemberg and North Rhine-Westphalia drive specification-grade procurement for SIL-rated safety systems. REACH Annex XVII PFAS restrictions are forcing compound reformulation partnerships between cable producers and material science institutes in Aachen and Stuttgart. The BASF Ludwigshafen chemical complex anchors demand for validated alternative chemistries in high-temperature environments.
United States
Petrochemical expansion along the Texas Gulf Coast and Permian Basin infrastructure drives multi-core shielded cable deployment for predictive maintenance networks. OSHA electrical safety standards and NEC Article 727 shape hazardous area installation requirements. Houston engineering-procurement-construction contractors now mandate single-source accountability for integrated cable and commissioning packages.
China
State Grid Corporation's sensor network modernization and offshore wind development in Jiangsu and Guangdong provinces concentrate demand. GB standards and MIIT industrial policy prioritize localization of fluoropolymer insulation supply chains. The Yangtze River Delta manufacturing belt faces acute pressure to substitute PFAS-dependent compounds ahead of anticipated MEE environmental regulations.
India
Reliance Industries and Indian Oil refineries in Gujarat and Maharashtra deploy dense instrumentation networks for digital transformation initiatives. BIS certification requirements and CEA grid standards tighten cable performance specifications for power generation applications. The Dahej and Hazira petrochemical corridors represent the fastest-growing demand clusters for multi-core shielded configurations.
Japan
Nuclear plant restart programs and semiconductor fabrication expansion in Kyushu and Tohoku drive radiation-resistant and cleanroom-grade cable demand. METI energy policy and JIS standards mandate domestic supplier qualification for critical infrastructure. Yokohama-based trading houses coordinate ETFE and FEP resin sourcing from domestic chemical producers facing geographic supply concentration risks.
Instrumentation Cables Market Vendor Landscape
Capital-heavy producers with captive compound manufacturing compete with asset-light designers relying on outsourced jacketing and conductor sourcing. The vendor base concentrates around three tiers: integrated material-compound-cable producers, specialized shielding and precision-engineering houses, and regional fabricators serving installation contractors. Strategic archetypes include fluoropolymer specialists defending thermal performance positioning, multi-core volume players optimizing tray-fill density specifications, and subsea integrators consolidating power and fiber architectures. Dominant competitive moves span backward integration into copper rod and resin production, plus engineering-procurement-construction partnership lockups for lump-sum turnkey project participation.
Among European integrated producers, Prysmian Group and Nexans exemplify divergent specialization vectors—Prysmian anchoring fluoropolymer-insulated premium positioning through in-house compound manufacturing, Nexans occupying offshore and submarine project channels where umbilical consolidation reshapes procurement specifications. Belden represents the precision-engineered shielding archetype, with its naming convention signaling North American heritage and interference-critical control system focus. These three illustrate how technical specialization, geographic supply chain configuration, and end-use application concentration stratify competitive positioning without requiring uniform scale or scope.
| Leading Market Players |
|---|
| Southwire Company |
| LS Cable & System |
| Prysmian Group |
| CommScope |
| Fujikura |
| Nexans |
| Sumitomo Electric |
| TE Connectivity |
| Belden |
| Others |
Supply Flow & Price Mechanics
Engineering-procurement-construction contractor consolidation in Middle Eastern downstream projects forces cable manufacturers toward bundled accountability for cable, termination, and commissioning packages, compressing direct manufacturer margins while elevating specification-grade premiums for integrated suppliers.
Pricing Analysis
Three-tier pricing structure across specification-grade, standard industrial, and economy levels governs procurement, with ATEX/IECEx certification tier and copper conductor purity driving differentiation. Cost compression in economy-grade unshielded multi-core runs intensifies because of LME copper volatility and legacy PVC substitution friction. Power generation utilities in Southeast Asia exhibit highest price sensitivity for tray-rated volume procurement, while North Sea offshore developers show lowest sensitivity for umbilical-integrated architectures.
Supply Chain Analysis
ATEX and IECEx certification gating restricts qualified supplier pools to manufacturers with 14-18 month approval timelines, concentrating viable production in Germany, Japan, and the United States. ETFE and FEP fluoropolymer resin supply rests on production clusters in China and Japan, creating single-source vulnerability for high-temperature insulation. Distribution runs through engineering-procurement-construction contractors and specialized industrial distributors serving lump-sum turnkey project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH-mandated PFAS reformulation costs and Asian manufacturing scale advantages, with compound chemistry expertise differential determining margin capture.
For Market Incumbents: Hedge fluoropolymer supply concentration by accelerating silicone rubber validation partnerships with US Gulf Coast chemical processors. Backward integration into recycled copper traceability systems captures EU Green Deal procurement scoring premiums. Defend specification-grade positioning through captive compound manufacturing rather than outsourced jacketing. For New Entrants and Emerging Players: REACH Annex XVII PFAS restrictions in Europe open a window for silicone and thermoplastic elastomer alternative suppliers lacking legacy fluoropolymer infrastructure. Target India's Dahej and Hazira petrochemical corridors for multi-core shielded cable penetration. Pursue BIS certification early to qualify for Reliance Industries and Indian Oil digital transformation tenders. For Investors and Strategic Acquirers: Asymmetric upside sits with compound-chemistry specialists possessing simultaneous fluoropolymer formulation and flame-retardant additive expertise. Long-term viability favors integrated material-compound-cable producers over asset-light designers across the analysis window. Monitor MEE environmental regulation announcements in China as inflection indicator for PFAS substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Compound Reformulation Partnership | REACH Annex XVII compliance secures European process industry access for German automotive suppliers. |
| Recycled Copper Traceability Investment | Verified circular material content satisfies EU Green Deal public tender scoring requirements. |
| Silicone Rubber Capacity Expansion | High-temperature steam tracing specifications from US Gulf Coast chemical processors displace fluoropolymer dependence. |
| Subsea Umbilical Integration | North Sea offshore wind developers consolidate power and fiber-optic instrumentation into single architectures. |
| BIS Certification Acceleration | Indian Oil and Reliance Industries tenders require domestic qualification for grid monitoring sensor networks. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market through structured interviews with plant engineers, EPC procurement leads, cable manufacturer technical directors, and compound chemistry R&D heads. Secondary validation draws from IEC standards documentation, REACH Annex XVII regulatory filings, SEC 10-K disclosures, and customs trade data. Bottom-up volume modeling triangulates against top-down industrial automation expenditure benchmarks.
Granularity-level modeling disaggregates demand across product type, installation method, end-use industry, and material chemistry, with regional regulatory framework as cross-cutting dimension. CAGRs derive from segment-specific growth rate reconciliation against macro industrial production indices. Forecast inputs incorporate sensor network densification rates in petrochemical corridors and PFAS substitution timeline assumptions.
Revisions become necessary when REACH enforcement intensity, copper price volatility bands, or offshore wind deployment schedules materially diverge from baseline assumptions. A model refresh is warranted upon material change in MEE environmental regulation announcements or IEC 61508 SIL certification requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Audio and Video Cables Market
Cables
High-Speed Interconnects Market
Cables
Multicore Cables Market
Cables
Europe Cable Joints Market
Cables
EPR Cable Market
Cables
Copper Cabling Systems Market
Cables
High Voltage Cable Termination Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Submarine Optical Fiber Cables Market
Cables
Shipboard Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
Water Leak Sensing Cable Market
Cables
Data Center Wire and Cable Market