
 USB Cable Market | 2026-2036
USB Cable Market Size, Share, and Industry Trends Forecast 2026-2036
USB Cable Market Outlook
E-commerce wholesale channels is reconfiguring how USB cable suppliers reach enterprise buyers and retail distributors. Luxshare Precision Industry Co. Ltd. anchors high-volume production for tier-one device OEMs through vertically integrated connector-cable assembly. Belkin International Inc. competes on brand recognition and retail shelf presence in North American consumer electronics stores. Anker Innovations Limited differentiates through direct-to-consumer positioning and power-delivery certification depth.
A USB cable is an electromechanical assembly comprising insulated copper conductors, shielding layers, and molded connectors designed to transmit data, power, or both between electronic devices per Universal Serial Bus protocol specifications. Manufacturing employs precision extrusion for conductor insulation, automated crimping for terminal attachment, and laser stripping for fiber optic variants to achieve specified impedance and bandwidth tolerances. USB Type-C now dominates new design-in activity across consumer electronics manufacturers and computer peripheral makers due to reversible insertion and expanded power delivery capacity. Fiber optic material configurations represent the fastest-growing structural segment as video transmission and high-speed data transfer applications push beyond copper bandwidth limits.
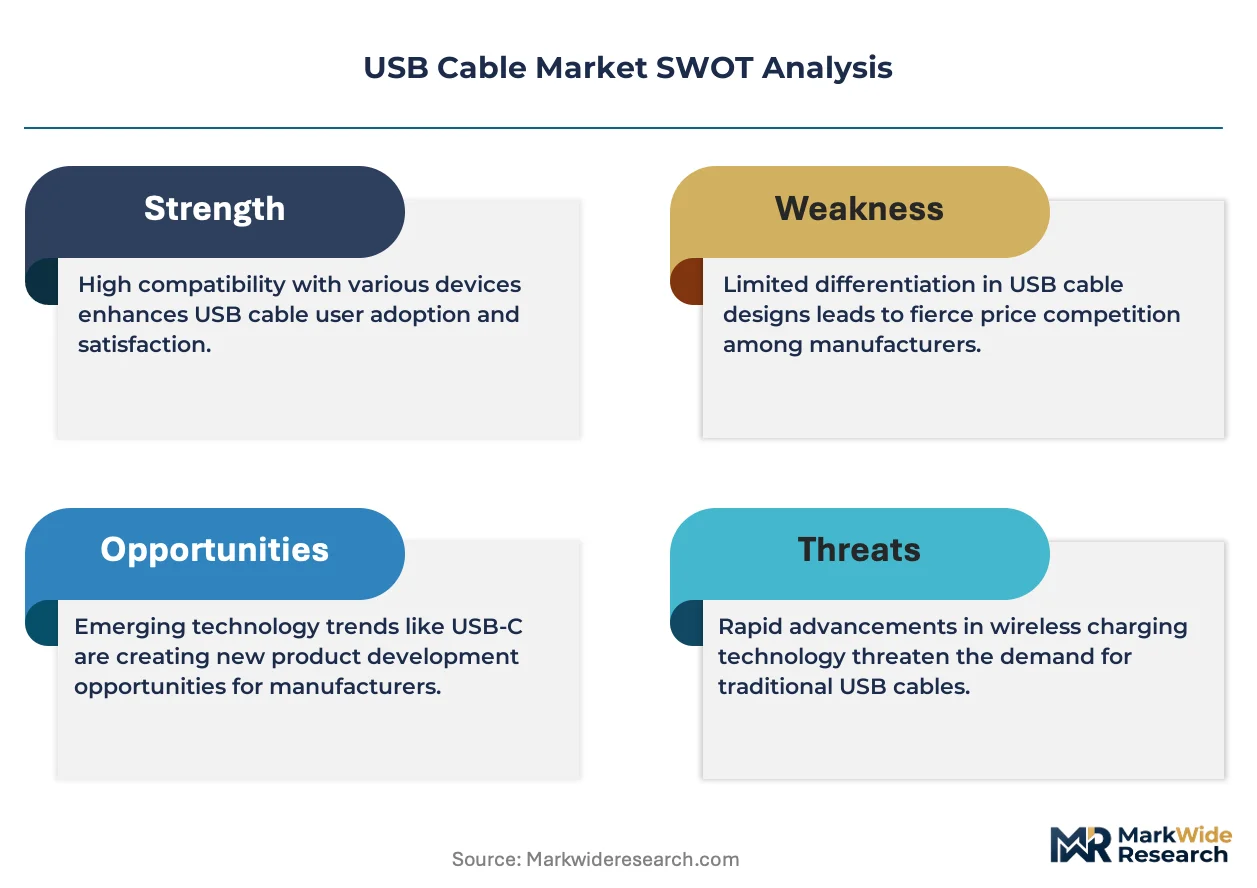
The USB Implementers Forum maintains connector certification programs that govern interoperability and safety testing for cable assemblies sold into consumer and commercial channels. The European Union's common charging port regulation, enforced through member state market surveillance authorities, mandates USB Type-C compatibility for smartphones, tablets, and cameras sold across Europe. China's GB standards and the US FCC electromagnetic compatibility framework impose additional conformance requirements on export-bound production. Stakeholders must monitor evolving power delivery specifications and regional enforcement timelines to align product roadmaps with compliance windows.
Market Dynamics
USB Type-C connector standardization is compressing proprietary cable ecosystems and forcing manufacturers to consolidate production lines around reversible, high-power-capable assemblies.
Growth Catalysts
- EU Common Charging Port Mandate:The European Union's regulation eliminating proprietary connectors for smartphones and tablets is accelerating USB Type-C adoption across device OEMs serving member state markets.
- Power Delivery Specification Expansion:USB Power Delivery 3.1 enabling 240W transmission is opening laptop and small appliance charging applications previously served by dedicated barrel connectors.
- Fiber Optic Material Advancement:Active optical cable configurations are penetrating video transmission and data center interconnect applications where copper conductor bandwidth limits constrain signal integrity.
Market Restraints
- Copper Price Volatility:Insulated copper conductor costs fluctuate with commodity exchange pricing, compressing margin on standard USB 2.0 and 3.0 cable categories where differentiation is minimal.
- Connector Certification Burden:USB Implementers Forum testing protocols and regional electromagnetic compatibility requirements impose fixed compliance costs that disproportionately burden low-volume cable assemblers.
- Wireless Charging Substitution:Qi-standard inductive charging pads are displacing wired power delivery in premium smartphone segments and automotive console applications.
Strategic Opportunities
- India Electronics Manufacturing:Production-linked incentive schemes for mobile device and component manufacturing are attracting cable assembly investments to serve domestic and export demand from Indian facilities.
- Automotive In-Cabin Connectivity:USB Type-C ports for rear-seat entertainment and driver phone integration are proliferating across electric vehicle and internal combustion engine platforms.
- E-commerce Direct Procurement:Enterprise buyers and retail distributors are bypassing traditional electronics wholesale channels to source certified cable assemblies through vertically integrated manufacturer storefronts.
Industry Challenges
- Precision Extrusion Talent Scarcity:Manufacturing engineers with expertise in tight-tolerance conductor insulation and automated crimping equipment programming command premium compensation in coastal Chinese industrial clusters.
- Legacy Inventory Stranding:USB Micro-B and proprietary connector cable stockpiles face accelerated obsolescence as EU enforcement timelines approach and OEM design-in activity shifts exclusively to Type-C.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Cable Market |
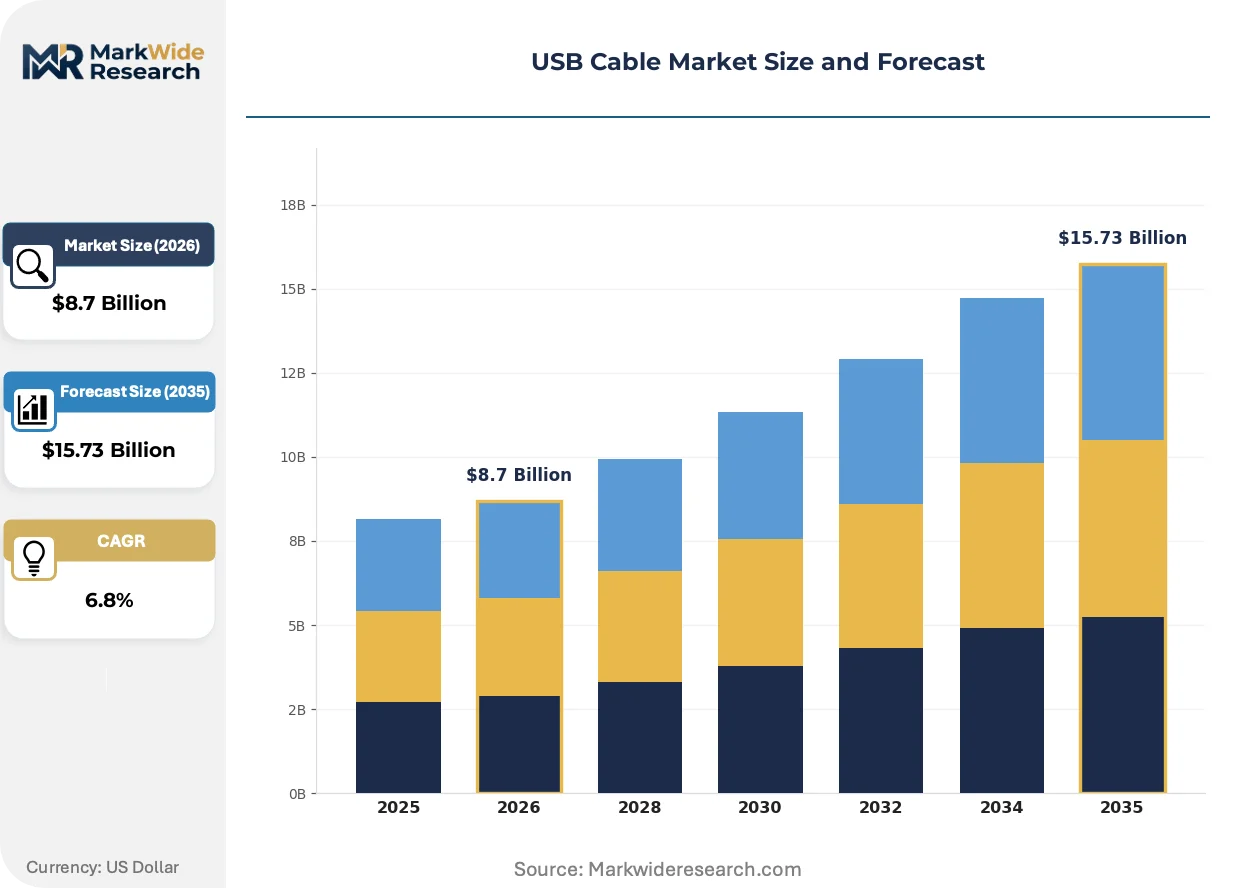
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Type-A, USB Type-B, USB Type-C, Micro USB, Mini USB Application: Data Transfer, Charging Devices, Audio Interfaces, Video Transmission, Power Delivery End User: Consumer Electronics Manufacturers, Computer Peripheral Makers, Mobile Device Producers, Automotive Electronics Suppliers, Industrial Equipment Designers Material: Copper, Aluminum, Fiber Optic, Tinned Copper, Silver Plated Conductors |
| Companies Covered | Belkin International Inc., Panasonic Corporation, Samsung Electronics Co. Ltd., AmazonBasics, UGREEN Group Limited, Apple Inc., Luxshare Precision Industry Co. Ltd., Baseus Technology Group, Anker Innovations Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Cable Market Strategic Shifts
Signal transmission architectures are bifurcating between copper dominance in cost-sensitive mass markets and fiber optic penetration in bandwidth-constrained professional applications.
Active optical cable technology is virtualizing traditional copper-based USB extension limitations. Fiber optic USB assemblies transmit 10Gbps+ signals across 50-meter spans without repeaters, enabling industrial machine vision and broadcast video workflows. Medical imaging equipment manufacturers and professional audio-visual integrators are specifying optical USB for electromagnetic interference-sensitive installations.
REACH substance restrictions and RoHS hazardous material directives are forcing connector plating chemistry revisions across European-bound production. Cadmium-free alternatives and halogen-free jacket compounds are becoming baseline specifications rather than premium options. Cable assemblers serving EU markets are requalifying entire product families to maintain CE marking eligibility.
Certification-driven preference formation is restructuring procurement evaluation criteria. Enterprise IT buyers now require USB Implementers Forum TID certification and independent power delivery safety testing prior to vendor qualification. Direct-to-consumer brands are leveraging certification depth as primary competitive differentiation against unbranded marketplace alternatives.
USB Cable Market Segmentation
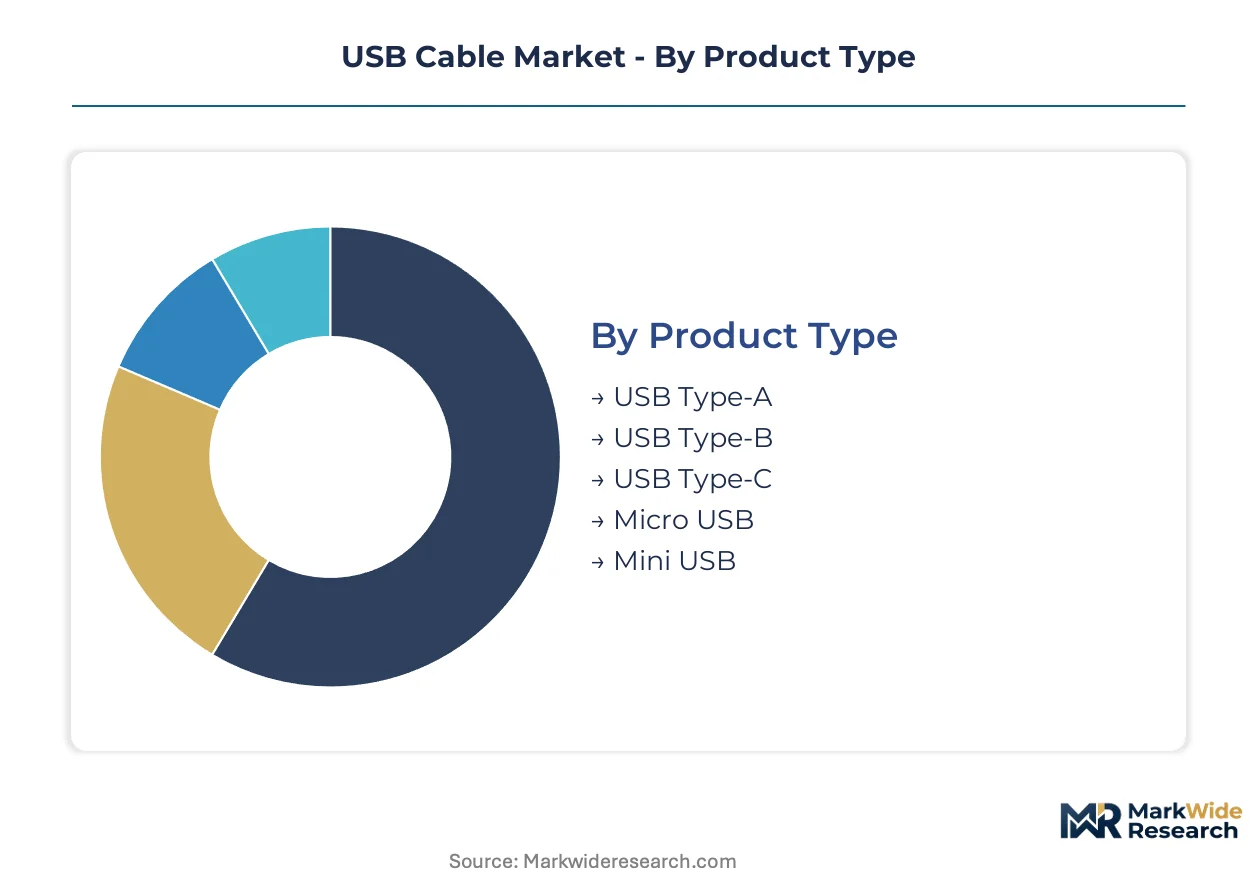
USB cable segmentation reflects divergent technical requirements across power delivery, data bandwidth, and environmental durability specifications. Procurement patterns vary sharply between cost-optimized consumer electronics and mission-critical industrial deployments.
Product Type:
Mature connector formats face accelerated displacement as reversible, high-power-capable designs capture design-in activity across device OEMs.
- USB Type-C:Reversible 24-pin configuration supports USB4 data rates and 240W power delivery through integrated configuration channel logic. Smartphone and laptop refresh cycles in China and Germany are consolidating procurement around this single connector standard.
- USB Type-A:Rectangular legacy interface retains installed base dominance in desktop computers, wall chargers, and automotive console ports where host-side compatibility requirements persist. Gradual phase-out is accelerating as peripheral makers complete Type-C transitions.
- USB Type-B:Squarish connector format persists in printer and industrial equipment applications requiring mechanical retention superior to micro formats. Niche demand concentrates in enterprise imaging hardware refresh programs.
- Micro USB:Compact 5-pin design faces inventory stranding as EU enforcement timelines approach and OEMs abandon this format for smartphones and tablets. Remaining demand channels through low-cost feature phone and IoT sensor segments.
- Mini USB:Obsolescent connector standard clings to legacy digital camera and portable GPS device support requirements. Replacement part demand dominates with minimal new design-in activity.
USB Type-C retains volume leadership; fiber optic-enabled Type-C variants hold the steepest expansion curve.
Application:
Functional specialization is fragmenting procurement specifications as power delivery and video transmission requirements diverge from basic data connectivity.
- Power Delivery:USB PD 3.1 protocol enables 240W transmission through enhanced SPR and EPR modes, replacing dedicated barrel connectors in gaming laptops and small appliances. Certification depth from USB Implementers Forum is becoming a non-negotiable vendor qualification criterion for enterprise IT buyers.
- Video Transmission:Alternate Mode signaling carries DisplayPort and HDMI protocols across Type-C cabling, consolidating dock and monitor connectivity. Professional AV integrators in the United States and Japan are specifying active optical variants for electromagnetic interference-sensitive broadcast installations.
- Data Transfer:USB4 and Thunderbolt 4 signaling demands precision impedance control through shielded twisted pair construction. Cloud data center interconnect applications are absorbing premium cable assemblies with independent signal integrity certification.
- Charging Devices:Basic 5V/2.4A configurations serve mass-market smartphone and accessory charging where cost minimization overrides performance margins. Unbranded marketplace alternatives dominate this price-compressed segment.
- Audio Interfaces:USB Audio Class 2.0 and 3.0 specifications drive demand in professional music production and podcasting equipment. Low-latency requirements favor short-run copper assemblies with gold-plated contact finishes.
Power Delivery commands the highest margin concentration; Video Transmission is climbing fastest on optical technology penetration.
End User:
Customer sophistication tiers separate certification-driven enterprise procurement from price-sensitive consumer electronics sourcing.
- Consumer Electronics Manufacturers:Tier-one device OEMs in China and South Korea anchor high-volume production through vertically integrated connector-cable assembly partnerships. EU common charging port mandates are forcing complete connector portfolio transitions ahead of enforcement deadlines.
- Mobile Device Producers:Smartphone and tablet specialists require ultra-flexible jacket compounds for bending durability testing. Regional regulatory fragmentation between FCC, CE marking, and GB standards necessitates multiple product family variants.
- Computer Peripheral Makers:Keyboard, mouse, and external storage vendors balance backward compatibility requirements against Type-C transition economics. Dock and hub manufacturers are driving demand for multi-port cable bundles with color-coded strain relief.
- Automotive Electronics Suppliers:In-cabin USB Type-C integration for rear-seat entertainment and driver phone pairing is proliferating across electric vehicle platforms from Germany and the United States. Temperature cycling and vibration specifications exceed consumer-grade requirements.
- Industrial Equipment Designers:Machine vision and factory automation applications specify shielded assemblies with IP67-rated overmolding for contaminant resistance. Active optical cables are penetrating bandwidth-constrained installations beyond copper distance limitations.
Consumer Electronics Manufacturers retain volume leadership; Automotive Electronics Suppliers hold the steepest expansion curve.
Material:
Conductive and shielding material selection directly determines bandwidth ceiling, flex life, and regional regulatory compliance eligibility.
- Copper:Oxygen-free high-conductivity copper dominates signal and power conductors across all USB generations. LME price volatility is compressing margins on standard-speed cable categories where material cost represents the largest cost stack component.
- Fiber Optic:Active optical cable configurations transmit 10Gbps+ signals across 50-meter spans without repeaters, enabling industrial machine vision and medical imaging workflows. EMEA and North American professional AV markets are specifying optical USB for electromagnetic interference immunity.
- Aluminum:Lightweight shielding alternative reduces overall cable weight in aerospace and portable electronics applications. Conductivity trade-offs limit deployment to lower-speed USB 2.0 configurations.
- Tinned Copper:Solder-dipped conductor strands enhance oxidation resistance in high-humidity environments and simplify hand-soldering termination for custom cable houses. Marine and outdoor applications specify this material for salt spray durability.
- Silver Plated Conductors:Precious metal plating reduces skin effect losses at gigahertz frequencies for premium USB4 and Thunderbolt assemblies. Professional audio and test equipment manufacturers absorb the material cost premium for signal integrity margins.
Copper retains volume leadership; Fiber Optic holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex anchors Asia-Pacific cable assembly exports, while Rotterdam's container terminals handle European distribution for Type-C inventories bound for German and French electronics manufacturers.
China
Smartphone refresh cycles and laptop production lines in Dongguan and Shenzhen drive Type-C cable procurement at scale. GB standards from SAMR mandate electromagnetic compatibility testing for all export-bound assemblies. The Pearl River Delta industrial cluster hosts vertically integrated connector-cable production facilities serving tier-one device OEMs.
Germany
Automotive electronics suppliers in Bavaria specify USB Type-C for in-cabin connectivity across electric vehicle platforms. The EU common charging port regulation, enforced through BNetzA market surveillance, eliminates proprietary connectors for smartphones and tablets. The Munich-Stuttgart corridor concentrates cable procurement offices for premium automotive OEMs.
United States
Enterprise IT buyers in Northern California and Texas require USB-IF TID certification for data center and professional AV deployments. FCC electromagnetic compatibility rules impose conformance testing on all cable assemblies sold domestically. The Austin-Dallas tech corridor absorbs high volumes of power-delivery certified cables for device OEM headquarters.
India
Mobile device manufacturing under PLI schemes in Uttar Pradesh and Tamil Nadu is attracting cable assembly investments for domestic and export demand. BIS certification requirements govern connector safety for India-bound production. The Noida-Greater Noida electronics manufacturing cluster hosts new cable extrusion and crimping capacity.
Japan
Professional audio-visual integrators in Tokyo and Osaka specify active optical USB for broadcast and medical imaging applications. METI technical standards govern high-speed data transmission cable performance. The Kanto region concentrates procurement for precision impedance-controlled assemblies serving industrial equipment designers.
USB Cable Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying connector and conductor inputs. The market structures around three concentration layers: multinational electronics brands with captive cable sourcing, specialized cable assemblers with certification depth, and commodity producers competing on unit economics. Dominant competitive moves include backward integration into connector manufacturing and geographic expansion toward India electronics manufacturing zones.
Among China-based fabricators, Luxshare Precision Industry Co. Ltd. and UGREEN Group Limited exemplify scale-driven assembly archetypes with vertically integrated production footprints. Belkin International Inc. and Anker Innovations Limited occupy positions within the brand-recognized tier competing on certification depth and retail channel presence. These four anchors illustrate the bifurcation between manufacturing-scale competitiveness and consumer-facing brand differentiation.
| Leading Market Players |
|---|
| Belkin International Inc. |
| Panasonic Corporation |
| Samsung Electronics Co. Ltd. |
| AmazonBasics |
| UGREEN Group Limited |
| Apple Inc. |
| Luxshare Precision Industry Co. Ltd. |
| Baseus Technology Group |
| Anker Innovations Limited |
| Others |
Value Chain & Pricing Dynamics
Connector-cable assembly concentration in China's Pearl River Delta feeds margin capture downstream toward certification-holding brand owners in North America and Europe. Copper conductor costs transmit directly into standard-speed cable pricing, while optical fiber assemblies command premium positioning through bandwidth performance separation.
Pricing Analysis
Volume-discount tiering structures stratify across USB-IF certification depth, with TID-certified power-delivery cables capturing three-to-five-fold premiums over unbranded marketplace alternatives. Price differentiation hinges on certification grade and volume scale, with enterprise IT procurement requiring independent safety testing as a non-negotiable qualification threshold. Cost compression in standard USB 2.0 and 3.0 categories is intensifying because copper commodity volatility squeezes assemblers lacking backward integration into conductor drawing. Consumer electronics accessory buyers exhibit highest price sensitivity, while automotive electronics suppliers absorb material premiums for temperature-cycling compliance.
Supply Chain Analysis
Upstream feedstock flows draw from copper cathode exchanges in Chile and China, optical fiber preform from the United States and Japan, and halogen-free jacket compounds from European specialty chemical producers. Raw material dependencies center on LME-tracked copper pricing, rare-earth-doped fiber amplifiers, and REACH-compliant plating chemistry. Single-source vulnerability concentrates in precision extrusion equipment servicing tight-tolerance USB4 and Thunderbolt assemblies. Distribution runs through vertically integrated manufacturer storefronts reaching enterprise buyers directly, bypassing traditional electronics wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USB cable procurement is becoming a service-attach opportunity as certification management and compliance documentation subscriptions expand faster than hardware unit shipments. After-sales technical support and regulatory update services represent the recurring-revenue layer accelerating beyond physical cable margins.
For Market Incumbents: Insulate market position by deepening captive control over connector injection molding capacity in Dongguan and Shenzhen industrial clusters. Accelerate USB-IF certification portfolio breadth ahead of EU common charging port enforcement timelines. Defensive consolidation around precision extrusion talent pools commands premium compensation in coastal Chinese manufacturing zones.
For New Entrants and Emerging Players: Automotive in-cabin USB Type-C integration for electric vehicle platforms in Germany and the United States represents the most penetrable entry point, with temperature-cycling specifications exceeding consumer-grade capabilities that incumbent consumer specialists struggle to meet. India's PLI-scheme mobile device manufacturing zones in Uttar Pradesh and Tamil Nadu offer second-mover assembly capacity without legacy Micro-B inventory stranding. Direct-to-enterprise procurement through vertically integrated storefronts bypasses entrenched distribution relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across active optical cable sub-segments as fiber alignment and signal conditioning electronics require cleanroom assembly investments beyond copper crimping economics. Long-term viability over the analysis window favors assemblers with demonstrated USB-IF TID certification depth and automotive OEM qualification track records. Acquisition target archetypes include precision impedance-control specialists serving data center interconnect applications. Signal to monitor: BIS certification completion rates for India-bound production as PLI scheme utilization inflects.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Connector Manufacturing | Captive supply of USB-IF certified connectors insulates Luxshare and UGREEN from external component volatility. |
| Active Optical Cable Capacity Expansion | 50-meter span fiber assemblies penetrate broadcast video and medical imaging beyond copper distance limits. |
| India Manufacturing Footprint Establishment | Noida-Greater Noida cluster positions assemblers for PLI-scheme mobile device procurement. |
| USB-IF Certification Portfolio Deepening | TID certification for 240W power delivery becomes non-negotiable for enterprise IT vendor qualification. |
| Direct-to-Enterprise Channel Development | Vertically integrated storefronts bypass wholesale intermediaries for data center and automotive procurement. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of USB Implementers Forum certification databases, SAMR GB standards filings, and EU common charging port regulatory impact assessments. Primary interviews engaged cable assembly plant managers, procurement leads at tier-one device OEMs, USB-IF compliance officers, and automotive electronics supplier quality directors. Secondary validation drew from customs trade data, FCC electromagnetic compatibility filings, and SEC 10-K supply chain disclosures. Bottom-up unit economics triangulate against top-down market sizing across connector type, application function, and end-user sophistication tiers.
Forecast inputs consider power-delivery specification evolution, regional enforcement timeline phasing, and fiber optic penetration curves across professional AV and industrial machine vision segments. Segmentation dimensions modeled include connector format transition velocity, certification depth tiers, material conductivity architecture, and geographic manufacturing cluster expansion. CAGRs derive from regression against historical refresh cycle patterns and regulatory mandate implementation schedules. Copper commodity volatility and wireless charging substitution rates represent key sensitivity inputs.
Practitioners should monitor EU member state market surveillance enforcement intensity, India PLI scheme capacity utilization inflections, and USB-IF power delivery specification revision cadence for early signals requiring forecast reassessment. Cross-checking against USB Implementers Forum quarterly certification statistics and SAMR standards update bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Flat Flexible Cables Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Industrial Cable Reels Market
Cables
Cable Material Market
Cables
Submarine Data Cables Market
Cables
Cable Trunking Market
Cables
Multicore Cables Market
Cables
Military Fiber Optic Cables Market
Cables
Global Wires and Cables Market
Cables
Power and Signal Cables Market
Cables
Low Voltage Cable Accessories Market
Cables
Low-Temperature Cable Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Global Cable Tie Market
Cables
Middle East Cable Market
Cables
Europe HVAC Cables Market