
 Network Cable Tester Market | 2026-2036
Network Cable Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Network Cable Tester Market Foresight
Data center infrastructure expansion is recalibrating procurement priorities across enterprise and colocation environments. Fluke Networks leverages its certification-grade portfolio to anchor relationships with tier-one facility operators. Keysight Technologies sustains R&D intensity in high-speed Ethernet validation, while VIAVI Solutions specializes in fiber-centric test architectures for hyperscale deployments.
A network cable tester is an electronic instrument that verifies electrical connectivity, wiremap integrity, and transmission performance across copper and fiber-optic cabling systems, typically measuring parameters such as insertion loss, return loss, and near-end crosstalk to certify compliance with structured cabling standards. Its primary commercial purpose is to reduce installation rework and guarantee that deployed infrastructure meets specified bandwidth capacity for data and voice networks. Portable units dominate field deployment scenarios where contractor mobility matters, while rack-mounted systems occupy permanent network operations centers demanding continuous link monitoring. Ethernet-focused testers represent the fastest-growing technology slice as 400G and 800G port rollouts multiply validation complexity.
FCC equipment authorization rules govern electromagnetic emissions compliance for testers sold into US telecommunications infrastructure, while TIA and ISO/IEC standards define the performance thresholds that certification-grade instruments must verify. The EU AI Act and CE marking requirements shape product design cycles for European-bound equipment, particularly where automated fault diagnosis features incorporate embedded analytics. Stakeholders must monitor how emerging 1.6T Ethernet standards and corresponding test specifications will reshape R&D roadmaps and hardware refresh cadences.
Market Dynamics
400G and 800G Ethernet port rollouts are compressing validation timelines and forcing hardware refresh cycles across certification-grade tester portfolios. This bandwidth inflection point is recalibrating R&D priorities toward high-speed signal integrity measurement.
Growth Catalysts
- TIA-568 certification mandates:North American structured cabling standards now require documented wiremap and transmission performance verification for commercial installations, elevating procurement of certification-grade instruments.
- Hyperscale data center buildouts:Cloud facility operators in the United States, Germany, and Japan are deploying fiber-deep architectures that demand advanced optical time-domain reflectometry validation.
- Fiber-to-the-premises expansion:Telecommunications infrastructure programs across multiple geographies are accelerating field technician deployment of portable optical loss test sets.
Market Restraints
- Semiconductor component concentration:Specialized analog-to-digital converters and high-frequency signal processors source predominantly from East Asian foundries, creating supply vulnerability.
- Calibration service oligopoly:ISO/IEC 17025-accredited calibration laboratories concentrate in Germany, the United States, and Japan, extending equipment downtime for operators elsewhere.
- Copper tester commoditization:Low-cost wiremap-only devices from unbranded manufacturers erode margin structures at the standard-grade tier.
Strategic Opportunities
- India data center localization:The country's PLI scheme for electronics manufacturing and emerging hyperscale campuses create underpenetrated demand for certification-grade validation equipment.
- 1.6T Ethernet pre-standard testing:IEEE 802.3dj draft specifications enable early-mover positioning for signal integrity instrumentation ahead of formal ratification.
- Cloud-based test data management:SaaS platforms for certificate storage and trend analytics represent a recurring revenue attach opportunity beyond hardware sales.
Industry Challenges
- High-speed signal integrity expertise scarcity:Technicians proficient in 112 Gbps PAM4 measurement and analysis command premium compensation, constraining field service scaling.
- Multi-standard firmware complexity:Simultaneous support for TIA-568, ISO/IEC 11801, and emerging IEEE standards extends development cycles and validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Cable Tester Market |
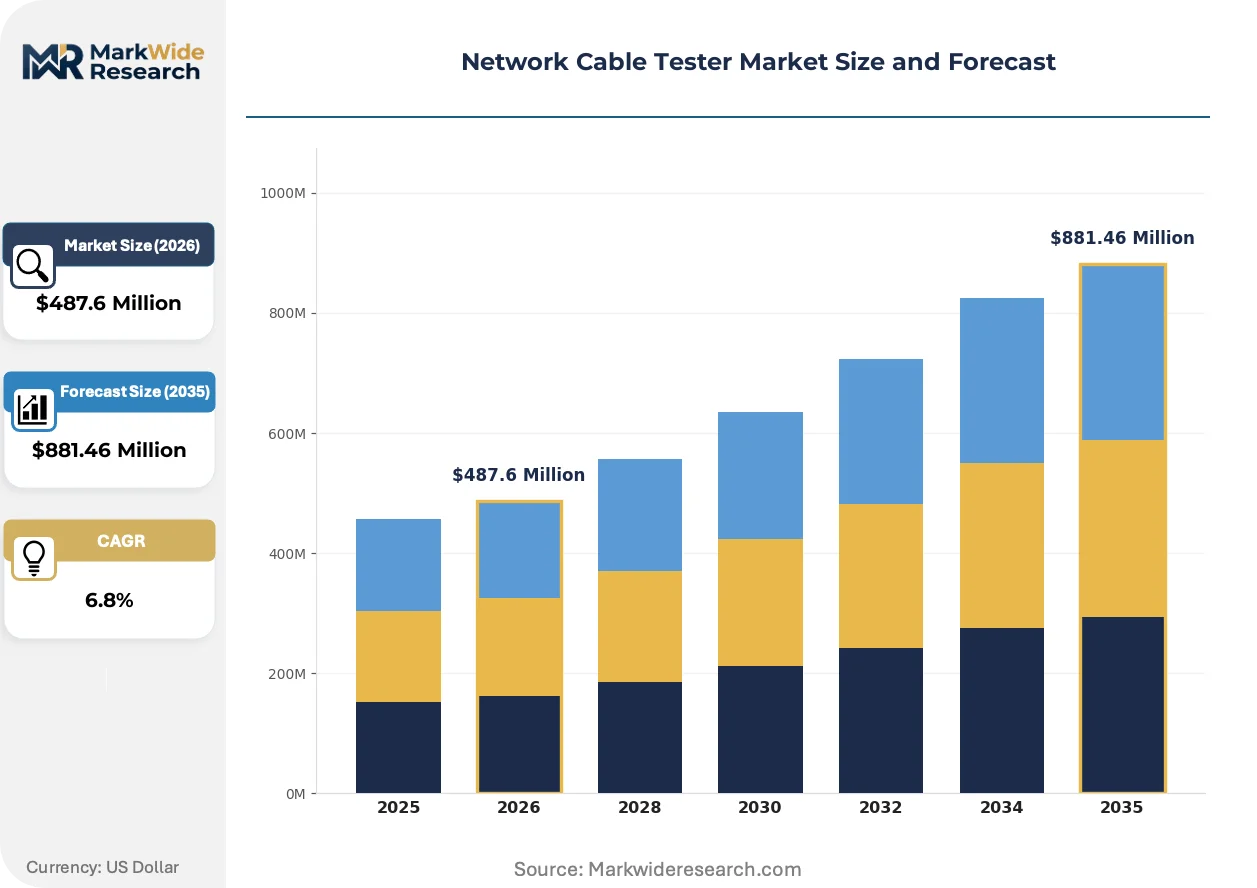
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Rack-mounted, Multi-function, Ethernet Technology: Wiremap, TDR, PoE, LAN End User: Telecommunications, IT Departments, Contractors, Educational Institutions Application: Installation, Maintenance, Troubleshooting, Certification |
| Companies Covered | Fluke Networks, Keysight Technologies, VIAVI Solutions, Ideal Industries, EXFO Inc., Anritsu Corporation, Klein Tools, TREND Networks, Softing IT Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Cable Tester Market Shifts & Advancements
Test instrumentation is migrating from standalone hardware toward integrated platforms that combine physical layer validation with cloud-native data management. This architectural shift is compressing the traditional boundary between field instrumentation and enterprise IT systems.
Modular tester architectures are converging with software-defined measurement capabilities. Tier-one facility operators in hyperscale campuses now specify platforms where hardware acquisition cost decouples from feature unlocks via firmware licensing. This model is converging with procurement expectations shaped by IT infrastructure purchasing, compressing capital expenditure recognition timelines for manufacturers while extending customer lifetime value through subscription attach.
The EU AI Act and corresponding CE marking requirements for embedded analytics are reshaping product development cycles for European-bound equipment. Automated fault diagnosis features incorporating machine learning inference now face conformity assessment procedures previously reserved for safety-critical systems. Certification-grade instrument manufacturers serving Germany, France, and the Netherlands are responding by segregating AI-enabled SKUs from base configurations to isolate regulatory scope.
Certification-driven preference shifts are consolidating purchasing authority within enterprise IT infrastructure teams. Where electrical contractors historically specified field testers, data center operators now mandate approved vendor lists aligned with their structured cabling certification programs. This concentration is most visible in United States colocation markets, where standardized equipment reduces training overhead and enables centralized test data repositories.
Network Cable Tester Market Segmentation
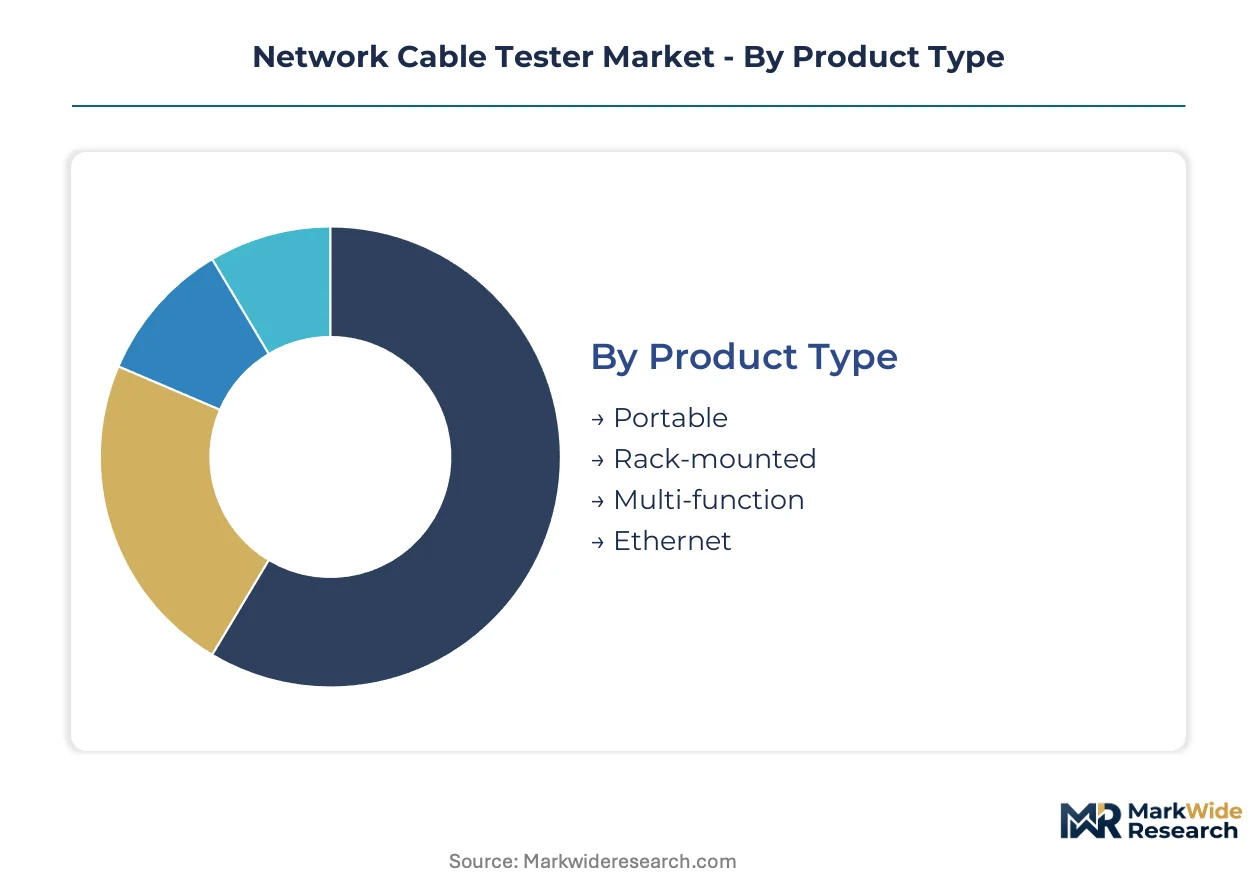
Segmentation in the network cable tester market reveals how capital allocation, technical complexity, and end-use requirements reshape procurement patterns across certification-grade and standard-grade tiers. Understanding these divisions clarifies why hyperscale operators and field contractors rarely source from the same supplier portfolios.
Product Type:
Capital intensity varies dramatically across form factors, with rack-mounted systems demanding the highest upfront investment in precision optics and thermal management infrastructure.
- Portable:Battery-powered handheld units integrate copper wiremap verification with basic optical loss measurement for field technician mobility. Demand concentrates among electrical contractors in Germany and the United States where TIA-568 certification mandates drive tool refresh cycles, though margin pressure from unbranded Asian manufacturers constrains premium positioning.
- Rack-mounted:Permanent installation platforms combine continuous link monitoring with centralized test data aggregation for network operations centers. Hyperscale campuses in Japan and the United States specify these systems for 400G/800G validation density, requiring ISO/IEC 17025 calibration infrastructure that extends total cost of ownership.
- Multi-function:Modular architectures supporting copper, fiber, and coaxial test through swappable adapters.
- Ethernet:Purpose-built instruments optimized for RJ45 termination verification and Power over Ethernet load testing.
Most installed capacity flows through Portable units. Expansion is steepest in Rack-mounted systems.
Technology:
Technical sophistication determines which segments command premium pricing versus commodity positioning in procurement decisions.
- Wiremap:Basic continuity and pinout verification functions represent the lowest technical barrier to entry, with functionality now embedded in smartphone-accessory form factors that erode standalone device markets.
- TDR:Time-domain reflectometry enables precise fault location in copper cabling through impedance discontinuity analysis. Data center operators in the United States and Japan deploy TDR-capable units for pre-certification troubleshooting, reducing installation rework costs that otherwise escalate in fiber-deep architectures.
- PoE:Power over Ethernet validation measures voltage drop and power delivery capacity across structured cabling runs. IT departments in Germany specify PoE test functions as IEEE 802.3bt high-power standards proliferate in smart building deployments, creating incremental attach revenue for certification-grade portfolios.
- LAN:Network-layer traffic generation and protocol analysis capabilities extend physical-layer testers into active equipment validation.
Wiremap dominates unit shipments. TDR capabilities are gaining share fastest among premium procurement segments.
End User:
Customer type dictates whether procurement flows through centralized IT infrastructure teams or decentralized contractor networks.
- Telecommunications:Carrier infrastructure divisions specify field-hardened optical test sets for FTTP deployment and maintenance, with procurement authority consolidating at national network engineering centers.
- IT Departments:Enterprise technology organizations mandate approved vendor lists aligned with structured cabling certification programs, most visible in United States colocation markets where standardized equipment reduces training overhead.
- Contractors:Electrical installation firms prioritize portable units with rapid wiremap feedback and durable chassis design for construction site conditions.
- Educational Institutions:University and technical college networks represent sporadic demand tied to campus infrastructure refresh cycles and vocational training program equipment grants.
IT Departments control the highest-value procurement decisions. Contractors generate the largest unit volumes.
Application:
Use-case segmentation separates one-time capital expenditure from recurring service revenue opportunities in manufacturer business models.
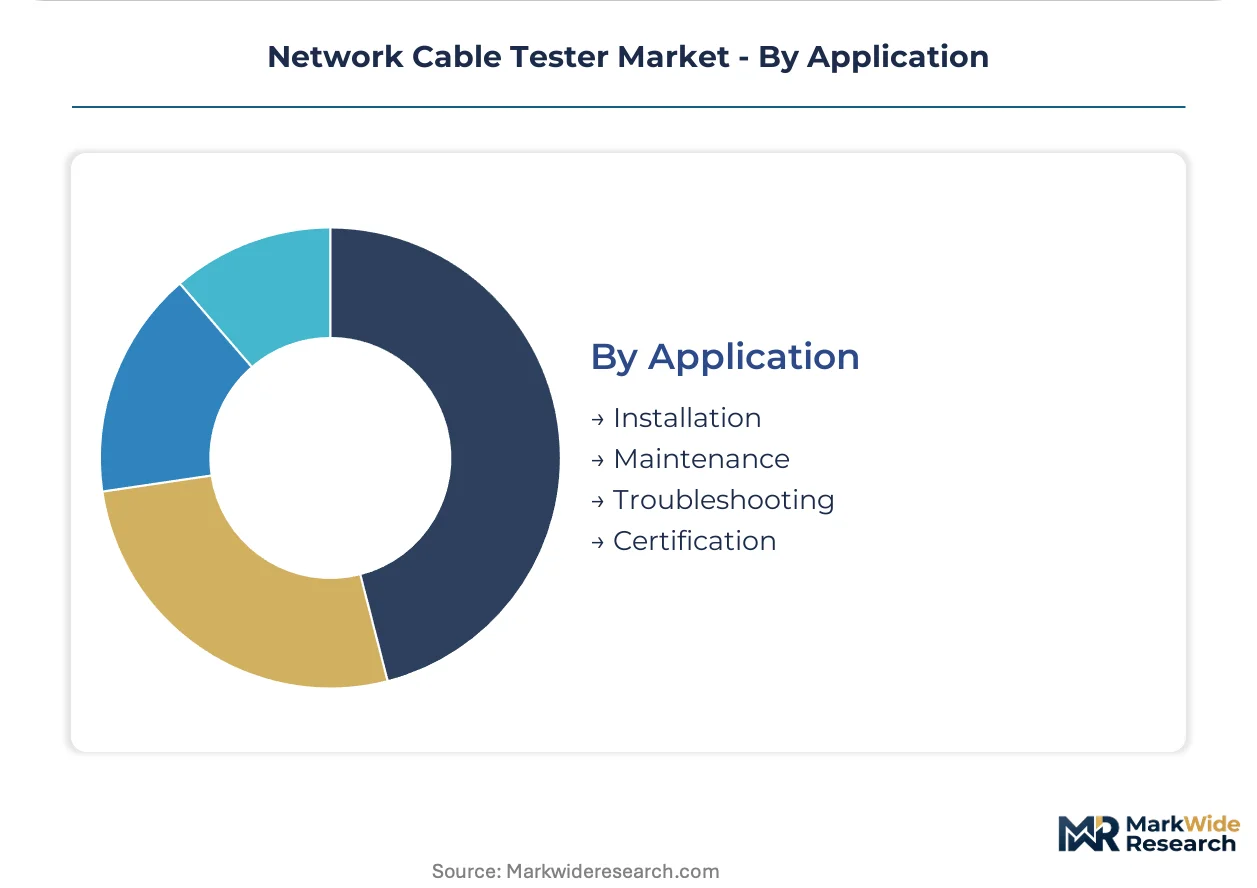
- Installation:Initial deployment verification requires comprehensive wiremap, length, and transmission performance measurement to certify compliance before client handover.
- Maintenance:Periodic link re-certification and preventive testing programs create recurring calibration and firmware subscription attach opportunities.
- Troubleshooting:Fault isolation applications prioritize speed of diagnosis over comprehensive documentation, favoring portable units with intuitive user interfaces.
- Certification:Formal compliance documentation for TIA-568 and ISO/IEC 11801 standards demands traceable measurement accuracy and cloud-based certificate storage, commanding premium pricing tiers.
Installation consumes the majority of hardware shipments. Certification applications deliver the highest margins and longest customer retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting manufacturing investment toward economies with streamlined conformity assessment procedures. Calibration infrastructure concentration in Germany, the United States, and Japan creates compliance cost arbitrage that shapes regional procurement patterns.
United States
Hyperscale data center construction in Northern Virginia, Dallas-Fort Worth, and Phoenix is compressing validation equipment procurement timelines. FCC equipment authorization rules govern electromagnetic emissions compliance for field-deployed testers. Cloud facility operators in Ashburn, Virginia specify certification-grade instruments aligned with TIA-568 structured cabling mandates.
Germany
Industrial automation networks and smart building deployments are elevating PoE validation requirements across Bavaria and Baden-Württemberg. The EU AI Act and CE marking requirements reshape product development cycles for embedded analytics features. Calibration laboratories in Munich and Stuttgart anchor ISO/IEC 17025-accredited service infrastructure for Central European operators.
Japan
Telecommunications infrastructure investment and fiber-deep hyperscale architectures concentrate demand in Tokyo, Osaka, and Nagoya metropolitan corridors. METI industrial standards and JIS certification protocols govern instrument performance specifications. Precision electronics manufacturing clusters in Chubu region supply specialized analog-to-digital converters for high-frequency signal processing.
India
Data center localization under the PLI scheme for electronics manufacturing is generating underpenetrated demand for certification-grade validation equipment. BIS technical standards and TRAI telecommunications regulations frame procurement specifications for network infrastructure. Emerging hyperscale campuses in Maharashtra and Karnataka require structured cabling certification programs aligned with international standards.
China
Domestic cloud infrastructure expansion and 5G backhaul deployment sustain wiremap and optical loss test set demand across Yangtze River Delta manufacturing corridors. MIIT equipment certification and GB standards compliance requirements structure market access for imported instruments. Shenzhen and Dongguan electronics clusters produce low-cost wiremap devices that pressure standard-grade pricing tiers.
Network Cable Tester Market Competitive Landscape
Strategic partnerships dominate the current landscape as tier-one facility operators consolidate approved vendor lists around certification-grade portfolios. The vendor base concentrates across three tiers: precision instrumentation multinationals with calibration service networks, regional specialists with fiber-centric architectures, and commoditized wiremap device manufacturers. Two archetypes anchor competitive positioning: full-stack certification platforms and modular field-hardened units. M&A activity and firmware licensing models represent the dominant competitive vectors reshaping capital expenditure recognition timelines.
Within the precision instrumentation tier, Fluke Networks and Keysight Technologies exemplify divergent strategic positioning. VIAVI Solutions occupies a specialist position in fiber-centric test architectures. These three companies collectively represent the certification-grade anchor points around which hyperscale procurement specifications consolidate. Their geographic footprints—American, American, and American respectively—reflect the concentration of data center demand and calibration infrastructure in the United States. Each anchors relationships with tier-one facility operators through distinct technical specializations rather than overlapping product portfolios.
| Leading Market Players |
|---|
| Fluke Networks |
| Keysight Technologies |
| VIAVI Solutions |
| Ideal Industries |
| EXFO Inc. |
| Anritsu Corporation |
| Klein Tools |
| TREND Networks |
| Softing IT Networks |
| Others |
Supply & Pricing Matrix
Hyperscale data center operators in Northern Virginia and Frankfurt concentrate procurement authority for certification-grade instruments, forcing manufacturers toward value-based pricing anchored in ISO/IEC 17025 calibration bundling rather than transactional hardware margins.
Pricing Analysis
Distributor markups of 15-25 percentage points separate factory pricing from end-user acquisition cost in European and North American channels. Certification-grade portfolios command three-tier pricing structure across premium, standard, and economy levels based on measurement accuracy tolerances and cloud-data subscription inclusion. Cost compression in wiremap-only devices intensifies because Shenzhen manufacturers flood contractor segments with sub-$100 units. Field contractors exhibit highest price sensitivity, while IT infrastructure teams at colocation facilities prioritize total cost of ownership over upfront hardware expenditure.
Supply Chain Analysis
Air freight premiums from East Asian semiconductor clusters add 8-12 percentage points to landed cost for high-frequency signal processors sourced from Taiwan and South Korea. Precision analog-to-digital converters and thermal management subassemblies draw from Japanese and German component ecosystems. Single-source vulnerability concentrates in specialized optics for OTDR modules manufactured in Chubu region facilities. Distribution runs through authorized service partners with calibration accreditation rather than traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on firmware licensing decoupled from hardware refresh cycles, allowing manufacturers to capture recurring revenue from installed certification-grade bases without incremental production cost.
For Market Incumbents: Lock in hyperscale procurement specifications through embedded cloud-data platforms that create switching costs beyond hardware replacement. Deepen calibration service network density in India and Southeast Asia to preempt emerging campus buildouts. Unbranded Asian wiremap manufacturers threaten standard-grade margins most acutely in contractor channels. For New Entrants and Emerging Players: The 40-60 percentage point spread between Fluke Networks certification units and economy wiremap devices offers white-space targeting for mid-tier modular architectures. India's PLI-supported data center localization represents the most penetrable geography for certification-grade entry. SaaS test data management attachments provide a go-to-market angle that sidesteps capital-intensive calibration infrastructure requirements. For Investors and Strategic Acquirers: Precision instrumentation multinationals are the most active acquirers in this space, consolidating fiber-centric specialists to round out hyperscale validation portfolios. Five-to-ten year viability favors manufacturers with captive calibration laboratory networks and firmware-subscription revenue exceeding 30 percent of total mix. The signal to monitor is IEEE 802.3dj ratification timing, which will trigger hardware refresh decisions across 400G-installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ISO/IEC 17025 accreditation in India reduces equipment downtime for PLI-funded data centers. |
| Firmware-Defined Feature Unlocking | Subscription licensing extends customer lifetime value beyond initial hardware recognition. |
| Fiber-Deep Architecture Specialization | OTDR expertise captures hyperscale procurement specifications in Ashburn and Frankfurt. |
| Cloud-Native Test Data Platform | Centralized certificate storage creates procurement stickiness with IT infrastructure teams. |
| 1.6T Ethernet Pre-Standard Instrumentation | Early IEEE 802.3dj alignment positions manufacturers for 800G refresh wave timing. |
Research Methodology
Multiple input streams — structured interviews with data center infrastructure directors, calibration laboratory technical leads, and electrical contractor procurement managers — were reconciled against TIA standards documentation, FCC equipment authorization filings, and hyperscaler capital expenditure disclosures. Secondary validation drew from SEC 10-K instrument revenue segmentations, ISO/IEC maintenance records, and trade customs data for optical test set imports. Bottom-up unit shipment estimates and top-down addressable market sizing were cross-referenced to anchor volume assumptions.
Historical certification-grade pricing trajectories were cross-referenced against panel input from tier-one facility operators to model replacement cycle timing across the projection horizon. Segmentation dimensions included form factor portability, measurement technology sophistication, end-user procurement authority, and application purpose from installation through recurring maintenance. CAGRs were derived from weighted average of infrastructure capex growth and standards-mandated refresh elasticity. Fiber-deep architecture penetration and 400G port deployment density served as industry-specific demand drivers.
Caveats apply where semiconductor supply disruptions or delays in IEEE 802.3dj ratification could materially shift the outlook for high-speed signal integrity instrumentation demand. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fire Resistance Cable Market
Cables
Polyurethane Cable Market
Cables
Low Voltage Cable Accessories Market
Cables
Europe Cable Management Market
Cables
Europe Cable Accessories Market
Cables
Cable Testing and Certification Market
Cables
Active Optical Cable Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Copper Cabling Systems Market
Cables
Electric Submersible Cable Sales Market
Cables
Coaxial Cable Market
Cables
Solar Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Wire and Cable Label Market
Cables
High-Speed Interconnects Market
Cables
Cable Management Accessories Market