
 Electric Vehicle Unshielded HV Cables Market | 2026-2036
Electric Vehicle Unshielded HV Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Unshielded HV Cables Market Insights
Buyer concentration among top-tier EV original equipment manufacturers is hardening as platform consolidation favors suppliers with multi-gigafactory qualification. LEONI leverages its European manufacturing footprint to anchor contracts with premium German automakers requiring ISO 6722 compliant unshielded architectures. Sumitomo Electric sustains Japanese market dominance through vertical integration into copper smelting and polymer compounding operations. Prysmian Group competes on charging infrastructure scale, controlling project pipelines across North American and European ultra-fast charging networks.
Electric vehicle unshielded HV cables are non-screened conductors rated typically from 600V to 1500V DC, constructed with stranded copper or aluminum cores insulated by cross-linked polyethylene or silicone compounds, designed to transmit power between battery packs, inverters, and motors without electromagnetic shielding to save mass and cost. Power cables dominate current revenue pools due to their ubiquity across every battery-electric drivetrain, while charging cables represent the fastest-expanding segment as 350kW+ station deployments multiply. Aluminum material adoption is accelerating fastest among segments as OEMs pursue kilogram reduction targets, though copper still commands premium applications where conductivity tolerance is non-negotiable.
China's MIIT and SAMR enforce GB/T standards governing high-voltage cable flame resistance and thermal cycling endurance, directly shaping supplier qualification requirements for domestic EV platforms. Europe's REACH and RoHS frameworks restrict halogenated flame retardants in polymer insulation, forcing reformulation investments across cable producers serving EU-registered vehicles. Stakeholders must monitor evolving battery voltage architectures—particularly 800V platform migrations—as these will redefine conductor sizing, insulation thickness, and connector integration requirements across the supply base.
Market Dynamics
Platform consolidation among battery-electric vehicle manufacturers is compressing supplier qualification timelines while simultaneously elevating technical barriers for cable architecture approval. This concentration dynamic rewards incumbents with multi-gigafactory validation history and marginalizes regional specialists lacking OEM platform access.
Growth Catalysts
- MIIT efficiency mandates:China's Ministry of Industry and Information Technology weight-reduction targets are accelerating aluminum conductor adoption in Jiangsu and Zhejiang manufacturing corridors.
- 800V architecture migration:High-voltage platform transitions are expanding unshielded cable deployment in powertrain segments where electromagnetic interference tolerance permits material substitution.
- Ultra-fast charging infrastructure:350kW+ station deployments across North American highway corridors are multiplying charging cable procurement volumes.
Market Restraints
- Copper price volatility:LME copper futures fluctuations are compressing margin predictability for stranded conductor producers locked into annual OEM supply agreements.
- Polymer feedstock concentration:Cross-linked polyethylene compounding capacity clusters in East Asian petrochemical hubs, creating geographic single-source vulnerability.
- REACH formulation costs:Europe's halogenated flame retardant restrictions are forcing reformulation investments that disadvantage smaller cable producers serving EU-registered vehicle platforms.
Strategic Opportunities
- Indian PLI scheme alignment:Production-linked incentive frameworks for advanced chemistry cell manufacturing are creating downstream cable demand in Tamil Nadu and Gujarat EV component clusters.
- Silicone insulation convergence:High-temperature polymer technologies are opening thermal cycling performance gaps against conventional XLPE in motor connection applications.
- SAMR safety protocol expansion:China's State Administration for Market Regulation is extending GB/T high-voltage cable standards to commercial vehicle platforms previously exempt from passenger car mandates.
Industry Challenges
- Multi-gigafactory qualification compression:OEM platform consolidation is collapsing supplier validation timelines from 18 months to sub-12 month windows.
- 800V connector integration complexity:Voltage architecture transitions are forcing simultaneous redesign of cable termination systems and insulation thickness specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Unshielded HV Cables Market |
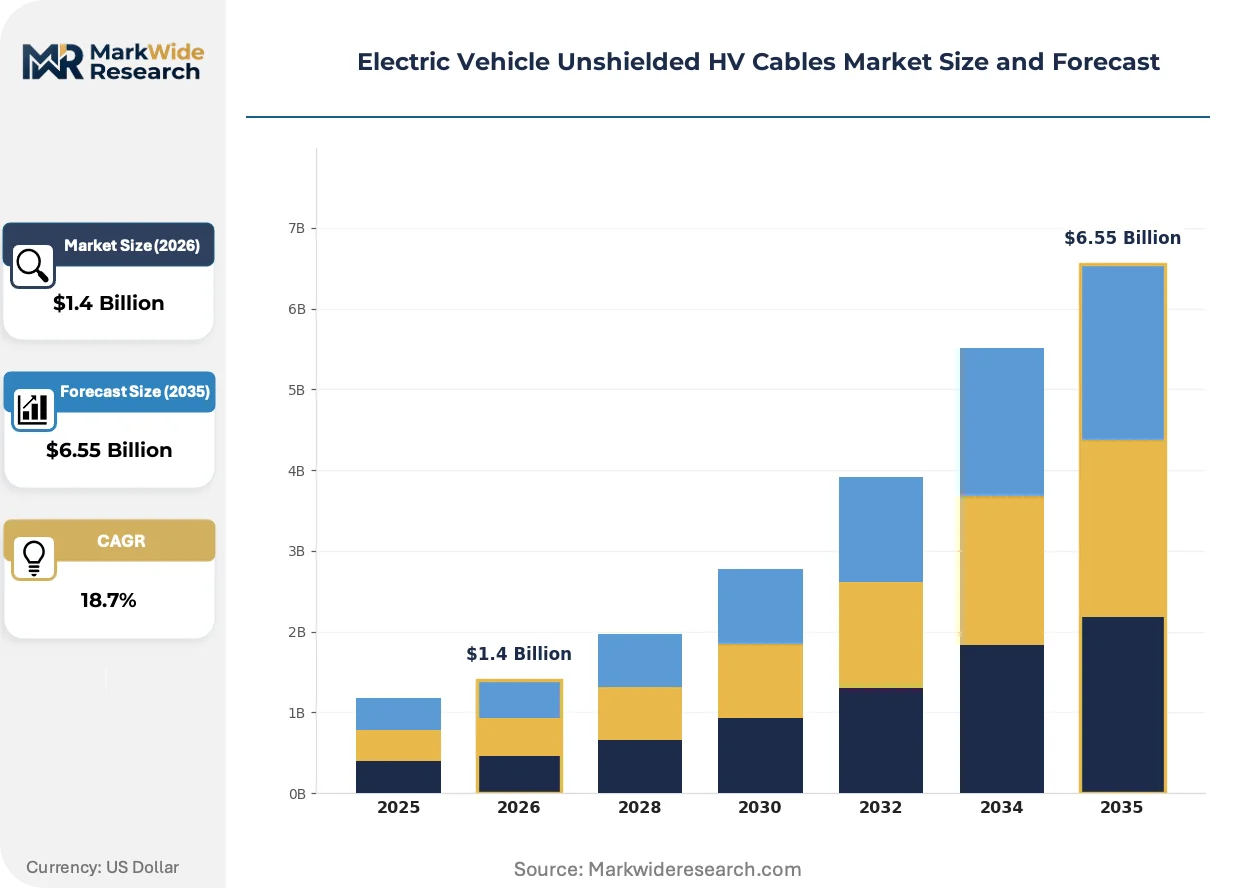
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Charging Cables, Connector Cables, Battery Cables End User: OEMs, Aftermarket Providers, Component Manufacturers, Fleet Operators Installation: Onboard Systems, Charging Stations, Infrastructure, Ancillary Systems Material: Copper, Aluminum, Polymer, Composite |
| Companies Covered | LEONI, Sumitomo Electric, Prysmian Group, ACOME, Coroflex, Champlain Cable, OMG, Tition, JYFT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Unshielded HV Cables Market Trends and Innovations
Active materials substitution and regulatory chemistry restrictions are rewiring competitive advantage in high-voltage cable architecture. Technical differentiation now hinges on thermal performance validation and polymer formulation agility rather than conductor metallurgy alone.
Automated conductor stranding with real-time diameter monitoring is automating quality consistency in aluminum core production. Tier-one suppliers serving German premium OEMs are deploying these systems to meet ISO 6722 dimensional tolerance requirements without manual inspection stations. The technology is automating labor cost structures that previously favored Chinese producers.
REACH Annex XVII restrictions on halogenated flame retardants are compelling insulation compound reformulation across European supply chains. Cable producers serving EU-registered vehicles must validate alternative thermal barrier chemistries without sacrificing GB/T flame resistance equivalence for Chinese export models. Silicone-based alternatives are capturing specification share in motor connection segments where temperature cycling endurance exceeds smoke toxicity concerns.
Fleet procurement centralization is consolidating cable specification authority at OEM platform engineering centers. Component sourcing decisions that previously dispersed to regional manufacturing plants now concentrate at BYD, CATL, and Tesla battery engineering headquarters. This pattern is most visible in China, where tier-one suppliers cluster within 200 kilometers of customer assembly plants to maintain just-in-sequence delivery windows.
Electric Vehicle Unshielded HV Cables Market Segmentation
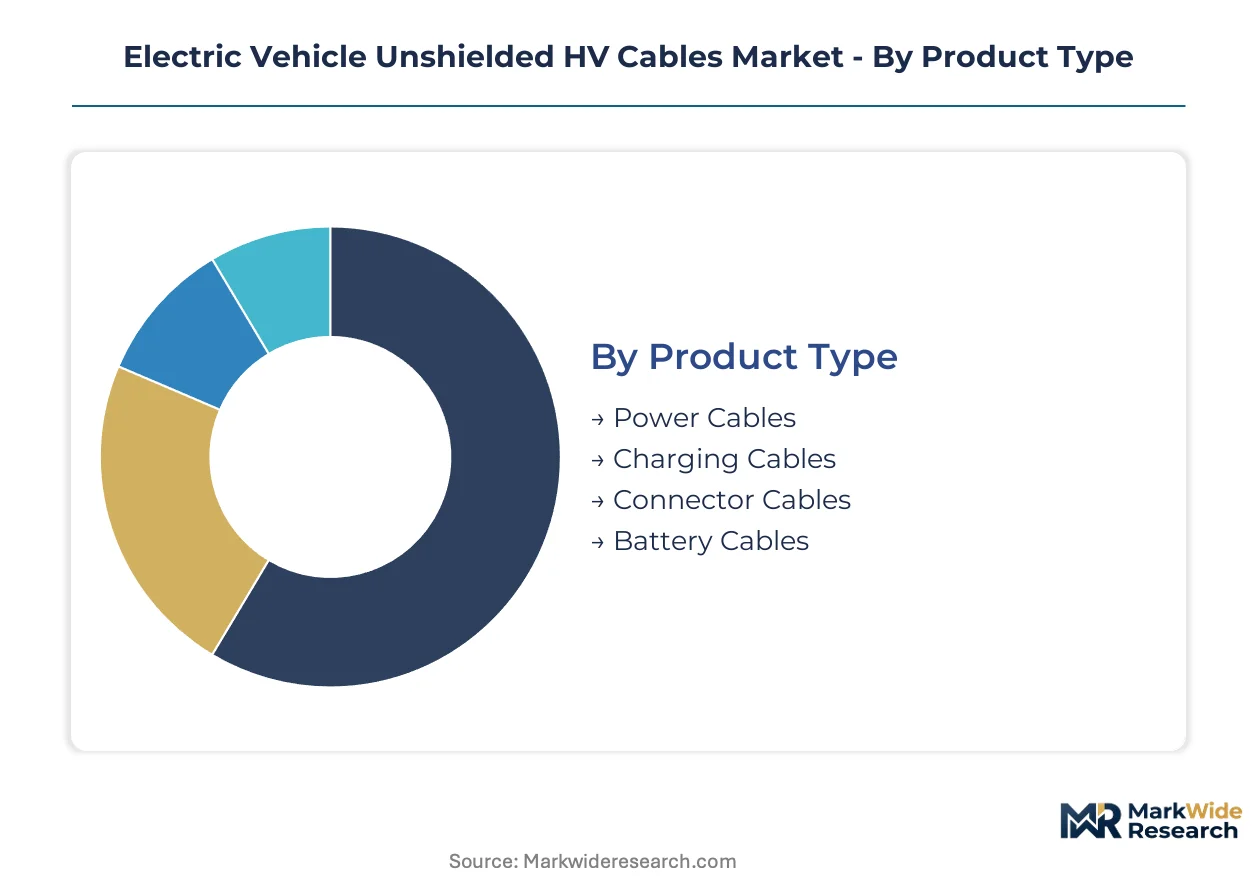
Segmentation in the Electric Vehicle Unshielded HV Cables Market reflects divergent certification burdens across product architectures. GB/T flame resistance mandates from China's SAMR apply differentially to powertrain versus charging applications, while ISO 6722 dimensional tolerances govern premium OEM supply.
Product Type:
Power cables carry GB/T 25085 and ISO 6722 dual certification requirements for passenger vehicle platforms, whereas charging infrastructure cables face additional IEC 62893 standards for DC fast-charging compatibility.
- Power Cables:Stranded copper or aluminum conductors insulated with cross-linked polyethylene or silicone compounds, rated 600V to 1500V DC. Demand concentrates in China's Jiangsu manufacturing corridor where tier-one suppliers cluster near BYD and CATL assembly plants to meet MIIT efficiency mandates for weight reduction.
- Charging Cables:Flexible conductor assemblies designed for 350kW+ ultra-fast charging stations, incorporating liquid-cooled architectures for thermal management. North American highway corridor deployments are multiplying procurement volumes as Electrify America and Tesla Supercharger networks expand.
- Connector Cables:Termination-integrated assemblies linking battery packs to inverters and motors.
- Battery Cables:High-current inter-cell connections within pack architectures subject to SAMR thermal cycling endurance protocols.
Power cables sit at the top of the volume ranking, with charging cables climbing the fastest.
End User:
Cost tier stratification separates qualification-intensive OEM supply from price-sensitive aftermarket channels, with fleet procurement centralization compressing margins for component manufacturers.
- OEMs:Original equipment manufacturers with multi-gigafactory validation requirements and 12-month qualification windows. Battery engineering headquarters at BYD, CATL, and Tesla now centralize specification authority previously dispersed to regional plants.
- Aftermarket Providers:Independent service channels serving vehicle repair networks and retrofit applications.
- Component Manufacturers:Tier-two and tier-three suppliers feeding cable assemblies to integrated system providers.
- Fleet Operators:Commercial vehicle procurement entities driving standardization across depot charging and onboard power distribution.
OEMs command the largest revenue share, while fleet operators are expanding most quickly as commercial electrification accelerates.
Installation:
Application environment dictates insulation thickness, connector sealing ratings, and electromagnetic compatibility tolerance across mobile versus fixed infrastructure deployment.
- Onboard Systems:Powertrain-integrated cabling between battery packs, inverters, and traction motors. 800V architecture migrations in Porsche Taycan and Hyundai E-GMP platforms are forcing simultaneous redesign of termination systems and conductor sizing.
- Charging Stations:Fixed infrastructure cabling for AC and DC charging points subject to local electrical codes and utility interconnection standards.
- Infrastructure:Grid-to-station distribution cabling and substation interconnection.
- Ancillary Systems:HVAC, thermal management, and auxiliary power distribution within vehicle architectures.
Onboard systems generate the highest unit volumes, with charging stations gaining share fastest.
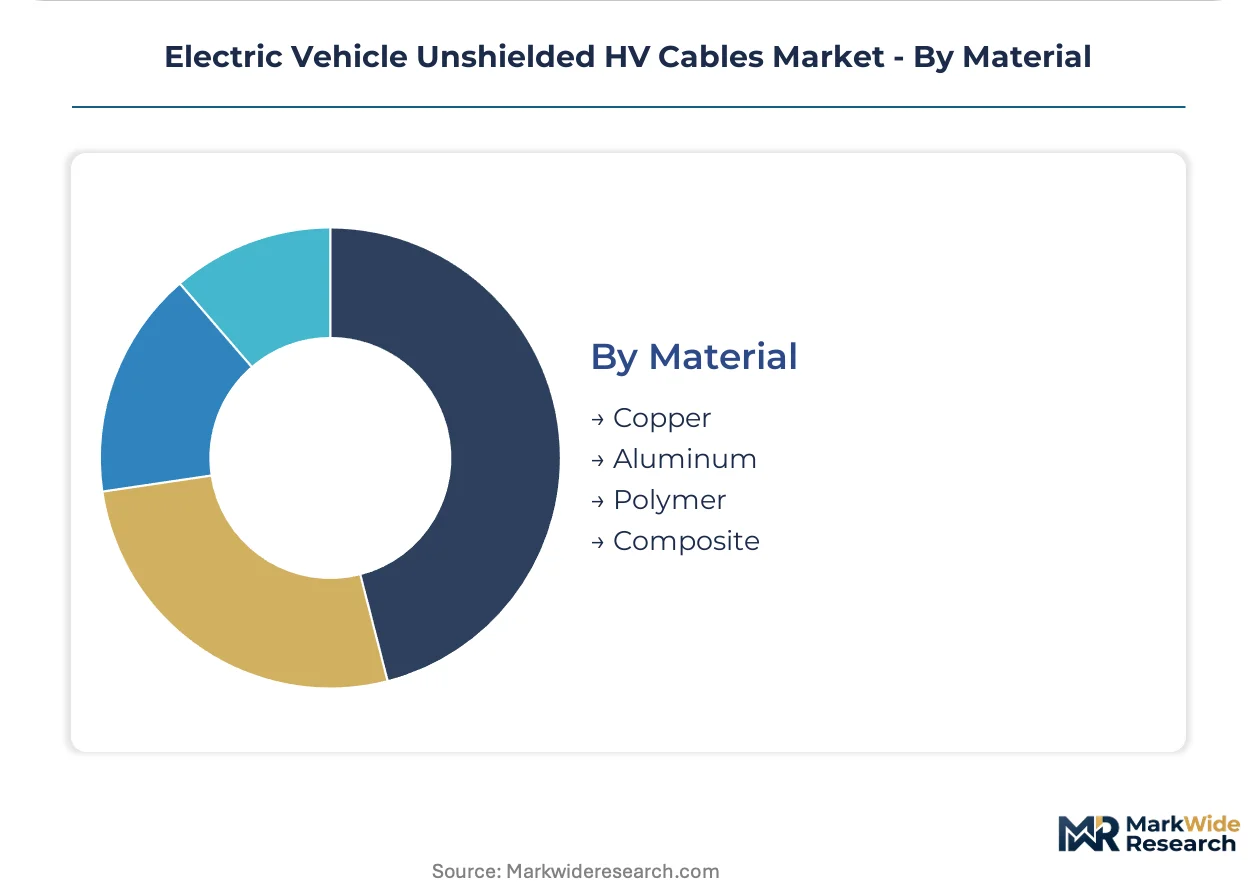
Material:
Margin structure varies sharply by conductor metallurgy and polymer chemistry, with aluminum adoption accelerating fastest among segments as OEMs pursue kilogram reduction targets.
- Copper:High-conductivity stranded conductors commanding premium applications where conductivity tolerance is non-negotiable, particularly in 800V motor connections. LME price volatility compresses margin predictability for producers locked into annual supply agreements.
- Aluminum:Lightweight conductor material penetrating power cable segments under MIIT weight-reduction mandates. China's Jiangsu and Zhejiang corridors are accelerating copper-to-aluminum transitions in battery-electric platforms.
- Polymer:Cross-linked polyethylene and silicone insulation compounds subject to REACH halogenated flame retardant restrictions.
- Composite:Hybrid conductor-insulation systems combining metallurgical and advanced polymer properties.
Copper retains the largest installed base, with aluminum expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's premium OEM engineering centers demand ISO 6722 precision, while China's Jiangsu corridor drives volume through BYD and CATL procurement consolidation.
China
MIIT weight-reduction mandates accelerate aluminum conductor transitions in battery-electric platforms. SAMR's GB/T standards govern flame resistance and thermal cycling endurance for high-voltage cable assemblies. Tier-one suppliers cluster in Jiangsu and Zhejiang manufacturing corridors within 200 kilometers of BYD and CATL assembly plants.
Germany
Premium automakers anchor European demand for ISO 6722 compliant unshielded architectures in 800V powertrain applications. REACH Annex XVII restrictions on halogenated flame retardants force insulation compound reformulation across EU-registered vehicle supply chains. Bavaria-based engineering centers centralize specification authority for multi-gigafactory validation programs.
United States
Ultra-fast charging infrastructure deployments across highway corridors multiply 350kW+ charging cable procurement volumes. NHTSA safety frameworks intersect with state-level electrical codes for fixed infrastructure installations. Michigan and California engineering hubs coordinate OEM platform decisions with Electrify America and Tesla Supercharger network expansion.
Japan
METI industrial policy supports domestic EV platform development with JIS standard alignment for high-voltage components. Copper smelting and polymer compounding operations concentrate competitive advantage among integrated producers. Kanto and Kansai manufacturing belts host motor connection cable specialists serving Toyota and Nissan electrification programs.
India
PLI scheme frameworks for advanced chemistry cell manufacturing create downstream cable demand in Tamil Nadu and Gujarat EV component clusters. BIS certification requirements shape supplier qualification timelines for domestic OEM platforms. Chennai and Ahmedabad industrial corridors attract tier-two cable assembly investments from Chinese and European component makers.
Electric Vehicle Unshielded HV Cables Market Competitive Landscape
European producers anchor one tier; East Asian specialists hold integrated material advantages. The vendor base compresses around multi-gigafactory qualification history, marginalizing regional specialists lacking OEM platform access. Three archetypes dominate: vertically integrated metallurgy-polymer compounders, charging infrastructure scale operators, and premium-tier ISO compliance specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among European cable fabricators, LEONI anchors premium-tier supply relationships with German OEM engineering centers. Sumitomo Electric exemplifies the integrated archetype through captive copper and polymer operations. Prysmian Group occupies a position bridging charging infrastructure scale with automotive powertrain supply, representing the infrastructure-automotive convergence vector.
| Leading Market Players |
|---|
| LEONI |
| Sumitomo Electric |
| Prysmian Group |
| ACOME |
| Coroflex |
| Champlain Cable |
| OMG |
| Tition |
| JYFT |
| Others |
Pricing and Supply Chain Analysis
Automated conductor stranding with real-time diameter monitoring is compressing labor cost differentials between Chinese and European producers while simultaneously reshaping where pricing power accumulates. This production-method transition rewards tier-one suppliers with capital-intensive quality systems and erodes the historical cost advantage of manual-stranding operations in Jiangsu manufacturing corridors.
Pricing Analysis
Capacity additions in China's Zhejiang province are reshaping price floors for aluminum conductor assemblies as MIIT weight-reduction mandates accelerate material substitution. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation hinging on ISO 6722 certification tier and volume scale. Cost compression in standard-grade power cables is intensifying because polymer feedstock concentration in East Asian petrochemical hubs limits supplier negotiating leverage. Aftermarket channels exhibit highest price sensitivity, while German premium OEMs remain least sensitive due to platform engineering centralization.
Supply Chain Analysis
Single-source vulnerability sits with cross-linked polyethylene compounding capacity clustered in South Korea and Japan, creating geographic concentration risk for insulation feedstocks. Raw material dependencies draw from LME copper futures, aluminum billet from Chinese smelters, and silicone polymer from German chemical producers. Tariff exposure on Chinese-origin aluminum conductor imports into North America and Europe threatens margin structures for cable assemblers without regional extrusion partnerships. Distribution runs through just-in-sequence direct delivery from tier-one suppliers to OEM gigafactory gates, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
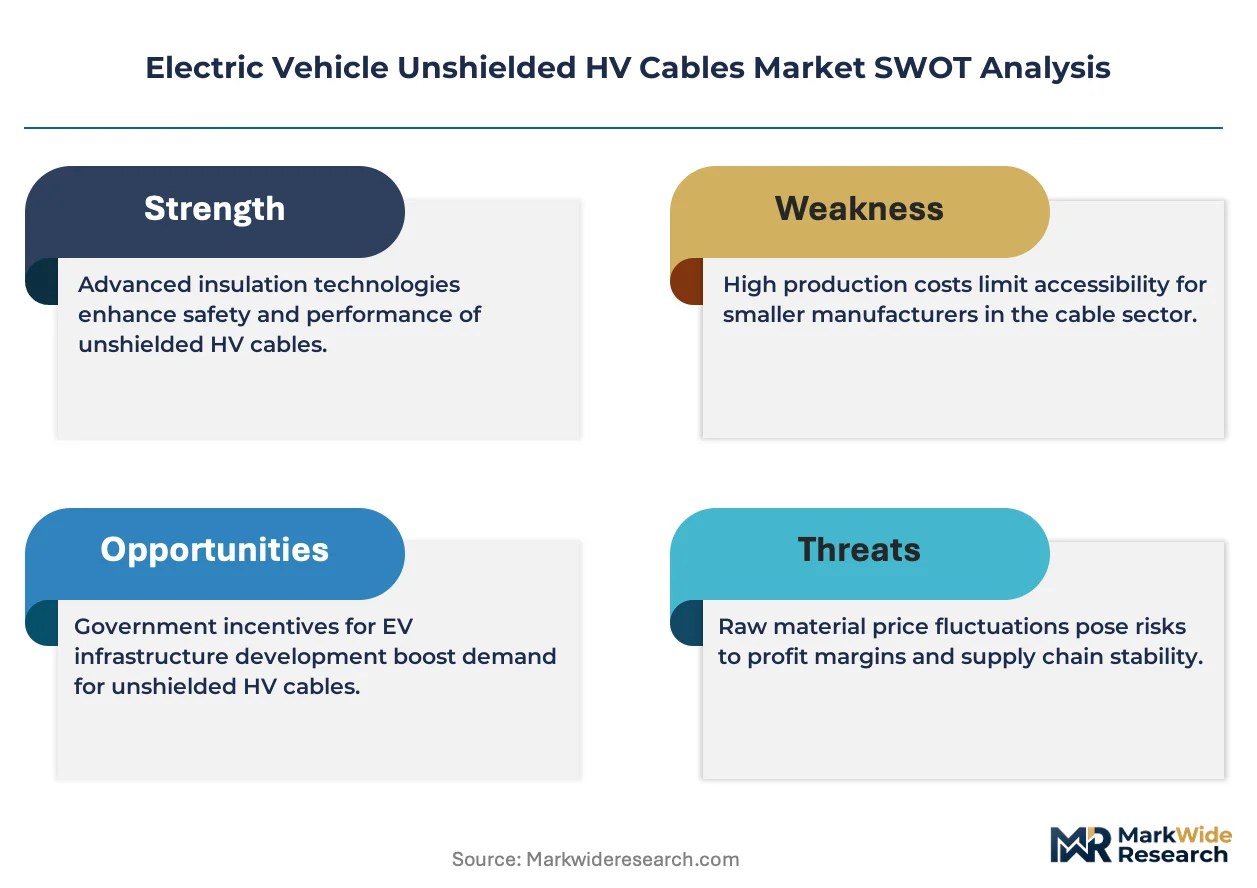
This market reads as a late-cycle quality story where 800V architecture migrations and REACH-compliant silicone insulation specifications concentrate procurement authority with validated incumbents.
For Market Incumbents: Hedge copper price exposure through backward integration into aluminum conductor extrusion or long-term LME hedging instruments. Defend qualification moats by accelerating SAMR GB/T certification for commercial vehicle platforms before regulatory windows compress. Capacity addition in India's Tamil Nadu corridor offers geographic diversification against Jiangsu concentration risk. For New Entrants and Emerging Players: Begin with silicone insulation compound formulation for motor connection segments where thermal cycling performance gaps against XLPE create specification openings. India's Gujarat EV component cluster represents the most penetrable geography given PLI scheme downstream demand and underdeveloped local cable assembly capacity. Pursue BIS certification alignment as the primary go-to-market angle for domestic OEM qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two cable assemblers lacking multi-gigafactory validation history but possessing REACH-compliant polymer formulation capabilities. Long-term viability favors producers with simultaneous automotive powertrain and charging infrastructure scale across the projection horizon. Watch 800V platform adoption curves at Korean and German OEMs as the inflection indicator for conductor sizing and insulation thickness specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | MIIT mandates in China accelerate kilogram-reduction targets across BYD and CATL supply chains. |
| REACH-Compliant Silicone Formulation Investment | ECHA restrictions on halogenated flame retardants force reformulation for EU-registered vehicle platforms. |
| Multi-Gigafactory Qualification Expansion | OEM platform consolidation compresses validation timelines from eighteen months to sub-twelve windows. |
| Indian PLI Scheme Alignment | Advanced chemistry cell manufacturing incentives in Tamil Nadu create downstream cable demand clusters. |
| Ultra-Fast Charging Infrastructure Partnership | Electrify America and Tesla Supercharger networks multiply 350kW+ charging cable procurement volumes. |
Research Methodology
Multiple input streams — primary interviews with OEM platform engineers and tier-one supplier procurement directors, secondary validation through MIIT regulatory filings and SAMR GB/T standard documentation, and customs data on copper and aluminum conductor trade flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed polymer compounding specialists, EV battery pack designers, and charging infrastructure EPC contractors. Secondary sources included IHS Markit vehicle production databases, LME metals pricing archives, and REACH Annex XVII regulatory updates.
Historical shipment volumes were cross-referenced against panel input from cable assemblers and OEM sourcing executives to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, conductor metallurgy, installation environment, and regional production cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating 800V platform penetration assumptions and aluminum substitution coefficients. Industry-specific forecast inputs included MIIT efficiency mandate compliance trajectories and SAMR safety protocol expansion timelines for commercial vehicle segments.
Caveats apply where LME copper volatility, REACH formulation cost escalations, or 800V architecture migration delays could materially shift the outlook. Forecasts reflect documented assumptions about OEM platform consolidation velocity and polymer feedstock supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Submarine Cabling Systems Market
Cables
Global Industrial Automation Cable Market
Cables
Cable Material Market
Cables
SATA Power Cable Market
Cables
Cable Market
Cables
Cable Racks Market
Cables
Magnetic Charging Cable Market
Cables
Shipboard Cable Market
Cables
LED Cable Market
Cables
Low-Temperature Cable Market
Cables
Radio Frequency Cables Market
Cables
Fire Resistance Cable Market
Cables
EDM Wires Market
Cables
FFC/FPC Jumper Cables Market
Cables
Cable Testers Market
Cables
US Cables Market