
 Wire and Cable Label Market | 2026-2036
Wire and Cable Label Market Size, Share, and Industry Trends Forecast 2026-2036
Wire and Cable Label Market Analytics
Aftermarket service revenue for label printing systems and ribbon resupply is reshaping profit pools across the wire and cable label value chain. Brady leverages its specialized identification portfolio to sustain premium positioning in industrial safety channels. Panduit anchors its competitive stance through deep channel control in structured cabling infrastructure. TE Connectivity differentiates via upstream integration into connector and label bundling for automotive harness applications.
Wire and cable labels are pressure-sensitive or heat-shrink identification substrates, typically composed of polyester, vinyl, or resin-impregnated materials, manufactured through thermal transfer, laser engraving, or inkjet processes to deliver permanent traceability in electrical and data infrastructure. Polyester labels dominate industrial applications where abrasion resistance and solvent exposure are critical, while vinyl labels occupy cost-sensitive contractor segments with moderate durability requirements. Resin labels represent the fastest-growing category as data center operators specify high-tack, heat-resistant adhesives for dense fiber routing environments.
UL standards, IEC 60601 electrical safety frameworks, and OSHA workplace identification requirements collectively mandate legibility, adhesion durability, and flame-retardant properties that filter non-compliant suppliers from specification lists. The EU RoHS directive and REACH chemical restrictions further constrain substrate formulations, pushing manufacturers toward halogen-free adhesive systems. Stakeholders must monitor evolving building electrification codes and renewable interconnection standards that will redefine label performance thresholds before the next infrastructure investment cycle matures.
Market Dynamics
Utility grid modernization and data center fiber density requirements are compressing specification cycles for heat-resistant identification substrates, forcing substrate manufacturers to recertify adhesive formulations against evolving flame-retardant standards before procurement windows close.
Growth Catalysts
- IEC 60601 electrical safety frameworks:Medical device manufacturers in Germany and Japan now mandate solvent-resistant polyester labels for equipment traceability, pulling premium substrate volumes into healthcare infrastructure.
- Data center fiber routing density:Hyperscale operators specify resin-impregnated labels with high-tack adhesives for 400G cable management, creating specification pull for heat-resistant identification systems.
- OSHA workplace identification requirements:Industrial facilities across the United States face compliance deadlines for arc-flash and lockout-tagout labeling, sustaining replacement demand for thermal transfer ribbons and vinyl substrates.
Market Restraints
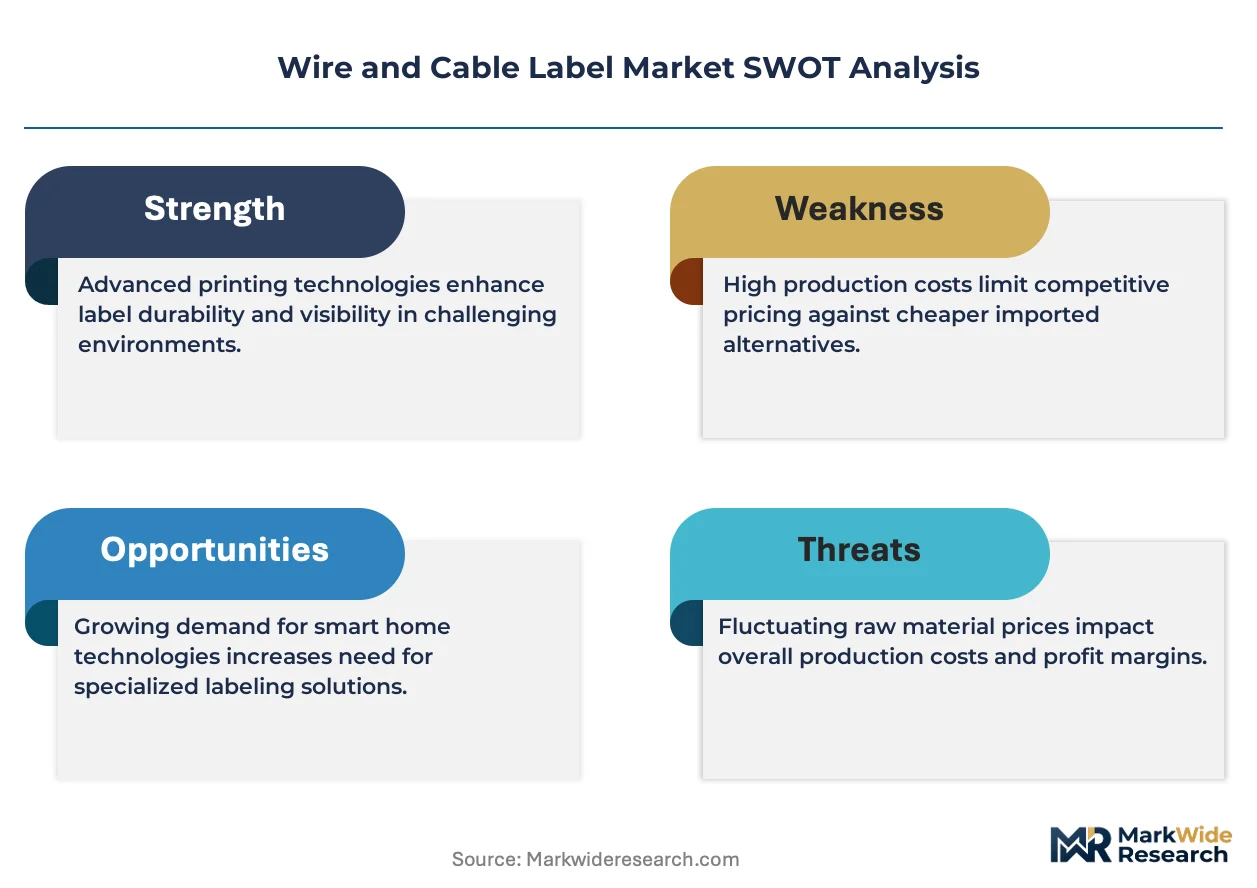
- Petrochemical input volatility:Polyester and vinyl substrate costs fluctuate with crude oil derivatives, compressing margins for manufacturers without backward integration into resin production.
- REACH chemical restrictions:ECHA halogen-free mandates eliminate legacy adhesive chemistries from EU specification lists, forcing costly reformulation cycles for exporters serving European utility channels.
- Laser engraving substitution:Permanent direct-part marking on metal cable trays reduces label attach rates in heavy industrial settings where mechanical abrasion exceeds adhesive durability.
Strategic Opportunities
- India building electrification:BIS certification requirements for commercial wiring create first-mover advantage for substrate suppliers establishing local thermal transfer ribbon production.
- EU Green Deal procurement incentives:Public infrastructure tenders now weight recycled-content substrates, opening specification windows for halogen-free polyester alternatives with post-consumer resin content.
- RFID-wireless hybrid convergence:Passive RFID inlays laminated to pressure-sensitive cable labels enable automated asset tracking in smart grid deployments without separate tag attachment.
Industry Challenges
- UL 969 adhesive certification timelines:Thermal transfer ribbon suppliers face 12-18 month validation cycles for new substrate-adhesive combinations, delaying specification entry for fast-evolving data center connector formats.
- Legacy print system integration:Industrial facilities with installed thermal transfer printer fleets resist migration to laser-compatible substrates, fragmenting procurement across incompatible ribbon formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire and Cable Label Market |
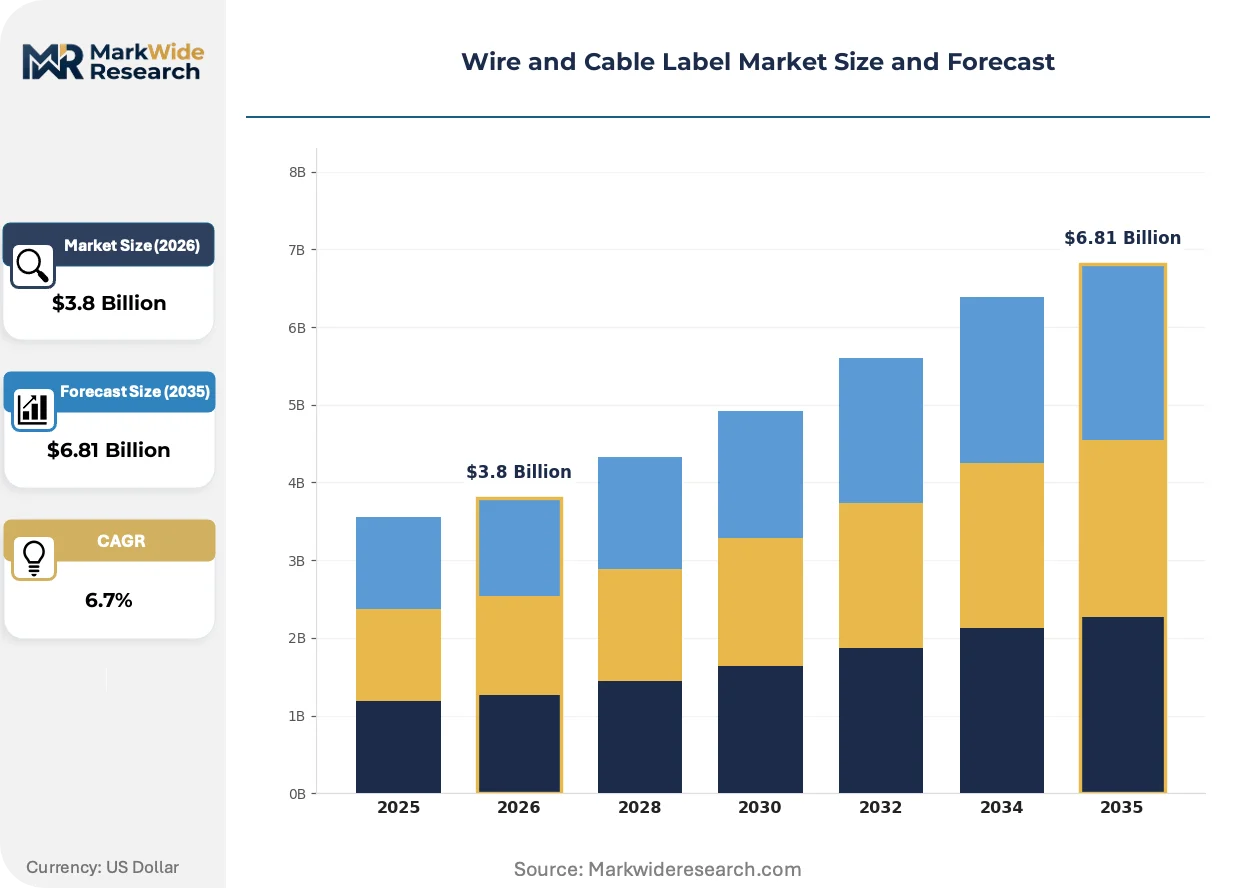
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Resin Labels, Vinyl Labels, Polyester Labels, Paper Labels Application: Electrical Wiring, Telecommunications, Automotive, Industrial Equipment End User: Manufacturers, Contractors, Distributors, Utility Companies Adhesive Type: Permanent Adhesive, Removable Adhesive, Heat-Resistant Adhesive, Waterproof Adhesive |
| Companies Covered | Phoenix Contact, HellermannTyton, TE Connectivity, Seton, Brother, Panduit, Brady, Ziptape, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire and Cable Label Market Evolving Landscape
Identification substrate technology is bifurcating between permanent heat-shrink sleeves for utility infrastructure and removable pressure-sensitive formats for data center reconfiguration cycles, with adhesive chemistry becoming the primary differentiation vector.
Laser-markable polyimide substrates is hybridizing thermal durability with direct-write flexibility, eliminating ribbon inventory for utility field crews. European grid operators in Germany and France now specify these materials for substation cable marshalling panels. The technology is compressing aftermarket ribbon revenue pools while expanding equipment attachment rates for laser system OEMs.
REACH Annex XVII restrictions on organotin catalysts in polyurethane adhesives are eliminating legacy formulations from EU-bound production lines. Substrate laminators must validate alternative cross-linking chemistries without sacrificing 150°C heat resistance. German automotive harness suppliers face the tightest compliance windows, with TE Connectivity and Leoni accelerating halogen-free adhesive qualification programs.
Specification consolidation around dual-certified substrates is concentrating procurement authority at engineering-consultant firms serving data center and utility verticals. Contractors now purchase pre-approved label kits rather than specifying raw materials independently. This shift is most visible in United States hyperscale construction, where Bechtel and DPR Engineering mandate Brady or Panduit bundled identification systems to accelerate commissioning timelines and reduce field substitution errors.
Wire and Cable Label Market Segmentation
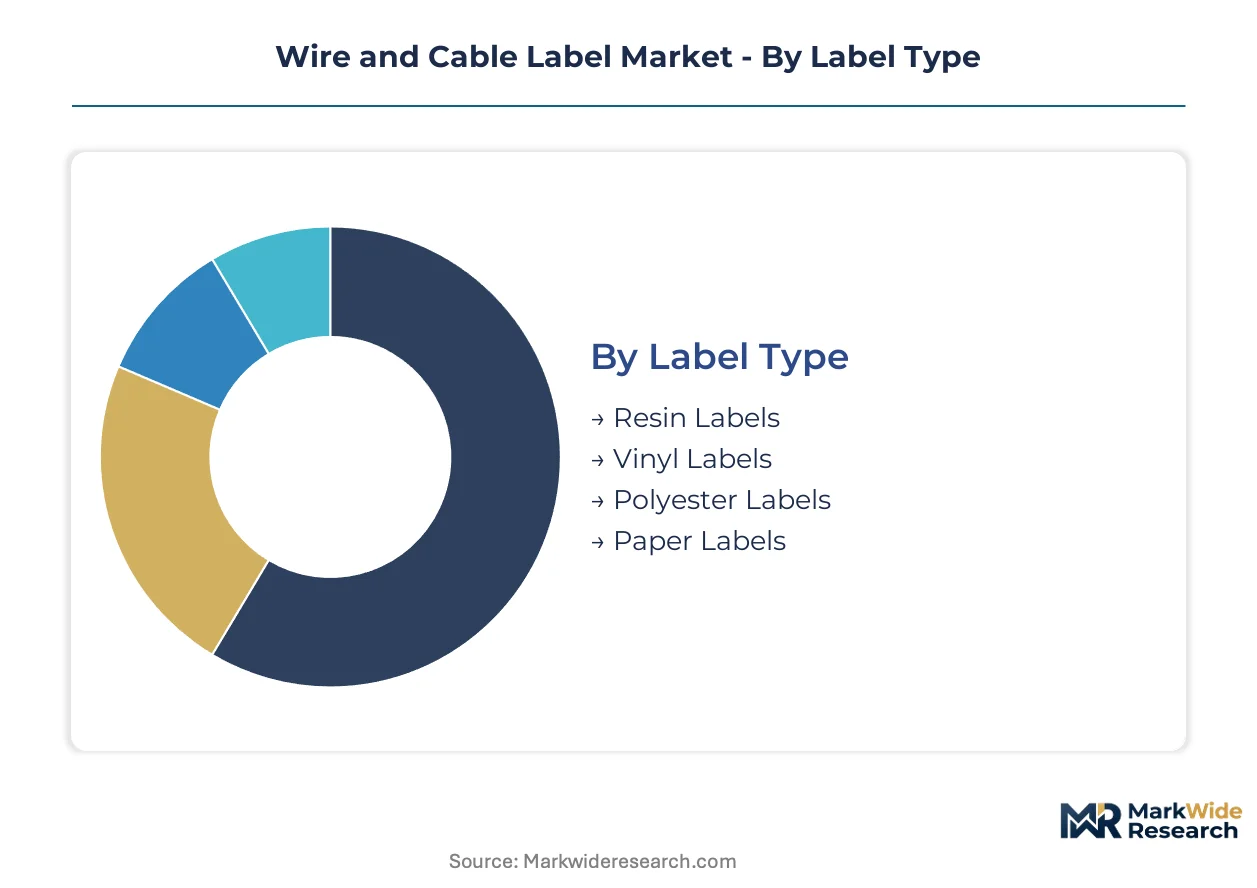
Wire and cable label procurement splits sharply between permanent infrastructure installations and reconfigurable data center environments. Specification authority concentrates at engineering-consultant firms bundling substrate-adhesive combinations into pre-approved kits for contractor channels.
Label Type:
Material chemistry determines thermal ceiling, solvent resistance, and compliance eligibility across electrical safety frameworks.
- Resin Labels:Impregnated synthetic substrates bond high-tack adhesives to fiber optic jackets in hyperscale data centers. Demand concentrates in United States cloud infrastructure where 400G cable density mandates heat-resistant identification for traceability during reconfiguration cycles.
- Polyester Labels:Abrasion-resistant film constructions withstand solvent exposure in industrial maintenance environments. German automotive harness suppliers specify these for IEC 60601 medical equipment traceability, pulling premium volumes into healthcare manufacturing.
- Vinyl Labels:Cost-optimized calendered films serve contractor segments with moderate durability requirements and tighter margin structures.
- Paper Labels:Uncoated stock for temporary indoor identification in controlled commercial wiring installations where moisture exposure is minimal.
The dominant share belongs to Polyester Labels, while Resin Labels are closing the gap fastest.
Application:
End-use verticals impose distinct certification burdens and replacement cadences on identification substrate procurement.
- Electrical Wiring:Flame-retardant labels for building electrification and grid modernization carry UL 969 adhesive certification requirements. United States utility infrastructure investment drives specification volume for heat-shrink and pressure-sensitive formats in substation marshalling panels.
- Telecommunications:Fiber optic cable management in hyperscale data centers demands resin-impregnated labels with repositionable adhesives for dense 400G routing environments.
- Automotive:Halogen-free adhesive systems for harness bundling face REACH Annex XVII compliance windows in European production lines.
- Industrial Equipment:Arc-flash and lockout-tagout labeling sustains replacement demand for thermal transfer ribbons and vinyl substrates under OSHA workplace identification mandates.
Electrical Wiring commands the largest procurement volume, though Telecommunications is expanding most quickly.
End User:
Procurement authority fragments across specification, installation, and resale channels with divergent technical fluency.
- Utility Companies:North American and European grid operators procure heat-resistant identification systems directly for modernization projects, consolidating purchasing at engineering-consultant firms.
- Contractors:Installation crews purchase pre-approved label kits from Panduit and Brady bundles rather than specifying raw materials independently, reducing field substitution errors in United States hyperscale construction.
- Manufacturers:Automotive and medical device OEMs mandate solvent-resistant polyester labels for equipment traceability, pulling substrate volumes into factory-floor integration.
- Distributors:Channel intermediaries stock thermal transfer ribbons and vinyl substrates for aftermarket service revenue in industrial facilities with installed printer fleets.
Utility Companies hold the dominant procurement position, while Contractors are gaining specification influence fastest.
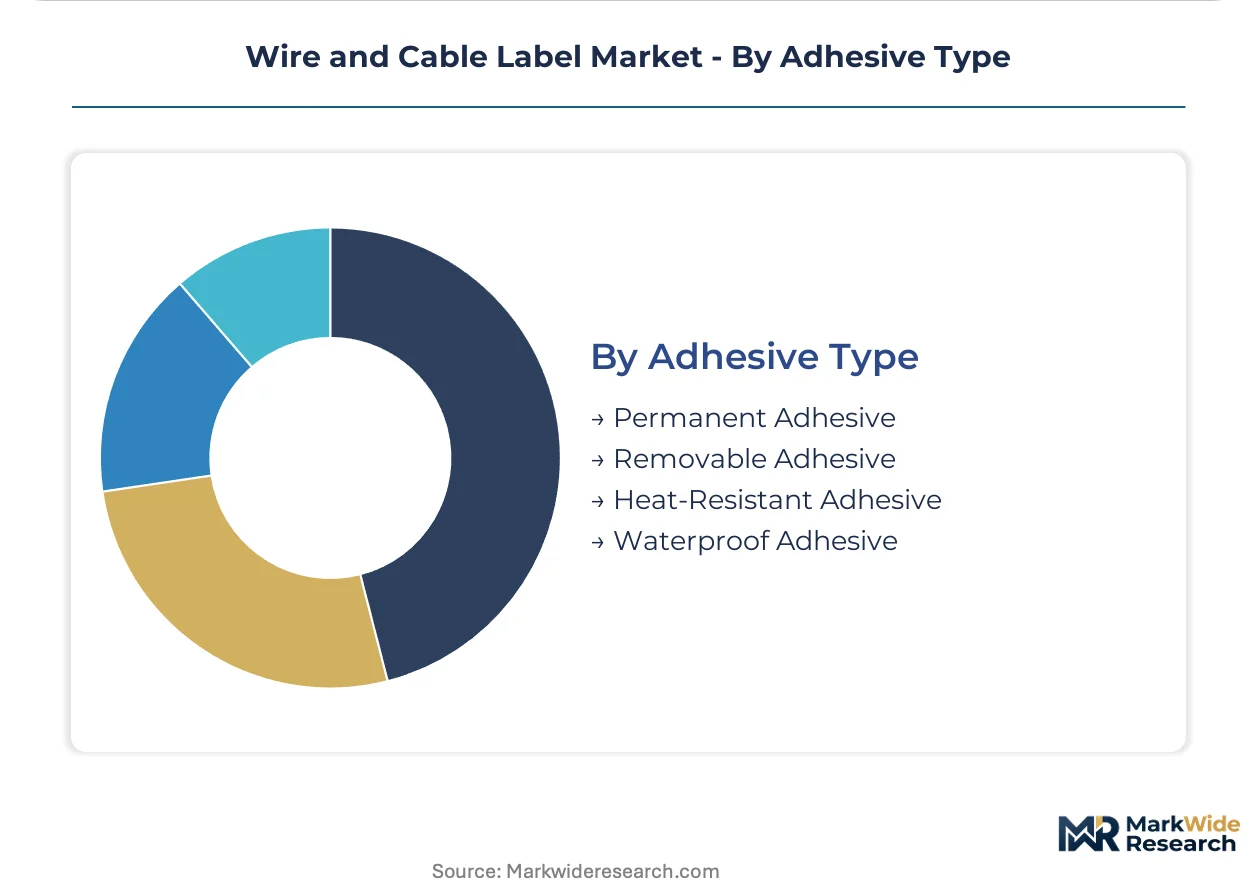
Adhesive Type:
Bond chemistry determines temperature tolerance, removability, and regulatory compliance eligibility across substrate laminations.
- Heat-Resistant Adhesive:Cross-linked polyurethane formulations maintain adhesion above 150°C in utility substation environments. German automotive harness suppliers accelerate halogen-free qualification programs under REACH Annex XVII organotin catalyst restrictions.
- Permanent Adhesive:High-shear acrylic systems dominate infrastructure installations where label detachment risks safety compliance or asset traceability.
- Removable Adhesive:Repositionable formulations serve data center reconfiguration cycles where cable moves require clean removal without residue.
- Waterproof Adhesive:Moisture-cure systems for outdoor electrical enclosures and submarine cable marshalling in coastal grid infrastructure.
Permanent Adhesive retains the largest installed base, yet Heat-Resistant Adhesive is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractors in India and Southeast Asia exhibit acute price sensitivity to vinyl substrate costs, while German automotive harness suppliers and United States hyperscale data center operators absorb premium pricing for certified halogen-free and heat-resistant adhesive systems without volume elasticity.
United States
Utility infrastructure investment and data center construction drive procurement volume for copper and fiber optic cable management systems. OSHA workplace identification requirements sustain replacement demand for thermal transfer ribbons across industrial facilities. Engineering-consultant firms in Northern Virginia and Dallas-Fort Worth consolidate specification authority for bundled identification systems.
Germany
Automotive harness suppliers accelerate halogen-free adhesive qualification programs under REACH Annex XVII organotin catalyst restrictions. IEC 60601 electrical safety frameworks mandate solvent-resistant polyester labels for medical equipment traceability. Industrial clusters in Baden-Württemberg and Bavaria concentrate substrate laminator capacity for European automotive OEM supply chains.
China
MIIT building electrification standards expand domestic demand for flame-retardant identification substrates in commercial wiring installations. GB standards for electrical safety equipment filter non-compliant suppliers from state-owned utility procurement lists. Manufacturing concentration in the Yangtze River Delta supplies both domestic grid modernization and export-oriented automotive harness production.
India
BIS certification requirements for commercial wiring create first-mover advantage for substrate suppliers establishing local thermal transfer ribbon production. CEA grid interconnection standards mandate permanent cable traceability for renewable energy projects. Industrial corridors in Gujarat and Maharashtra attract adhesive formulation investments serving South Asian building electrification.
Japan
METI industrial safety codes and JIS standards enforce flame-retardant material mandates for electrical infrastructure identification. Medical device manufacturers specify premium polyester substrates for equipment traceability in healthcare manufacturing. Precision manufacturing clusters in Aichi Prefecture supply heat-shrink sleeve systems for automotive and industrial export markets.
Wire and Cable Label Market Competitive Landscape
Capability concentration sits with specialized identification substrate laminators; scale advantage sits with diversified electrical component conglomerates. The vendor base organizes into three strategic archetypes: premium-tier specialists commanding engineering-consultant specification authority, mid-scale regional fabricators serving contractor distribution channels, and diversified industrial conglomerates bundling labels with connector systems. Competitive moves center on adhesive formulation recertification against evolving flame-retardant standards and backward integration into halogen-free resin production.
Among diversified electrical component manufacturers, TE Connectivity exemplifies the bundling archetype through upstream control over connector and label combinations for automotive harness applications. Brady and Panduit occupy positions within the premium-tier specialist segment, with the former sustaining industrial safety channel positioning and the latter anchoring structured cabling infrastructure through deep distribution control. These three companies represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Phoenix Contact |
| HellermannTyton |
| TE Connectivity |
| Seton |
| Brother |
| Panduit |
| Brady |
| Ziptape |
| 3M |
| Others |
Value Network & Pricing Analysis
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across wire and cable label manufacturing, compressing margins for polyester and vinyl substrate producers without captive resin production while amplifying premium capture for halogen-free adhesive specialists serving German automotive and United States data center channels.
Pricing Analysis
Aftermarket service revenue from thermal transfer ribbon resupply and print system maintenance drives lifetime value across the value chain. Pricing stratifies across premium, standard, and economy tiers based on UL 969 certification grade and volume scale. Cost compression in vinyl substrates is intensifying because crude oil derivative fluctuations squeeze contract margins. Contractors in India and Southeast Asia exhibit acute price sensitivity, while German automotive harness suppliers absorb premium pricing for REACH-compliant halogen-free systems without volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration for adhesive formulation and substrate lamination rests with specialized EMS providers in China, Germany, and the United States. Raw material dependencies draw from petrochemical feedstocks for polyester and vinyl films, halogen-free resin systems for EU-bound production, and thermal transfer ribbon coatings. Single-source vulnerability concentrates in organotin catalyst supply for legacy polyurethane adhesives facing REACH Annex XVII elimination. Distribution runs through engineering-consultant firms bundling pre-approved label kits for contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wire and cable label demand sits at an early-cycle expansion story justified by building electrification mandates across India and Southeast Asia creating specification windows before local supply capacity matures.
For Market Incumbents: Pre-empt laser engraving substitution in heavy industrial settings by accelerating polyimide substrate qualification for direct-part marking compatibility. Secure backward integration into halogen-free resin production to defend margin position against REACH-driven reformulation cycles. Anchor channel control through bundled identification systems that reduce field substitution errors in United States hyperscale construction.
For New Entrants and Emerging Players: Build out local thermal transfer ribbon production in Gujarat and Maharashtra to capture BIS certification first-mover advantage in India's building electrification wave. Target India's commercial wiring segment through adhesive formulation partnerships serving CEA grid interconnection standards. Pursue RFID-wireless hybrid convergence as a go-to-market angle for smart grid deployments.
For Investors and Strategic Acquirers: The market sits at a specification-consolidation phase that favors adhesive formulation specialists with UL 969 certification pipelines. Long-term viability hinges on halogen-free chemistry transitions and data center fiber density tailwinds. Monitor UL validation timelines for new substrate-adhesive combinations as an inflection indicator for specification entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Adhesive Qualification | REACH Annex XVII compliance opens EU automotive harness procurement to qualified laminators. |
| RFID-Wireless Hybrid Development | Passive inlay integration enables automated asset tracking in FERC-regulated smart grid deployments. |
| Local Ribbon Production Buildout | BIS certification proximity captures share in India's CEA-mandated renewable interconnection projects. |
| Polyimide Laser-Markable Substrate Launch | Eliminates ribbon inventory for German and French utility field crews while expanding equipment attachment. |
| Engineering-Consultant Partnership | Bechtel and DPR bundling mandates concentrate procurement authority at pre-approved kit suppliers. |
Research Methodology
Desk research of customs trade data, SEC filings from diversified electrical component manufacturers, and UL certification databases preceded structured interviews with substrate laminator technical directors, thermal transfer printer OEM product managers, and engineering-consultant specification engineers. Primary fieldwork with utility procurement officers and automotive harness supplier quality leads combined with secondary validation from ECHA regulatory filings and OSHA compliance documentation. Bottom-up volume modeling across adhesive type and label chemistry segments triangulated against top-down infrastructure investment forecasts.
Assumptions held fixed include REACH Annex XVII enforcement timelines and UL 969 certification cycle durations, while variables included petrochemical input cost trajectories and data center fiber density adoption curves. The analytical framework modeled label type, application vertical, end-user procurement channel, and adhesive chemistry across the analysis window. CAGRs derived from segment-level volume buildups incorporating utility grid modernization spend and hyperscale construction pipelines.
Stress conditions across crude oil derivative volatility bands and EU regulatory acceleration scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to ECHA halogen-free mandate timing and data center connector format evolution. Quarterly review of UL validation pipeline status and utility infrastructure appropriation cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optic Cable Accessories Market
Cables
High Voltage Cables Market
Cables
Shipboard Cable Market
Cables
Cable Tags Market
Cables
Military Cable Market
Cables
USB Cable Market
Cables
Cable Lugs Market
Cables
Global Cable Gland Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Radio Frequency Cables Market
Cables
Asia-Pacific Cable Joints Market
Cables
Cable Tray Market
Cables
Europe Wire and Cable Market
Cables
SATA Power Cable Market
Cables
Cable Testing Market
Cables
Cable Management System Market