
 Nuclear Multi-Conductor Cables Market | 2026-2036
Nuclear Multi-Conductor Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Multi-Conductor Cables Market Insights
Project finance structures with long-term power purchase agreements is reshaping how cable suppliers participate in nuclear new-build programs. Nexans leverages its vertical integration from copper rod to finished cable to sustain qualification margins. Prysmian Group anchors European reactor maintenance cycles with specialized low-smoke halogen-free portfolios. RSCC Wire & Cable competes on domestic content requirements for US Department of Energy projects.
Nuclear multi-conductor cables are engineered assemblies containing multiple insulated conductors within a common jacket, rated for radiation resistance up to 200 Mrad and temperatures exceeding 90°C continuous operation, designed to maintain circuit integrity during design-basis accident conditions including loss-of-coolant scenarios. Shielded cable configurations dominate safety-related applications where electromagnetic interference mitigation protects reactor protection system signals. Instrumentation cables represent the fastest-growing application segment as digital instrumentation and control upgrades replace analog systems across aging reactor fleets. Copper conductor material maintains its position in safety-class installations where thermal conductivity and termination reliability outweigh aluminum's weight advantages.
The US Nuclear Regulatory Commission enforces 10 CFR 50 Appendix B quality assurance and IEEE 1202 flame-test compliance for safety-related cable installations, while the International Atomic Energy Agency's safety standards shape national adoption frameworks across emerging nuclear programs. European regulators under the Euratom Treaty mandate environmental qualification aging simulations that extend cable qualification timelines and raise barrier-to-entry thresholds. Stakeholders must monitor divergence between national nuclear regulatory frameworks and harmonized IEC standards as reactor export projects multiply across jurisdictions with varying technical acceptance criteria.
Market Dynamics
Digital instrumentation and control upgrades across aging reactor fleets are compressing procurement cycles and forcing cable suppliers to requalify products for signal integrity requirements that analog systems never demanded.
Growth Catalysts
- Seismic qualification mandates:IEC 60780 protocols are expanding cable testing requirements for new reactor builds in coastal zones prone to tectonic activity.
- China's coastal nuclear expansion:Provincial utilities in Fujian and Zhejiang are accelerating tendering for qualified cable assemblies to meet reactor commissioning schedules.
- Radiation-resistant polymer compounds:Advanced ethylene-tetrafluoroethylene formulations are extending cable service life in high-radiation containment environments.
Market Restraints
- Copper price volatility:Conductor material costs fluctuate with London Metal Exchange pricing, squeezing qualification margins on long-delivery nuclear contracts.
- European qualification timeline compression:Euratom Treaty environmental aging simulations extend type-approval cycles by 18-24 months versus prior certification frameworks.
- Cross-linked polyethylene substitution:Non-safety-grade applications increasingly specify XLPE-insulated cables that bypass nuclear-grade qualification costs.
Strategic Opportunities
- India's Kudankulam corridor:Russian-designed VVER reactor expansions are creating demand for cable suppliers with dual IEC and Russian GOST certification capability.
- Small modular reactor deployment:Factory-fabricated SMR designs favor pre-tested cable harnesses over field-terminated installations.
- 10 CFR 50 Appendix B harmonization:US quality assurance standards are becoming reference frameworks for emerging nuclear programs in the Middle East and Southeast Asia.
Industry Challenges
- Radiation qualification engineering scarcity:Specialized expertise in 200 Mrad accelerated aging test protocols remains concentrated among a handful of laboratory facilities.
- Legacy analog system integration:Digital I&C cable retrofits must maintain electromagnetic compatibility with existing reactor protection system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Multi-Conductor Cables Market |
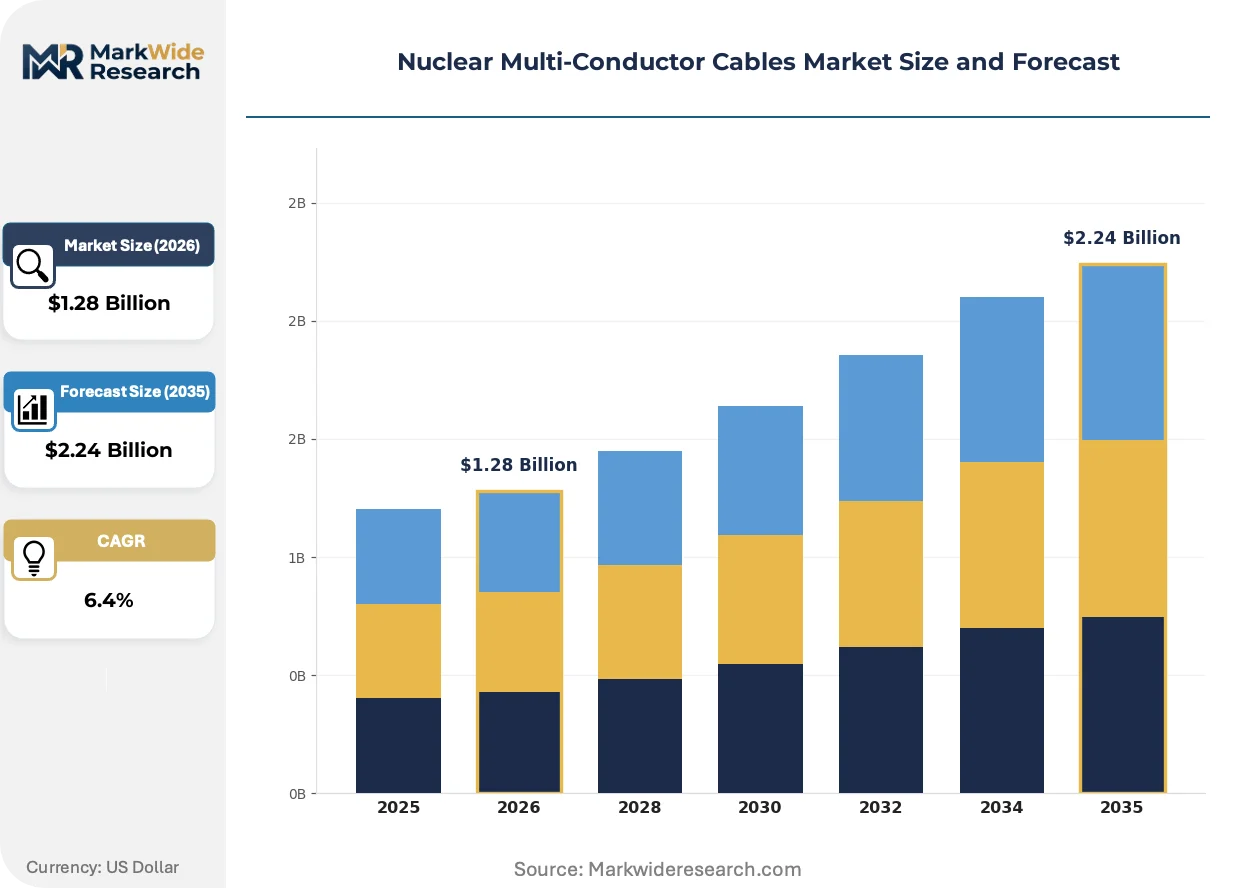
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shielded Cables, Unshielded Cables, Flexible Cables, Specialty Cables Material: Copper, Aluminum, Polyethylene, PVC Application: Power Distribution, Control Systems, Instrumentation, Communication End User: Nuclear Plants, Research Facilities, Utilities, Industrial Plants |
| Companies Covered | Nexans, Prysmian Group, General Cable, RSCC Wire & Cable, Habia Cable, Southwire Company, Kabelwerk Eupen, Anhui Cable, TMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Multi-Conductor Cables Market Trends and Innovations
Signal transmission integrity under accident conditions is becoming the decisive technical battleground as reactor operators replace obsolete analog instrumentation with digital platforms.
Silicon carbide fiber-optic sensing cables are digitizing reactor monitoring architectures by transmitting temperature and neutron flux data without electromagnetic interference susceptibility. Korean and Chinese utilities are piloting these systems in containment penetration applications. The technology is digitizing how safety-related sensor networks are architected, collapsing separate power and signal cable runs into unified fiber assemblies.
REACH substance restrictions on halogenated flame retardants are forcing reformulation of low-smoke cable jackets across European nuclear maintenance programs. Compound suppliers are accelerating phosphorous-nitrogen intumescent systems to replace legacy antimony trioxide formulations. French and Finnish reactor operators are requiring full material disclosure documentation that extends supply chain audit depth three tiers upstream.
Long-term power purchase agreements are compressing cable procurement into multi-reactor framework contracts that bundle initial installation with 40-year replacement part commitments. EPC contractors are consolidating vendor panels to three qualified sources per cable category. This concentration is most visible in China's state-backed nuclear builds where procurement centralization under CNNC and CGN procurement platforms limits supplier access windows.
Nuclear Multi-Conductor Cables Market Segmentation
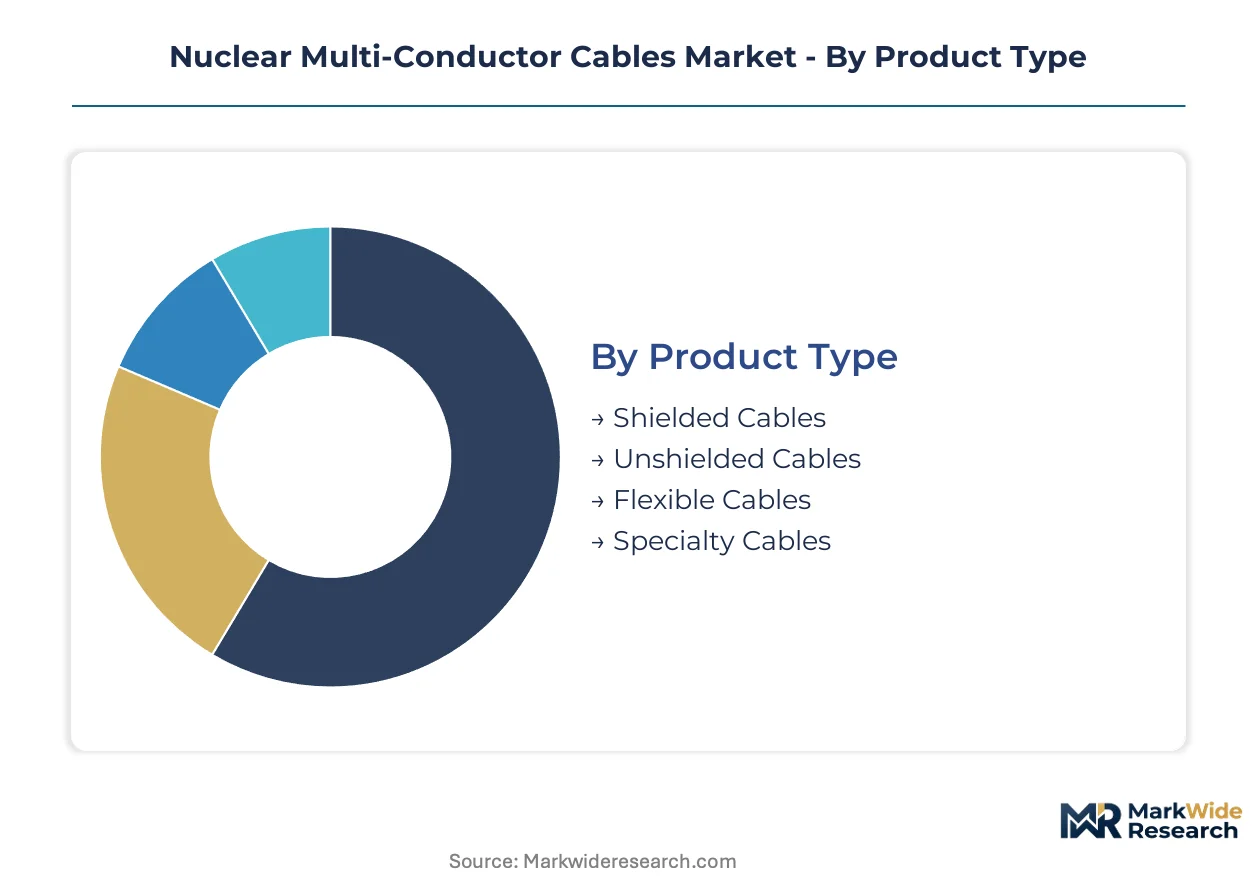
Cable specification tiers determine qualification pathways and margin structures across nuclear installations. Each segmentation dimension carries distinct regulatory weight and procurement logic.
Product Type:
Electromagnetic shielding requirements differentiate safety-class cable architectures and testing protocols.
- Shielded Cables:Metallic braid or tape shielding attenuates electromagnetic interference across reactor protection system signal paths. Demand concentrates in digital instrumentation retrofits where signal integrity requirements exceed analog-era specifications. IEC 60780 seismic qualification mandates are tightening procurement standards for coastal reactor builds in China and India.
- Flexible Cables:Stranded conductor construction with elastomeric insulation permits routing through containment penetration areas with space constraints. Korean and Chinese utilities specify these for maintenance access zones where rigid conduit installation proves impractical. Factory-fabricated cable harnesses for small modular reactor designs favor pre-tested flexible assemblies over field-terminated alternatives.
- Unshielded Cables:Non-shielded multi-conductor configurations serve non-safety power distribution circuits where electromagnetic compatibility requirements permit simpler construction.
- Specialty Cables:Hybrid fiber-optic power assemblies and silicon carbide sensing cables address emerging containment monitoring architectures.
Shielded configurations command the established base. The steepest expansion runs through flexible cable formats.
Material:
Conductor and insulation material selections trade thermal performance against weight, cost, and qualification burden.
- Copper:High thermal conductivity and termination reliability sustain dominance in safety-class installations. US Nuclear Regulatory Commission 10 CFR 50 Appendix B quality assurance frameworks reference copper conductor specifications as baseline for safety-related cable approvals.
- Polyethylene:Cross-linked and radiation-resistant formulations extend service life in high-radiation containment environments. Advanced ethylene-tetrafluoroethylene compounds are displacing legacy insulation in Chinese coastal reactor programs.
- Aluminum:Weight advantages apply in non-safety structural cabling where termination complexity penalties are acceptable.
- PVC:Limited to non-safety applications due to halogen emission concerns under IEEE 383 flame-testing protocols.
Copper maintains the qualification anchor. Polyethylene compounds are climbing the fastest on radiation resistance specifications.
Application:
Functional role within reactor architecture determines signal integrity requirements and accident-condition performance criteria.
- Instrumentation:Low-capacitance multi-pair cables transmit sensor signals to reactor protection systems with microsecond response requirements. Digital instrumentation and control upgrades across aging US and European fleets are compressing procurement cycles for qualified instrumentation cable assemblies.
- Power Distribution:Medium-voltage multi-conductor feeders route auxiliary power through containment boundaries. Chinese provincial utilities in Fujian and Zhejiang are accelerating tendering for qualified power cable assemblies to meet reactor commissioning schedules.
- Control Systems:Command and indication circuits for valve actuators and motor operators require verified circuit integrity under loss-of-coolant accident conditions.
- Communication:Data networks for plant monitoring and administrative systems operate outside safety-class boundaries with reduced qualification overhead.
Power distribution commands the installed volume base. Instrumentation cables are gaining share fastest on digital platform conversion.
End User:
Customer type shapes procurement centralization, contract duration, and qualification documentation depth.
- Nuclear Plants:Operating utilities demand 40-year replacement part commitments bundled with initial installation. CNNC and CGN procurement platforms in China are consolidating vendor panels to three qualified sources per cable category, limiting supplier access windows.
- Utilities:Diversified generation portfolios apply nuclear-grade specifications to critical infrastructure standards across combined cycle and renewable assets.
- Research Facilities:Test reactors and materials research installations specify reduced radiation resistance ratings with accelerated replacement cycles.
- Industrial Plants:Non-nuclear heavy process industries adopt nuclear-grade cable specifications for extreme environment reliability in chemical and metallurgical applications.
Plant operators command the contract value base. Research facility procurement is expanding most quickly on small reactor demonstration programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned utilities and independent power producers concentrate procurement authority across coastal reactor corridors. Long-term power purchase agreements bundle cable supply into multi-decade framework contracts. Qualification requirements diverge sharply between IEEE 383 jurisdictions and IEC 60780 regimes.
China
Fujian and Zhejiang provincial utilities accelerate tendering for qualified cable assemblies to meet reactor commissioning schedules. CNNC and CGN procurement platforms consolidate vendor panels to three qualified sources per cable category. The Yangtze River Delta hosts the densest concentration of domestic cable qualification laboratories serving coastal nuclear provinces.
United States
Operating utilities execute digital instrumentation and control upgrades across aging reactor fleets, compressing procurement cycles for qualified assemblies. The US Nuclear Regulatory Commission enforces 10 CFR 50 Appendix B quality assurance frameworks that reference copper conductor specifications as baseline for safety-related approvals. The Southeast nuclear corridor spanning Georgia and South Carolina concentrates maintenance demand from Westinghouse-designed pressurized water reactors.
India
Russian-designed VVER reactor expansions at Kudankulam create demand for cable suppliers with dual IEC and Russian GOST certification capability. The Atomic Energy Regulatory Board mandates environmental qualification aging simulations that extend cable approval timelines. Tamil Nadu's coastal nuclear zone anchors procurement concentration for indigenous pressurized heavy water reactor programs.
France
Électricité de France maintenance cycles drive demand for specialized low-smoke halogen-free cable portfolios across the domestic reactor fleet. Euratom Treaty environmental aging simulations extend type-approval cycles by 18-24 months versus prior certification frameworks. The Provence-Alpes-Côte d'Azur region concentrates specialized compound suppliers serving Flamanville and Tricastin installations.
South Korea
Korea Hydro & Nuclear Power pilots silicon carbide fiber-optic sensing cables in containment penetration applications. The Korea Institute of Nuclear Safety enforces seismic qualification protocols aligned with IEC 60780 for coastal reactor builds. The Busan-Ulsan industrial corridor hosts cable harness fabrication facilities supplying Shin Kori and Shin Hanul construction sites.
Nuclear Multi-Conductor Cables Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented qualification tiers. The vendor base separates into three strategic archetypes: vertically integrated copper-to-cable manufacturers, regional qualification specialists, and project-specific harness fabricators. Dominant competitive moves include backward integration into radiation-resistant polymer compounding and captive supply of copper rod to sustain qualification margins.
Among European cable manufacturers, Nexans and Prysmian Group occupy positions representing the integrated-manufacturer archetype. RSCC Wire & Cable exemplifies regional qualification specialists competing on domestic content requirements. These three entities anchor the competitive structure without exhausting the qualified vendor base.
| Leading Market Players |
|---|
| Nexans |
| Prysmian Group |
| General Cable |
| RSCC Wire & Cable |
| Habia Cable |
| Southwire Company |
| Kabelwerk Eupen |
| Anhui Cable |
| TMC |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European radiation-resistant polymer compounding facilities is compressing supplier margins while amplifying pricing power for qualified cable manufacturers with captive compound supply. IEEE 383 and IEC 60780 certification burdens are forcing buyers into long-term framework contracts that lock in pricing across reactor construction cycles.
Pricing Analysis
Nuclear-grade qualification tier creates the primary spread between safety-class and industrial-grade cable pricing. Three-tier pricing structure across safety-qualified, nuclear-industrial, and commercial-grade levels reflects differential certification burden and replacement part commitment depth. Cost compression in the commercial-grade tier is intensifying because cross-linked polyethylene substitutes are displacing nuclear-qualified specifications in non-safety applications. Research facilities and industrial adopters exhibit the highest price sensitivity, while operating utilities with 40-year replacement commitments show minimal elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for copper rod and finished cable flows. Manufacturing concentrates in China, France, and South Korea, with each hub serving distinct regulatory certification zones. Raw material sourcing draws from Chilean copper concentrate, German fluoropolymer resin, and Japanese radiation-resistant additives. Single-source vulnerability in qualified polymer compounding creates bottlenecks for new reactor builds. Distribution runs through state-backed procurement platforms in China and EPC contractor vendor panels in Western markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in cable qualification maintenance and 40-year replacement part provisioning are expanding faster than initial hardware installation revenue. Recurring revenue from environmental requalification and aging simulation testing creates annuity streams that hardware margins cannot match.
For Market Incumbents: Harden qualification asset positions by securing captive radiation-resistant polymer compounding capacity before European laboratory bottlenecks worsen. Deepen backward integration into copper rod production to offset London Metal Exchange volatility squeezing long-delivery nuclear contract margins. Lock in multi-reactor framework contracts with CNNC and CGN procurement platforms before vendor panel consolidation closes access windows.
For New Entrants and Emerging Players: Pursue India's Kudankulam corridor as the most penetrable geography, where dual IEC and Russian GOST certification requirements have thinned qualified supplier ranks. Target research facility procurement for small modular reactor demonstration programs, where reduced radiation resistance ratings lower qualification barriers. Enter through factory-fabricated cable harness partnerships with SMR developers seeking pre-tested assemblies over field-terminated alternatives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with captive qualification laboratory assets and long-term utility service contracts. Five-to-ten year viability favors suppliers with dual IEEE and IEC certification capability as reactor export projects multiply across jurisdictions. Watch for inflection in small modular reactor deployment announcements, which favor pre-tested harness suppliers and compress field-service revenue pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of radiation-resistant formulations insulates margins from European laboratory bottlenecks. |
| Dual Certification Investment | Simultaneous IEEE 383 and IEC 60780 qualification opens access to US and Asian reactor export projects. |
| Long-Term Framework Contracting | Multi-reactor bundles with 40-year replacement commitments lock in revenue across commissioning cycles. |
| Factory Harness Fabrication | Pre-tested cable assemblies align with small modular reactor factory-fabrication architectures. |
| Digital I&C Retrofit Specialization | Signal integrity expertise for analog-to-digital upgrades captures fastest-growing instrumentation segment. |
Research Methodology
The analysis maps shielded cable configurations, flexible cable formats, and specialty fiber-optic sensing assemblies, each validated through procurement directors at state-owned utilities, EPC contractor engineering leads, and nuclear regulatory affairs specialists. Primary interviews with reactor protection system architects and cable qualification laboratory managers combined with secondary validation from IEEE standards documentation, IEC certification registries, and national nuclear regulatory filings. Bottom-up unit demand modeling and top-down market sizing triangulate volume estimates across the projection horizon.
Assumptions held reactor commissioning schedules and regulatory framework stability fixed, while copper price trajectories and SMR deployment pace varied across sensitivity scenarios. Segmentation dimensions modeled include product type, conductor material, application function, and end-user procurement centralization, with regional regulatory cluster as an additional nuclear-specific dimension. CAGRs derived from fitted trend extrapolation against historical qualification cycle data and reactor construction pipeline visibility. Forecast inputs incorporated IEEE 383 flame-test adoption timelines and Euratom Treaty environmental aging simulation expansion.
Sensitivities concentrate around copper price volatility, reactor project delays, and divergence between national regulatory frameworks. Forecasts reflect documented assumptions about certification burden stability and qualified laboratory capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Europe Cable Management Market
Cables
Copper Cable Market
Cables
High Voltage Cables Market
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
United States Cable Accessories Market
Cables
Downhole Cables Market
Cables
Active Optical Cable Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
EDM Wires Market
Cables
Audio and Video Cables Market
Cables
LED Cable Market
Cables
Sensing Cable Market
Cables
Military Cable Market
Cables
Submarine Cabling Systems Market
Cables
Twisted Pair Cable Market
Cables
LASER Light Cables Market