
 Semiconductor Memory Market | 2026-2036
Semiconductor Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Memory Market Analysis
The EU Green Deal is hardening carbon-accounting rules for semiconductor fabs, pushing memory manufacturers toward renewable-powered production. Samsung Electronics leverages its captive foundry network to sustain cost leadership in 3D NAND wafer output. SK Hynix anchors high-bandwidth memory supply for GPU accelerators. Micron Technology competes through advanced packaging R&D in Idaho and Singapore.
Semiconductor memory encompasses volatile and non-volatile electronic storage cells fabricated from silicon-based transistor arrays, typically organized in bit-addressable matrices with access speeds measured in nanoseconds and retention characteristics spanning milliseconds to decades without power; these devices serve as the primary working and persistent storage layer across virtually all digital systems. DRAM dominates volume shipments for computing applications where speed outweighs cost, while Flash memory captures margin pools in data storage and mobile devices due to its non-volatile density advantage. DDR5 technology is displacing prior generations in server sockets, and 3D NAND stack heights continue climbing as the structural path to cost-per-bit reduction.
The EPA enforces hazardous substance reporting for U.S. memory fabrication facilities, while REACH governs chemical inputs for European-bound production, and China's MEE administers emissions permits for domestic wafer plants. These frameworks elevate compliance costs but also filter out sub-scale competitors unable to fund environmental controls. Stakeholders must track how memory-intensive AI inference deployment reshapes procurement specifications before the next process node transition.
Market Dynamics
AI training clusters are absorbing HBM and DDR5 at rates that outstrip wafer-level supply expansion, compressing procurement cycles and elevating spot-price volatility as the dominant market-shaping force.
Growth Catalysts
- GPU accelerator pull:Cloud service providers are scaling memory-dense server deployments to support generative AI inference workloads, tightening HBM allocation queues.
- EU AI Act:Embedded memory in autonomous vehicles and industrial robotics faces new conformity assessment requirements, driving qualified supplier consolidation.
- 3D NAND layer stacking:Process migration beyond 200-layer architectures is reducing die cost for enterprise SSD penetration into cold storage tiers.
Market Restraints
- Extreme ultraviolet lithography dependency:ASML equipment lead times constrain DRAM node transitions, capping bit supply elasticity.
- Fluorinated gas emissions controls:REACH and EPA reporting obligations inflate fab operating costs for etch and chamber-clean processes.
- Geographic concentration risk:Front-end wafer output clusters in Hsinchu and Pyeongtaek expose downstream buyers to seismic and geopolitical disruption.
Strategic Opportunities
- India semiconductor incentives:PLI scheme subsidies for memory packaging and testing are attracting module assembly investment away from traditional ASEAN hubs.
- In-memory computing architectures:Processing-in-memory arrays are converging with AI accelerator designs to reduce data movement energy.
- Automotive edge AI:L4 autonomous systems require fault-tolerant non-volatile storage, opening specification windows for emerging MRAM and ReRAM tiers.
Industry Challenges
- Process engineer scarcity:Atomic layer deposition expertise resides in a limited talent pool concentrated in South Korea and Taiwan.
- Legacy DDR4 inventory absorption:Server OEM qualification timelines delay socket migration, stranding working capital in prior-generation die.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Memory Market |
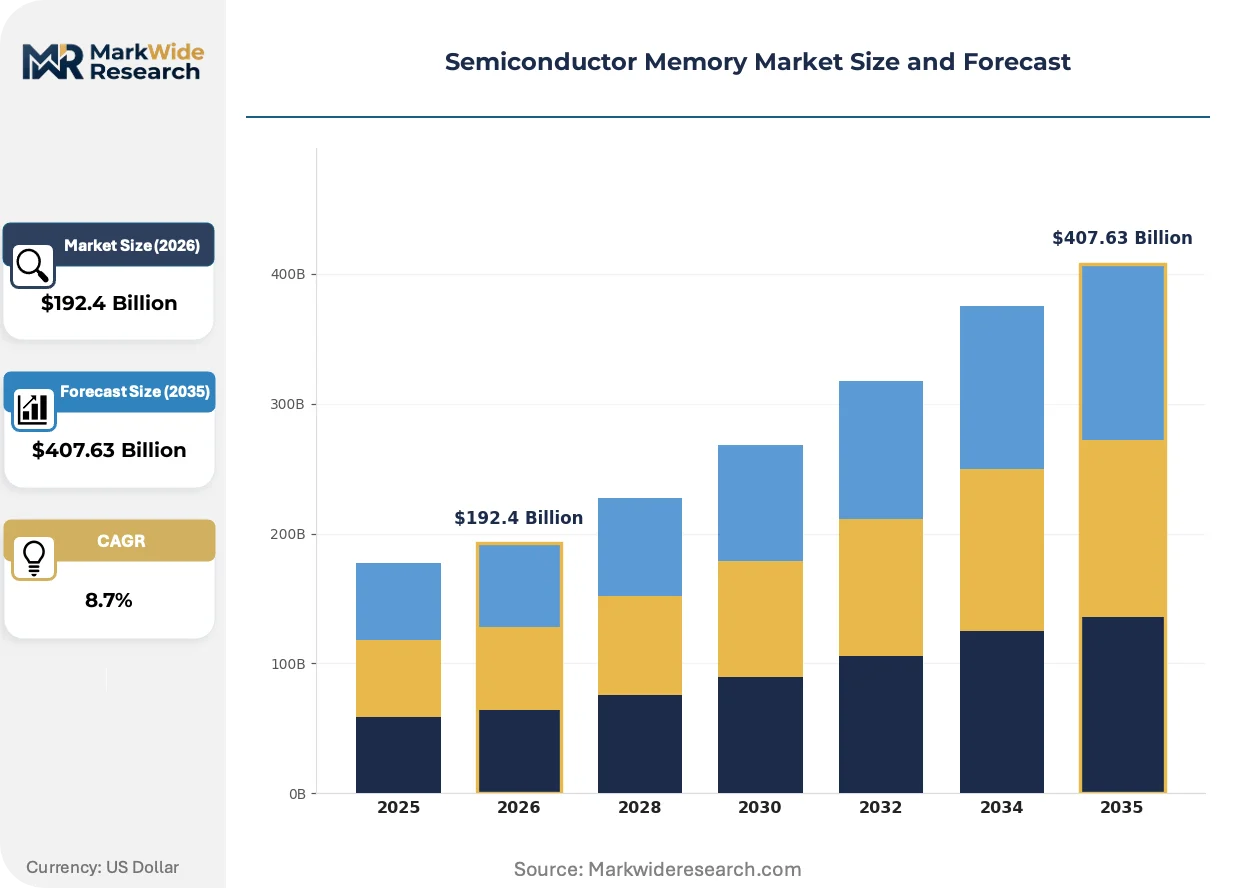
| Market Size in 2026 | $192.4 Billion |
| Market Size in 2035 | $407.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash, EEPROM End User: Consumer Electronics, Automotive, Industrial, Telecommunications Technology: 3D NAND, DDR4, DDR5, LPDDR Application: Data Storage, Computing, Networking, Mobile Devices |
| Companies Covered | Intel Corporation, Marvell Technology, Samsung Electronics, Infineon Technologies, Lam Research, SK Hynix, Western Digital, ChangXin Memory Technologies, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Memory Market Emerging Trajectories
Memory subsystem design is fragmenting along workload-specific axes, with bandwidth-optimized and capacity-optimized architectures diverging rather than converging on universal standards.
Compute Express Link is unifying coherent memory pooling across CPU, GPU, and accelerator sockets. Hyperscale datacenter operators are adopting CXL 2.0 switch fabrics to disaggregate DRAM resources from processor nodes. This technology is unifying previously siloed memory budgets into shared resource pools, compressing stranded capacity and reshaping module form factor roadmaps.
REACH authorization requirements for PFAS and fluorinated greenhouse gases are tightening chemical input scrutiny for European-bound production. Memory fabs are reformulating wet etch chemistries and chamber clean processes to preempt supply chain exclusion. High-bandwidth memory stacks with complex through-silicon via processing face the steepest compliance cost escalation.
Hyperscale buyers are consolidating procurement through direct wafer-level agreements rather than distributor-mediated spot purchasing. Tier-one cloud operators now negotiate multi-year die supply contracts with foundry partners, bypassing traditional module vendor channels. This pattern is most pronounced in North American and Chinese datacenter buildouts, where memory represents the dominant server bill-of-materials cost component.
Semiconductor Memory Market Segmentation
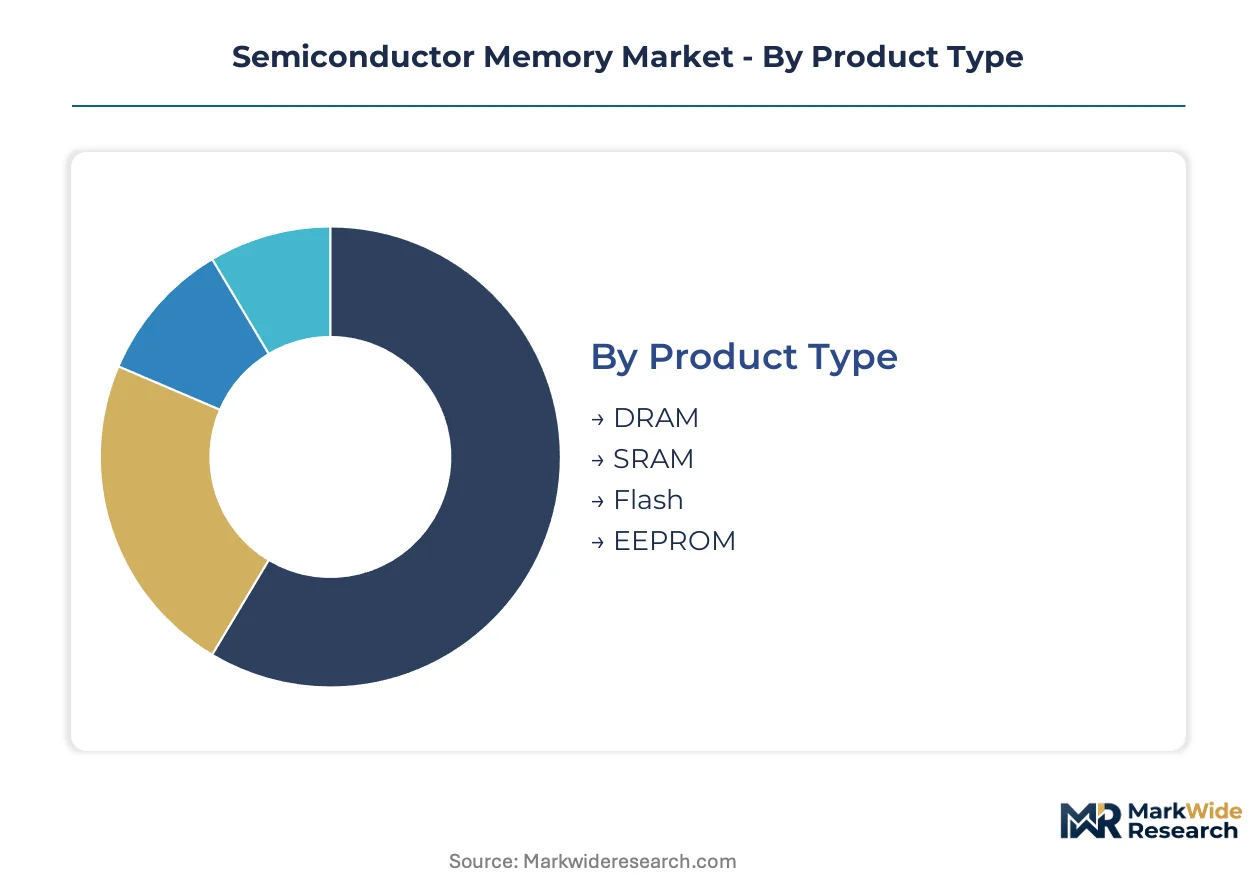
Memory procurement specifications diverge sharply between bandwidth-hungry AI accelerators and cost-sensitive cold storage tiers. Suppliers must align process node roadmaps with distinct thermal, density, and endurance requirements across these splits.
Product Type:
DRAM commands wafer output volumes while Flash captures margin pools in persistent storage applications.
- DRAM:Capacitor-based volatile cells refresh thousands of times per second to retain charge. Cloud service providers in Virginia and Frankfurt absorb DDR5 die for training clusters, constrained by EUV equipment lead times from ASML. Today's leader: DRAM. Tomorrow's challenger: Flash.
- SRAM:Six-transistor bistable latches deliver nanosecond access without refresh overhead. Cache hierarchies in Xeon and EPYC processors in Oregon and Austin concentrate demand, driven by inference latency specifications. Embedded configurations in automotive ECUs face REACH compliance for fluorinated chamber cleans.
- Flash:Floating-gate charge trapping enables decade-scale retention without power. Enterprise SSD penetration into Singapore and Tokyo data centers accelerates as 200-layer 3D NAND yields improve.
- EEPROM:Byte-addressable electrical erasure suits configuration storage in industrial controllers. Shenzhen and Suzhou module houses supply automotive tier-1s with MEE emissions permits.
DRAM wafer starts dominate foundry allocation; Flash bit shipments expand most quickly in enterprise storage tiers.
End User:
Automotive qualification timelines stretch longest while consumer electronics volumes fluctuate with handset refresh cycles.
- Consumer Electronics:Smartphones and tablets in Seoul and Cupertino drive LPDDR5 procurement for AI-enabled camera pipelines. Spot price volatility compresses module vendor margins during inventory corrections.
- Automotive:L4 autonomous systems in Stuttgart and Detroit require fault-tolerant non-volatile storage across temperature extremes. EU AI Act conformity assessments for embedded memory extend supplier qualification windows to 18-24 months.
- Industrial:Programmable logic controllers in Munich and Yokohama specify extended-temperature DRAM for factory automation. RoHS substance restrictions govern solder joint reliability in 10-year service life deployments.
- Telecommunications:Baseband units in Ericsson and Nokia supply chains in Stockholm and Espoo buffer 5G payload data with HBM2E stacks. CXL 2.0 disaggregation is reshaping rack-level memory pooling architectures.
Automotive commands premium pricing; telecommunications infrastructure climbs fastest on AI inference deployment.
Technology:
DDR5 socket penetration advances in servers while LPDDR dominates mobile thermal envelopes.
- 3D NAND:Vertical charge-trap cells stack beyond 200 layers to reduce die cost per gigabit. Yields at Samsung's Pyeongtaek and Kioxia's Yokkaichi fabs determine enterprise SSD pricing in North American hyperscale tenders.
- DDR4:Mature 1z-nm process nodes supply legacy server sockets in Dallas and Phoenix. Stranded inventory absorption delays working capital recovery for module assemblers.
- DDR5:On-die ECC and PMIC integration raise power efficiency for AI training clusters. Intel Sapphire Rapids and AMD Genoa platforms in Santa Clara and Austin drive socket migration.
- LPDDR:Low-voltage operation extends battery endurance in foldable handsets. MediaTek and Qualcomm reference designs in Hsinchu specify LPDDR5X for generative AI on-device processing.
DDR5 claims server sockets fastest; 3D NAND layer stacking sustains cost reduction curves.
Application:
Data storage and computing applications pull divergent memory architectures—capacity-optimized versus bandwidth-optimized.
- Data Storage:QLC 3D NAND in 30TB enterprise SSDs displaces 10K RPM hard drives in cold tiers. Backblaze and AWS Glacier deployments in Sacramento and Dublin concentrate procurement.
- Computing:HBM3 stacks with 12-Hi TSV processing feed NVIDIA H100 and AMD MI300 accelerators. TSMC CoWoS capacity in Taichung constrains GPU-attached memory supply.
- Networking:SmartNICs and DPUs in Mellanox and Pensando supply chains buffer packet data with GDDR6. Tel Aviv and Bangalore fabless designers specify deterministic latency for 400G switch fabrics.
- Mobile Devices:Unified memory architecture in Apple Silicon and Qualcomm Snapdragon consolidates DRAM and storage controllers. Shenzhen assembly plants source stacked package-on-package configurations from ASE and Amkor.
Computing commands highest bit density per socket; networking gains fastest on SmartNIC penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineering talent concentrates in Hsinchu and Pyeongtaek, anchoring advanced node development. Cleanroom technicians and EUV specialists migrate between Samsung, SK Hynix, and TSMC facilities, creating knowledge spillovers that sustain regional competitiveness. This workforce distribution shapes where capital deploys.
United States
Hyperscale datacenter operators in Virginia and Oregon absorb DDR5 and HBM die for AI training infrastructure. The EPA enforces hazardous substance reporting for fabrication facilities in Idaho and California. Micron Technology operates advanced packaging R&D in Boise and Singapore, feeding module assembly for domestic server OEMs.
China
ChangXin Memory Technologies and Yangtze Memory Technologies expand 3D NAND and DRAM capacity for domestic cloud providers. The MEE administers emissions permits for wafer plants in Hefei and Wuhan. The Yangtze River Delta cluster concentrates module assembly operations serving Shenzhen consumer electronics manufacturers.
South Korea
SK Hynix anchors high-bandwidth memory supply for NVIDIA GPU accelerators deployed globally. Samsung Electronics leverages captive foundry networks to sustain cost leadership in 3D NAND wafer output. The Pyeongtaek complex hosts the world's densest concentration of atomic layer deposition expertise.
Japan
Kioxia and Western Digital joint ventures supply enterprise SSD controllers and 3D NAND die from Yokkaichi. METI coordinates national semiconductor strategy including memory technology roadmaps. The Nagoya industrial corridor hosts precision equipment suppliers feeding ASML lithography tool maintenance.
Taiwan
TSMC CoWoS advanced packaging capacity in Taichung constrains GPU-attached HBM supply for AI accelerators. The National Development Council oversees industrial park incentives for memory packaging investment. Hsinchu Science Park aggregates DRAM design houses and testing facilities serving global module vendors.
Semiconductor Memory Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent cost structures. The market consolidates around three Korean and American conglomerates controlling advanced node wafer output, while Chinese state-backed entrants challenge in mature technology tiers. Strategic archetypes separate captive foundry operators, pure-play memory specialists, and diversified semiconductor conglomerates. Competitive moves center on backward integration into equipment partnerships and multi-year supply contracts with hyperscale cloud operators.
Among Korea-based fabricators, Samsung Electronics and SK Hynix occupy positions as scale-driven suppliers anchoring HBM and 3D NAND output. Micron Technology represents the American archetype with integrated design and packaging operations. Intel Corporation exemplifies diversified semiconductor conglomerates with memory operations sitting within broader compute platform strategies. These three entities collectively shape procurement specifications and process node roadmaps across server, mobile, and automotive sockets.
| Leading Market Players |
|---|
| Intel Corporation |
| Marvell Technology |
| Samsung Electronics |
| Infineon Technologies |
| Lam Research |
| SK Hynix |
| Western Digital |
| ChangXin Memory Technologies |
| Micron Technology |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's carbon-accounting mandates gate qualified supply for European-bound memory production, restricting premium-tier pricing access to fabs with renewable-powered operations and verified fluorinated gas controls.
Pricing Analysis
Bundled long-term wafer supply contracts dominate AI accelerator procurement, while unbundled spot purchasing persists in consumer electronics modules. Three-tier pricing structure across HBM premium, DDR5 standard, and DDR4 economy levels tracks EUV equipment access and yield maturity. Cost compression in legacy DDR4 die is intensifying because server OEM qualification delays strand working capital. Hyperscale cloud operators exhibit lowest price sensitivity; module assemblers serving Shenzhen handset manufacturers face acute margin pressure.
Supply Chain Analysis
Reverse-logistics flows for enterprise SSD refurbishment concentrate in Singapore and Malaysia testing facilities, extending NAND flash service life for cold storage tiers. Front-end wafer output clusters in Taiwan, South Korea, and the United States anchor bit supply. EUV lithography equipment and fluorinated etch chemistries constitute critical input dependencies. Single-source vulnerability around ASML equipment lead times constrains node transition elasticity. Distribution runs through direct foundry-to-hyperscale agreements alongside traditional module vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act operates as a regulatory compounder, extending embedded memory qualification timelines for autonomous systems and consolidating procurement around pre-certified suppliers.
For Market Incumbents: Cement cost leadership in 3D NAND through captive foundry scale at Pyeongtaek and Xi'an complexes. Defend HBM allocation priority against emerging Chinese state-backed entrants by deepening atomic layer deposition talent pools. Accelerate advanced packaging R&D in Idaho and Singapore to offset TSMC CoWoS capacity constraints.
For New Entrants and Emerging Players: Launch via specialized automotive module assembly targeting Stuttgart and Detroit L4 autonomous programs, where EU AI Act conformity assessments create 18-24 month qualification windows that favor agile suppliers. Penetrate India's PLI-subsidized packaging and testing corridors to bypass ASEAN hub congestion.
For Investors and Strategic Acquirers: Roll-up economics work for advanced packaging specialists because TSMC CoWoS capacity shortages force GPU vendors to diversify HBM2E and HBM3 substrate sources. Monitor CXL 2.0 switch fabric adoption rates as the inflection signal for memory disaggregation investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EUV Equipment Partnerships | ASML collaboration secures node transition priority for Samsung and SK Hynix roadmaps. |
| Long-term Wafer Supply Agreements with Hyperscalers | Direct contracts with Virginia and Oregon cloud operators bypass distributor margin capture. |
| Green Manufacturing Transition to Renewable Power | EU Green Deal compliance unlocks premium pricing for European-bound HBM and DDR5 die. |
| Advanced Packaging Capacity Expansion | TSMC CoWoS bottlenecks create arbitrage opportunity for Boise and Singapore R&D facilities. |
| Automotive Qualification Fast-Track Investment | EU AI Act pre-certification opens specification windows for MRAM and ReRAM emerging tiers. |
Methodological Framework
Bottom-up hyperscaler capex modeling reconciled against top-down wafer start tracking forms the analytical core. Primary interviews with DRAM product managers, EUV process engineers, datacenter procurement officers, and automotive tier-1 qualification leads combined with secondary validation from SEC filings, ASML equipment order disclosures, EPA hazardous substance reports, and EU ETS carbon-accounting records. Triangulation across supply-side bit output estimates and demand-side socket penetration rates calibrated segment-level projections.
Input-output matrices map wafer starts through yield curves to bit supply, cross-referenced against server platform launch schedules and AI training cluster deployment timelines across the analysis window. Segmentation dimensions span product type, end-use vertical, technology node, and geographic regulatory cluster. CAGRs derive from fitted diffusion curves for DDR5 socket migration and 3D NAND layer stacking roadmaps, incorporating EUV equipment lead time constraints and fluorinated gas emissions permit scarcity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption scenarios affecting Hsinchu and Pyeongtaek production clusters. Practitioners should monitor ASML equipment order backlogs and EU AI Act implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
VCSEL Market