
 Capacitor Kits Market | 2026-2036
Capacitor Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitor Kits Market Outlook
Trained electronics assembly labor is collapsing across mature manufacturing economies, pushing OEMs and contract manufacturers toward pre-sorted capacitor kits that reduce handling errors and shorten board-assembly cycles. Murata Manufacturing leverages its ceramic capacitor dominance to bundle precision-grade kits targeting high-frequency RF applications. TDK Corporation sustains competitive positioning through vertical magnetics integration that feeds specialized film-capacitor assortments for automotive traction systems. Vishay Intertechnology anchors kit distribution through broad channel control across industrial and military-aerospace verticals.
Capacitor kits are curated assortments of passive charge-storage components, typically packaged by dielectric family, voltage rating, or capacitance decade to streamline procurement and prototyping workflows; standard kits incorporate temperature coefficients spanning C0G NP0 through X7R formulations with rated voltages from 6.3 VDC to 500 VDC. Ceramic configurations occupy the highest volume tier due to multilayer chip scalability and cost efficiency in consumer electronics pick-and-place operations. Electrolytic assortments command stronger margin pools in industrial equipment maintenance channels where long-life aluminum and polymer formulations address ripple-current endurance requirements. Automotive end-user demand is accelerating fastest as EV inverter modules and onboard charger circuits multiply bulk capacitance needs per vehicle platform.
RoHS and REACH frameworks in Europe restrict hazardous substances in passive component plating and dielectric formulations, compelling kit assemblers to certify lead-free terminations and halogen-free packaging. China's GB standards and MIIT directives enforce domestic conformity assessment for capacitor lots entering state-backed infrastructure projects, creating divergent compliance burdens for multinational kit suppliers. Japan's METI circular-economy guidelines pressure manufacturers to disclose material content for recycling-stage recovery. Stakeholders must monitor evolving substance restriction schedules and regional conformity pathways to avoid kit shipment detention at customs checkpoints.
Market Dynamics
Component kit standardization is reshaping how procurement teams manage passive inventory, as multilayer ceramic supply concentration in East Asian manufacturing clusters forces buyers toward pre-qualified assortments that reduce qualification overhead and incoming inspection labor.
Growth Catalysts
- EV Powertrain Electrification:Automotive OEMs are tripling bulk capacitance per vehicle platform for traction inverters and onboard chargers, pulling high-voltage film and ceramic assortments into dedicated kit formats.
- REACH Substance Phase-Out:ECHA restrictions on cadmium and lead in electrode plating are accelerating certified lead-free kit adoption across European industrial maintenance channels.
- Shenzhen Component Trading Density:China's Pearl River Delta concentration of capacitor foundries and electronics assembly contractors enables same-day kit customization for prototype engineers.
Market Restraints
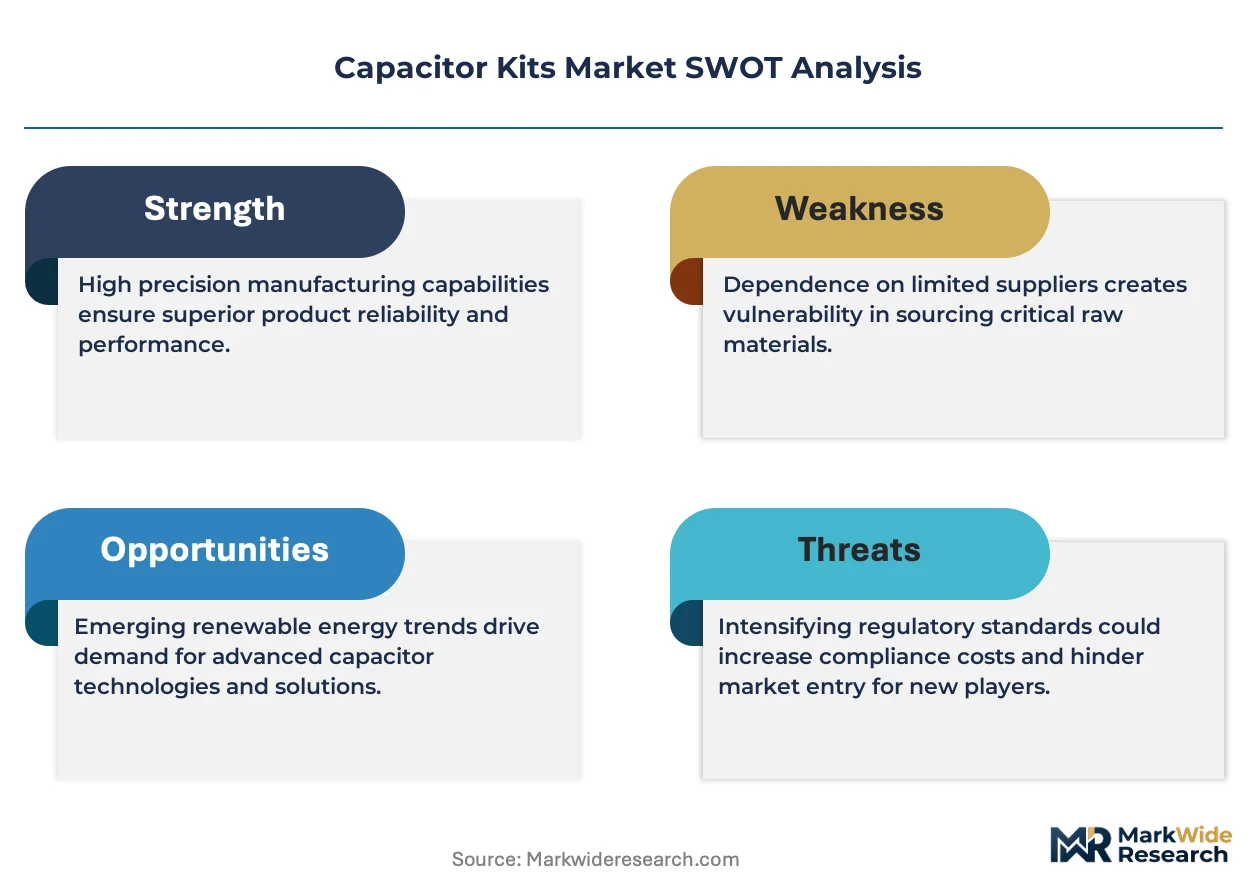
- Palladium Electrode Cost Volatility:Precious metal price swings in base-metal electrode formulations compress margin predictability for mid-tier kit assemblers serving price-sensitive appliance OEMs.
- MLCC Foundry Geographic Concentration:Over 70 percent of multilayer ceramic chip capacity sits in Japan, South Korea, and Taiwan, exposing kit suppliers to single-source disruption from seismic or geopolitical events.
- Aluminum Electrolytic Lifetime Limitations:Liquid electrolyte evaporation in high-temperature automotive underhood applications restricts kit applicability for 15-year vehicle lifetime requirements.
Strategic Opportunities
- India Electronics Manufacturing Incentives:PLI scheme subsidies for component domestication are opening kit assembly and regional distribution nodes for suppliers establishing local stocking presence.
- GaN/SiC Converter Adoption:Wide-bandgap semiconductor switching frequencies above 100 kHz are creating demand for low-ESR ceramic kits optimized for high-frequency power conditioning.
- Repair Café and Circular Economy Mandates:METI guidelines and EU right-to-repair frameworks are expanding addressable market for maintenance-grade electrolytic assortments in consumer appliance refurbishment.
Industry Challenges
- Component Obsolescence Forecasting:Kit planners struggle to predict manufacturer-specific part discontinuations, forcing write-downs of stranded inventory when dielectric formulations sunset.
- Cross-Border Customs Classification Complexity:Harmonized System code ambiguity for mixed-component kits triggers detention delays at EU and China entry points, requiring dedicated trade compliance staffing.
- Pick-and-Place Programming Integration:Kit buyers demand pre-loaded component tape orientations and feeder map files, adding engineering overhead that erodes margin on low-volume custom assortments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitor Kits Market |
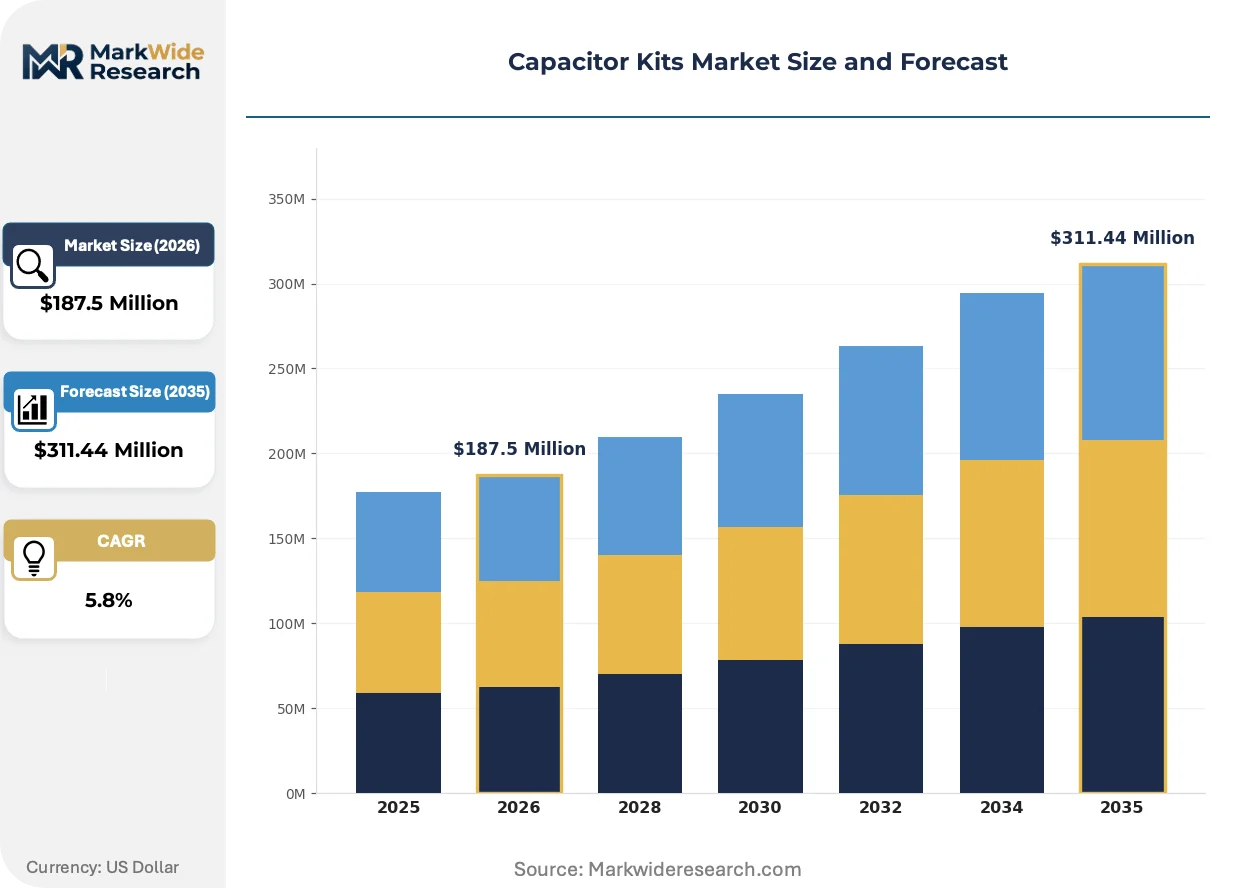
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $311.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic, Ceramic, Film, Tantalum End User: Consumer Electronics, Automotive, Industrial Equipment, Telecommunications Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra-High Voltage Capacitance Value: Below 1μF, 1μF to 10μF, 10μF to 100μF, Above 100μF |
| Companies Covered | Murata Manufacturing Co., Ltd., TDK Corporation, Vishay Intertechnology, Inc., KYOCERA AVX Components Corp., Panasonic Holdings Corporation, Nippon Chemi-Con Corporation, Nichicon Corporation, Rubycon Corporation, KEMET Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitor Kits Market Strategic Shifts
Passive component packaging is converging with digital procurement infrastructure, as cloud-based inventory management and automated kit configuration tools compress the gap between engineering specification and factory-floor availability.
Polymer aluminum solid capacitors are supplanting traditional liquid electrolytic formulations in compact power supply designs. Server power supply designers at hyperscale datacenter operators are adopting these components for 105°C endurance and reduced equivalent series resistance. This transition is supplanting incumbent radial leaded assortments in 1U rack-mount kit configurations, compressing available shelf space for legacy wet aluminum products.
China's GB standards enforcement through MIIT conformity assessment procedures is tightening traceability requirements for capacitor lots entering state-backed infrastructure tenders. Domestic kit assemblers must now provide material composition disclosures and lot-level test data that foreign competitors struggle to match without localized quality systems. Industrial automation and smart grid sectors are most affected, with European kit suppliers accelerating joint venture partnerships to maintain eligibility.
Consolidated vendor-managed inventory programs are displacing spot-buy procurement for high-volume contract manufacturers. Foxconn and Pegatron tier-one facilities are mandating blanket purchase order structures with quarterly consumption true-ups, forcing kit distributors to absorb carrying cost and demand forecast risk. This behavioral shift is most visible in Taiwan and Mexico maquiladora operations, where material planners prioritize suppliers offering consignment stocking and EDI integration over price-minimizing spot market transactions.
Capacitor Kits Market Segmentation
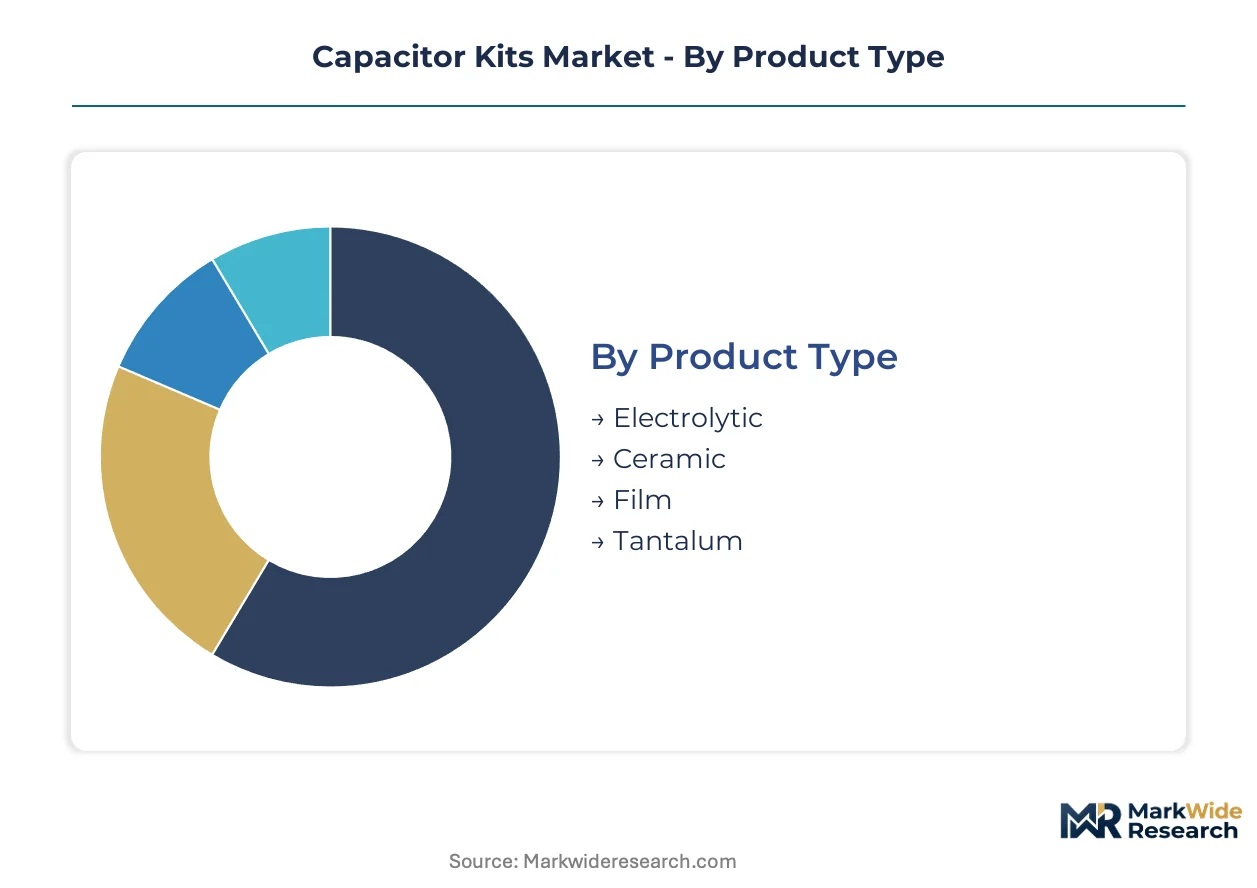
Capacitor kit segmentation reflects divergent procurement patterns across domestic appliance repair channels and export-driven automotive supply chains. Kit assemblers configure assortments differently for Shenzhen electronics trading hubs versus European industrial maintenance networks.
Product Type:
Domestic consumption concentrates in ceramic assortments for consumer electronics prototyping, while electrolytic and film kits dominate export flows to automotive and industrial equipment channels.
- Ceramic:Multilayer chip configurations leverage C0G NP0 through X7R dielectric formulations for surface-mount pick-and-place operations. Shenzhen trading hubs and domestic appliance manufacturers absorb the highest kit volumes for RF filtering and decoupling applications.
- Electrolytic:Aluminum and polymer formulations address ripple-current endurance in power supply conditioning. Automotive underhood applications and industrial motor drives pull these assortments through maintenance-grade distribution channels, though liquid electrolyte evaporation constraints limit 15-year vehicle lifetime applicability.
- Film:Metallized polypropylene and polyester constructions serve high-voltage DC link applications in EV traction inverters.
- Tantalum:Solid manganese and polymer cathode variants target military-aerospace and medical device reliability requirements.
Ceramic holds the largest share; momentum sits with film kits as EV powertrain electrification accelerates.
End User:
Cost tier stratification separates premium-certified automotive kits from economy-grade consumer electronics assortments.
- Automotive:AEC-Q200 qualification mandates temperature cycling and mechanical shock testing for traction inverter and onboard charger applications. OEMs triple bulk capacitance per vehicle platform, pulling high-voltage film and ceramic assortments into dedicated kit formats with lot traceability documentation.
- Industrial Equipment:Long-life aluminum electrolytic kits address ripple-current endurance in motor drives and welding equipment. European REACH compliance and China's GB standards enforcement create divergent certification burdens for multinational suppliers.
- Consumer Electronics:Shenzhen component trading density enables same-day kit customization for prototype engineers and maker communities.
- Telecommunications:Base station power supplies and 5G mmWave infrastructure demand low-ESR ceramic assortments.
Automotive commands premium pricing tiers; consumer electronics drives volume scale.
Voltage Rating:
Application maturity separates established low-voltage ceramic assortments from emerging ultra-high voltage film configurations.
- Low Voltage:6.3 VDC to 50 VDC ratings dominate multilayer ceramic chip kits for smartphone and tablet decoupling networks.
- Medium Voltage:50 VDC to 250 VDC spans industrial power supply input filtering and LED driver applications.
- High Voltage:250 VDC to 500 VDC film capacitor kits serve solar inverter DC links and EV onboard chargers.
- Ultra-High Voltage:Above 500 VDC specialized film constructions address grid-scale energy storage and traction inverter bus capacitance.
Low voltage holds the largest share; ultra-high voltage is expanding most quickly.
Capacitance Value:
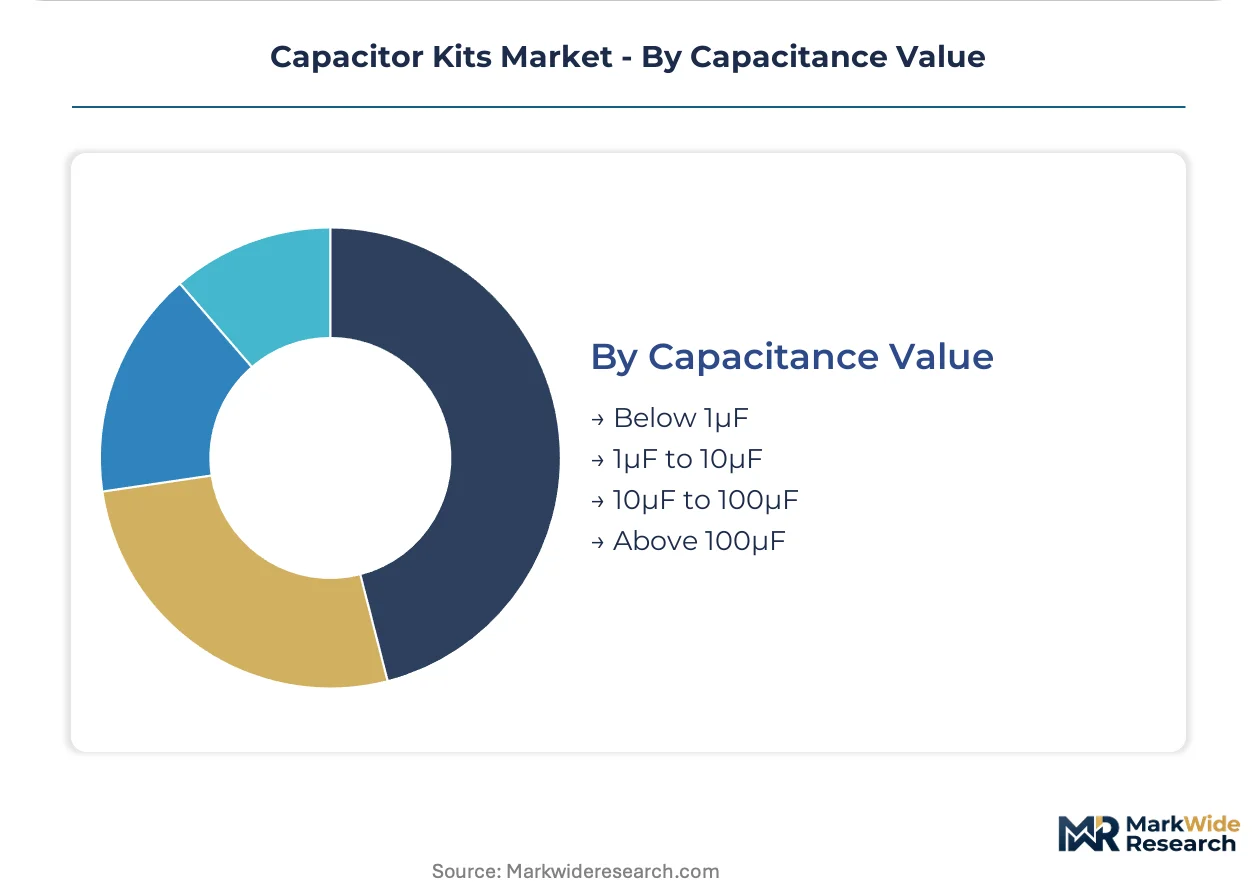
Supply concentration in East Asian MLCC foundries shapes availability across the microfarad spectrum.
- Below 1μF:High-frequency decoupling and RF matching applications in telecommunications and consumer electronics.
- 1μF to 10μF:Bulk decoupling for microcontroller and FPGA power rails in industrial automation.
- 10μF to 100μF:Switching power supply output filtering and audio coupling circuits.
- Above 100μF:Aluminum electrolytic and polymer solid formulations dominate energy storage for motor drives and automotive subsystems.
Below 1μF holds the largest share; above 100μF is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT conformity assessment procedures anchor kit demand in China, where state-backed infrastructure tenders enforce GB standards traceability. ECHA substance restrictions reshape European procurement patterns. Regional kit consumption clusters around manufacturing density and regulatory enforcement intensity.
China
Shenzhen's component trading hubs absorb the highest kit volumes for consumer electronics prototyping and domestic appliance manufacturing. MIIT directives enforce material composition disclosures for capacitor lots entering state-backed infrastructure projects. Pearl River Delta foundries enable same-day kit customization for export-oriented contract manufacturers.
Japan
METI circular-economy guidelines pressure manufacturers to disclose material content for recycling-stage recovery. Domestic MLCC foundries concentrate in Kyushu and Kansai industrial corridors. Tokyo-based trading houses coordinate kit distribution for automotive and telecommunications verticals across Southeast Asian assembly nodes.
Germany
REACH compliance mandates reshape industrial maintenance channel procurement for lead-free terminations and halogen-free packaging. ECHA cadmium and lead restrictions accelerate certified kit adoption across motor drive and welding equipment sectors. Bavarian automotive suppliers source high-voltage film assortments for EV traction inverter integration.
United States
FAA certification requirements and NHTSA automotive safety standards drive AEC-Q200 qualified kit demand for aerospace and electric vehicle applications. Southwest semiconductor fabrication clusters pull precision ceramic assortments for RF and power conditioning designs. EPA hazardous substance reporting influences domestic kit assembler material selection protocols.
India
PLI scheme subsidies for component domestication open kit assembly and regional distribution opportunities for establishing local stocking presence. BIS certification requirements tighten for capacitor lots entering telecommunications and industrial automation tenders. Tamil Nadu and Karnataka electronics manufacturing zones absorb maintenance-grade electrolytic assortments for motor drive refurbishment.
Capacitor Kits Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with ceramic dielectric specialists commanding premium positioning while trading-house assemblers compete on customization velocity. The market structures around three tiers: integrated material suppliers with captive dielectric production, specialized kit configurators serving prototype engineers, and broad-line distributors managing vendor-managed inventory programs. Dominant competitive moves include backward integration into dielectric formulation and geographic expansion through joint venture partnerships to satisfy local content requirements.
Among Japanese material suppliers, Murata Manufacturing Co., Ltd. and TDK Corporation exemplify the integrated archetype with captive ceramic and magnetics production feeding specialized kit formats. Vishay Intertechnology, Inc. anchors the broad-line distribution tier with channel control across industrial and military-aerospace verticals. KYOCERA AVX Components Corp. occupies a position between these tiers, representing the specialist configurator archetype for high-reliability applications.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Vishay Intertechnology, Inc. |
| KYOCERA AVX Components Corp. |
| Panasonic Holdings Corporation |
| Nippon Chemi-Con Corporation |
| Nichicon Corporation |
| Rubycon Corporation |
| KEMET Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term blanket purchase order structures with quarterly consumption true-ups dominate high-volume procurement, locking contract manufacturers into price visibility while forcing kit distributors to absorb carrying cost and demand forecast risk. This contractual pattern concentrates margin pressure on mid-tier assemblers serving price-sensitive appliance OEMs in China's Pearl River Delta, where Shenzhen trading hubs enable rapid spot-market alternatives.
Pricing Analysis
Price spreads between Japanese ceramic dielectric kits and Chinese trading-house assortments reach substantial multiples for equivalent capacitance ratings. Three-tier pricing structure across AEC-Q200 automotive, industrial-grade, and economy consumer tiers separates certified film assortments from uncatalogued Shenzhen bundles. Cost compression in mid-tier electrolytic kits is intensifying because palladium electrode volatility squeezes base-metal electrode formulations. Appliance OEM procurement teams exhibit highest price sensitivity, while automotive platform engineers prioritize lot traceability over unit cost.
Supply Chain Analysis
Inventory carrying periods for multilayer ceramic chip kits have extended as MLCC foundry concentration in Japan, South Korea, and Taiwan creates allocation bottlenecks during demand surges. Raw material dependencies center on palladium for base-metal electrodes, aluminum foil for electrolytic constructions, and polypropylene film for DC link applications. Single-source vulnerability from seismic exposure in Kyushu industrial corridors threatens ceramic dielectric supply continuity. Distribution runs through vendor-managed inventory programs at Foxconn and Pegatron tier-one facilities, displacing spot-buy procurement for high-volume contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capacitor kits market is entering a cyclical recovery phase as EV powertrain electrification triples bulk capacitance demand per vehicle platform, creating sustained absorption capacity for high-voltage film assortments.
For Market Incumbents: Compound channel control through backward integration into dielectric formulation and captive magnetics production, mirroring Murata Manufacturing's ceramic dominance strategy. Prioritize AEC-Q200 certification investment to defend margin position against emerging trading-house competitors from Shenzhen. Accelerate joint venture partnerships in India to satisfy PLI scheme local content requirements before multinational competitors establish regional stocking presence.
For New Entrants and Emerging Players: Lead with customization velocity for prototype engineers in Shenzhen's maker communities, where same-day kit configuration commands premium positioning unavailable to integrated material suppliers. Target maintenance-grade electrolytic assortments for India's Tamil Nadu motor drive refurbishment sector, where BIS certification barriers remain lower than automotive qualification tiers. Establish direct EDI integration with contract manufacturers to bypass incumbent distributor markups.
For Investors and Strategic Acquirers: Capital is best deployed toward specialist kit configurators with established MIIT traceability systems and GB standards compliance infrastructure, as China's state-backed infrastructure tenders increasingly exclude foreign competitors lacking localized quality systems. Long-term viability hinges on circular-economy material disclosure capabilities responding to METI recycling-stage recovery guidelines. Watch for ECHA substance restriction schedule acceleration as the inflection indicator requiring portfolio rebalancing toward lead-free termination specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Formulation | Captive ceramic production insulates Murata Manufacturing from MLCC foundry allocation shocks. |
| AEC-Q200 Certification Investment | Automotive qualification opens traction inverter kit opportunities at Bavarian EV suppliers. |
| Joint Venture Partnership Formation | Local content compliance secures eligibility for China's state-backed infrastructure tenders. |
| Vendor-Managed Inventory Program Expansion | Consignment stocking aligns with Foxconn's blanket purchase order consumption structures. |
| Polymer Aluminum Solid Capacitor Transition | High-temperature endurance addresses 15-year automotive lifetime requirements beyond liquid electrolytic limits. |
Study Parameters
Initial hypotheses were tested against primary input from electronics repair technicians, prototype engineers, OEM procurement managers, and vocational training program directors and refined through secondary validation against MIIT conformity assessment procedures, ECHA substance restriction databases, SEC 10-K filings from listed component manufacturers, and customs/trade data from capacitor export flows. Bottom-up demand aggregation from end-user consumption patterns was triangulated with top-down supply-side capacity assessments across Japanese, South Korean, and Taiwanese MLCC foundries.
Variance decomposition across product type, voltage rating, capacitance value, and end-user application dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic drivers including EV adoption curves and electronics manufacturing incentive schemes. Industry-specific forecast inputs incorporated palladium price volatility indices and REACH substance phase-out schedules.
Forecasts assume regulatory continuity in ECHA REACH frameworks, China's GB standards enforcement, and Japan's METI circular-economy guidelines; material policy shifts would require re-modeling with adjusted compliance cost assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Cordless Phone Battery Market
Electronic Components
Data Acquisition Card Market
Electronic Components
IF Digital Attenuator Market
Electronic Components
Battery Holders Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Crystal Oscillators Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Intel Motherboards Market
Electronic Components
Printed Circuit Board Market
Electronic Components
Electric Fuse Market
Electronic Components
USB Charger Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Fuse Bases Market
Electronic Components
Resonators Market