
 Flash Memory Market | 2026-2036
Flash Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Flash Memory Market Intelligence
South Korea's Pyeongtaek cluster is rewriting the geographic map of advanced memory manufacturing. Samsung Electronics anchors the high-capacity enterprise SSD segment through in-house production of 200-plus layer 3D NAND. SK Hynix competes aggressively in HBM and high-density storage for AI servers. Micron Technology dominates the US-based captive supply chain for automotive-grade flash modules.
Flash memory stores data in semiconductor cells using floating-gate or charge-trap transistors organized in NAND or NOR architectures, with 3D NAND stacking vertical layers to achieve terabit-scale densities in single packages. NAND Flash occupies the volume tier for consumer and enterprise storage, while NOR Flash sustains demand in code-storage applications requiring fast random access. Embedded Flash differentiates automotive and industrial systems where soldered-down reliability outranks removable media convenience.
REACH restrictions on fluorinated greenhouse gases and the EU F-Gas Regulation are forcing memory fabs to qualify alternative etching chemistries for high-aspect-ratio channel holes. China's GB standards and SAMR certification requirements shape product access for foreign suppliers serving domestic server and smartphone manufacturers. Stakeholders must monitor how Korea's METI and the US EPA coordinate chemical disclosure rules as layer counts exceed 300 and process chemistries intensify in complexity.
Market Dynamics
Layer-stacking density in 3D NAND fabrication is virtualizing traditional planar scaling economics, forcing capital reallocation toward etching equipment capable of 300-plus vertical channel holes while EU chemical disclosure rules tighten material qualification timelines.
Growth Catalysts
- AI Server Storage:Hyperscale data center operators are expanding high-capacity enterprise SSD procurement to support training workload data pipelines, with SK Hynix and Samsung Electronics anchoring supply from South Korea's Pyeongtaek cluster.
- REACH Chemical Compliance:The EU's F-Gas Regulation and ECHA disclosure requirements are accelerating qualification of alternative etching chemistries, creating first-mover advantage for fabs with advanced process integration capabilities.
- Automotive Embedded Flash:Soldered-down NAND modules for ADAS and infotainment systems are displacing removable storage in vehicle architectures, with functional safety certification under ISO 26262 becoming a procurement gate.
Market Restraints
- Fluorinated Gas Supply Concentration:High-aspect-ratio channel etching depends on NF3 and CF4 chemistries produced by a concentrated supplier base in East Asia, exposing fabs to input cost volatility and export control friction.
- 300-Layer Technical Ceiling:String stacking and wafer bowing constraints in 3D NAND fabrication are compressing yield curves as layer counts exceed 250, forcing slower ramp rates for new process nodes.
- China Market Access Friction:GB standards and SAMR certification requirements for domestic server and smartphone procurement are extending product qualification timelines for foreign suppliers.
Strategic Opportunities
- India Data Center Buildout:The country's PLI scheme for electronics manufacturing and hyperscale cloud expansion in Mumbai and Chennai are creating demand for localized SSD assembly and testing operations.
- Compute Express Link Convergence:CXL memory pooling architectures are enabling flash-based memory tiering alongside DRAM in AI servers, opening new socket opportunities for high-density NAND modules.
- EU Green Deal Incentives:The European Chips Act and carbon border adjustment mechanisms are subsidizing fab construction in Dresden and Leuven, creating captive demand for regional flash supply.
Industry Challenges
- Atomic-Layer Deposition Talent Scarcity:The specialized engineering workforce for high-aspect-ratio film deposition is concentrated among equipment vendors and leading fabs, constraining second-tier expansion.
- Automotive Qualification Timelines:AEC-Q100 stress testing and PPAP documentation for automotive-grade flash modules extend product development cycles to 18-24 months, compressing margin capture windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flash Memory Market |
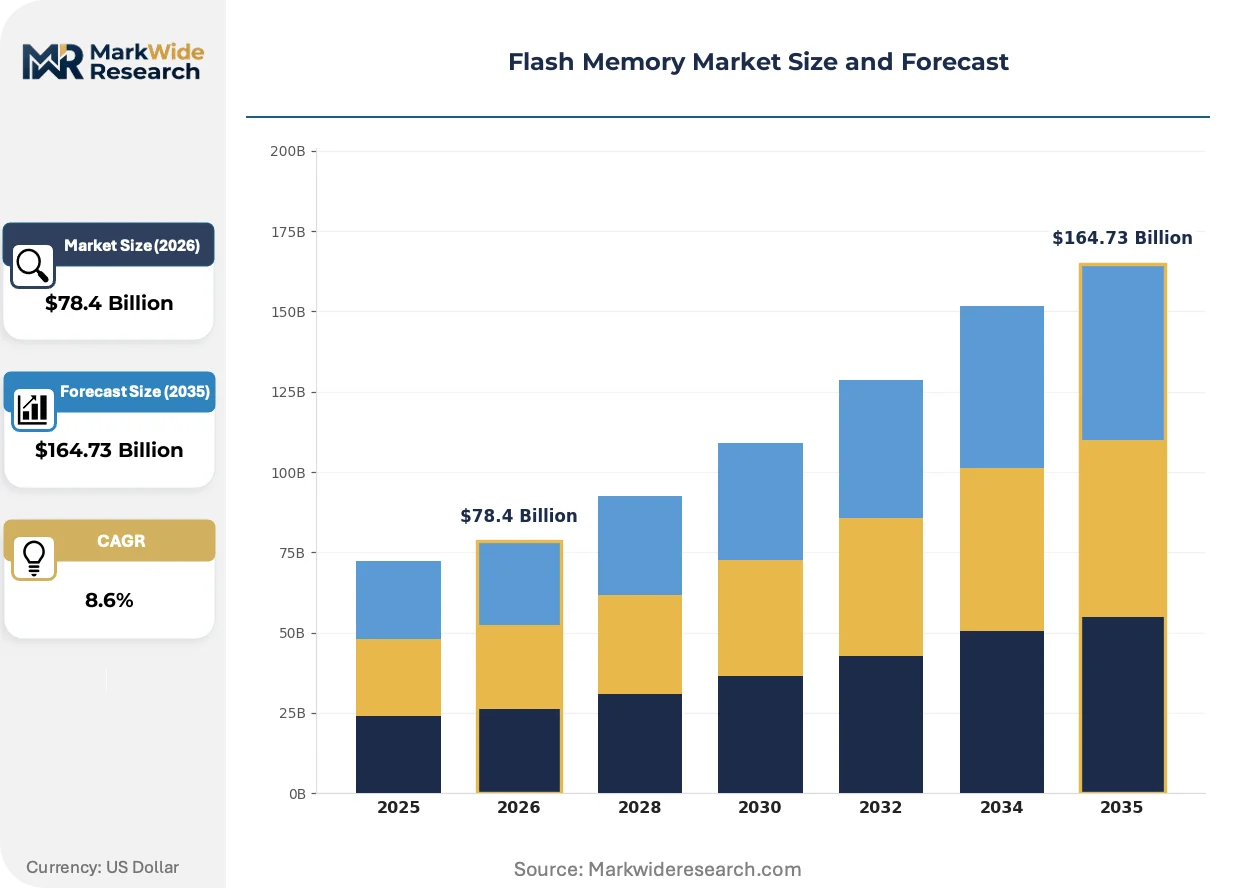
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
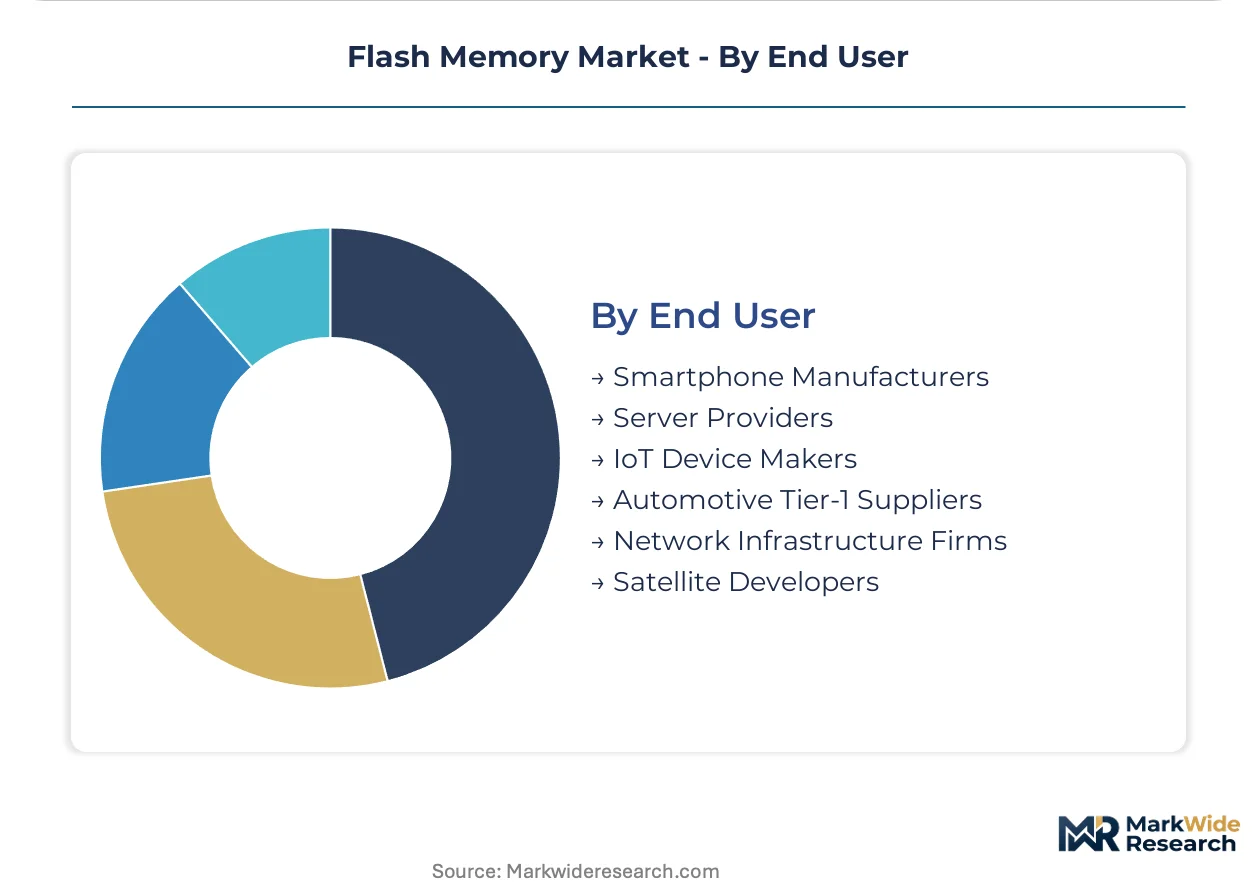
| Segmentation | Product Type: NAND Flash, NOR Flash, 3D NAND, Embedded Flash, Single-Level Cell, Multi-Level Cell Technology: SLC, MLC, TLC, QLC, Resistive RAM, Spin-Transfer Torque RAM Application: Consumer Electronics, Automotive Systems, Data Centers, Industrial Automation, Telecommunications Equipment, Aerospace End User: Smartphone Manufacturers, Server Providers, IoT Device Makers, Automotive Tier-1 Suppliers, Network Infrastructure Firms, Satellite Developers |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, Western Digital, KIOXIA, Intel Corporation, SanDisk, Kingston Technology, Transcend Information, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flash Memory Market Strategic Shifts & Innovations
Flash memory architecture is virtualizing storage hierarchies across data centers, edge devices, and automotive systems, with layer-stacking advances and interface standardization compressing the traditional boundaries between memory and storage tiers.
Charge-trap flash technology using silicon nitride storage layers is virtualizing the floating-gate paradigm that dominated planar NAND scaling. Data center operators are adopting 200-plus layer TLC and QLC devices for warm-tier AI training storage, with CXL-enabled memory expansion controllers collapsing latency gaps between DRAM and flash tiers. This convergence is virtualizing server motherboard real estate allocation, enabling denser compute packaging in hyperscale racks.
The EU F-Gas Regulation and REACH restrictions on perfluorinated compounds are forcing memory fabs to qualify fluorine-free etching chemistries for high-aspect-ratio channel formation. Industrial consequence includes extended process development cycles and capital redirection toward atomic-layer etching equipment. South Korean fabs under METI coordination are most affected, with Samsung Electronics and SK Hynix accelerating alternative chemistry partnerships to maintain layer-stacking roadmaps.
Hyperscale procurement is consolidating around direct supplier relationships for custom firmware and form-factor specifications, displacing distribution-centric purchasing for enterprise SSDs. Channel disintermediation is most visible in North American cloud deployments, where Meta, Google, and Microsoft negotiate directly with NAND manufacturers for qualified device supply, compressing distributor margins and forcing logistics providers toward value-added testing and integration services.
Flash Memory Market Segmentation

Flash memory segmentation reveals divergent lifecycle dynamics across product architectures, with consumer-grade NAND turning over in 18-month cycles while automotive embedded flash extends to 7-year qualification windows. Understanding these temporal patterns exposes where inventory risk concentrates and which technology transitions reward early positioning.
Product Type:
Cycle times compress from raw commodity NAND to specialized embedded variants, with smartphone-bound Multi-Level Cell devices refreshing fastest and aerospace-qualified modules persisting across decade-long platform lives.
- NAND Flash:Charge-trap transistor arrays organized in page-block hierarchies deliver block-erasable storage for high-density applications. Server providers in South Korea's Pyeongtaek cluster absorb the highest volumes, though 300-layer yield compression is extending node transition timelines.
- NOR Flash:Random-access byte-addressable architecture sustains code-storage applications requiring execute-in-place capability. Automotive Tier-1 Suppliers under ISO 26262 certification mandates drive procurement, with functional safety documentation extending development cycles to 24 months.
- 3D NAND:Vertical layer stacking achieves terabit-scale densities through high-aspect-ratio channel etching. Data center operators deploy 200-plus layer TLC devices for AI training pipelines, with CXL-enabled controllers collapsing latency gaps to DRAM tiers.
- Embedded Flash:Soldered-down modules integrated at board-level eliminate removable media failure modes. IoT Device Makers facing extended field-deployment requirements favor industrial-temperature grades with 10-year retention specifications.
- Single-Level Cell:One-bit-per-cell configuration maximizes endurance and retention for mission-critical storage. Network Infrastructure Firms specify SLC for firmware and logging applications where rewrite cycles exceed 100,000 per block.
- Multi-Level Cell:Two-bit-per-cell encoding balances density against performance for cost-sensitive volume applications. Smartphone Manufacturers in India and Vietnam drive procurement through PLI-linked assembly expansion.
NAND Flash anchors the volume base while Embedded Flash gains share at the steepest rate as industrial and automotive systems displace removable storage.
Technology:
Cost tier stratification separates premium endurance grades from commodity density plays, with SLC commanding 4-6x pricing multiples over QLC while layer-stacking advances compress the historical cost-per-gigabyte spread.
- SLC:Single-bit cells deliver maximum program-erase endurance and data retention for industrial and automotive applications. Satellite Developers specify radiation-hardened SLC for orbital deployments where replacement is impossible.
- MLC:Two-bit encoding halves die area versus SLC for equivalent capacity, enabling consumer SSD cost structures. Server Providers in hyperscale cloud deployments specify MLC for read-intensive warm-tier storage.
- TLC:Three-bit cells dominate smartphone and client SSD volumes through controller-managed error correction. Smartphone Manufacturers under India's PLI scheme accelerate TLC procurement for domestic assembly lines.
- QLC:Four-bit encoding pushes density limits for archival and cold-storage applications with infrequent access patterns. Data center operators deploy QLC for AI training dataset retention where read latency tolerance permits.
- Resistive RAM:Memristor-based bit-cell technology eliminates transistor scaling dependencies through resistance-state switching. Industrial Automation vendors prototype ReRAM for edge devices requiring deterministic write latency.
- Spin-Transfer Torque RAM:Magnetic tunnel junction storage delivers non-volatility with SRAM-like speed for persistent memory tiers. Network Infrastructure Firms evaluate STT-MRAM for cache applications demanding unlimited endurance.
TLC captures the highest shipment volumes while QLC expands most quickly as hyperscale operators qualify four-bit cells for warm-tier displacement.
Application:
Application segmentation tracks margin structure divergence, with aerospace modules commanding 40-60% gross margins against sub-10% consumer NAND returns, while data center procurement concentrates purchasing power.
- Consumer Electronics:Smartphones, tablets, and removable storage media absorb the highest unit volumes of commodity NAND. Smartphone Manufacturers in India and Vietnam drive regional demand through PLI-linked production expansion.
- Automotive Systems:ADAS, infotainment, and gateway modules require AEC-Q100 qualified flash with -40°C to 125°C operational ranges. Automotive Tier-1 Suppliers extend qualification timelines to 18-24 months under functional safety mandates.
- Data Centers:Enterprise SSDs and NVMe storage arrays serve AI training and inference workloads. Server Providers negotiate direct supplier relationships, displacing distribution-centric purchasing for qualified device supply.
- Industrial Automation:PLCs, robotics controllers, and edge gateways demand extended-temperature flash with 10-year retention. IoT Device Makers specify industrial-grade modules for predictive maintenance and process control.
- Telecommunications Equipment:Base stations, routers, and core network infrastructure require high-reliability code storage. Network Infrastructure Firms under ETSI standards specify NOR flash for firmware and configuration persistence.
- Aerospace:Avionics, satellite systems, and defense platforms demand radiation-hardened flash with failure-in-place redundancy. Satellite Developers specify SLC with single-event upset mitigation for geostationary and low-earth orbit deployments.
Consumer Electronics anchors the volume base while Data Centers gains share at the steepest rate as AI server buildouts accelerate enterprise SSD procurement.
End User:
Customer-type segmentation exposes procurement pattern fragmentation, with smartphone manufacturers driving spot-market volatility through quarterly purchasing while satellite developers commit to multi-year supply agreements.
- Smartphone Manufacturers:High-volume purchasers of TLC and QLC NAND for embedded storage and removable microSD cards. India's PLI scheme and Vietnam's electronics export incentives are redistributing assembly capacity across South and Southeast Asia.
- Server Providers:Hyperscale cloud operators and enterprise OEMs specifying custom firmware and form-factor enterprise SSDs. Direct supplier relationships with Samsung Electronics and SK Hynix displace distributor margins in North American deployments.
- IoT Device Makers:Industrial sensor, gateway, and edge computing vendors requiring extended-temperature embedded flash. India's smart city initiatives and manufacturing PLI schemes are expanding domestic module assembly.
- Automotive Tier-1 Suppliers:Delphi, Bosch, and Continental-class integrators specifying AEC-Q100 qualified flash under OEM-directed qualification. ISO 26262 functional safety certification gates procurement for ADAS and domain controller modules.
- Network Infrastructure Firms:Ericsson, Nokia, and Huawei-class vendors deploying NOR flash for base station firmware and NAND for edge storage. ETSI and 3GPP standards compliance shapes memory specification requirements.
- Satellite Developers:SpaceX, Thales Alenia, and ISRO-class organizations procuring radiation-hardened SLC for orbital and deep-space missions. ITAR and EAR export controls restrict supplier qualification to domestic and allied-nation vendors.
Smartphone Manufacturers anchors the volume base while Server Providers gains share at the steepest rate as hyperscale data center expansion concentrates purchasing power among cloud operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI coordinates chemical disclosure protocols for South Korean fabs advancing beyond 250-layer 3D NAND. Layer-stacking roadmaps in Pyeongtaek and Icheon drive regional supply concentration.
South Korea
SK Hynix and Samsung Electronics anchor enterprise SSD supply for AI server buildouts. METI's fluorinated gas reporting requirements accelerate alternative etching chemistry partnerships. The Pyeongtaek cluster hosts the world's densest 3D NAND fabrication complexes.
United States
Hyperscale cloud operators in Northern Virginia and Oregon direct-procure qualified NAND devices. EPA chemical disclosure rules intersect with CHIPS Act fab subsidies in Idaho and New York. Micron Technology maintains captive automotive-grade flash production for domestic OEM supply chains.
China
Domestic server and smartphone manufacturers drive procurement under GB standards and SAMR certification. MIIT's integrated circuit policies shape local qualification timelines for foreign suppliers. Yangtze Memory Technologies anchors domestic 3D NAND capacity in Wuhan.
Japan
Equipment vendors in Tokyo and Osaka supply atomic-layer deposition systems for high-aspect-ratio channel formation. METI's semiconductor materials strategy coordinates fluorine-free etching research. Yokohama-based KIOXIA maintains NAND flash fabrication alongside specialized memory development.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich specify AEC-Q100 qualified flash under KBA-directed functional safety mandates. ECHA REACH restrictions on perfluorinated compounds extend material qualification cycles. Dresden's European Chips Act subsidies attract fab construction for regional captive supply.
Flash Memory Market Key Industry Players
Vertically integrated conglomerates and specialized memory fabricators split the market into distinct capability tiers. Samsung Electronics and SK Hynix anchor the high-capacity enterprise segment through in-house 3D NAND production. Western Digital and KIOXIA occupy positions in client storage and removable media. Competitive moves center on layer-stacking roadmaps and direct hyperscale procurement relationships.
Among South Korea-based fabricators, Samsung Electronics exemplifies the vertically integrated archetype controlling design through wafer output. SK Hynix occupies a position within the same geography specializing in high-bandwidth memory integration. Micron Technology represents the diversified multinational with geographic dispersion across Idaho, Singapore, and Japan.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| Western Digital |
| KIOXIA |
| Intel Corporation |
| SanDisk |
| Kingston Technology |
| Transcend Information |
| Others |
Cost & Logistics Intelligence
NF3 and CF4 chemistry supply concentration in East Asia determines both enterprise SSD pricing spreads and fab location decisions for 200-plus layer 3D NAND capacity. Buyers face compressed negotiation leverage when fluorinated gas export controls tighten, forcing qualification timelines for alternative etching chemistries that reshape total cost structures.
Pricing Analysis
South Korean enterprise SSDs command 15-25% premiums over Taiwan-assembled equivalents due to Pyeongtaek cluster proximity to wafer output. Contract-based long-term offtake dominates hyperscale procurement, with AEC-Q100 certification and CXL firmware customization as primary price differentiation drivers. Cost compression in QLC tiers intensifies as yield curves compress beyond 250 layers, though satellite developers show minimal price sensitivity for radiation-hardened SLC.
Supply Chain Analysis
High-purity NF3 feedstock draws from concentrated Japanese and South Korean chemical suppliers, with silicon wafers sourced from Japan, Taiwan, and Germany. Atomic-layer deposition equipment rests on Tokyo and Osaka equipment vendors, creating single-source vulnerability for second-tier fabs expanding beyond 200-layer nodes. Distribution runs through direct supplier relationships with hyperscale cloud operators, displacing traditional distributor margins in North American deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flash memory sits in early-cycle expansion as AI server buildouts accelerate enterprise SSD penetration beyond traditional storage replacement cycles. CXL-enabled memory tiering and 300-layer roadmap execution represent the primary adoption tailwinds through the projection horizon.
For Market Incumbents: Build process integration moats around atomic-layer etching capabilities to defend against emerging Chinese memory entrants qualifying 200-layer devices under domestic GB standards. Secure captive fluorine-free chemistry partnerships before EU F-Gas Regulation enforcement tightens, and expand in-house controller firmware development to preserve margin on hyperscale direct procurement. For New Entrants and Emerging Players: Build out India-based SSD assembly and testing operations to capture PLI-linked demand from Mumbai and Chennai hyperscale buildouts. Automotive embedded flash under ISO 26262 certification presents the most penetrable segment, with 18-24 month qualification windows favoring patient capital deployment and Tier-1 supplier co-development partnerships. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors equipment vendors and specialty chemical suppliers over commodity NAND fabricators. Long-term viability hinges on layer-stacking roadmap execution and alternative chemistry qualification timelines. Watch METI-EPA coordination on fluorinated gas disclosure rules as the signal for regulatory chokepoint intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Etching Chemistry Qualification | Samsung Electronics and SK Hynix partnerships with Japanese chemical suppliers accelerate EU F-Gas compliance timelines. |
| CXL Memory Pooling Integration | Enterprise SSD vendors enabling DRAM-flash tiering collapse latency gaps for AI training workloads. |
| India PLI Scheme Localization | SSD assembly and testing operations in Mumbai and Chennai capture hyperscale data center procurement. |
| Automotive Functional Safety Certification | AEC-Q100 and ISO 26262 documentation gates procurement for ADAS and domain controller modules. |
| Direct Hyperscale Supplier Relationships | Meta, Google, and Microsoft negotiations displace distributor margins in North American cloud deployments. |
Research Approach
Operator-level perspectives from NAND fabrication engineers, hyperscale data center procurement officers, automotive Tier-1 supplier quality managers, and semiconductor equipment vendor technical directors anchored the qualitative base. Primary interview findings triangulated against SEC 10-K filings from memory fabricators, SEMI equipment market data, hyperscaler capex disclosures, and customs records for fluorinated gas trade flows. Bottom-up wafer capacity modeling and top-down end-use demand aggregation validated volume estimates.
Scenario-bracketing around AI server deployment trajectories, 300-layer yield ramp assumptions, and EU chemical regulation enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, bit-cell technology, application vertical, and end-user procurement pattern. CAGRs derived from layer-stacking roadmaps, capital intensity per wafer, and hyperscale storage refresh cycles.
Stress conditions across fluorinated gas supply disruptions, China market access friction, and 300-layer technical ceiling constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on chemistry qualification timelines and yield curve normalization. Cross-checking against SEMI capital equipment forecasts and hyperscaler disclosed storage capex is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
AI Powered Storage Market
Data Storage
Data Storage Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Data Center Ssds Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
North America SSD Caching Market
Data Storage
Europe Flash Memory Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Recordable Optical Disc Market
Data Storage
Americas Flash Memory Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
Digital Recording System Market
Data Storage
Storage and Management Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Ceph Storage Solutions Market