
 Chip Equalizers Market | 2026-2036
Chip Equalizers Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Equalizers Market Insights
South Korea is narrowing its foundry capacity gap in RF and mixed-signal chip production, with Samsung's expanded Pyeongtaek lines now serving fabless equalizer designers. Texas Instruments leverages its Dallas-based 300mm analog fab to sustain cost leadership in programmable gain equalizers. Analog Devices anchors the high-performance segment through its Wilmington, Massachusetts precision manufacturing campus. Qorvo competes aggressively in mmWave equalization for 5G massive MIMO arrays.
Chip equalizers are active or passive integrated circuits that correct frequency-dependent signal distortion by applying gain or attenuation across defined spectral bands, typically operating from kilohertz to millimeter-wave frequencies depending on architecture. These devices employ gallium arsenide, silicon germanium, or CMOS processes with programmable filter banks, variable gain amplifiers, and digital control interfaces to restore signal integrity in bandwidth-limited channels. Digital equalizers now command the fastest expansion trajectory as software-defined radio architectures displace fixed analog implementations in base stations and automotive radar modules. OFDM technology dominates telecommunications applications where subcarrier-based compensation mitigates multipath fading, while FDMA retains niche strength in legacy satellite uplink systems with stable channel conditions.
The FCC in the United States mandates electromagnetic compatibility certification under Part 15 rules for consumer electronics equalizers, while the EU AI Act and CE marking frameworks impose conformity assessment burdens on adaptive digital variants with embedded machine learning. China's MIIT enforces GB standards for radio transmission equipment that dictate equalizer performance thresholds in domestic 5G infrastructure tenders. Stakeholders must monitor evolving spectrum allocation decisions by national regulators and the interoperability requirements those decisions impose on equalizer frequency response specifications.
Market Dynamics
The migration from fixed analog equalizers to software-configurable digital architectures constitutes the dominant structural force reshaping competitive positioning and value capture across the chip equalizer supply base.
Growth Catalysts
- Telecommunications Infrastructure Deployment:5G base station rollouts in China, South Korea, and the United States are pulling high-frequency signal compensation components into volume production. Domestic procurement mandates under China's MIIT GB standards accelerate local sourcing of RF equalizer chips.
- EU F-Gas Regulation:Semiconductor manufacturing process gases face tightening phase-down schedules, compelling foundries to retool etching and deposition equipment. This regulatory pressure is concentrating qualified production capacity among EU-compliant fabs in Germany and France.
- Silicon Germanium Process Maturation:SiGe BiCMOS technology achieves cost parity with GaAs for sub-6 GHz applications while preserving linearity specifications. Automotive radar module suppliers in Japan and Germany are adopting SiGe-based programmable equalizers for volume production.
Market Restraints
- Raw Material Concentration:High-purity gallium arsenide substrate supply concentrates among Japanese and Chinese producers, exposing fabless designers to price volatility and allocation risk during capacity constraints.
- Technical Bandwidth Limitations:CMOS-based equalizers face fundamental noise figure penalties above 28 GHz, restricting their deployment in millimeter-wave massive MIMO arrays where compound semiconductor alternatives retain performance advantages.
- REACH Compliance Burden:EU chemical substance restrictions impose extensive documentation requirements on semiconductor packaging materials, extending qualification timelines for new equalizer product introductions by 6-12 months.
Strategic Opportunities
- India Telecommunications Expansion:TRAI spectrum auctions and domestic manufacturing incentives under the PLI scheme create procurement windows for imported equalizer chips in base station and fiber optic equipment.
- Automotive Radar Convergence:Fusion of 77-81 GHz radar with 5G-V2X communication modules demands dual-band equalization capability. Tier-1 automotive suppliers in Germany and Japan are specifying multi-protocol equalizer architectures.
- EU AI Act Certification Pathway:Adaptive digital equalizers with embedded machine learning qualify for streamlined conformity assessment when demonstrating deterministic response behavior, creating regulatory preference for specific architectural approaches.
Industry Challenges
- RF/Mixed-Signal Talent Scarcity:Design of high-frequency equalizer circuits requires specialized expertise in electromagnetic simulation and parasitic extraction that remains concentrated among experienced engineers at established semiconductor firms.
- Multi-Standard Certification Complexity:Equalizer products must simultaneously satisfy FCC Part 15 electromagnetic compatibility, CE marking, and MIIT GB radio transmission requirements, multiplying test matrix duration and cost.
- Legacy System Integration Friction:Digital equalizer adoption in satellite communication infrastructure confronts FDMA-based channel architectures with stable but infrequent equalization requirements, complicating upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Equalizers Market |
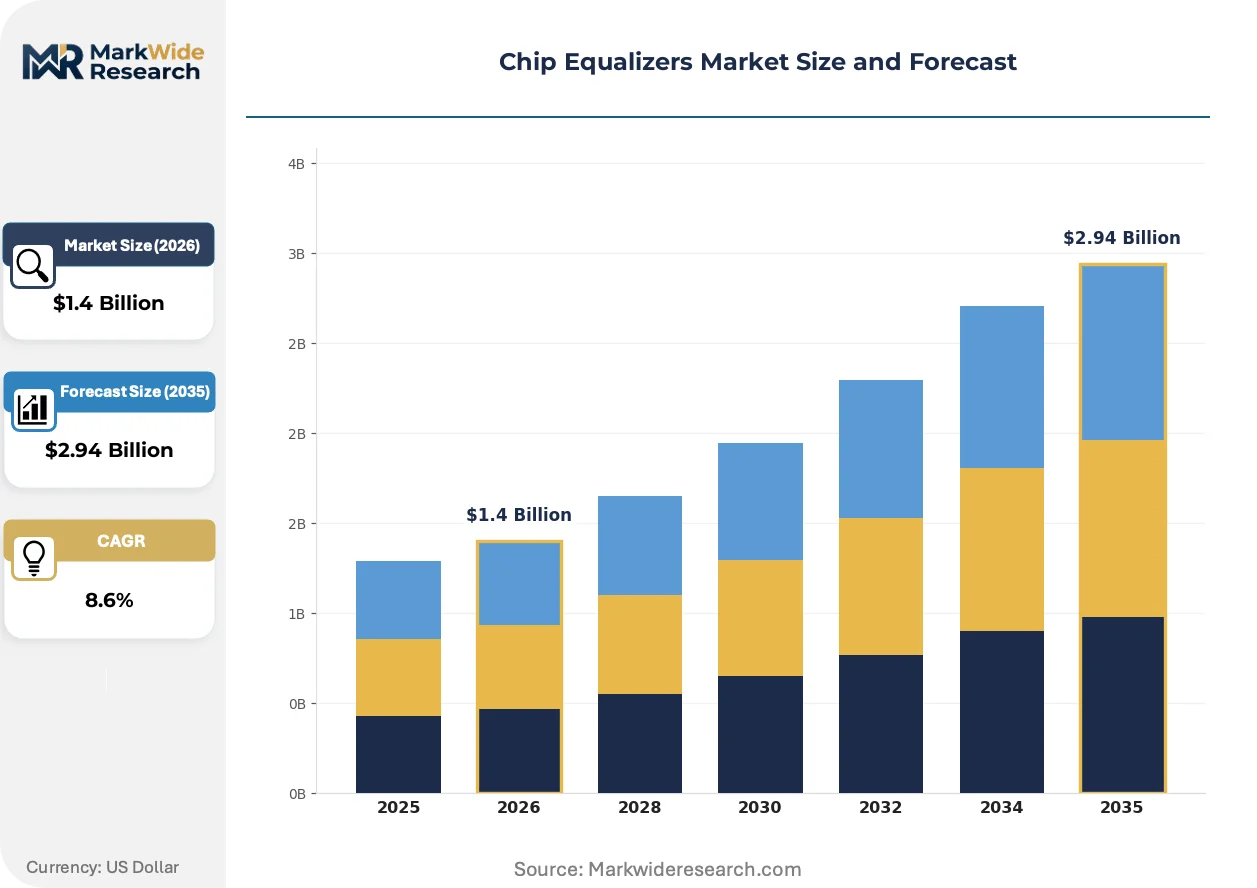
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Equalizers, Digital Equalizers, Parametric Equalizers, Graphic Equalizers Technology: FDMA, TDMA, OFDM, SC-FDMA End User: Telecommunications, Consumer Electronics, Automotive, Broadcasting Application: Audio Processing, Video Processing, Signal Compensation, Speech Enhancement |
| Companies Covered | Mini-Circuits, Texas Instruments, Analog Devices, Microchip Technology, Semtech, Marki Microwave, Qorvo, Broadcom, Skyworks Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Equalizers Market Trends and Innovations
Software-defined radio architectures are compressing the traditional boundary between analog front-end and digital baseband processing, forcing equalizer designers to reconceptualize product boundaries and interface specifications.
SiGe BiCMOS technology is hybridizing the cost structure of RF equalizer production. The process delivers GaAs-comparable noise performance through 6 GHz while leveraging standard CMOS fabrication infrastructure. Base station OEMs in South Korea and the United States are qualifying SiGe programmable gain equalizers for massive MIMO deployments. This technology convergence is compressing margins for pure-play GaAs foundries serving mid-band applications.
REACH and the EU F-Gas Regulation are tightening material compliance requirements for semiconductor manufacturing. Restricted substance lists now encompass fluorinated gases used in plasma etching and chamber cleaning processes. Foundries serving European automotive and telecommunications customers must demonstrate alternative process gas adoption or risk exclusion from qualified supplier lists. German and French fabs are investing in abatement and recovery systems to preserve market access.
Buyers in telecommunications infrastructure are consolidating procurement authority at the system level rather than component level. Base station OEMs now specify equalizer performance as part of integrated RF chain sourcing contracts, displacing discrete chip purchasing by subsystem integrators. This concentration is most visible in China's 5G rollout, where state-owned operators delegate component selection to domestic equipment vendors with captive design teams.
Chip Equalizers Market Segmentation
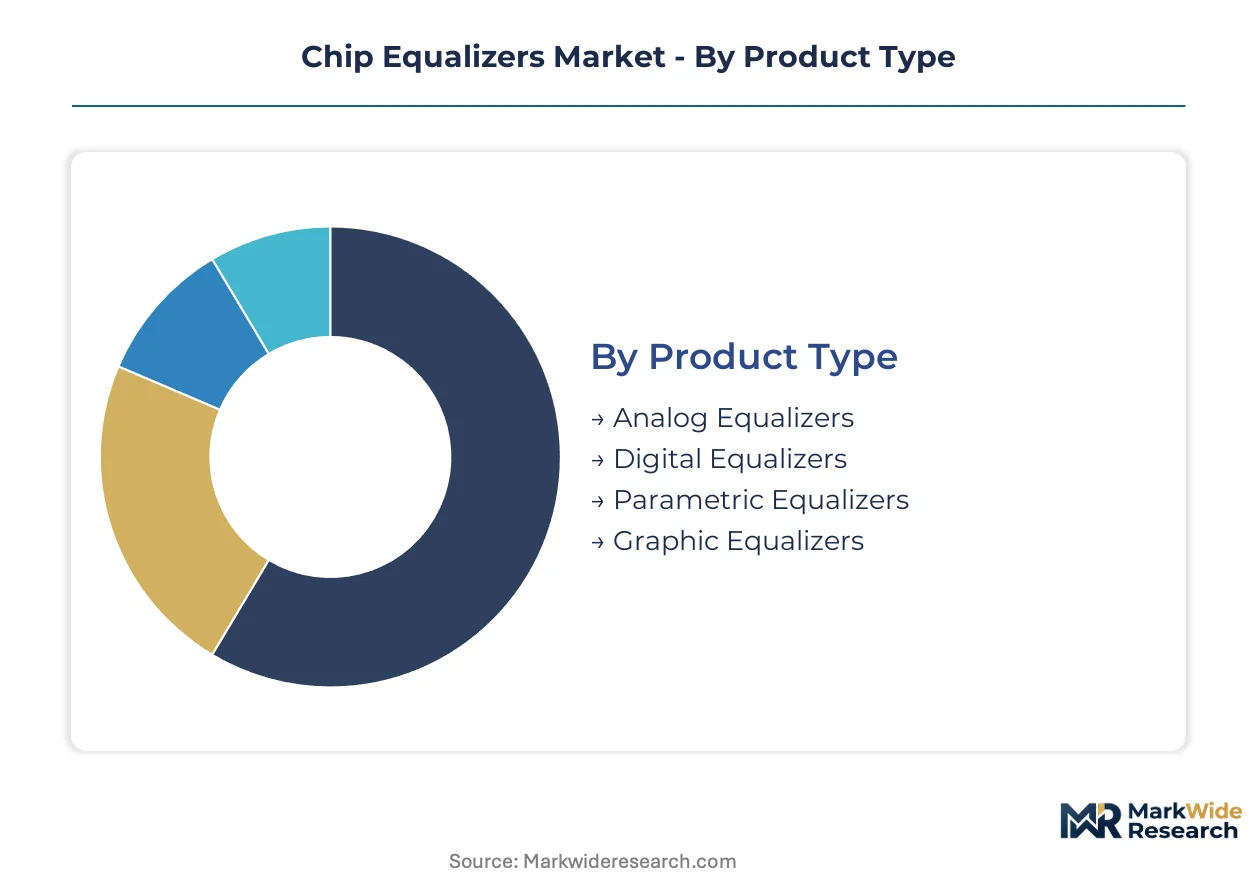
Chip equalizer architectures diverge sharply across frequency bands, signal processing domains, and compliance regimes. Procurement patterns in telecommunications infrastructure favor programmable digital variants, while automotive and consumer segments sustain demand for fixed-function analog implementations. Understanding these segment boundaries clarifies where technology transitions disrupt incumbent supply relationships.
Product Type:
Cost tier determines manufacturing process selection and margin structure across equalizer categories.
- Analog Equalizers:These devices employ passive resistor-capacitor networks or active operational amplifier stages to shape frequency response without digital conversion. Telecommunications infrastructure in China retains substantial procurement of fixed analog equalizers for legacy FDMA backhaul systems where channel conditions remain stable.
- Digital Equalizers:Programmable filter banks with analog-to-digital conversion enable software-defined adaptation to varying channel impairments. Base station OEMs in South Korea and the United States are qualifying digital equalizers for massive MIMO deployments where subcarrier-level compensation mitigates multipath fading.
- Parametric Equalizers:Selective frequency band manipulation with adjustable center frequency and Q-factor serves professional audio processing applications.
- Graphic Equalizers:Fixed-band sliding controls address consumer electronics price points where manufacturing scale outweighs precision requirements.
Analog equalizers command the established base. The steepest expansion runs through digital equalizers.
Technology:
Application context dictates multiple access methodology selection, with spectral efficiency requirements driving architecture preference.
- OFDM:Orthogonal frequency-division multiplexing distributes data across multiple subcarriers with cyclic prefix protection against inter-symbol interference. 5G NR base stations in China, South Korea, and the United States deploy OFDM-based equalization to handle frequency-selective fading in sub-6 GHz and millimeter-wave bands.
- SC-FDMA:Single-carrier FDMA reduces peak-to-average power ratio for mobile uplink transmission. Smartphone RF front-end modules incorporate SC-FDMA equalizers to preserve battery life while maintaining link quality.
- FDMA:Frequency-division multiple access retains niche deployment in satellite communication uplinks with stable channel conditions.
- TDMA:Time-division multiple access persists in legacy cellular infrastructure and specialized industrial radio systems.
FDMA anchors established satellite and legacy cellular installations. The steepest expansion trajectory belongs to OFDM.
End User:
Customer type concentration varies by certification burden and procurement scale, with infrastructure operators dominating high-value contracts.
- Telecommunications:Base station OEMs and network operators specify equalizer performance as part of integrated RF chain sourcing. China's MIIT enforces GB standards that dictate equalizer thresholds in domestic 5G infrastructure tenders, concentrating procurement authority among state-owned operators.
- Automotive:Tier-1 suppliers in Germany and Japan specify multi-protocol equalizer architectures for fusion of 77-81 GHz radar with 5G-V2X communication modules. SiGe BiCMOS technology achieves cost parity with GaAs for these sub-6 GHz applications.
- Consumer Electronics:FCC Part 15 electromagnetic compatibility certification governs equalizer deployment in smartphones, tablets, and wireless audio equipment.
- Broadcasting:Professional audio and video production equipment demands precision equalization with low phase distortion.
Telecommunications commands the established revenue base. Automotive is climbing the fastest as radar-V2X convergence accelerates.
Application:
Volume concentration follows signal processing complexity, with compensation tasks dominating over enhancement functions.
- Signal Compensation:Frequency-dependent gain adjustment restores integrity in bandwidth-limited channels. Optical fiber transmission systems and wireless backhaul networks deploy compensation equalizers to counteract chromatic dispersion and multipath effects.
- Audio Processing:Studio monitoring, live sound reinforcement, and consumer playback systems employ equalization for tonal balance and room correction.
- Video Processing:Broadcast transmission and display calibration use equalizers to manage color channel bandwidth and timing alignment.
- Speech Enhancement:Noise suppression and intelligibility improvement in telecommunications headsets and voice assistants.
Signal compensation anchors the established base. Speech enhancement is gaining share fastest as voice interface deployment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 5G base station deployment pipeline underwrites China's commanding position in chip equalizer procurement, with state-backed fiber optic backhaul networks extending from coastal manufacturing zones to interior provinces.
China
MIIT-mandated domestic procurement quotas for 5G infrastructure concentrate equalizer demand among state-owned equipment vendors. The Yangtze River Delta manufacturing corridor houses RF component fabs supplying base station OEMs with programmable gain devices. Shanghai and Suzhou clusters specialize in SiGe BiCMOS process development for sub-6 GHz applications.
United States
FCC spectrum auctions for C-band and millimeter-wave bands drive base station OEM demand for high-frequency equalization components. The Dallas-Fort Worth metro anchors analog fab capacity for programmable gain equalizers serving telecommunications infrastructure. Greater Boston maintains design centers for adaptive digital architectures with embedded machine learning.
South Korea
Samsung's Pyeongtaek foundry expansion narrows the RF mixed-signal production gap for fabless equalizer designers. The Seoul Capital Area concentrates design houses specifying mmWave equalization for 5G massive MIMO arrays. Busan-Ulsan industrial corridors support packaging and test facilities for high-frequency components.
Germany
EU F-Gas Regulation compliance requirements concentrate qualified foundry capacity in Dresden and Munich manufacturing zones. REACH documentation burdens extend qualification timelines for automotive radar equalizers specified by Tier-1 suppliers. Bavaria hosts precision manufacturing campuses serving telecommunications and industrial automation end uses.
Japan
METI industrial policy supports domestic production of high-purity GaAs substrates for compound semiconductor equalizers. The Kanto region around Tokyo maintains legacy FDMA satellite communication equipment requiring stable analog equalization. Kyushu semiconductor clusters specialize in automotive radar module integration for 77-81 GHz applications.
Chip Equalizers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The supplier base organizes around three tiers: diversified analog semiconductor houses with captive fabrication, fabless RF specialists leveraging foundry partnerships, and integrated device manufacturers serving defense-aerospace niches. Consolidation pressures concentrate procurement authority at base station OEMs, compressing margins for discrete component vendors. Capacity expansion in South Korean foundries and strategic partnerships between automotive Tier-1s and chip designers represent the dominant competitive vectors reshaping supply relationships.
Among diversified analog fabricators, Texas Instruments and Analog Devices exemplify scale-driven positions in programmable gain equalization. Qorvo occupies a specialist tier focused on mmWave frequency bands for 5G infrastructure deployment. These three anchors illustrate the segmentation between cost-optimized analog production and performance-oriented compound semiconductor alternatives.
| Leading Market Players |
|---|
| Mini-Circuits |
| Texas Instruments |
| Analog Devices |
| Microchip Technology |
| Semtech |
| Marki Microwave |
| Qorvo |
| Broadcom |
| Skyworks Solutions |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor anchors freight cost dynamics for gallium arsenide substrate shipments, compressing margins for fabless equalizer designers while amplifying price differentiation between high-volume telecommunications contracts and low-volume aerospace procurement.
Pricing Analysis
Volume-discount tiering structures separate mass-production 5G base station contracts from specialized automotive radar development programs. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with FCC Part 15 and CE marking compliance commanding substantial premiums. Cost compression in the standard tier is intensifying because Samsung's Pyeongtaek foundry expansion adds RF mixed-signal capacity. Telecommunications OEMs exhibit the highest price sensitivity, while defense-aerospace buyers prioritize performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentrates at Samsung's Pyeongtaek lines, Texas Instruments' Dallas 300mm fab, and TSMC's Hsinchu facilities for advanced CMOS nodes. Geographic supply concentrates in South Korea, the United States, and Taiwan for front-end fabrication, with Japan and China controlling high-purity GaAs substrate production. Raw material dependencies rest on germanium feedstock, high-purity arsenic, and specialized ceramic packaging. Single-source vulnerability in GaAs substrate supply poses structural risk. Distribution runs through base station OEM direct procurement rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chip equalizer market tracks a cyclical recovery pattern as 5G base station deployment waves create alternating demand peaks across telecommunications infrastructure procurement cycles.
For Market Incumbents: Harden supply chain resilience through backward integration into GaAs substrate sourcing or captive SiGe BiCMOS capacity additions in Dresden-compliant fabs. Defend against margin erosion from Samsung's foundry expansion by accelerating REACH-compliant packaging qualification timelines. Prioritize certification investment for EU AI Act deterministic response pathways in adaptive digital architectures.
For New Entrants and Emerging Players: India's underpenetrated telecommunications infrastructure offers white-space opportunity under TRAI spectrum auctions and PLI scheme manufacturing incentives. Target automotive radar-V2X convergence applications in Germany and Japan where multi-protocol equalizer specifications remain fluid. Pursue fabless design partnerships with Pyeongtaek or Hsinchu foundries as the primary go-to-market angle.
For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by concentrating qualified foundry capacity among EU-compliant manufacturing zones, elevating strategic value of Dresden and Munich-based production assets. Long-term viability centers on 5G-Advanced and 6G infrastructure refresh cycles spanning the next decade. Target acquisition archetypes include fabless RF specialists with MIIT GB certification pathways. Monitor MIIT domestic procurement quota enforcement as the primary inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| SiGe BiCMOS Process Migration | Cost parity with GaAs through 6 GHz preserves linearity for South Korean massive MIMO deployments. |
| EU F-Gas Compliance Investment | Abatement system adoption preserves qualified supplier status for German automotive Tier-1 contracts. |
| MIIT GB Certification Pathway | Domestic procurement quota eligibility unlocks China's state-owned operator tender participation. |
| Adaptive Digital Architecture Development | Deterministic response behavior qualifies for streamlined EU AI Act conformity assessment. |
| GaAs Substrate Supply Agreement | Long-term offtake contracts with Japanese producers mitigate allocation risk during capacity constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with base station OEM procurement directors, fabless RF design house technical leads, foundry process engineers, automotive Tier-1 supplier component strategists, and telecommunications infrastructure project managers. Secondary validation drew from FCC Part 15 filing databases, MIIT GB standard publications, EU REACH restricted substance lists, SEC 10-K semiconductor segment disclosures, and customs trade data for GaAs substrate flows. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Calibration against historical capacity utilization rates at named foundry facilities informed the analytical framework. Segmentation dimensions modeled include equalizer architecture type, frequency band deployment, multiple access methodology, end-use industry vertical, and regional regulatory compliance cluster. CAGRs were derived from slope analysis of technology adoption curves and infrastructure deployment pipelines. Industry-specific forecast inputs incorporated 5G base station rollout schedules and automotive radar module production forecasts.
Practitioners should monitor foundry capacity expansion announcements, MIIT procurement quota enforcement actions, and EU F-Gas Regulation phase-down schedules for early signals requiring forecast revision. Cross-checking against IHS Markit telecommunications infrastructure capex data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
DNA Chip Market