
 Universal Testing Machine Market | 2026-2036
Universal Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Testing Machine Market Outlook
Carbon-fiber-reinforced polymers in aerospace primary structures is decoupling legacy hydraulic testing demand from next-generation electromechanical platform procurement. ZwickRoell GmbH & Co. KG leverages its German manufacturing base to dominate European aerospace certification workflows. MTS Systems Corporation anchors North American automotive fatigue testing through servo-hydraulic systems integrated into OEM validation labs. Illinois Tool Works Inc. differentiates via Instron's dual-column electromechanical range serving university research consortia across multiple continents.
A universal testing machine applies controlled tensile, compressive, or bending loads to specimens, typically achieving force capacities from one kilonewton to several meganewtons with crosshead displacement resolution down to sub-micron levels. These systems determine yield strength, ultimate tensile strength, elongation, and modulus of elasticity for metals, polymers, composites, and ceramics destined for safety-critical applications. Electromechanical systems now lead product type demand due to energy efficiency and precision advantages in sub-500 kN ranges, while servo-hydraulic configurations retain structural dominance in high-force fatigue and fracture mechanics testing for wind turbine blades and rail components. Digital technology adoption concentrates margin pools in software-integrated platforms offering real-time data acquisition and cloud-connected analytics, displacing analog and manual control architectures in developed markets.
FAA airworthiness directives and EU MDR material traceability mandates compel aerospace and medical device manufacturers to maintain calibrated, auditable testing records across production batches. ASTM E8, ISO 6892, and JIS Z 2241 standards govern test methodology, creating compliance barriers for equipment lacking multi-standard protocol libraries. China's SAMR and GB standard harmonization programs are accelerating domestic substitution of imported testing platforms in state-funded infrastructure projects. Stakeholders must evaluate whether regional certification reciprocity agreements will fragment equipment specification requirements or consolidate demand around transnational standard convergence.
Market Dynamics
Electromechanical platforms are displacing servo-hydraulic systems across sub-500 kN force ranges, compressing validation timelines for carbon-fiber-reinforced polymer airframes while tightening margin pools on legacy equipment.
Growth Catalysts
- EU MDR material traceability mandates:Medical device manufacturers must maintain calibrated, auditable testing records across production batches, forcing equipment upgrades at contract manufacturers in Germany and Switzerland.
- China's eastern industrial corridor:Domestic testing standards converging with ISO and ASTM benchmarks are accelerating state-funded infrastructure procurement of multi-standard protocol libraries.
- Wind turbine blade fatigue validation:Gigawatt-scale offshore installations in Denmark and the United States require high-force servo-hydraulic configurations for 20-year lifecycle certification.
Market Restraints
- Force transducer supply concentration:Precision load cell manufacturing clusters in Germany and Japan create single-source vulnerabilities for electromechanical system integrators.
- ASTM/ISO/JIS multi-standard compliance costs:Equipment lacking native protocol libraries faces exclusion from aerospace OEM validation labs in the United States and France.
- Manual control architecture obsolescence:Analog systems in university research consortia face accelerated depreciation as cloud-connected analytics become baseline requirements.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating first-mover advantages for testing equipment vendors establishing calibration centers in Maharashtra and Karnataka.
- Real-time data acquisition convergence:Edge computing integration with electromechanical crosshead controllers is enabling predictive maintenance contracts at automotive OEM validation facilities.
- Japan's METI carbon-neutral materials roadmap:Bio-based polymer certification protocols are opening specialized testing workflows for tensile modulus characterization of cellulose-reinforced compounds.
Industry Challenges
- Crosshead displacement calibration expertise:Sub-micron resolution maintenance requires specialized metrology technicians scarce in emerging manufacturing clusters.
- FAA airworthiness directive compliance timelines:Aerospace suppliers face 18-24 month certification cycles for new testing protocols, compressing equipment procurement windows.
- Legacy hydraulic system integration:Retrofitting existing fatigue testing rigs with digital data acquisition architectures demands custom engineering without standardized interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Testing Machine Market |
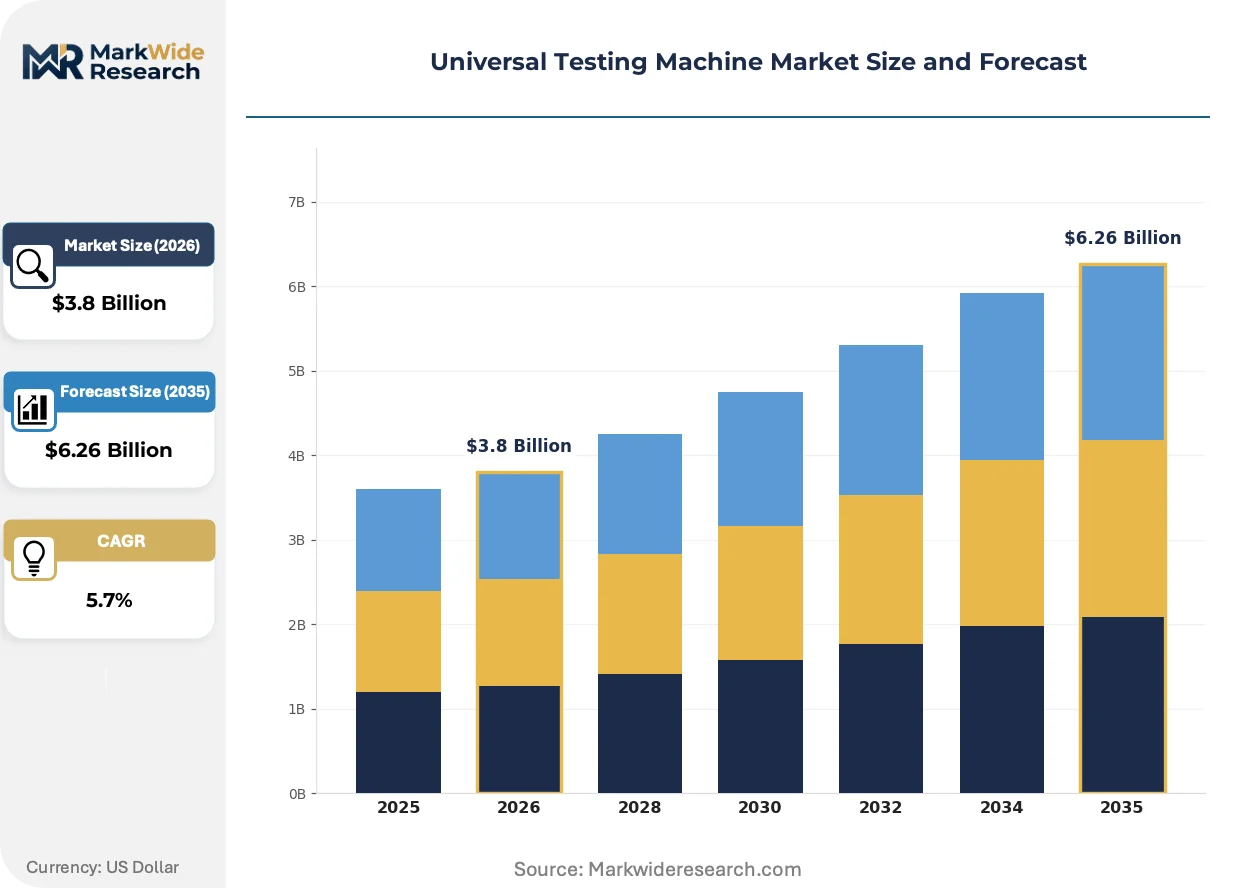
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Hydraulic, Servo-hydraulic, Pneumatic Application: Material Testing, Component Testing, Endurance Testing, Fatigue Testing End User: Aerospace, Automotive, Construction, Education Technology: Digital, Analog, Computerized, Manual |
| Companies Covered | AMETEK Inc., Tinius Olsen Ltd., Illinois Tool Works Inc., Instron, Hegewald & Peschke Meß- und Prüftechnik GmbH, ZwickRoell GmbH & Co. KG, MTS Systems Corporation, ADMET Inc., Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Testing Machine Market Strategic Shifts
Digital thread architectures are rewiring how validation data flows from specimen testing through regulatory submission, collapsing the latency between physical measurement and certification documentation.
Cloud-native testing platforms are converging with electromechanical hardware to enable distributed access to raw load-displacement curves. Automotive OEMs in Germany and the United States are piloting browser-based test control interfaces that eliminate local software licensing dependencies. This architecture is compressing IT infrastructure costs at multi-site manufacturing networks while complicating cybersecurity compliance for ITAR-controlled aerospace workflows.
FAA certification protocol updates are tightening force measurement uncertainty budgets for composite airframe validation. Suppliers to Boeing and Airbus must now demonstrate NIST-traceable calibration chains with documented environmental conditioning histories. The affected segment—tier-two aerospace component manufacturers—is responding by consolidating testing volumes at third-party accredited laboratories rather than maintaining captive equipment.
After-sales service unbundling is fragmenting long-term equipment relationships. University research consortia in the United Kingdom and Australia are shifting from comprehensive maintenance contracts toward pay-per-incident technical support paired with remote diagnostics subscriptions. This pattern concentrates most visibly in materials science departments where capital equipment refresh cycles exceed seven years and in-house technician staffing has declined.
Universal Testing Machine Market Segmentation
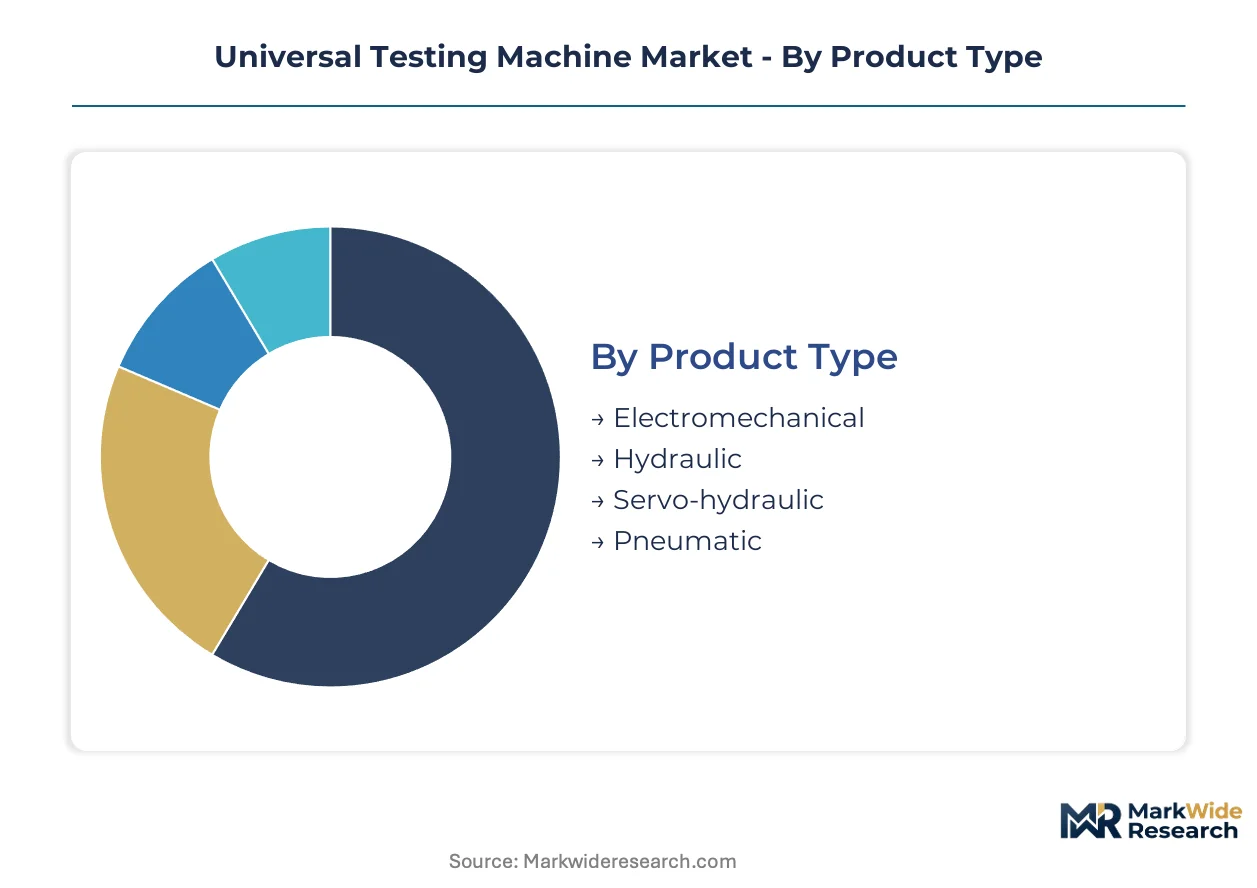
Testing equipment procurement patterns diverge sharply across force ranges, control architectures, and compliance regimes. Segment boundaries determine margin capture, with electromechanical platforms commanding premium pricing in aerospace validation while hydraulic systems retain structural dominance in fatigue applications.
Product Type:
Force generation mechanisms define precision characteristics, energy consumption profiles, and maintenance intervals across installation bases.
- Electromechanical:Ball-screw and linear motor drives achieve sub-micron displacement resolution with energy efficiency advantages in sub-500 kN ranges. Demand concentrates in Germany and the United States for composite airframe validation, driven by FAA certification protocol updates tightening measurement uncertainty budgets.
- Servo-hydraulic:Closed-loop hydraulic actuation delivers sustained high-force cycling essential for 20-year wind turbine blade fatigue certification. Procurement clusters in Denmark and offshore wind corridors where gigawatt-scale installations require lifecycle validation beyond electromechanical force limits.
- Hydraulic:Open-loop hydraulic systems serve legacy installations in rail component testing with lower precision requirements but higher force capacity needs.
- Pneumatic:Compressed air-driven systems occupy niche applications in textile and packaging material testing where rapid cycling at low forces suffices.
Mature deployment sits with servo-hydraulic configurations in heavy industry fatigue labs. Newer deployment is concentrated in electromechanical platforms displacing legacy hydraulic capacity in aerospace and automotive OEM validation facilities.
Application:
Test methodology selection tracks material criticality and regulatory exposure, with aerospace and medical device manufacturers facing the most stringent documentation requirements.
- Material Testing:Tensile, compressive, and bending characterization of metals, polymers, and composites determines yield strength and modulus of elasticity for safety-critical structures. Demand concentrates in China's eastern industrial corridor where SAMR standard harmonization accelerates multi-standard protocol library procurement.
- Fatigue Testing:Cyclic loading protocols validate 20-year structural lifecycles for wind turbine blades and rail components. Germany and Denmark anchor procurement of high-force servo-hydraulic configurations for offshore wind certification.
- Component Testing:Sub-assembly validation for automotive suspension systems and medical device structural elements requires force capacities between material-level and full-system testing.
- Endurance Testing:Sustained load maintenance protocols serve civil engineering applications including bridge cable and building anchor validation.
Procurement volume concentrates in material testing for production batch release. Margin expansion is accelerating fastest in fatigue testing where lifecycle certification mandates extend contract durations.
End User:
Customer archetypes exhibit divergent procurement rhythms, with aerospace and automotive OEMs consolidating testing volumes while education and construction segments fragment across smaller installations.
- Aerospace:Tier-two component manufacturers face 18-24 month FAA certification cycles for new testing protocols, compressing equipment procurement windows and consolidating volumes at third-party accredited laboratories.
- Automotive:OEM validation labs in Germany and the United States pilot cloud-native testing platforms with browser-based control interfaces, eliminating local software licensing dependencies.
- Construction:Infrastructure project contractors in China procure electromechanical systems for rebar and concrete validation against converging GB and ISO benchmarks.
- Education:University research consortia in the United Kingdom and Australia shift from comprehensive maintenance contracts toward pay-per-incident technical support paired with remote diagnostics subscriptions.
Capital intensity peaks in aerospace where NIST-traceable calibration chains are mandatory. Deployment breadth is expanding most quickly in education segments adopting subscription-based service models.
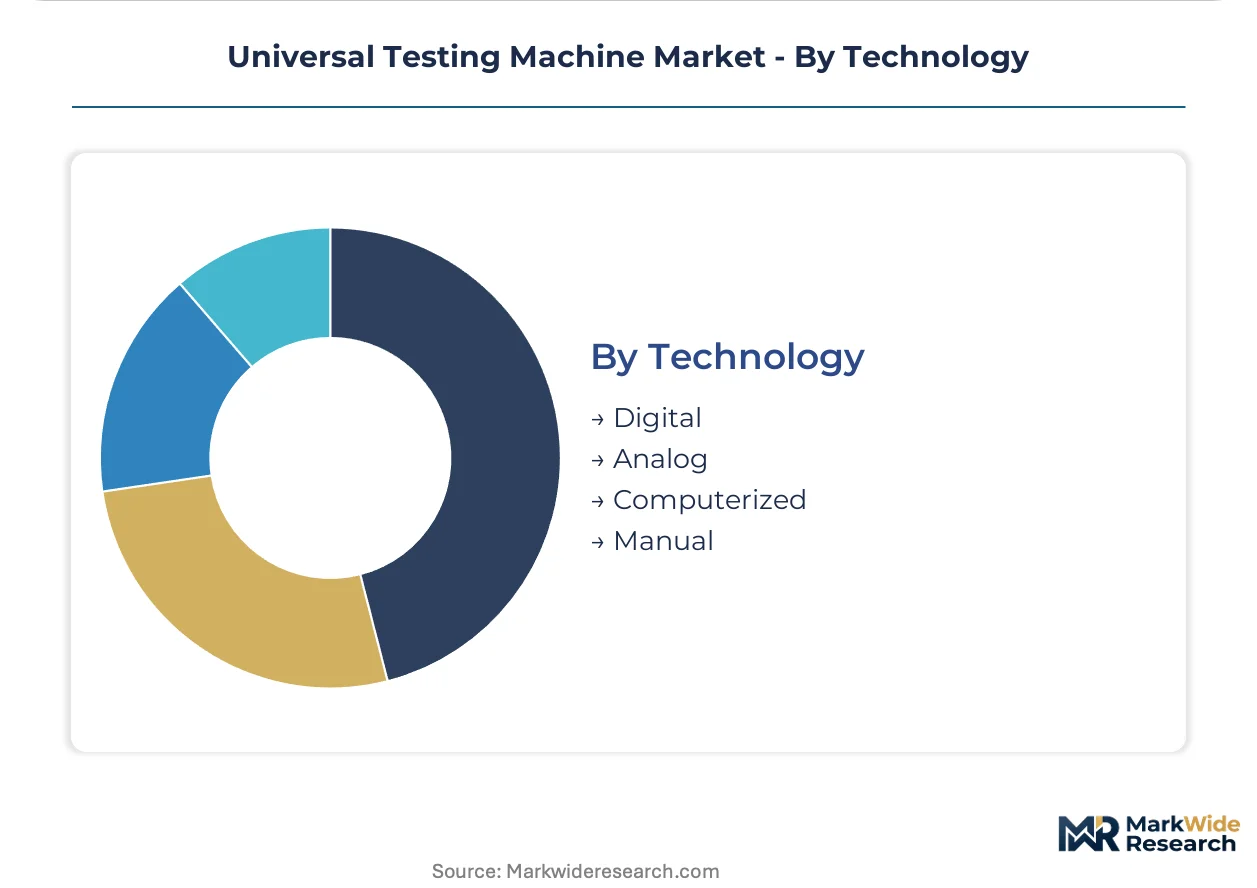
Technology:
Control architecture selection determines data integrity, audit trail completeness, and cybersecurity exposure across regulated industries.
- Digital:Real-time data acquisition with cloud-connected analytics enables predictive maintenance contracts at automotive OEM validation facilities. EU MDR and FAA mandates compel medical device and aerospace manufacturers to maintain calibrated, auditable testing records.
- Computerized:PC-integrated control systems with multi-standard protocol libraries (ASTM E8, ISO 6892, JIS Z 2241) face exclusion barriers from aerospace OEM validation labs lacking native compliance.
- Analog:Legacy voltage-based control architectures face accelerated depreciation as cloud-connected analytics become baseline requirements in developed markets.
- Manual:Hand-cranked systems with mechanical load indicators persist in emerging market education segments with limited capital budgets and technician availability.
Regulatory compliance is forcing displacement of analog and manual architectures. Digital platforms are gaining share fastest where ITAR-controlled aerospace workflows permit cloud connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern industrial corridor functions as the dominant tax-incentive zone, concentrating state-funded procurement of multi-standard testing platforms where GB benchmarks converge with ISO and ASTM protocols.
United States
FAA airworthiness directives and Boeing-Airbus supplier mandates drive electromechanical platform demand for composite airframe validation. NIST-traceable calibration chains are mandatory for tier-two aerospace component manufacturers. Wichita, Kansas and Seattle-Tacoma anchor procurement clusters where third-party accredited laboratories consolidate testing volumes.
Germany
EU MDR material traceability requirements force equipment upgrades at medical device contract manufacturers in Baden-Württemberg. The country's national aerospace regulator enforces stringent measurement uncertainty budgets for structural component certification. Munich-Stuttgart industrial corridor dominates European aerospace certification workflows.
China
SAMR standard harmonization programs accelerate domestic substitution of imported testing platforms in state-funded infrastructure projects. GB standard convergence with ISO benchmarks enables multi-standard protocol library procurement. Yangtze River Delta manufacturing clusters drive demand for electromechanical systems in rebar and concrete validation.
Japan
METI carbon-neutral materials roadmap opens specialized testing workflows for bio-based polymer certification. JIS Z 2241 standards govern test methodology, creating compliance barriers for equipment lacking native protocol libraries. Nagoya-Osaka industrial belt concentrates fatigue testing demand for automotive and rail component validation.
India
PLI scheme for medical devices creates first-mover advantages for vendors establishing calibration centers. CDSCO alignment with international medical device standards accelerates testing equipment procurement. Maharashtra and Karnataka industrial corridors attract domestic manufacturing investments with tax incentives.
Universal Testing Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with electromechanical platform vendors capturing premium pricing in aerospace validation while hydraulic system integrators retain structural dominance in fatigue applications. The vendor base organizes around three strategic archetypes: German precision-engineering houses, North American integrated testing conglomerates, and Asian electronics-focused manufacturers. Competitive moves concentrate on geographic expansion through calibration center establishment and technology licensing partnerships for digital thread architectures.
Within the precision-engineering tier, ZwickRoell GmbH & Co. KG and Hegewald & Peschke Meß- und Prüftechnik GmbH exemplify German manufacturing-base dominance in European aerospace certification workflows. MTS Systems Corporation occupies a position among North American integrated testing providers serving automotive OEM validation labs. Illinois Tool Works Inc. sits within the conglomerate archetype, with its Instron division representing dual-column electromechanical range penetration across university research consortia.
| Leading Market Players |
|---|
| AMETEK Inc. |
| Tinius Olsen Ltd. |
| Illinois Tool Works Inc. |
| Instron |
| Hegewald & Peschke Meß- und Prüftechnik GmbH |
| ZwickRoell GmbH & Co. KG |
| MTS Systems Corporation |
| ADMET Inc. |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
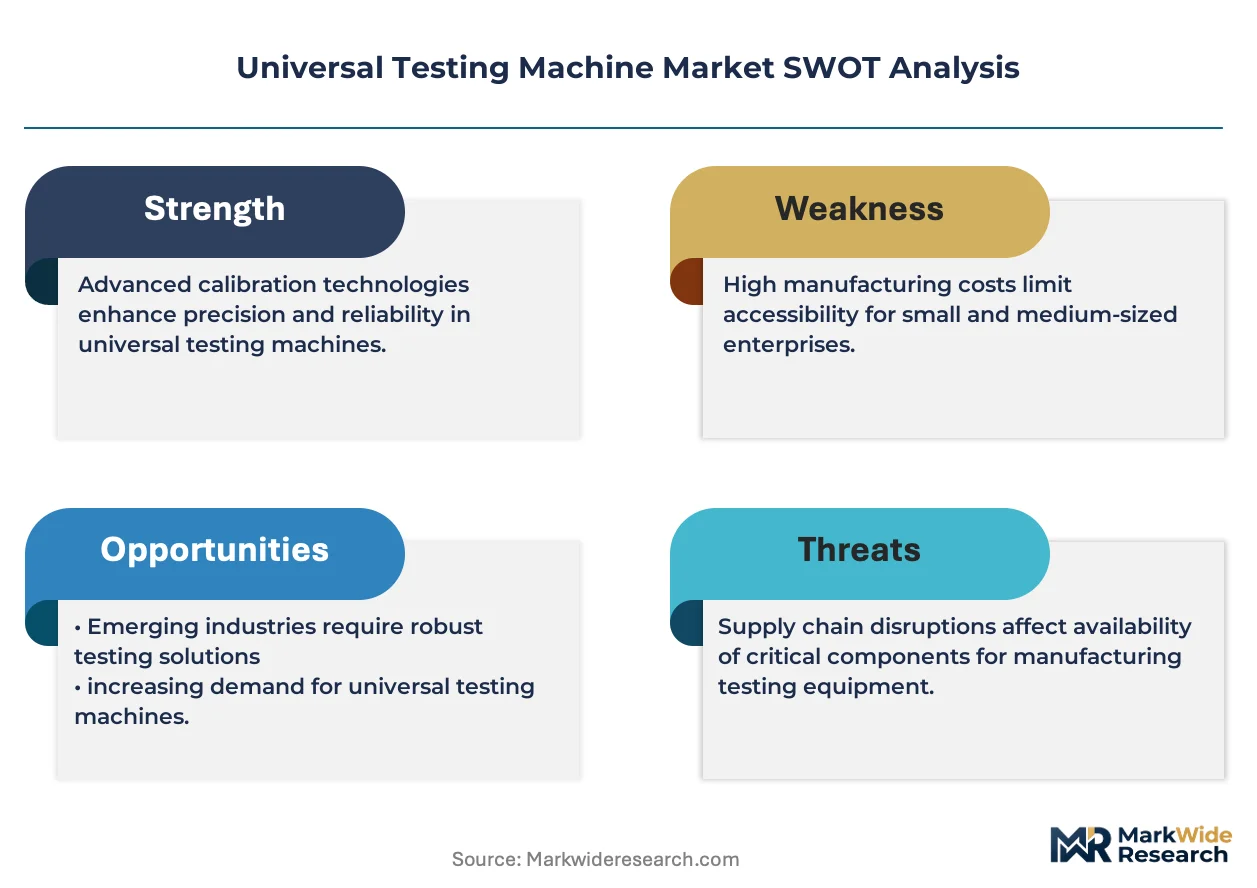
Electromechanical platform adoption is compressing legacy hydraulic equipment margins while concentrating procurement power among aerospace OEMs demanding NIST-traceable calibration chains. This technology transition simultaneously elevates precision-component costs and fragments supplier pricing power across German and Japanese force transducer clusters.
Pricing Analysis
Volume concentrates in mid-range electromechanical systems while margin pools accrue to premium aerospace-grade platforms with multi-standard protocol libraries. Pricing stratifies across certification-grade, standard, and education-tier equipment levels, with EU MDR and FAA mandates driving premium-tier cost inflation. Price erosion runs through manual-control architectures facing accelerated depreciation as cloud-connected analytics become baseline requirements. University research consortia exhibit highest price sensitivity, while tier-two aerospace suppliers show lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with precision load cell manufacturing clusters in Germany and Japan, creating bottlenecks for electromechanical system integrators. Component sourcing draws from Taiwanese electronics, German precision machining, and Chinese structural fabrication. Supply chain risk centers on tariff exposure for force transducers crossing multiple regulatory jurisdictions. Distribution runs through OEM-direct channels for aerospace validation labs and regional distributor networks for education and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over calibration center networks and force transducer supply determines margin capture. Players are pursuing backward integration into precision load cell manufacturing to defend pricing power.
For Market Incumbents: Acquire calibration center networks in Maharashtra and Karnataka to preempt India's PLI-driven medical device manufacturing expansion. Consolidate third-party laboratory relationships in Wichita and Seattle-Tacoma to capture tier-two aerospace testing volume migration. Defend against emerging Asian electronics-focused manufacturers by embedding NIST-traceable calibration chains as non-negotiable procurement requirements. For New Entrants and Emerging Players: Edge computing integration with electromechanical controllers offers a technology-first wedge into automotive OEM predictive maintenance contracts. Target China's Yangtze River Delta infrastructure contractors with GB-standard compliant electromechanical systems priced below German imports. Penetrate through browser-based test control interfaces that eliminate legacy software licensing dependencies. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated testing conglomerates seeking geographic expansion. Long-term viability favors vendors with captive force transducer supply and multi-standard protocol libraries. Acquisition target archetype: German precision-engineering houses with established aerospace certification workflows. Watch for FAA certification protocol updates as inflection indicators accelerating equipment refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Center Establishment | Captures recurring service revenue from EU MDR-mandated audit trails in Germany and Switzerland. |
| Backward Integration into Load Cells | Reduces single-source vulnerability to German and Japanese precision component suppliers. |
| Cloud-Native Platform Development | Enables browser-based interfaces eliminating local software licensing at automotive OEM labs. |
| Multi-Standard Protocol Licensing | Secures exclusion barriers against equipment lacking native ASTM E8, ISO 6892, or JIS Z 2241 compliance. |
| Regional Manufacturing Footprint | Qualifies vendors for China's state-funded infrastructure procurement under SAMR harmonization programs. |
Study Parameters
Multi-period observation of equipment procurement volumes, certification protocol updates, and force transducer supply constraints anchored the trend analysis, supplemented by interviews with validation lab directors, aerospace tier-two component manufacturers, and medical device contract manufacturers. Secondary validation drew from FAA airworthiness directive filings, SAMR standard harmonization announcements, SEC 10-K equipment expenditure disclosures, and customs data on testing machinery imports. Bottom-up triangulation across end-user segments converged with top-down market sizing.
Segment-weighting approaches applied differential growth assumptions across electromechanical and servo-hydraulic product types, material testing and fatigue testing applications, and aerospace versus education end-user archetypes. CAGRs were derived through regression analysis of historical procurement patterns and forward projection of regulatory mandate timelines. Industry-specific forecast inputs included EU MDR implementation phases and China's GB standard convergence milestones.
Several conditions sit outside the modeled scope, including unannounced FAA certification protocol revisions and geopolitical disruptions to German-Japanese force transducer trade flows. Forecasts reflect documented assumptions about regulatory enforcement intensity and standard harmonization velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Density Tester Market
Test and Measurement
Crock Meter Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
PXI SMU Market
Test and Measurement
EMC Testing Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Temperature Humidity Chambers Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Continuous Friction Tester Market