
 Modular Plating System Market | 2026-2036
Modular Plating System Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Plating System Market Foresight
Market Context
German automation suppliers is pivoting toward scalable plating module architectures for electric vehicle powertrain components. Schunk GmbH & Co. KG leverages its gripper and automation portfolio to integrate plating cells into turnkey manufacturing lines. SMC Corporation sustains pneumatic and electric actuator supply chains that feed modular tank positioning systems across Asian job shops. Festo AG & Co. KG differentiates through fluid handling modules that reduce chemical waste in barrel plating configurations.
Technical Definition and Structural Segments
A modular plating system comprises interchangeable process cells—typically tank, rack, barrel, or continuous configurations—engineered to specific substrate dimensions and electrolyte chemistries, with standardized interfaces for power supply, fluid circulation, and automated workpiece transfer. These systems enable manufacturers to reconfigure production lines for batch sizes ranging from prototype jewelry runs to high-volume automotive fastener coating without full line replacement. Tank plating dominates capital deployment due to its flexibility across aerospace turbine blade and semiconductor wafer applications, while continuous plating architectures capture margin pools in strip steel and wire processing for electronics connectors. Electroplating technology leads unit shipments, though electroless plating grows fastest in medical device and electronics verticals demanding uniform coating thickness on complex geometries.
Regulatory Frame and Outlook
EPA effluent guidelines and OSHA hexavalent chromium exposure limits shape equipment specifications in North American job shops, while REACH and RoHS compliance in Europe mandates substitution tracking for restricted plating chemistries. China's MEE enforces wastewater discharge standards that accelerate adoption of closed-loop rinse recovery modules in Guangdong and Jiangsu manufacturing clusters. Stakeholders must monitor evolving PFAS restrictions and nickel compound classifications across multiple jurisdictions to anticipate retrofit cycles and chemistry reformulation timelines.
Market Dynamics
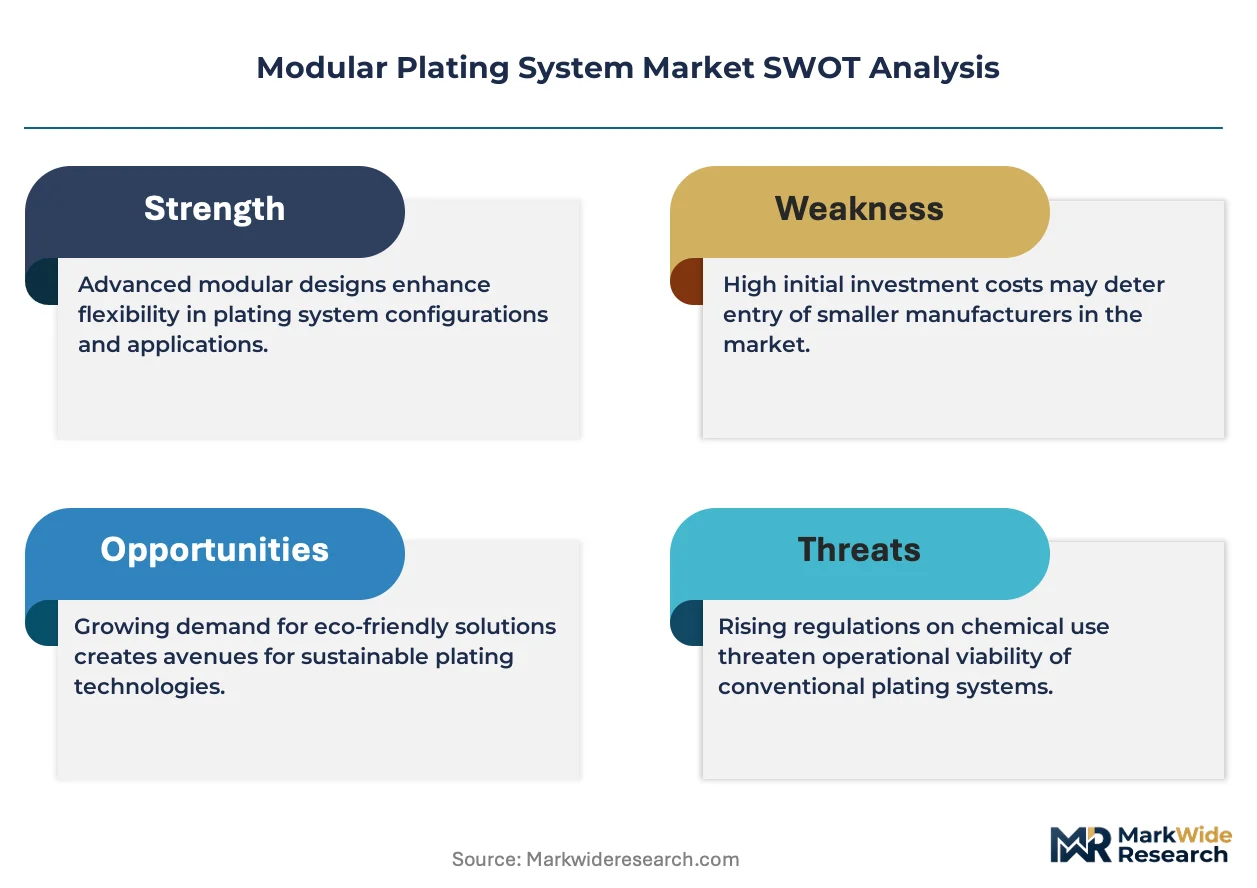
Closed-loop electroplating architectures are redirecting capital flows as REACH compliance and China's GB standards tighten hazardous substance limits, forcing equipment buyers to prioritize chemistry recovery and wastewater elimination over throughput metrics alone.
Growth Catalysts
- EV Powertrain Expansion:Automotive OEMs in Germany and Japan are scaling modular plating capacity for lightweight component finishing, creating dedicated demand for reconfigurable tank systems.
- Electronics Manufacturing Corridors:Precision electronics clusters spanning South Korea, Taiwan, and Malaysia concentrate demand for high-uniformity barrel and rack configurations.
- Closed-Loop Mandates:China's MEE wastewater discharge standards are accelerating retrofit cycles in Guangdong and Jiangsu manufacturing clusters.
Market Restraints
- Specialized Input Concentration:High-purity electrolyte chemistries and proprietary anode formulations concentrate supply among German and Japanese specialty chemical houses.
- Hexavalent Chromium Substitution Friction:OSHA exposure limits and REACH authorization requirements force costly chemistry reformulation without drop-in alternatives for hard chrome applications.
- PFAS Regulatory Uncertainty:Evolving restrictions on fluorinated surfactants in plating baths create formulation risk across multiple jurisdictions.
Strategic Opportunities
- Medical Device Vertical:Electroless plating demand accelerates for implantable components requiring uniform thickness on complex geometries.
- Semiconductor Wafer Processing:Tank plating flexibility enables rapid reconfiguration between prototype and volume production for advanced packaging substrates.
- Job Shop Automation:Pneumatic and electric actuator integration from Asian suppliers reduces manual handling in batch operations.
Industry Challenges
- Electrolyte Chemistry Expertise Gap:Formulation specialists capable of optimizing closed-loop chemistries for specific substrate alloys remain scarce in North American and European labor pools.
- Legacy System Integration:Retrofitting rinse recovery modules into existing tank lines requires custom plumbing and control architecture without standardized interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Plating System Market |
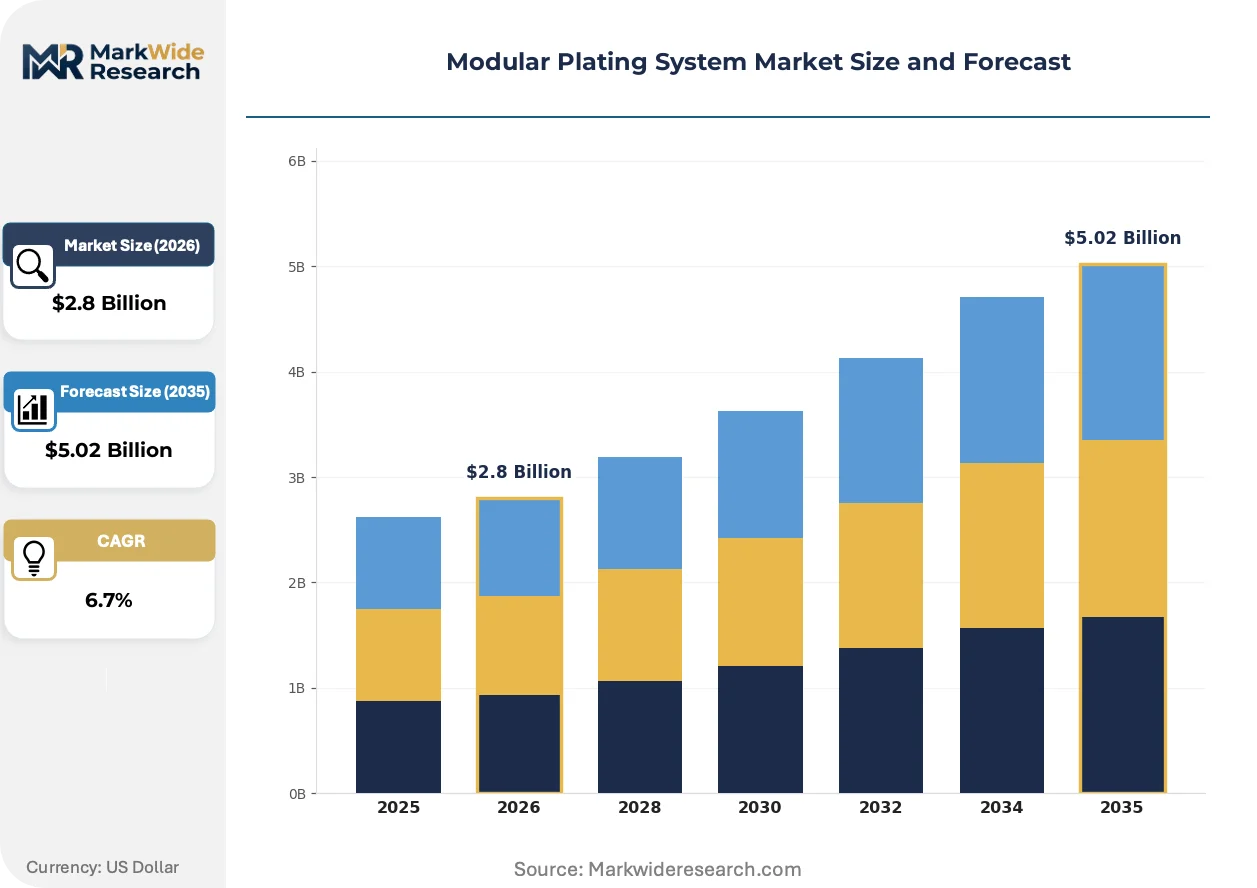
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tank Plating, Rack Plating, Barrel Plating, Continuous Plating Technology: Electroplating, Electroless Plating, Anodizing, Chemical Plating Application: Aerospace, Automotive Parts, Electronics, Jewelry End User: Manufacturers, OEMs, Job Shops, Repair Services |
| Companies Covered | Schunk GmbH & Co. KG, Zimmer Group, SMC Corporation, Festo AG & Co. KG, Thomson Industries, Inc., Parker Hannifin Corporation, Hiwin Technologies Corp., Stryker, OsteoMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Plating System Market Shifts & Advancements
Digital process control and chemistry monitoring systems are compressing batch-to-batch variation while enabling predictive maintenance, fundamentally altering how plating operations staff and scale production cells.
Artificial intelligence-driven bath analysis is modularizing quality assurance workflows in high-mix job shops. Automotive fastener suppliers in Germany adopt machine-vision-equipped cells that auto-adjust current density based on real-time thickness feedback. This capability collapses setup times between alloy specifications without dedicated technician intervention.
REACH substance restrictions and RoHS compliance mandates are forcing chemistry disclosure through entire supply chains. European aerospace contractors now require plating subcontractors to document electrolyte composition down to ppm thresholds. Equipment vendors respond with sealed-cell architectures that prevent operator exposure and enable automated chemistry replenishment.
Service contracting is displacing capital purchase for mid-volume manufacturers. Taiwanese electronics assemblers increasingly lease plating capacity with guaranteed thickness specifications rather than owning tank lines. This shift transfers process risk to equipment providers while locking in chemistry supply agreements.
Modular Plating System Market Segmentation
Modular plating system buyers configure process cells around substrate geometry, batch volume, and chemistry constraints. Segment selection dictates automation architecture, regulatory compliance burden, and total cost of ownership across multi-year production cycles.
Product Type:
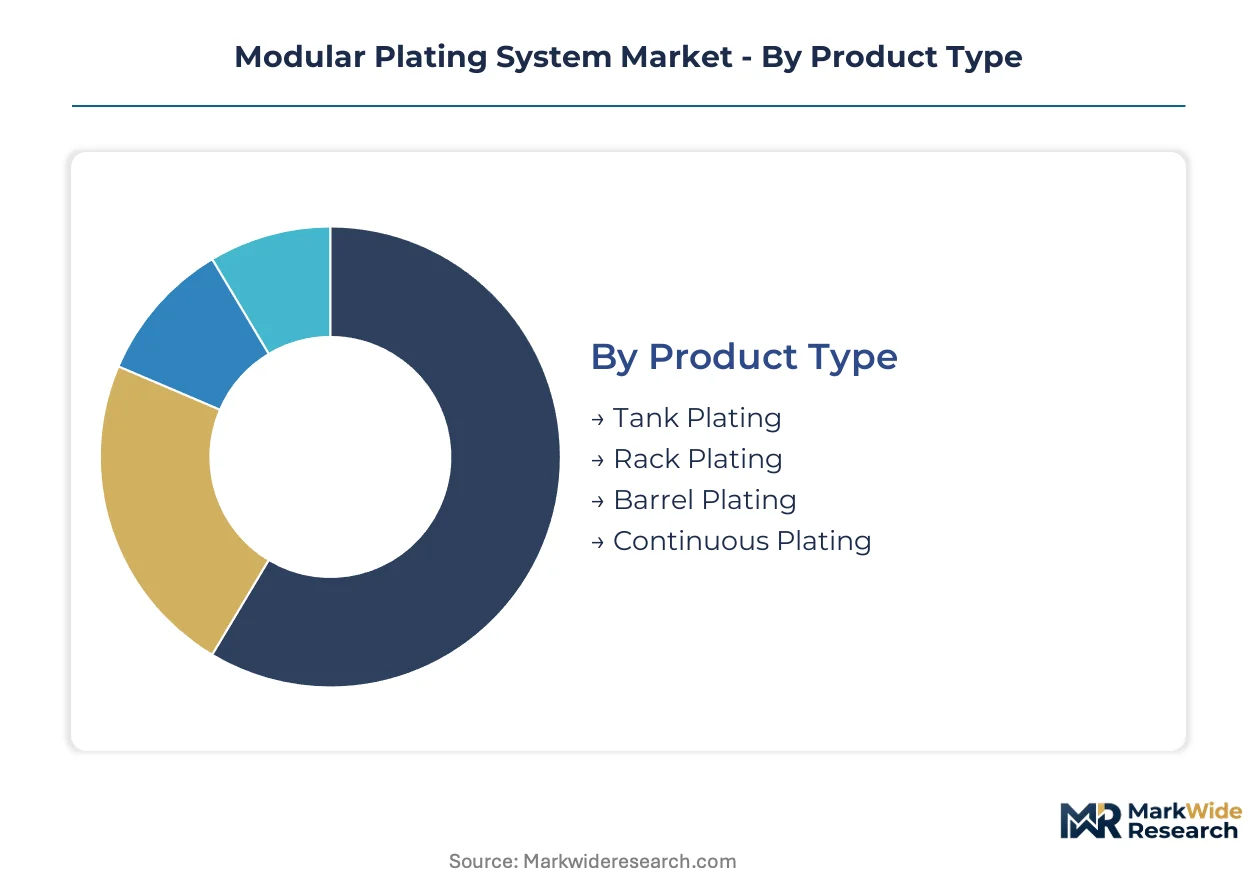
Tank plating demands the highest upfront capital outlay due to electrolyte containment infrastructure and power supply scaling, while continuous plating spreads fixed costs across extended throughput runs.
- Tank Plating:Individual immersion cells accommodate aerospace turbine blades and semiconductor wafers with flexible electrolyte volumes. German automotive OEMs deploy reconfigurable tank arrays for EV powertrain component finishing where batch specifications shift quarterly.
- Continuous Plating:Strip steel and wire processing architectures minimize handling labor through automated feed systems. Electronics connector manufacturers in Taiwan favor continuous lines for high-volume copper-nickel-gold deposition on precision stampings.
- Rack Plating:Fixture-mounted workpiece handling suits complex geometries requiring selective coating.
- Barrel Plating:Rotating drum configurations process small fasteners and jewelry components in bulk.
Tank plating absorbs the bulk of installed capacity; continuous plating is expanding most quickly.
Technology:
Process chemistry selection hinges on substrate conductivity, uniformity requirements, and hazardous substance restrictions that vary by end-use jurisdiction.
- Electroplating:External DC power drives metal ion reduction onto conductive substrates with precise thickness control. REACH hexavalent chromium authorization pressures European job shops toward trivalent alternatives for hard chrome applications.
- Electroless Plating:Autocatalytic reduction deposits uniform coatings on non-conductive and complex geometries without external current. Medical device manufacturers specify electroless nickel-phosphorus for implantable components requiring biocompatibility certification.
- Anodizing:Electrochemical oxide growth enhances aluminum wear resistance and dye absorption.
- Chemical Plating:Immersion displacement processes deposit sacrificial layers without electrical infrastructure.
Electroplating retains dominant share in capital deployment; electroless plating climbs the fastest on medical and electronics demand.
Application:
End-use verticals impose divergent certification standards that filter equipment specifications through aerospace NADCAP accreditation, automotive IATF compliance, and electronics IPC criteria.
- Automotive Parts:Fastener, connector, and powertrain component finishing requires high-throughput barrel and rack configurations. Japanese OEMs in Aichi Prefecture source modular tank systems enabling rapid reconfiguration between zinc-nickel and zinc-iron alloy specifications.
- Electronics:Semiconductor packaging substrates and connector plating demand sub-micron thickness uniformity. South Korean memory manufacturers in Gyeonggi Province specify closed-loop rinse recovery to meet MEE wastewater standards for new facility permits.
- Aerospace:Turbine blade and landing gear coatings require NADCAP-accredited process control documentation.
- Jewelry:Precious metal deposition for decorative and investment pieces favors small-batch tank flexibility.
Automotive applications anchor equipment revenue; electronics verticals show steepest expansion trajectory.
End User:
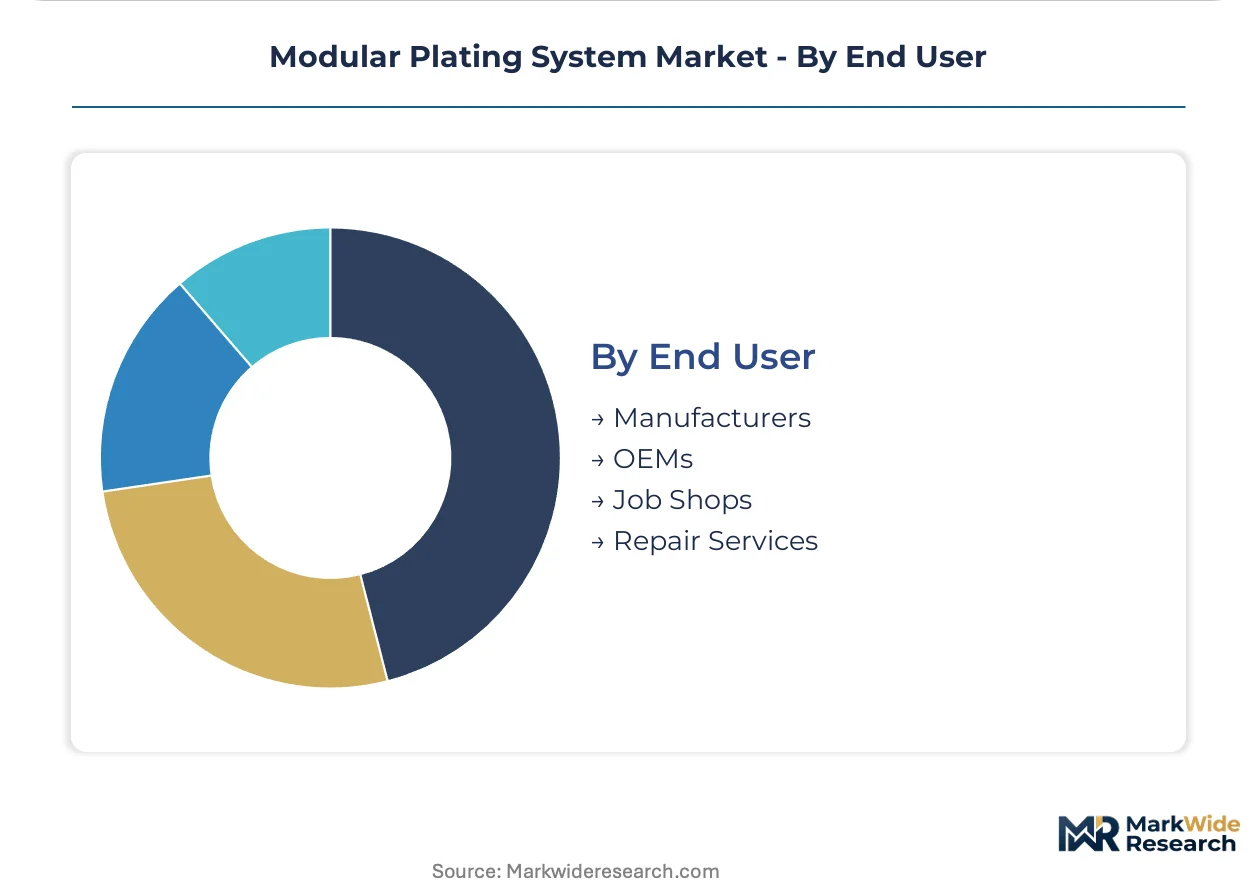
Customer scale and in-house technical capability determine whether buyers prefer turnkey integration or component-level procurement with self-assembly.
- Job Shops:Independent plating service providers prioritize reconfigurable cells accommodating diverse customer specifications. Malaysian electronics corridors concentrate job shop demand for barrel systems processing mixed alloy fasteners.
- OEMs:Captive plating operations integrate modular cells into vertically controlled manufacturing lines. German automotive groups specify automated workpiece transfer from Schunk gripper systems to minimize labor exposure.
- Manufacturers:Mid-volume producers balance in-house capacity against subcontracting economics.
- Repair Services:Maintenance and refurbishment operations require portable or compact plating modules.
Job shops represent the largest installed base; OEM captive operations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrolyte formulation expertise and Japanese precision automation anchor the geographic distribution of modular plating system demand. Equipment procurement concentrates in manufacturing corridors where automotive electrification and electronics packaging drive capital deployment.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg scale reconfigurable tank systems for EV powertrain component finishing. REACH authorization requirements for hexavalent chromium redirect investment toward trivalent chemistry infrastructure. Aichi Prefecture supply relationships extend into German automation integration partnerships.
China
GB standards for hazardous substance limits and MEE wastewater discharge rules accelerate closed-loop rinse recovery module adoption. Guangdong and Jiangsu manufacturing clusters retrofit existing tank lines to meet permit requirements for new semiconductor packaging facilities.
Japan
Precision electronics manufacturers in Tokyo and Osaka prefectures demand high-uniformity barrel configurations for connector plating. METI industrial standards shape equipment specifications for medical device electroless nickel-phosphorus applications. Nagoya automotive suppliers integrate modular cells into vertically controlled fastener production.
South Korea
Memory semiconductor packaging substrates in Gyeonggi Province require sub-micron thickness uniformity from tank plating architectures. MFDS biocompatibility certification drives electroless plating investment for implantable medical components. Busan-Ulsan manufacturing corridors concentrate job shop demand for mixed alloy processing.
United States
EPA effluent guidelines and OSHA hexavalent chromium exposure limits shape equipment specifications in Midwest automotive job shops. Michigan and Ohio plating service providers prioritize retrofit compatibility over greenfield capacity. Aerospace contractors in California and Washington state mandate NADCAP-accredited process control documentation.
Modular Plating System Market Competitive Landscape
Global majors compete with regional champions across automation integration and chemistry handling specialization. The vendor base stratifies between turnkey system integrators and component-level suppliers of actuators, grippers, and fluid handling modules. Three archetypes dominate: German automation houses with gripper-to-tank integration capabilities, Japanese pneumatic specialists feeding Asian job shop supply chains, and diversified motion control conglomerates spanning multiple industrial verticals. Competitive positioning hardens through strategic partnerships between equipment vendors and specialty chemical formulators, plus geographic expansion into electronics manufacturing corridors.
Within the German automation tier, Schunk GmbH & Co. KG and Festo AG & Co. KG occupy positions anchored in gripper integration and fluid handling modules respectively. SMC Corporation exemplifies the Asian pneumatic specialist archetype supplying actuator infrastructure across regional job shop networks. These three entities represent distinct competitive vectors: turnkey manufacturing line integration, chemistry waste reduction engineering, and distributed component supply chain density.
| Leading Market Players |
|---|
| Schunk GmbH & Co. KG |
| Zimmer Group |
| SMC Corporation |
| Festo AG & Co. KG |
| Thomson Industries, Inc. |
| Parker Hannifin Corporation |
| Hiwin Technologies Corp. |
| Stryker |
| OsteoMed |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between NADCAP-accredited aerospace systems and commodity job shop equipment manifests in both pricing premiums and supply chain sourcing strategies. Premium-tier vendors command substantial markups through bundled chemistry compliance documentation and warranty coverage, while standard configurations compete on equipment-only pricing with service contracts unbundled as optional add-ons.
Pricing Analysis
Warranty and service bundling separates premium-tier German automation integrators from Asian component suppliers competing on unbundled equipment-only pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and automation depth, with NADCAP-accredited aerospace systems commanding the widest margins. Cost compression in standard barrel configurations intensifies as Malaysian and Taiwanese job shops consolidate procurement volumes. OEM captive operations demonstrate lowest price sensitivity due to integration complexity, while independent job shops exhibit highest elasticity to equipment-only quotes.
Supply Chain Analysis
Certification and qualification gating concentrates high-purity electrolyte sourcing among German and Japanese specialty chemical houses. Equipment manufacturing draws from precision actuator supply chains in Japan, automation integration expertise in Germany, and tank fabrication capacity across China and South Korea. Single-source vulnerability in proprietary anode formulations creates exposure to reformulation timelines driven by REACH substance restrictions. Distribution runs through regional systems integrators serving automotive corridors in Bavaria, electronics clusters in Gyeonggi Province, and semiconductor packaging hubs in Taiwan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop electroplating architectures are displacing open-tank legacy systems as China's MEE wastewater standards and REACH authorization requirements tighten compliance windows. This technology-transition phase rewards vendors capable of chemistry recovery integration and automated process control.
For Market Incumbents: Acquire electrolyte formulation specialists capable of optimizing closed-loop chemistries for specific substrate alloys. Incumbents must defend against emerging Asian automation vendors by deepening captive supply of high-purity anode materials and securing NADCAP-accredited process documentation capabilities. Capacity addition in Jiangsu and Guangdong manufacturing clusters captures retrofit demand from existing tank line operators facing permit renewal deadlines. For New Entrants and Emerging Players: Mid-volume medical device manufacturers in South Korea represent an underserved buyer archetype requiring electroless nickel-phosphorus systems with MFDS biocompatibility certification. New entrants should target this segment through leasing-based service contracting models that transfer process risk from capital-constrained manufacturers. A go-to-market angle emphasizing guaranteed thickness specifications with automated chemistry replenishment addresses the expertise gap in North American and European labor pools. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified motion control conglomerates seeking vertical integration into surface finishing automation. Long-term viability hinges on chemistry-handling specialization rather than commodity tank fabrication, with the analysis window favoring vendors with sealed-cell architectures and digital process control capabilities. The signal to watch is accelerated PFAS restriction timelines that would force premature retrofit cycles and chemistry reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Formulation | Captive supply of high-purity chemistries insulates margin pressure from German and Japanese specialty houses. |
| Sealed-Cell Architecture Development | REACH-compliant designs prevent operator exposure and enable automated replenishment for aerospace contractors. |
| Leasing-Based Service Contracting | Taiwanese electronics assemblers increasingly prefer guaranteed specifications over capital ownership of tank lines. |
| Regional Manufacturing Footprint Expansion | Proximity to Guangdong and Jiangsu clusters accelerates retrofit installation timelines for MEE compliance deadlines. |
| Digital Process Control Integration | AI-driven bath analysis compresses batch-to-batch variation for high-mix German automotive fastener suppliers. |
Research Methodology
Independent corroboration across plating equipment OEMs, specialty chemical formulators, and automotive Tier 1 procurement teams underwrites the qualitative findings in this study. Primary interviews with plant engineers at Bavarian automotive facilities, technical R&D directors at electrolyte suppliers, and aftermarket service heads at Asian job shop networks combined with secondary validation from SEC filings, customs and trade data, and MEE wastewater discharge records. Bottom-up equipment shipment analysis and top-down capital expenditure triangulation anchored market sizing across the projection horizon.
Rate-of-change decomposition structured the analytical framework, modeling demand drivers separately for tank, continuous, rack, and barrel configurations across automotive, electronics, aerospace, and medical device verticals. CAGRs were derived from regression analysis of historical capital expenditure patterns and forward-looking regulatory compliance deadlines, with segmentation dimensions including process chemistry type, automation level, and regional manufacturing cluster. Industry-specific forecast inputs incorporated REACH authorization timelines for hexavalent chromium and China's dual carbon goals affecting industrial wastewater permitting.
Revisions become necessary when PFAS restriction timelines accelerate, nickel compound classifications shift across multiple jurisdictions, or semiconductor packaging substrate demand diverges from current trajectory assumptions. A model refresh is warranted upon material change in China's MEE enforcement intensity or German automotive electrification capex commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
IGBT Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Global Power MOSFET Market