
 Semiconductor Wafer Frame Market | 2026-2036
Semiconductor Wafer Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wafer Frame Market Insights
The capital-intensity divergence between integrated materials suppliers and assembly-focused component makers is unwinding competitive stability across the wafer frame supply base. Disco Corporation leverages vertical integration into precision dicing equipment to anchor premium positioning for its frame offerings. Entegris sustains technology leadership through advanced polymer formulations that dominate contamination-sensitive applications. Sumitomo Bakelite competes on thermal stability credentials in high-temperature backend processes.
A semiconductor wafer frame is a precision-engineered support ring, typically manufactured from aluminum, stainless steel, or engineered polymers with dimensional tolerances below 50 micrometers, designed to secure wafers during dicing, grinding, and transport operations. Metal frames retain structural rigidity for 300mm wafer handling in high-volume foundries, while plastic frames address cost-sensitive temporary bonding applications where chemical resistance outweighs mechanical load requirements. Foundries command the largest procurement volumes, though fabless companies are shifting toward captive packaging strategies that reshape frame specification workflows. Wafer processing applications absorb the majority of frame consumption, yet packaging lines represent the fastest-growing demand node as chiplet architectures proliferate.
REACH compliance in Europe, RoHS substance restrictions, and Japan's METI semiconductor materials guidelines collectively tighten material disclosure and recyclability mandates for frame producers. FDA oversight of medical-grade chip packaging indirectly elevates traceability standards that propagate upstream to frame suppliers. Semiconductor manufacturers must monitor how dual-use export controls from multiple jurisdictions reshape supply chain qualification timelines.
Market Dynamics
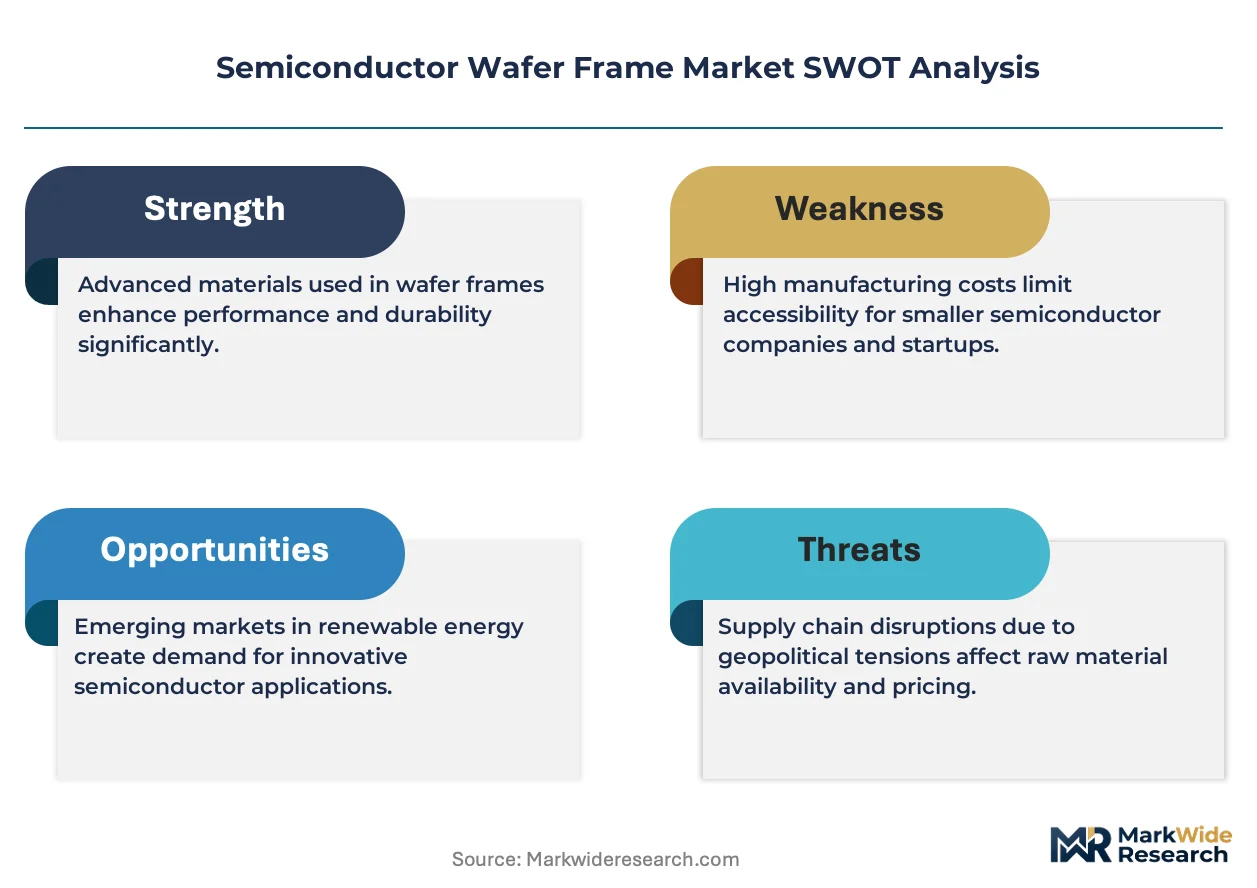
Advanced packaging architectures are compressing specification cycles for wafer frame suppliers as chiplet-based designs multiply dicing steps per finished device. Foundries now demand frames that survive sequential thermal cycling across hybrid bonding, temporary bonding, and debonding workflows without dimensional drift.
Growth Catalysts
- EU Chip Sovereignty:Localization mandates under the European Chips Act are qualifying regional frame suppliers for captive foundry supply chains, expanding procurement pools beyond incumbent Asian sources.
- 300mm Wafer Proliferation:Backend facilities in Taiwan and South Korea are retrofitting lines for larger wafer formats, driving replacement demand for frames with enhanced rigidity-to-weight ratios.
- Polymer Formulation Advances:Entegris and competitors are engineering thermoplastic variants that match aluminum thermal expansion coefficients, opening substitution pathways in cost-sensitive packaging tiers.
Market Restraints
- Aluminum Price Volatility:Metal frame producers face margin compression when London Metal Exchange aluminum spikes, with limited pass-through power against long-term foundry contracts.
- Taiwan Supply Concentration:Over 60% of precision machining capacity for high-tolerance metal frames sits within earthquake-exposed industrial zones, creating systemic disruption risk.
- Dimensional Tolerance Ceiling:Sub-20 micrometer flatness specifications for EUV-patterned wafers exceed current polymer frame capabilities, locking metal dominance in leading-edge nodes.
Strategic Opportunities
- India Semiconductor Mission:Micron's Gujarat assembly facility and Tata's planned fab are qualifying local frame suppliers under PLI-linked domestic content requirements.
- Medical Device Packaging:FDA traceability mandates for implantable chips are propagating upstream to frame vendors who can deliver lot-level material genealogy documentation.
- Hybrid Metal-Polymer Designs:Frames combining aluminum rings with polymer inserts are capturing interest from OSATs seeking to balance thermal performance against temporary bonding chemical resistance.
Industry Challenges
- Precision Machining Talent Scarcity:CNC operators capable of maintaining sub-50 micrometer tolerances across aluminum and stainless steel alloys command wage premiums that compress contract manufacturer margins.
- Dual-Use Export Control Complexity:BIS and METI licensing requirements for frames used in military-grade FPGA packaging are extending qualification timelines by 4-6 months for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wafer Frame Market |
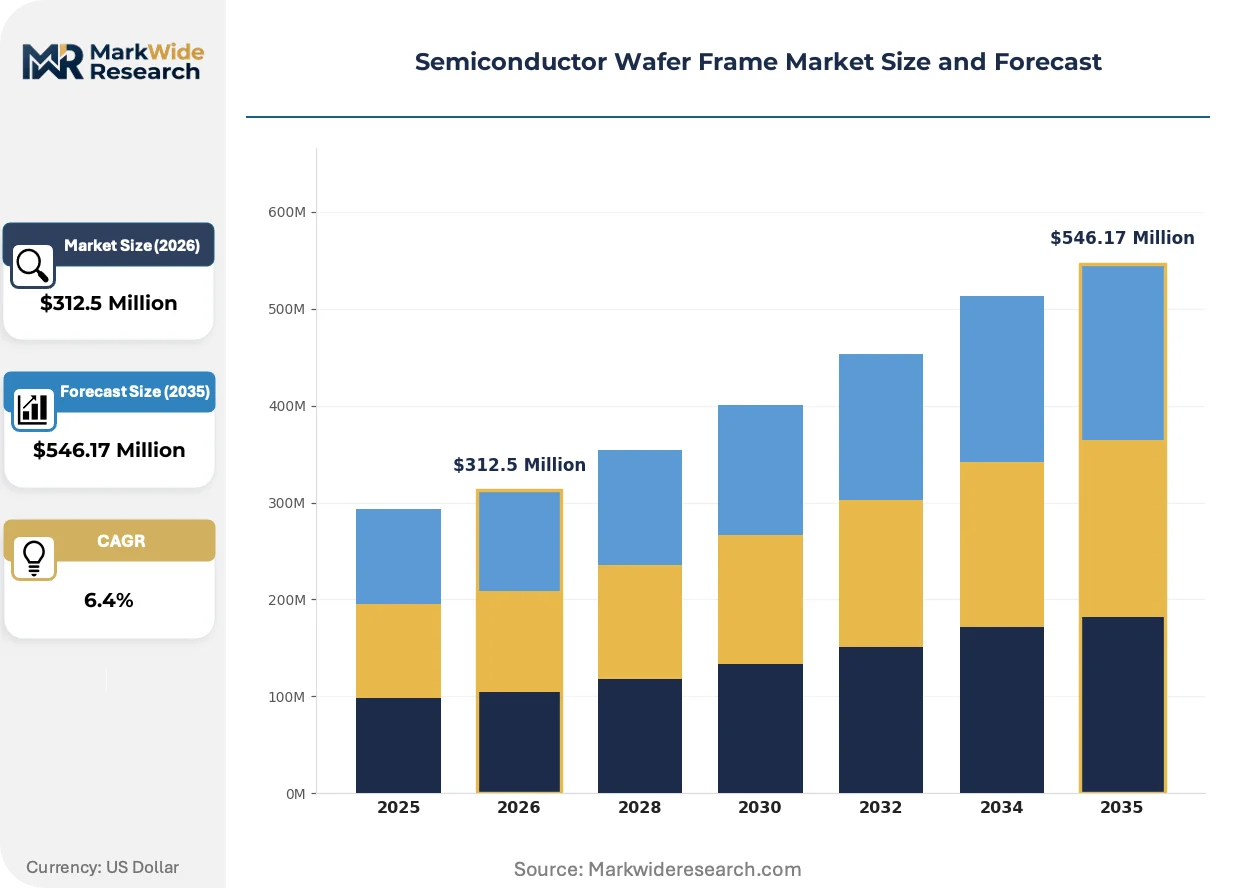
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Frames, Plastic Frames, Composite Frames, Silicon Frames End User: Foundries, Fabless Companies, Integrated Device Manufacturers, Research Institutions Frame Material: Aluminum, Steel, Nylon, Polycarbonate Application: Wafer Processing, Packaging, Transportation, Storage |
| Companies Covered | Disco Corporation, Sumitomo Bakelite, Entegris, Advantek, Schott, 3M, LINTEC Corporation, Meiko Electronics, Shin-Etsu Polymer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wafer Frame Market Trends and Innovations
Material science breakthroughs and regulatory disclosure mandates are converging to redefine competitive advantage in wafer frame supply. Suppliers now compete on contamination traceability and thermal cycling resilience rather than dimensional precision alone.
Carbon-fiber-reinforced polymer formulations are fragmenting the traditional metal-polymer dichotomy in temporary bonding applications. Memory packaging houses in South Korea are piloting these composites for their superior stiffness-to-weight ratios during high-speed dicing. The technology is fragmenting procurement categories as buyers reconsider whether single-material frames remain optimal for multi-step backend workflows.
REACH substance disclosure expansions are forcing reformulation of epoxy-based polymer frames used in European packaging facilities. ECHA's 2024 candidate list additions for SVHCs have triggered supply chain audits extending three tiers upstream to raw resin suppliers. Frame vendors serving STMicroelectronics and Bosch semiconductor divisions are accelerating migration to halogen-free thermoplastic alternatives to preempt authorization bottlenecks.
Consolidated procurement contracts are displacing spot purchasing as fabless companies centralize packaging decisions under captive OSAT strategies. Apple and NVIDIA are negotiating multi-year frame supply agreements directly with Entegris and Disco rather than delegating to assembly subcontractors. This concentration is most visible in Arizona and Texas, where TSMC and Samsung Foundry greenfield projects are pre-qualifying suppliers for decade-long fab lifecycles.
Semiconductor Wafer Frame Market Segmentation
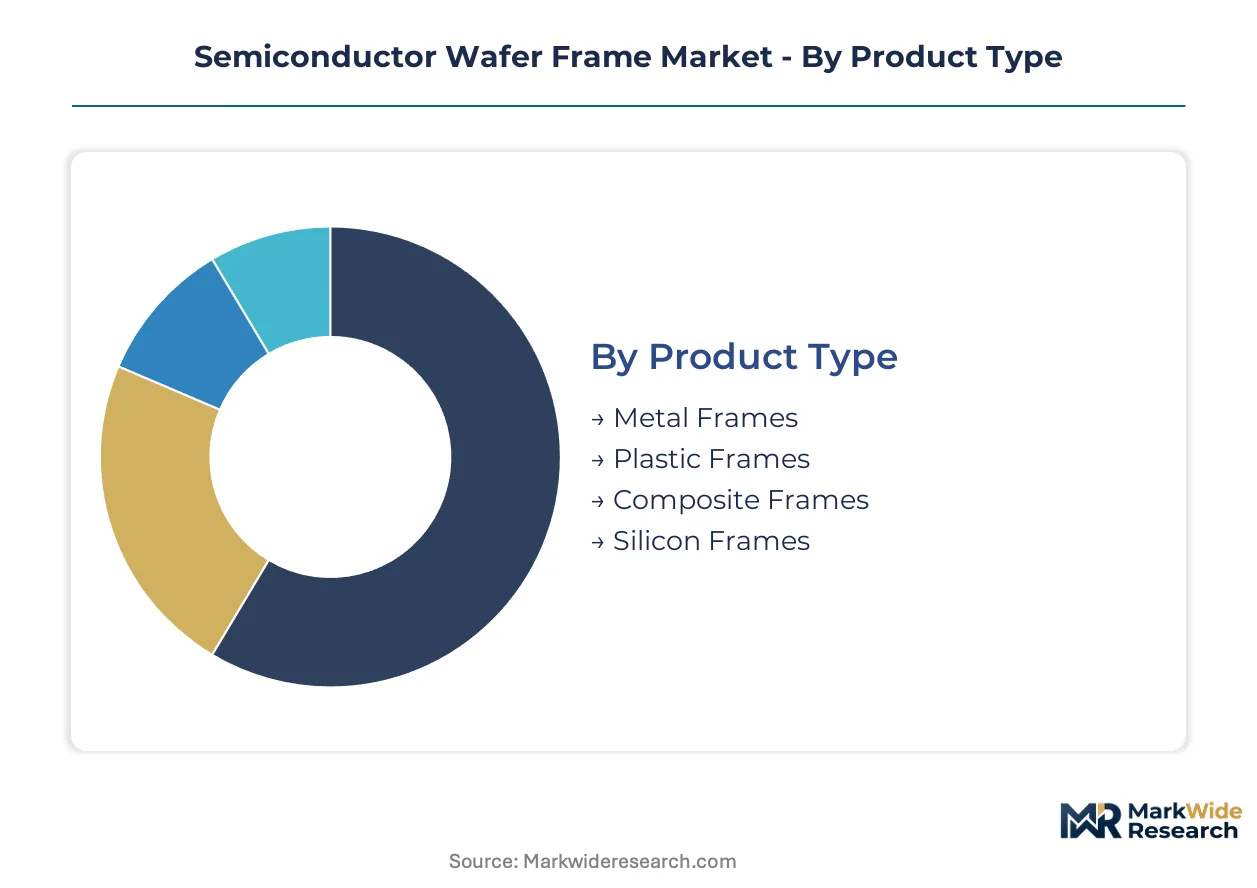
Wafer frame procurement patterns diverge sharply across material compositions and end-use workflows. Specification requirements from foundry backend processes versus fabless packaging strategies create distinct margin architectures that suppliers must navigate.
Product Type:
Margin pools concentrate in metal frames for high-volume foundry contracts, while polymer variants capture value through chemical resistance specifications in temporary bonding workflows.
- Metal Frames:Aluminum and stainless steel constructions maintain sub-50 micrometer tolerances essential for 300mm wafer handling in Taiwan and South Korea foundries. Disco Corporation anchors premium positioning here through captive machining capabilities tied to dicing equipment sales. Thermal cycling resilience across hybrid bonding workflows drives specification tightening.
- Plastic Frames:Engineered polymers from Entegris and Sumitomo Bakelite address cost-sensitive temporary bonding where chemical resistance outweighs mechanical load requirements. REACH compliance mandates are accelerating halogen-free formulation shifts for European packaging facilities.
- Composite Frames:Carbon-fiber-reinforced variants are piloting in South Korean memory packaging for stiffness-to-weight optimization during high-speed dicing operations.
- Silicon Frames:Specialized applications in extreme flatness requirements for EUV-patterned wafer handling remain niche due to brittleness constraints.
The dominant share belongs to Metal Frames, while Plastic Frames is closing the gap fastest through polymer formulation advances matching aluminum thermal expansion coefficients.
End User:
Volume concentration follows captive packaging centralization under fabless majors, reshaping procurement from fragmented OSAT delegation to direct multi-year agreements.
- Foundries:TSMC, Samsung Foundry, and Intel contract the highest frame volumes for in-house backend processing. 300mm wafer proliferation across Taiwan and Arizona greenfield sites drives rigidity-to-weight specification evolution.
- Fabless Companies:Apple and NVIDIA are pre-qualifying frame suppliers directly rather than delegating to assembly subcontractors, compressing vendor lists.
- Integrated Device Manufacturers:Texas Instruments and Analog Devices maintain mixed sourcing strategies balancing captive fabrication with outsourced packaging.
- Research Institutions:CEA-Leti in France and IMEC in Belgium pilot next-generation frame materials under EU Chips Act funding mechanisms.
Foundries command procurement volume leadership, though Fabless Companies are expanding their supplier influence most rapidly through consolidated contracting.
Frame Material:
Raw material cost structures and machining complexity determine supplier margin durability across alloy and polymer categories.
- Aluminum:Dominates 300mm wafer applications through optimal stiffness-to-weight ratios. London Metal Exchange price volatility compresses contract manufacturer margins during spike periods.
- Steel:Stainless variants command premium positioning in high-temperature backend processes where thermal stability exceeds aluminum limits.
- Nylon:Cost-effective temporary bonding solutions face substitution pressure from advanced thermoplastics with superior contamination profiles.
- Polycarbonate:Optical clarity requirements in inspection-intensive workflows sustain niche demand despite thermal expansion limitations.
Aluminum retains the largest installed base, while Steel is gaining share fastest in high-temperature process applications.
Application:
Workflow step intensity varies dramatically, with packaging lines multiplying frame touches per finished device as chiplet architectures proliferate.
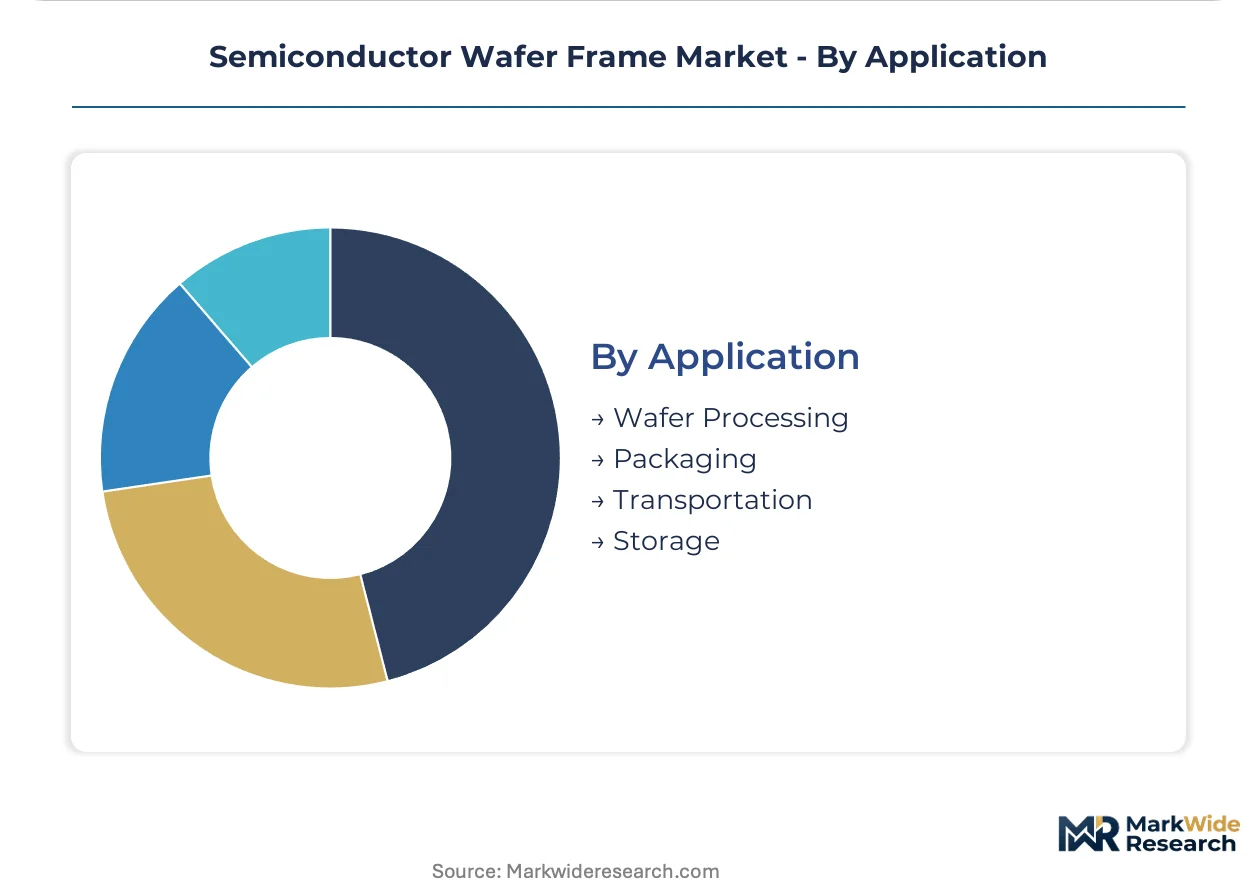
- Wafer Processing:Dicing and grinding operations consume the majority of frame cycles. Disco Corporation integrates frame supply with precision equipment sales to lock in foundry specifications.
- Packaging:Hybrid bonding, temporary bonding, and debonding workflows are multiplying frame touches per device. OSATs in Malaysia and Vietnam are qualifying frames for sequential thermal cycling survival.
- Transportation:Cleanroom logistics requirements sustain demand for contamination-sealed frame designs with traceable material genealogy.
- Storage:Long-term wafer inventory management drives specifications for dimensional stability across humidity and temperature variations.
Wafer Processing absorbs the highest absolute volume, though Packaging is expanding most quickly through advanced packaging architecture proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for wafer frames tilt heavily toward net imports in Europe and North America, while Taiwan, South Korea, and Japan maintain structural surpluses through captive precision machining ecosystems. Cross-border qualification timelines now stretch 4-6 months under dual-use export controls, reshaping regional sourcing strategies.
Taiwan
TSMC's backend facilities in Hsinchu and Taichung anchor the densest concentration of 300mm frame consumption worldwide. METI-aligned material traceability requirements from Japanese equipment vendors propagate downstream to local frame suppliers. The Southern Taiwan Science Park hosts precision machining clusters where Disco Corporation maintains integrated frame-dicing equipment service operations.
South Korea
Samsung Foundry and SK Hynix memory packaging lines in Pyeongtaek and Icheon drive demand for thermal-cycling-resistant frames. The country's national semiconductor regulator enforces K-REACH substance disclosure mandates that exceed baseline EU requirements. Busan-Ulsan industrial corridors host carbon-fiber-reinforced polymer pilot programs for high-speed dicing applications.
Japan
Sumitomo Bakelite and Shin-Etsu Polymer headquarters in Tokyo and Nagoya anchor polymer formulation leadership for high-temperature backend processes. METI semiconductor materials guidelines mandate lot-level genealogy documentation that propagates to medical-grade chip packaging. Kyoto-Osaka precision manufacturing belts supply stainless steel frames for hybrid bonding workflows.
United States
Intel's Arizona and Ohio fabs plus TSMC's Phoenix greenfield site are pre-qualifying frame suppliers for decade-long procurement cycles. FDA oversight of implantable medical devices elevates traceability standards that frame vendors must satisfy. Texas Instruments maintains mixed sourcing strategies balancing captive Dallas fabrication with outsourced packaging.
Germany
Bosch semiconductor divisions in Reutlingen and Infineon packaging facilities in Dresden drive REACH-compliant frame demand under ECHA's 2024 SVHC candidate list expansions. The country's national chemical regulator enforces halogen-free thermoplastic migration timelines stricter than EU baselines. Bavaria's Munich-Stuttgart industrial corridor hosts research partnerships between frame suppliers and automotive chip packagers.
Semiconductor Wafer Frame Market Competitive Landscape
Concentration sits with precision equipment-integrated suppliers and advanced materials specialists who anchor opposing ends of the value chain. Three archetypes dominate: vertically integrated dicing equipment vendors, polymer formulation leaders, and contract machining specialists serving cost-sensitive tiers. Competitive moves center on captive supply agreements with greenfield fabs and polymer substitution R&D to displace aluminum in packaging applications.
Within the equipment-integrated tier, Disco Corporation exemplifies backward integration into precision machining capabilities that lock in foundry specifications. Entegris and Sumitomo Bakelite occupy positions as formulation specialists whose material science depth commands premium positioning in contamination-sensitive workflows. Among diversified industrial conglomerates, 3M and Schott represent scale-driven entries whose cross-sector manufacturing infrastructure supports wafer frame as a specialty line.
| Leading Market Players |
|---|
| Disco Corporation |
| Sumitomo Bakelite |
| Entegris |
| Advantek |
| Schott |
| 3M |
| LINTEC Corporation |
| Meiko Electronics |
| Shin-Etsu Polymer |
| Others |
Pricing and Supply Chain Analysis
Polymer substitution for aluminum in temporary bonding workflows simultaneously shifts procurement geography toward South Korean resin compounders and compresses pricing premiums historically commanded by precision-machined metal frames. This material transition rewards formulation specialists with captive polymer science capabilities while eroding margin pools for contract machinists dependent on London Metal Exchange aluminum pricing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to Entegris and Disco Corporation formulations with lot-level genealogy documentation for FDA-traceable medical packaging, while economy tiers serve spot purchasers in Southeast Asian OSAT corridors. Pricing pressure stems from aluminum volatility passing through long-term foundry contracts with limited renegotiation windows. Fabless companies consolidating procurement under captive OSAT strategies exhibit lowest price sensitivity, whereas independent Malaysian and Vietnamese assemblers negotiate aggressively on per-unit frame costs.
Supply Chain Analysis
Taiwan Strait shipping lanes concentrate risk for frame deliveries bound for Arizona and Texas greenfield fabs. Raw material flows draw from Japanese aluminum smelters, South Korean carbon-fiber resin compounders, and German specialty steel mills. Single-source vulnerability sits with precision machining clusters in Hsinchu and Taichung earthquake zones. Distribution runs through equipment-integrated vendors supplying dicing tools and consumables as bundled packages rather than discrete component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor wafer frame market sits in early-cycle recovery as EU Chip Act localization mandates rebuild regional supplier ecosystems outside incumbent Asian concentration. Foundry capex normalization in Taiwan and Arizona signals replacement demand acceleration for 300mm-compatible frame systems.
For Market Incumbents: Shield premium positioning by deepening backward integration into precision machining capabilities that lock TSMC and Intel specifications. Accelerate halogen-free thermoplastic R&D to preempt ECHA authorization bottlenecks. Counter carbon-fiber composite substitution threats with hybrid metal-polymer designs that balance thermal performance against chemical resistance in temporary bonding workflows. For New Entrants and Emerging Players: Anchor in India's PLI-linked domestic content requirements as Micron's Gujarat facility and Tata's planned fab qualify local suppliers. Target medical device packaging segments where FDA traceability mandates propagate upstream to frame vendors with lot-level material genealogy capabilities. Pursue direct qualification pathways with fabless majors consolidating procurement under captive OSAT strategies rather than subcontractor delegation. For Investors and Strategic Acquirers: The market sits at a restructuring phase that favors formulation specialists with polymer science depth over commodity machining operations. Five-to-ten year viability hinges on substitution economics between aluminum and advanced thermoplastics in advanced packaging workflows. Watch carbon-fiber-reinforced polymer pilot outcomes in South Korean memory packaging as inflection indicators for material category fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Disco Corporation locks foundry specifications by captive-producing frames alongside dicing equipment sales. |
| Halogen-Free Thermoplastic Migration | REACH SVHC candidate list expansions force Entegris reformulation for STMicroelectronics and Bosch compliance. |
| Hybrid Metal-Polymer Design Development | OSATs in Malaysia balance thermal cycling resilience against temporary bonding chemical resistance requirements. |
| Direct Fabless Qualification Pathways | Apple and NVIDIA compress vendor lists by negotiating multi-year agreements outside subcontractor channels. |
| Carbon-Fiber Composite Pilot Programs | SK Hynix and Samsung memory packaging lines test stiffness-to-weight optimization for high-speed dicing throughput. |
Research Methodology
Operator-level perspectives from foundry backend engineers, OSAT procurement leads, polymer formulation scientists, precision machining plant managers, and medical device packaging quality directors anchored the qualitative base. Secondary validation drew from METI semiconductor materials guidelines, ECHA SVHC candidate list filings, FDA 510(k) implantable device submissions, and SEC 10-K disclosures from equipment-integrated suppliers. Bottom-up frame consumption estimates triangulated against top-down foundry capex allocations across the analysis window.
Sensitivity analysis tested polymer substitution elasticity, aluminum price volatility scenarios, and dual-use export control timeline extensions. The analytical framework modeled segmentation across material composition, end-user archetype, and application workflow intensity throughout the forecast period. CAGRs derived from wafer start projections, advanced packaging architecture penetration curves, and regional fab buildout schedules.
Material uncertainties — EU Chips Act localization timeline delays, Taiwan seismic disruption events, and ECHA authorization bottlenecks for halogen-free alternatives — sit outside the modeled envelope. Forecasts reflect assumptions about substitution economics and regulatory disclosure stringency that practitioners should keep alternative scenarios live as greenfield fab qualification schedules and REACH compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Americas Power Transistor Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Precision Link Carrier Market