
 Fin Field Effect Transistor (Finfet) Market | 2026-2036
Fin Field Effect Transistor (Finfet) Market Size, Share, and Industry Trends Forecast 2026-2036
Fin Field Effect Transistor (Finfet) Market Foresight
The gap between leading-edge FinFET wafers and mature-node commodity production is broadening into a durable pricing chasm. Intel Corporation leverages its IDM strategy to sustain captive supply for x86 and foundry roadmaps alike. Samsung Electronics anchors its logic ambitions in Pyeongtaek with aggressive node transitions. Taiwan Semiconductor Manufacturing Company Limited dominates pure-play foundry output at the most advanced geometries.
A Fin Field Effect Transistor (FinFET) is a non-planar, three-dimensional MOSFET architecture where the conducting channel rises vertically as a thin silicon fin wrapped by the gate electrode on multiple sides, enabling superior electrostatic control and reduced short-channel effects at sub-20nm process nodes. Multi-gate configurations now lead performance benchmarks for high-density logic, while silicon FinFET technology still occupies the bulk of commercial wafer starts even as indium gallium arsenide variants gain traction in radio-frequency and photonics integration. Data centers and cloud service providers together form the most concentrated end-user demand pool, driven by AI training clusters and inference accelerators that require the power-efficiency gains only advanced FinFET nodes deliver.
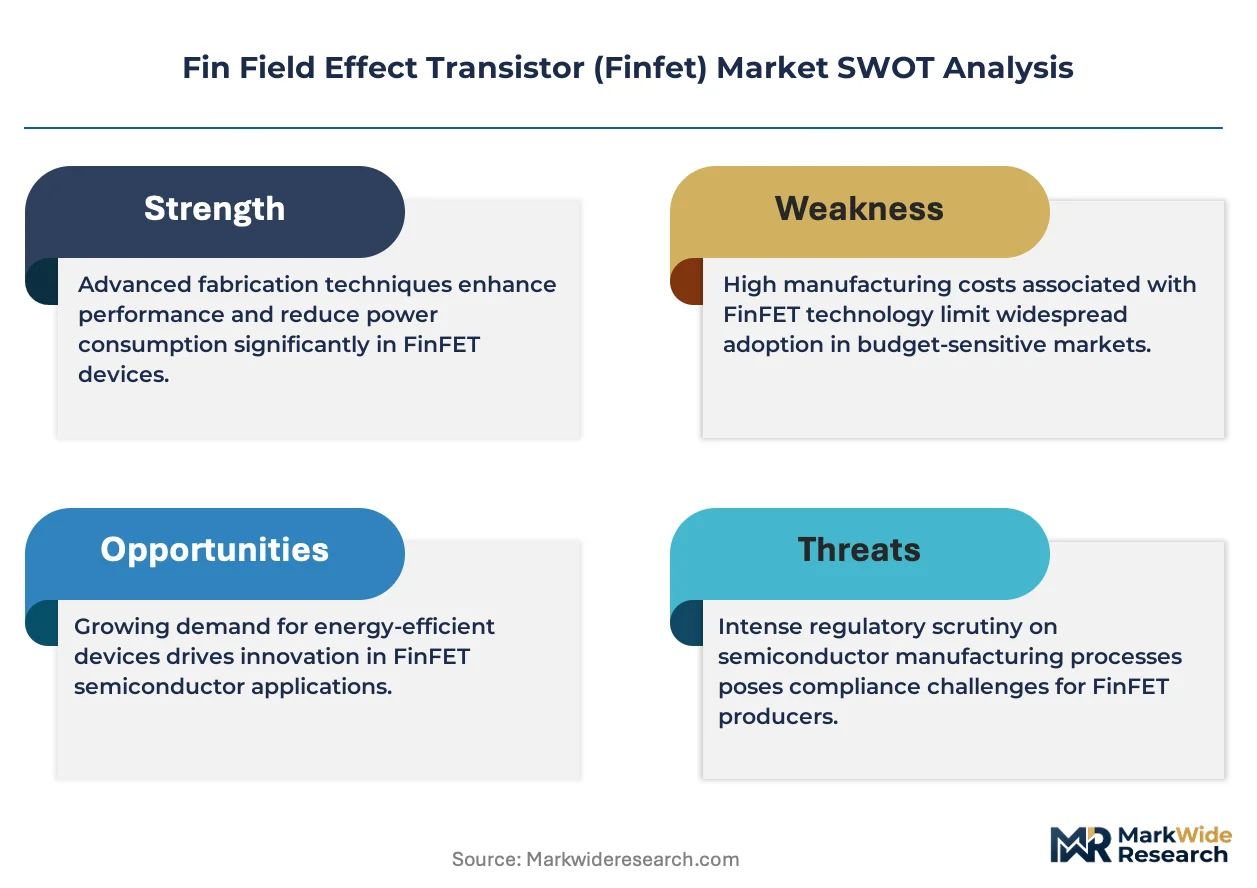
Export control frameworks administered by the US Department of Commerce's Bureau of Industry and Security, alongside China's GB standards for semiconductor reliability and the EU Chips Act's subsidy conditionality, are fragmenting equipment and materials access across jurisdictions. REACH and RoHS compliance in Europe further constrain the chemistries permissible in FinFET fabrication, raising qualification burdens for new process materials. Stakeholders must now calibrate capacity commitments against which regulatory blocs will recognize each other's product certifications and which will erect parallel compliance walls.
Market Dynamics
The transition from planar to gate-all-around architectures is compressing the commercial lifespan of each FinFET generation while AI accelerator demand absorbs wafer starts at unprecedented density. This node-to-node acceleration rewards foundries with the capital depth to sustain parallel development tracks.
Growth Catalysts
- EU Chips Act subsidy conditionality:Captive foundry investments in Dresden and Leuven are expanding EUV lithography capacity for sub-5nm logic. Equipment qualification timelines have shortened under sovereign production mandates.
- AI training clusters:Hyperscale data centers in Taiwan, Arizona, and Bavaria now specify FinFET-based inference accelerators as standard procurement. Power-density requirements at rack level eliminate planar alternatives.
- Indium gallium arsenide integration:III-V material stacks for RF front-ends and silicon photonics are extending FinFET utility into non-digital domains. Process compatibility with existing 300mm infrastructure preserves capital efficiency.
Market Restraints
- EUV pellicle supply concentration:Single-source dependency for high-NA lithography membranes creates chokepoint vulnerability. Defect rates above specification freeze entire production lots.
- Fluorinated gas chemistry constraints:REACH Annex XVII restrictions on perfluorinated compounds limit etch process options. Alternative chemistries require full requalification of critical dimension control.
- Gate-all-around substitution timeline:Samsung's 3nm GAA introduction compresses the remaining addressable window for FinFET dominance at leading edge. Migration economics favor greenfield capacity over retrofit.
Strategic Opportunities
- India's semiconductor PLI scheme:Gujarat and Assam greenfield sites offer decade-long fiscal incentives for mature-node FinFET derivatives. Analog-mixed signal and automotive qualification represent immediate entry vectors.
- Automotive functional safety certification:ISO 26262 ASIL-D compliance at 16nm and 22nm nodes opens insulated gate driver and battery management segments. Tier-1 module suppliers are qualifying second-source foundry relationships.
- Chiplets and 2.5D integration:Die disaggregation protocols enable FinFET-based I/O dies to companion with more advanced compute tiles. Interposer standardization through UCIe consortium reduces integration friction.
Industry Challenges
- Process integration engineering scarcity:Deep sub-wavelength lithography-etch overlap optimization requires experience pools concentrated at three foundry operators. Compensation inflation is compressing IDR margins.
- Multi-patterning reticle set costs:Quadruple patterning at 7nm and 5nm nodes demands 80-plus mask layers per design. NRE amortization across low-volume AI chip tapeouts extends breakeven timelines.
- Export control compliance fragmentation:US BIS entity list restrictions, China's GB semiconductor reliability standards, and EU dual-use regulations create parallel certification tracks. Legal entity structuring now consumes senior executive bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fin Field Effect Transistor (Finfet) Market |
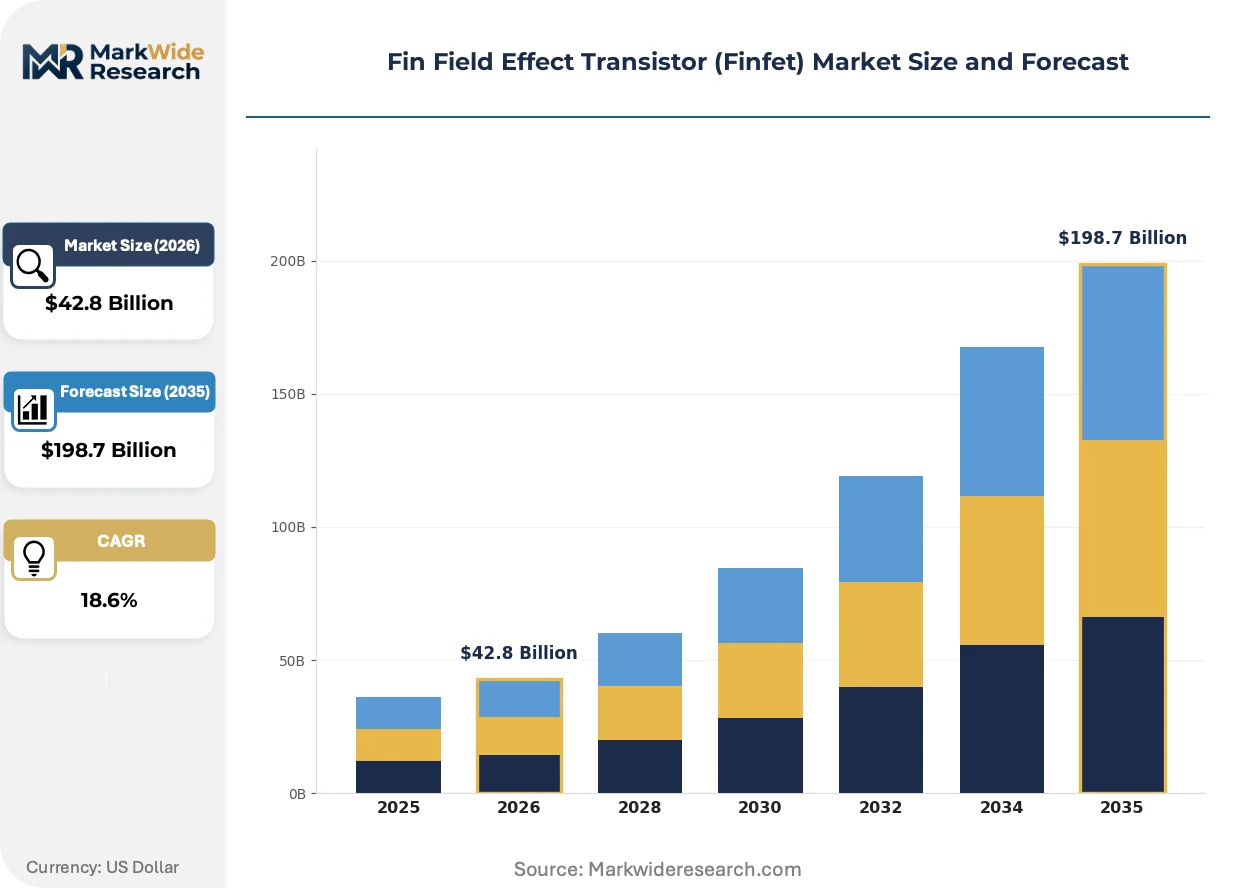
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $198.7 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Gate, Triple Gate, Multi-Gate, Single Gate Technology: Silicon FinFET, Indium Gallium Arsenide, High-K Metal Gate, SiGe FinFET Application: Consumer Electronics, Automotive Electronics, Power Management, Telecommunications End User: Data Centers, Cloud Service Providers, Semiconductor Manufacturers, Research Institutions |
| Companies Covered | Intel Corporation, Taiwan Semiconductor Manufacturing Company Limited, Samsung Electronics, NVIDIA Corporation, GlobalFoundries, Texas Instruments, NXP Semiconductors, Qualcomm Incorporated, MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fin Field Effect Transistor (Finfet) Market Shifts & Advancements
Process-material innovation and sovereign capacity mandates are diverging the FinFET supply base into technology-isolated blocs. Equipment and chemistry access now routes through jurisdiction-specific approval frameworks.
Backside power delivery networks are electrifying the FinFET power-performance-area calculus. TSMC and Intel have committed to buried power rail architectures at 2nm-class nodes. Data center CPU and GPU designers are re-architecting floorplans to exploit the reduced IR drop and freed front-side routing resources.
REACH authorization requirements for PFAS chemistries are forcing etch chamber retrofits across European fabrication sites. ECHA's 2023 restriction proposal on fluorinated polymers threatens C4F6 and C4F8 process gas supply chains. Foundries with pre-qualified fluorine-free alternatives are accelerating their European expansion timelines.
Hyperscale procurement teams are consolidating foundry relationships from six-plus qualified sources to two strategic partnerships. Long-term capacity reservation contracts with pre-payment structures are displacing spot-market wafer purchases. This concentration is most visible among US-based cloud service providers securing Arizona and Oregon fab output through 2028.
Fin Field Effect Transistor (Finfet) Market Segmentation
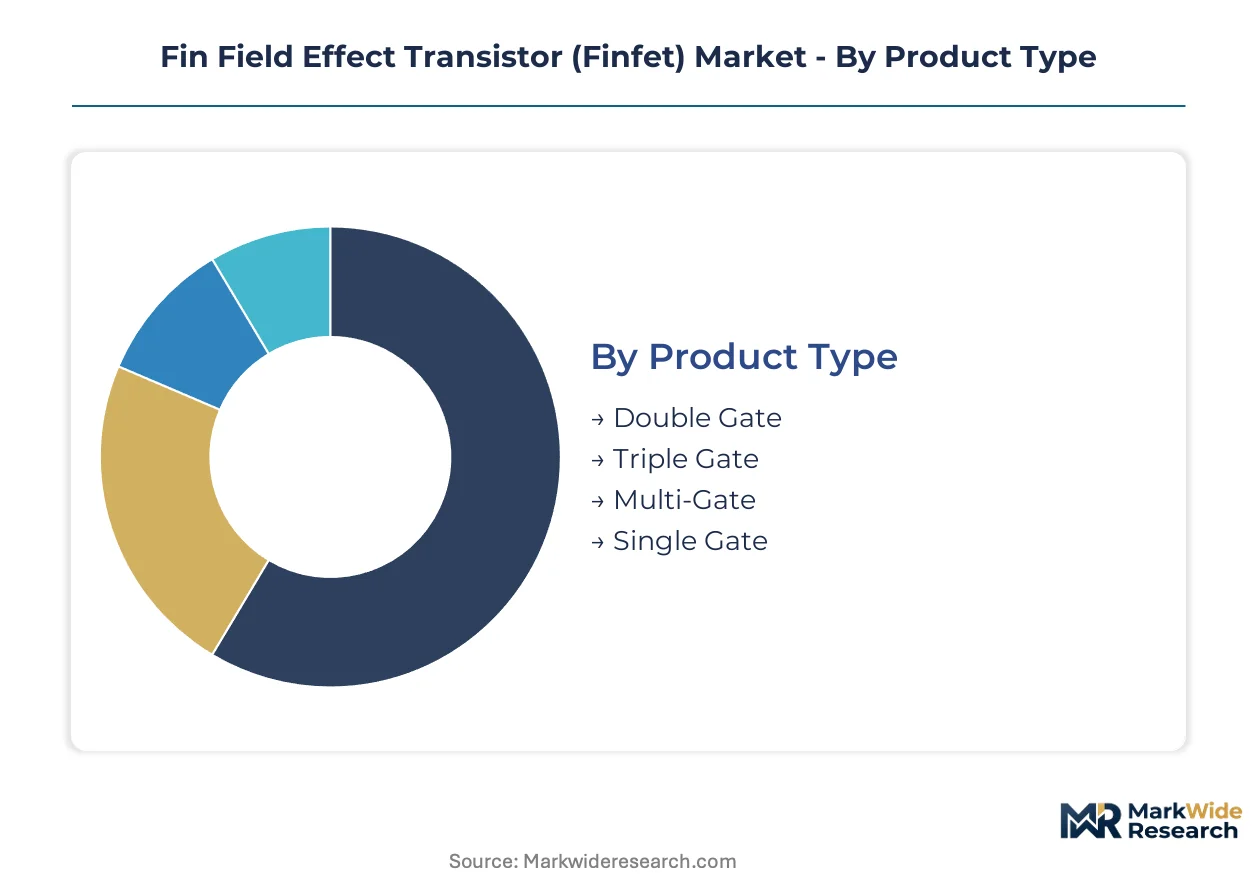
FinFET architecture choices determine power-performance tradeoffs across node generations, while material systems and end-use specifications fragment procurement requirements. Segment boundaries align with foundry qualification timelines and sovereign capacity mandates.
Product Type:
Node transitions drive replacement cycles, with each gate configuration commanding distinct tooling footprints and design rule ecosystems.
- Multi-Gate:Wrap-around gate structures deliver superior electrostatic control for sub-5nm logic, with gate-all-around evolution extending this topology. Data center AI accelerators in Taiwan and Arizona now specify multi-gate as baseline for training workloads, compressing planar obsolescence timelines.
- Triple Gate:Three-sided channel coverage balances manufacturability with leakage suppression at 7nm through 3nm nodes. Samsung's Pyeongtaek complex and Intel's Oregon fabs anchor demand, driven by smartphone SoC and client CPU roadmaps requiring density without full GAA migration costs.
- Double Gate:Dual-sided gate control serves cost-optimized 14nm and 10nm derivatives for automotive and industrial MCUs.
- Single Gate:Legacy planar-compatibility configurations persist in mature-node derivatives for analog-mixed signal integration.
Volume placements concentrate in Triple Gate; the faster expansion belongs to Multi-Gate.
Technology:
Material stack selection separates digital logic density leaders from RF and photonics specialists, with qualification costs creating technology moats.
- Silicon FinFET:Dominant 300mm infrastructure compatibility preserves capital efficiency across foundry networks. TSMC's N3 and N2 roadmaps, Intel's 18A node, and Samsung's 3GAP all iterate on silicon fin structures, with Arizona and Dresden sovereign fabs replicating this technology base.
- Indium Gallium Arsenide:III-V compound semiconductors enable millimeter-wave and photonics integration beyond silicon's carrier mobility limits. Telecommunications infrastructure in Germany and South Korea drives qualification, with silicon photonics transceivers absorbing InGaAs FinFETs for 800G optical links.
- High-K Metal Gate:HfO₂ dielectric stacks reduce gate leakage at aggressive scaling, now standard across leading-edge nodes.
- SiGe FinFET:Strained silicon-germanium channels enhance hole mobility for PMOS devices in RF front-end applications.
Silicon FinFET claims dominant wafer starts; InGaAs variants are climbing the fastest as optical interconnect penetration deepens.
Application:
End-use thermal and reliability specifications dictate node selection, with automotive and power segments insulating mature FinFET generations from leading-edge displacement.
- Data Centers:AI training clusters absorb the densest FinFET wafer allocations, with rack-level power density eliminating planar alternatives. Hyperscale procurement teams in Virginia, Frankfurt, and Singapore specify 5nm-class inference accelerators as standard, locking in multi-year capacity reservations.
- Automotive Electronics:ISO 26262 ASIL-D functional safety requirements at 16nm and 22nm nodes create insulated demand pools. Battery management systems and gate drivers for electric vehicles in Bavaria and Michigan foundries qualify second-source relationships, extending FinFET relevance beyond digital logic.
- Consumer Electronics:Smartphone SoCs and PC CPUs drive leading-edge node adoption with annual refresh cycles.
- Telecommunications:5G baseband and mmWave RF demand specialized FinFET derivatives for signal integrity.
Data Center placements dominate wafer value; Automotive Electronics is gaining share fastest as electrification multiplies semiconductor content per vehicle.
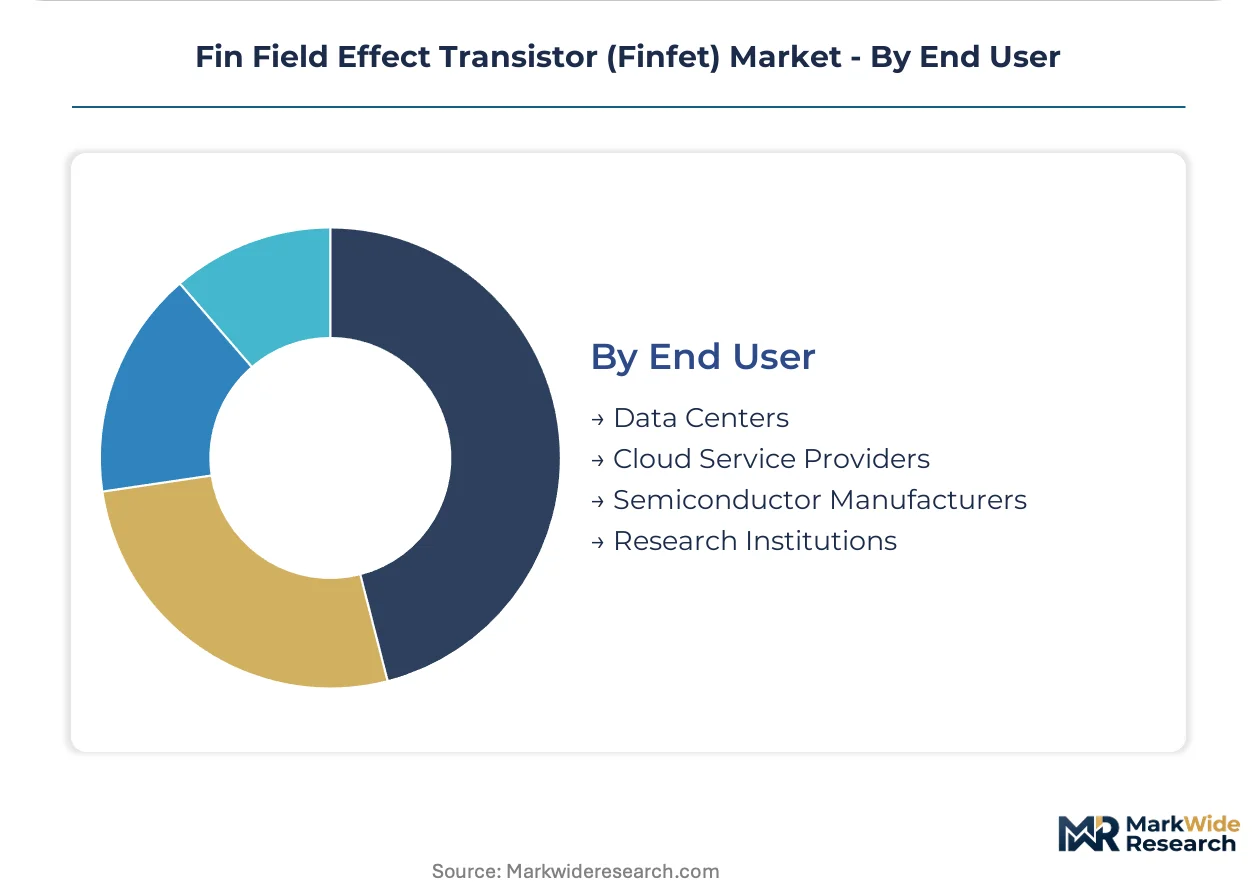
End User:
Procurement concentration among hyperscale operators is collapsing qualified supplier lists from six-plus sources to two strategic partnerships.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform consolidate foundry relationships through pre-paid capacity structures. Arizona and Oregon fab output is committed through 2028, with long-term contracts displacing spot-market purchases.
- Semiconductor Manufacturers:IDM operators including Intel and Samsung sustain captive supply for x86 and foundry roadmaps, with EU Chips Act subsidies conditioning Dresden and Leuven investments on sovereign output targets.
- Data Centers:Colocation and enterprise operators specify FinFET-based accelerators for AI inference at the edge.
- Research Institutions:CERN, imec, and national laboratories drive early-stage material and architecture exploration.
Cloud Service Providers command the largest capacity reservations; Semiconductor Manufacturers are expanding most quickly under sovereign subsidy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the densest concentration of leading-edge FinFET fabrication capacity worldwide. Sovereign subsidy programs in Germany, India, and the United States are accelerating greenfield investments outside Taiwan. Export control frameworks administered by the US Bureau of Industry and Security are fragmenting equipment access across jurisdictions.
United States
Hyperscale cloud service providers in Virginia and Oregon drive demand for 5nm-class inference accelerators. The CHIPS and Science Act directs $52 billion toward domestic semiconductor manufacturing. Intel's Oregon fabs and TSMC's Arizona greenfield site are expanding EUV lithography capacity for advanced logic production.
Taiwan
TSMC's Hsinchu and Tainan facilities process the majority of global leading-edge FinFET wafer starts. The National Development Council coordinates sovereign technology protection measures. Southern Taiwan Science Park clusters pure-play foundry output with specialized packaging and testing ecosystems.
Germany
Automotive electronics manufacturers in Bavaria qualify 16nm and 22nm FinFET nodes for battery management systems. The EU Chips Act subsidizes Dresden and Leuven captive foundry investments. Siemens and Infineon anchor a functional safety certification ecosystem for ISO 26262 ASIL-D compliance.
China
Domestic AI accelerator designers in Shanghai and Beijing specify imported FinFET wafers for training clusters. GB semiconductor reliability standards create parallel certification tracks for equipment qualification. SMIC's Shanghai fabs concentrate mature-node FinFET derivatives for analog-mixed signal applications.
South Korea
Samsung Electronics anchors logic ambitions in Pyeongtaek with aggressive node transitions. The Ministry of Trade, Industry and Energy coordinates national semiconductor competitiveness initiatives. Giheung and Hwaseong complexes integrate memory and logic fabrication with specialized materials supply chains.
Fin Field Effect Transistor (Finfet) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across node specialization and captive capacity depth. The vendor base concentrates around three foundry operators controlling sub-5nm lithography-etch optimization expertise. Strategic archetypes include integrated device manufacturers sustaining captive supply, pure-play foundries monetizing process leadership, and fabless designers extracting architectural differentiation. Dominant competitive moves encompass sovereign-subsidized greenfield capacity expansion and long-term pre-paid reservation contracts displacing spot-market procurement.
Among US-based integrated manufacturers, Intel Corporation exemplifies the IDM archetype with captive fabrication for x86 and foundry roadmaps. Taiwan Semiconductor Manufacturing Company Limited anchors the pure-play foundry tier with Hsinchu-based process leadership. Samsung Electronics represents the Korean conglomerate model integrating memory, logic, and display fabrication under unified technology development.
| Leading Market Players |
|---|
| Intel Corporation |
| Taiwan Semiconductor Manufacturing Company Limited |
| Samsung Electronics |
| NVIDIA Corporation |
| GlobalFoundries |
| Texas Instruments |
| NXP Semiconductors |
| Qualcomm Incorporated |
| MediaTek Inc. |
| Others |
Supply & Pricing Matrix
Node-to-node performance bifurcation between gate-all-around and legacy FinFET generations splits procurement into premium compute and cost-optimized tiers, with each tier demanding distinct supply chain configurations and qualification timelines. Hyperscale buyers in Arizona and Taiwan now negotiate wafer pricing against guaranteed capacity pools, while automotive purchasers in Bavaria absorb longer lead times for ISO 26262-certified nodes.
Pricing Analysis
Yield-per-wafer throughput anchors value-based pricing for leading-edge FinFET production, with hyperscale cloud providers in Virginia and Frankfurt paying premiums for guaranteed 5nm-class allocation. Price differentiation rests on EUV lithography intensity and functional safety certification tier, with ASIL-D automotive nodes commanding 40% premiums over consumer-grade equivalents. Cost compression in mature-node derivatives intensifies as India's PLI scheme subsidizes 28nm-class capacity additions. Fabless AI chip designers exhibit highest price sensitivity, while sovereign-funded IDM operators absorb NRE amortization across captive volumes.
Supply Chain Analysis
Reticle refurbishment and EUV pellicle recovery flows now constitute critical reverse-logistics channels for foundries seeking to defray quadruple-patterning mask set costs. Manufacturing concentration in Taiwan, South Korea, and the United States creates geographic chokepoint exposure for advanced logic. High-purity fluorinated gases, single-crystal silicon ingots, and high-NA lithography equipment anchor input dependencies. Single-source vulnerability for pellicle membranes threatens production continuity. Distribution runs through long-term pre-paid reservation contracts displacing spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gate-all-around architectures are displacing FinFET dominance at sub-3nm nodes, compressing the commercial window for each planar generation and forcing capacity commitments before technology obsolescence.
For Market Incumbents: Anticipate GAA substitution timelines by accelerating 2nm-class FinFET depreciation schedules and locking automotive qualification contracts before process migration. Intel and TSMC should deepen backward integration into EUV pellicle supply as single-source chokepoints threaten yield stability. Captive foundry investments in Dresden and Arizona must front-load sovereign subsidy capture before conditionality tightens. For New Entrants and Emerging Players: Begin with automotive functional safety certification at 16nm and 22nm nodes, where ISO 26262 ASIL-D compliance creates insulated demand pools resistant to leading-edge displacement. India's Gujarat greenfield sites offer decade-long fiscal incentives for mature-node FinFET derivatives. Analog-mixed signal integration for battery management systems represents the most penetrable white-space target, with qualification partnerships replacing direct foundry competition. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized materials suppliers with pre-qualified fluorine-free etch chemistries, as ECHA restrictions on PFAS compounds force European fab retrofits. Long-term viability favors process-integration engineering teams with deep sub-wavelength lithography-etch overlap expertise concentrated at three foundry operators. Watch for hyperscale procurement consolidation from six-plus qualified sources to two strategic partnerships as inflection signal for pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EUV Pellicle Supply | TSMC and Intel are securing captive membrane sources to eliminate single-source dependency for high-NA lithography. |
| Automotive Functional Safety Certification | ISO 26262 ASIL-D compliance at 16nm nodes opens insulated demand pools for battery management and gate driver applications. |
| Sovereign Subsidy Capture in Greenfield Fabs | EU Chips Act and CHIPS Act funding conditionality requires accelerated equipment qualification timelines in Dresden and Arizona. |
| Fluorine-Free Etch Chemistry Pre-Qualification | ECHA's PFAS restriction proposal favors foundries with pre-qualified alternative chemistries for European expansion. |
| Long-Term Capacity Reservation Contracts | Hyperscale cloud providers in Virginia and Oregon are displacing spot-market purchases with pre-paid structures through 2028. |
Research Methodology
Document review covered foundry roadmaps, EUV lithography equipment specifications, and sovereign subsidy filings, complemented by interviews with fab operations executives, process integration engineers, hyperscale procurement officers, and automotive Tier 1 supplier quality directors. Secondary validation drew from SEC 10-K disclosures, ECHA chemical restriction proposals, and national semiconductor competitiveness white papers. Bottom-up wafer start estimates triangulated against top-down foundry capacity announcements.
Segment-level projections across node generations, gate configurations, material systems, and end-use specifications fed into analytical framework outputs over the projection horizon. CAGRs derived from capacity expansion schedules, equipment lead times, and hyperscale capex commitment trajectories. Forecast inputs incorporated EUV scanner delivery backlogs, fluorinated gas chemistry availability, and export control licensing timelines.
Underlying measurement precision varies by segment; data center accelerator demand carries tighter precision than emerging InGaAs photonics integration. Forecasts reflect assumptions on GAA substitution velocity, sovereign subsidy disbursement pacing, and REACH chemical restriction implementation. Practitioners should monitor EUV pellicle defect rate trends, hyperscale procurement consolidation announcements, and ECHA PFAS regulatory finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Modular Plating System Market