
 South Korea MLCC Market | 2026-2036
South Korea MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea MLCC Market Insights
Software-defined battery management calibration is rebalancing what automakers purchase from MLCC suppliers. Samsung Electro-Mechanics leverages its Gyeonggi-do fabrication complex to anchor high-voltage ceramic supply for domestic EV platforms. LG Innotek competes through specialized automotive-grade qualification programs that extend its reach into tier-one module suppliers. Taiyo Yuden sustains R&D intensity in ultra-miniature dielectric formulations for 5G handset RF chains.
Multi-layer ceramic capacitors stack alternating layers of dielectric ceramic and metal electrodes into monolithic chips that filter, decouple, and stabilize voltage across electronic circuits; barium titanate-based dielectrics dominate Class II formulations due to their high permittivity-to-volume ratio. The automotive end-user segment leads absolute consumption as inverter and onboard charger densities multiply with 800V architectures. Ultra-high capacitance grades capture expanding margin pools where dielectric layer thinning below 0.3 micrometers demands proprietary co-firing expertise. Medium voltage ratings still occupy the highest shipment volumes across consumer electronics and industrial motor drives.
MFDS material safety directives and KATS electrical safety standards constrain dielectric powder formulations and terminal plating chemistries for domestic circulation. The Korean Agency for Technology and Standards enforces dimensional tolerances that shape procurement specifications for export-bound Korean automotive electronics. Stakeholders must monitor how Seoul's national semiconductor cluster incentives redirect captive MLCC capacity toward system-in-package integration with domestic foundry output.
Market Dynamics
Electric vehicle powertrain electrification is compressing procurement cycles for high-voltage ceramic components across Hyundai Motor Group's domestic supply base. Dielectric layer thinning below 0.3 micrometers now separates qualified suppliers from commodity competitors.
Growth Catalysts
- K-Battery Strategy:Seoul's national battery industrial policy mandates localized component sourcing for EV platforms, pulling MLCC demand into domestic fabrication networks.
- 800V Architectures:Inverter and onboard charger density multiplication in premium EV segments consumes ultra-high capacitance grades at accelerated rates.
- Gyeonggi-do Cluster Concentration:Samsung Electro-Mechanics' Suwon and Sejong production bases anchor captive supply chains for tier-one automotive electronics module suppliers.
Market Restraints
- Barium Titanate Supply Concentration:Dielectric powder synthesis expertise concentrates among Japanese and Chinese material suppliers, creating input cost volatility for Korean formulators.
- MFDS Material Compliance:MFDS-aligned material safety directives constrain terminal plating chemistries and dielectric formulations, extending qualification timelines for new product introductions.
- Co-firing Technical Limitations:Proprietary high-temperature co-firing expertise for sub-micron layer stacks remains concentrated among a handful of integrated manufacturers, capping output scaling.
Strategic Opportunities
- System-in-Package Integration:National semiconductor cluster incentives redirect captive MLCC capacity toward co-packaging with domestic foundry output, creating new module-level value capture.
- Sejong Production Base Expansion:Greenfield capacity in Sejong offers tax-advantaged expansion for automotive-grade qualification programs serving export-bound Korean tier-ones.
- 5G Handset RF Chain Miniaturization:Ultra-miniature dielectric formulations for millimeter-wave filter applications open margin pools outside saturated consumer commodity segments.
Industry Challenges
- Co-firing Process Engineering Talent:Scarce expertise in high-temperature ceramic-metal co-firing constrains yield improvement programs across domestic fabrication lines.
- KATS Dimensional Tolerance Certification:Korean Agency for Technology and Standards enforcement of export-bound tolerance specifications demands sustained metrology capex without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea MLCC Market |
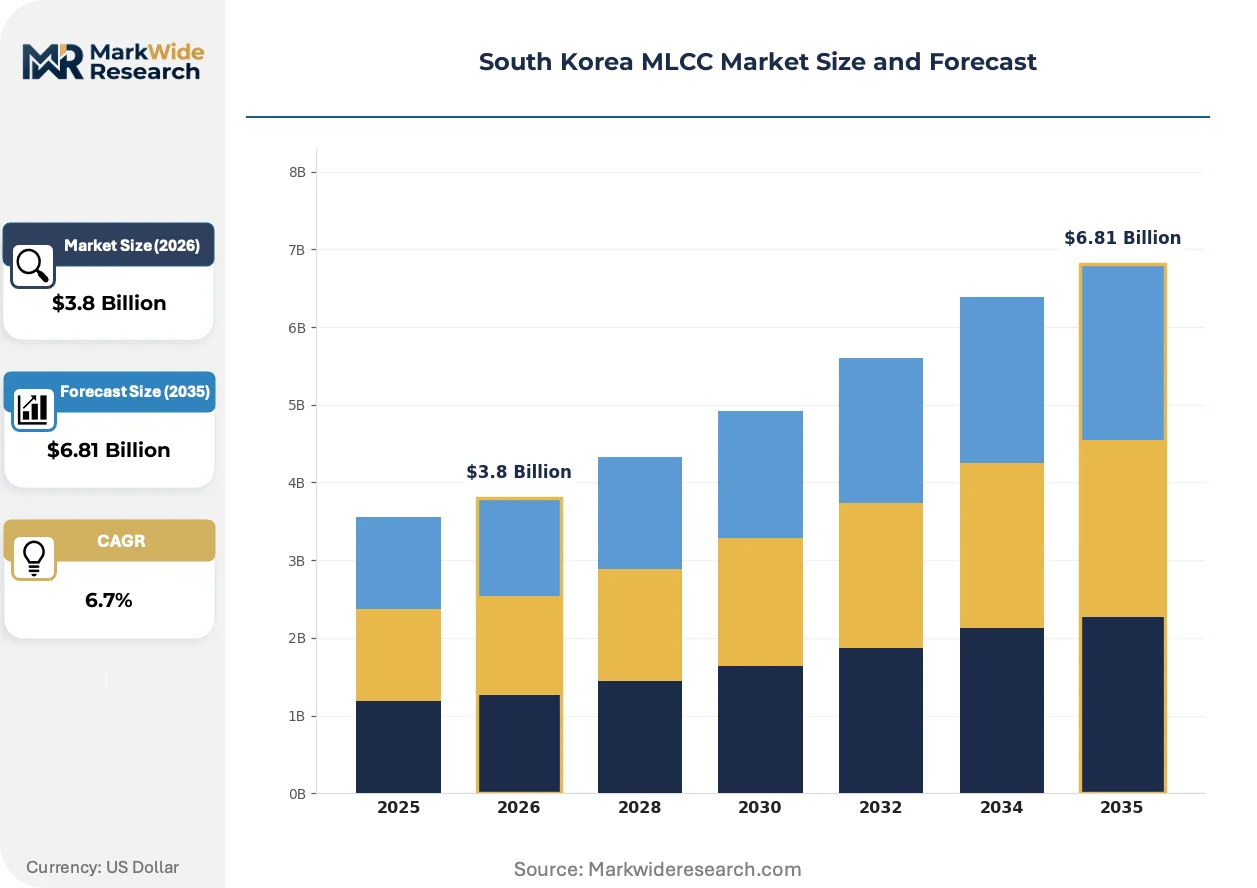
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Multi-layered, Chip, Ceramic, Tantalum End User: Consumer Electronics, Automotive, Industrial, Telecommunications Capacitance: Low, Medium, High, Ultra-High Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra-High Voltage |
| Companies Covered | Taiyo Yuden, LG Innotek, Samsung Electro-Mechanics, Yageo Corporation, Vishay Intertechnology, Murata Manufacturing, Kyocera, Walsin Technology Corporation, TDK Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea MLCC Market Trends and Innovations
Dielectric formulation chemistry and layer deposition precision are redefining competitive separation between integrated manufacturers and specialized component suppliers. Three active developments reshape procurement specifications and production economics.
Ultra-thin dielectric layer technology is expanding into automotive-qualified MLCC grades. Samsung Electro-Mechanics and domestic competitors deploy atomic-level thickness control to stack 500+ layers in compact footprints. Hyundai Motor Group's tier-one module suppliers now specify these grades for inverter DC-link applications, compressing qualification windows for second-tier formulators.
MFDS material safety directives and KATS electrical safety standards are tightening concurrently. Dielectric powder sourcing now requires documented compliance with heavy metal restrictions and terminal plating chemistry disclosures. Automotive electronics exporters face dual certification burdens: domestic MFDS alignment plus customer-mandated AEC-Q200 qualification, extending new product introduction timelines.
Buyer concentration among domestic EV platform integrators is compressing supplier negotiation leverage. Hyundai Motor Group and its designated tier-ones now dictate specification roadmaps three generations forward, displacing spot-market procurement with long-term capacity reservation agreements. This pattern concentrates in Gyeonggi-do's semiconductor cluster, where physical proximity to Samsung Electro-Mechanics' fabrication complex shapes contract terms.
South Korea MLCC Market Segmentation
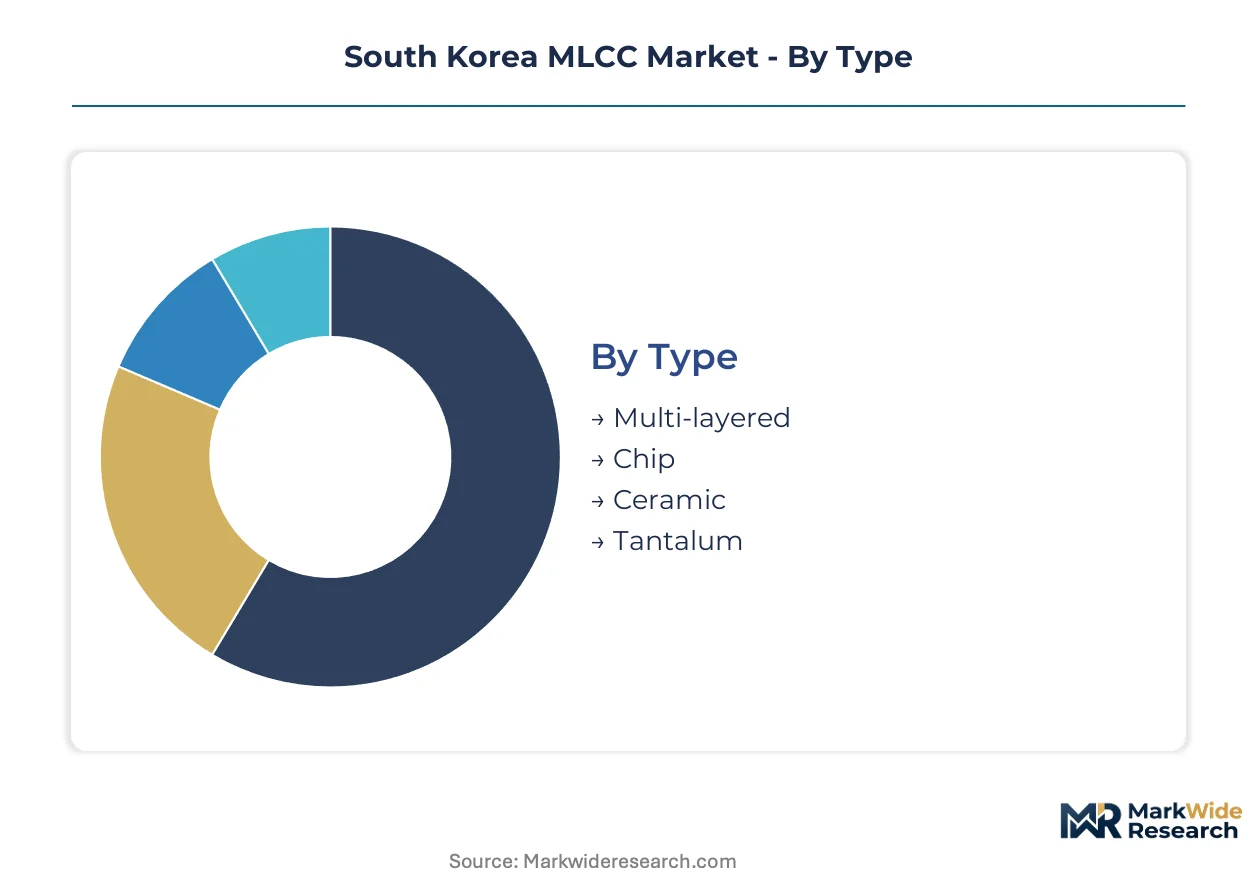
MLCC procurement patterns in South Korea diverge sharply across dielectric formulations and qualification tiers. Hyundai Motor Group's tier-one suppliers now specify capacitance-voltage combinations that eliminate commodity suppliers from automotive RFQs.
Type:
Capital intensity peaks in ceramic formulations requiring proprietary co-firing furnaces and sub-micron dielectric deposition systems.
- Multi-layered:These devices stack 500+ alternating ceramic and electrode layers into monolithic chips using precision tape-casting and high-temperature co-firing. Samsung Electro-Mechanics deploys these for Hyundai Motor Group's inverter DC-link applications, where layer thinning below 0.3 micrometers demands captive process expertise.
- Chip:Surface-mount ceramic capacitors dominate high-volume consumer electronics procurement from Gyeonggi-do module suppliers. Samsung Electro-Mechanics and LG Innotek compete on dimensional tolerance adherence to KATS specifications for export-bound shipments.
- Ceramic:Barium titanate-based Class II formulations anchor high-permittivity applications across South Korea's telecommunications infrastructure.
- Tantalum:Polymer and manganese-dioxide cathode variants serve niche military and medical electronics requiring stable capacitance under bias.
Most installed capacity flows through Multi-layered. Expansion is steepest in Chip.
End User:
Application qualification timelines separate automotive-grade suppliers from consumer electronics commodity producers.
- Automotive:AEC-Q200 qualification and MFDS material safety compliance now gate entry to Hyundai Motor Group's tier-one supply base. Onboard charger and inverter density multiplication in 800V architectures consumes ultra-high capacitance grades at premium pricing.
- Consumer Electronics:Smartphone RF chain miniaturization drives demand for ultra-miniature dielectric formulations in Samsung Electronics' Galaxy device supply chain. Taiyo Yuden sustains R&D intensity for 5G millimeter-wave filter applications.
- Industrial:Motor drive and power supply applications favor medium-voltage ratings with extended temperature stability.
- Telecommunications:Base station power amplifiers and network infrastructure equipment specify high-reliability grades for continuous operation.
Procurement volume concentrates in Automotive. Margin expansion is climbing the fastest in Consumer Electronics.
Capacitance:
Dielectric layer thickness and active area geometry determine which capacitance tiers Korean formulators can manufacture profitably.
- Ultra-High:Grades exceeding 100 microfarads in compact footprints require atomic-level thickness control and proprietary co-firing expertise. Hyundai Motor Group's tier-one module suppliers specify these for 800V inverter DC-link applications, compressing qualification windows for domestic competitors.
- High:Capacitance ranges from 10-100 microfarads serve industrial motor drives and telecommunications power supplies with moderate space constraints.
- Medium:Standard decoupling and filtering applications across consumer electronics occupy the highest shipment volumes.
- Low:Pico-farad ranges dominate high-frequency RF applications in 5G handsets and millimeter-wave radar modules.
Production yield challenges concentrate in Ultra-High. Customer specification migration is accelerating fastest toward High.
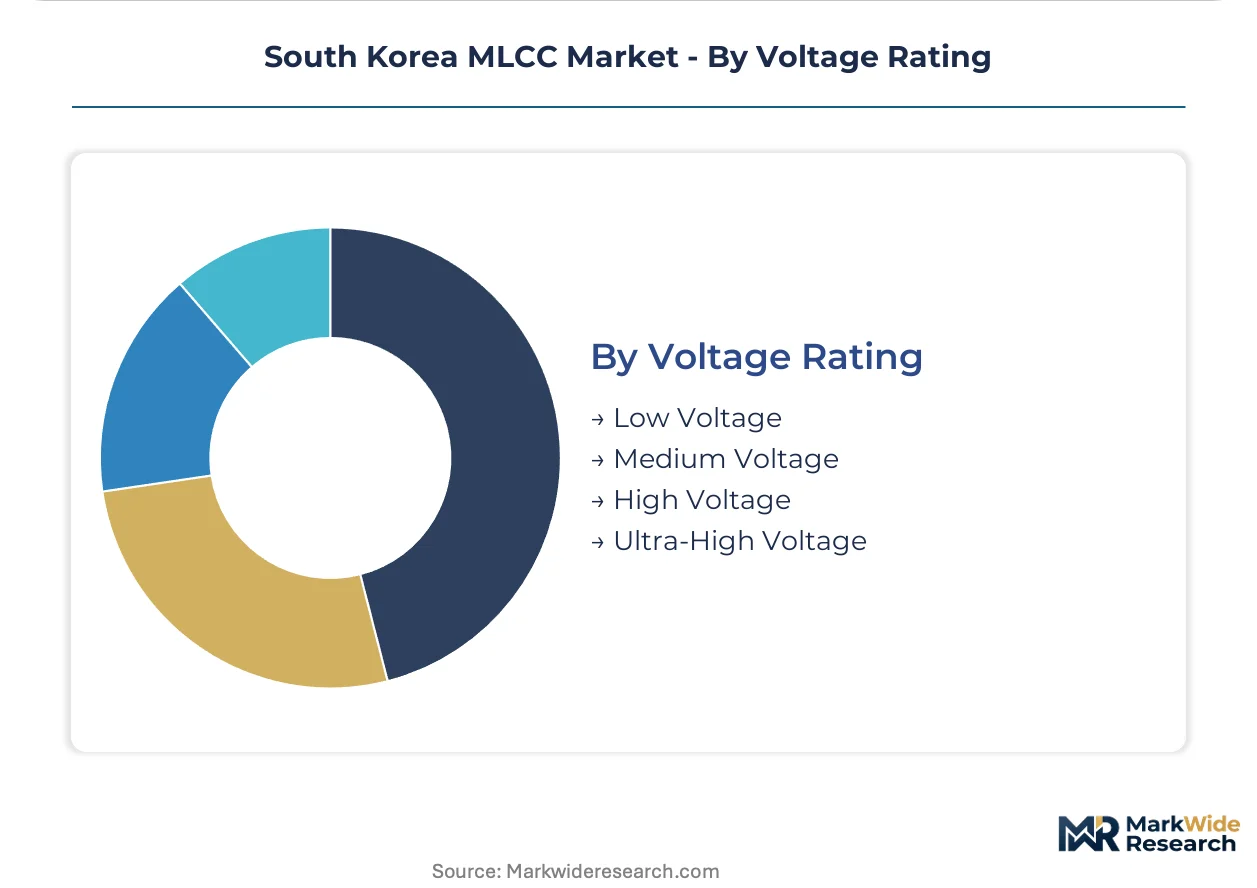
Voltage Rating:
Thermal management and dielectric breakdown resistance define competitive separation across voltage tiers.
- High Voltage:Ratings from 500V to 3kV serve EV onboard chargers and DC-DC converters where electric field stress demands optimized barium titanate formulations. Samsung Electro-Mechanics leverages its Gyeonggi-do fabrication complex for these automotive-qualified grades.
- Ultra-High Voltage:Specialized ceramic formulations above 3kV serve industrial power electronics and grid infrastructure with limited domestic Korean production.
- Medium Voltage:50-500V ratings balance cost and performance across industrial motor drives and commercial power supplies.
- Low Voltage:Sub-50V ratings saturate consumer electronics and handheld device markets with commodity pricing pressure.
Domestic fabrication investment concentrates in High Voltage. Technical qualification requirements are expanding most quickly in Ultra-High Voltage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands dielectric powder synthesis expertise while South Korea dominates automotive-grade MLCC fabrication for EV platforms. China scales commodity-grade capacity fastest. Taiwan anchors RF component miniaturization for consumer electronics supply chains.
Japan
Murata Manufacturing and Taiyo Yuden drive ultra-miniature dielectric R&D for 5G millimeter-wave applications. METI industrial policy directs material science investments toward next-generation ceramic formulations. Kyoto and Nagaoka production clusters concentrate atomic-layer deposition expertise for sub-micron layer stacks.
China
Yageo Corporation and domestic suppliers expand medium-voltage capacity for industrial motor drives and telecommunications infrastructure. MIIT standards enforcement tightens dielectric powder purity requirements for domestic circulation. Shenzhen and Dongguan electronics corridors absorb commodity-grade MLCC output for consumer device assembly.
Taiwan
Walsin Technology Corporation anchors RF chain component supply for smartphone original design manufacturers. National development programs prioritize advanced ceramic material autonomy. Hsinchu Science Park integration with semiconductor foundry output enables system-in-package co-development.
United States
Vishay Intertechnology and defense contractors sustain demand for high-reliability tantalum and ceramic grades in aerospace applications. DOD supply chain security directives accelerate onshore qualification programs for critical electronic components. Arizona and Texas semiconductor corridors attract MLCC module packaging investment.
Germany
Automotive electronics tier-ones specify AEC-Q200 qualified components for inverter and powertrain modules in premium EV platforms. KBA type-approval processes extend validation timelines for imported ceramic capacitors. Bavaria's automotive supplier cluster drives procurement concentration toward integrated European MLCC networks.
South Korea MLCC Market Competitive Landscape
Top-tier vendors anchor automotive-grade qualification programs, while mid-tier fabricators compete on consumer electronics volume and dimensional tolerance adherence. The vendor base stratifies across integrated material-to-component manufacturers, specialized ceramic formulators, and commodity-scale assemblers. Three archetypes dominate: captive suppliers serving domestic EV platforms, RF miniaturization specialists, and diversified passive component conglomerates. Capacity reservation agreements and atomic-layer deposition licensing represent the dominant competitive moves.
Within the integrated manufacturing tier, Samsung Electro-Mechanics and LG Innotek exemplify Korean fabricators leveraging Gyeonggi-do production concentration for automotive customer proximity. Taiyo Yuden represents the specialized dielectric R&D archetype, occupying a position in ultra-miniature formulations for millimeter-wave applications. These three entities anchor distinct competitive vectors: captive supply chain integration, domestic platform qualification, and RF performance specialization.
| Leading Market Players |
|---|
| Taiyo Yuden |
| LG Innotek |
| Samsung Electro-Mechanics |
| Yageo Corporation |
| Vishay Intertechnology |
| Murata Manufacturing |
| Kyocera |
| Walsin Technology Corporation |
| TDK Corporation |
| Others |
Pricing and Supply Chain Analysis
Barium titanate dielectric powder costs cascade through South Korea's MLCC fabrication tiers, with Japanese and Chinese material suppliers commanding premium pricing for high-purity formulations while domestic formulators absorb margin compression through layer-thinning process investments.
Pricing Analysis
Capacity additions in China are reshaping price floors for medium-voltage consumer-grade MLCCs, forcing Korean fabricators toward automotive-qualified premium tiers. Pricing stratifies across AEC-Q200 certified automotive grades, industrial reliability tiers, and commodity consumer electronics segments. Cost compression in standard-grade dielectrics intensifies because Chinese suppliers scale tape-casting output for smartphone module suppliers. Tier-one automotive electronics buyers exhibit the lowest price sensitivity due to qualification lock-in, while consumer electronics procurement teams drive aggressive spot-market negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Hyundai Motor Group's tier-one module suppliers mandate qualified backup suppliers for high-voltage inverter-grade MLCCs, constraining single-source leverage. Geographic supply concentration centers on Japan for dielectric powder synthesis expertise, China for commodity-grade ceramic capacity, and South Korea for automotive-qualified fabrication. Raw material dependencies rest on barium titanate precursors, nickel electrode pastes, and copper terminal plating chemistries. Single-source vulnerability concentrates in sub-micron dielectric deposition equipment. Distribution runs through Gyeonggi-do semiconductor cluster direct-to-module supplier contracts, bypassing traditional distributor channels for qualified automotive grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
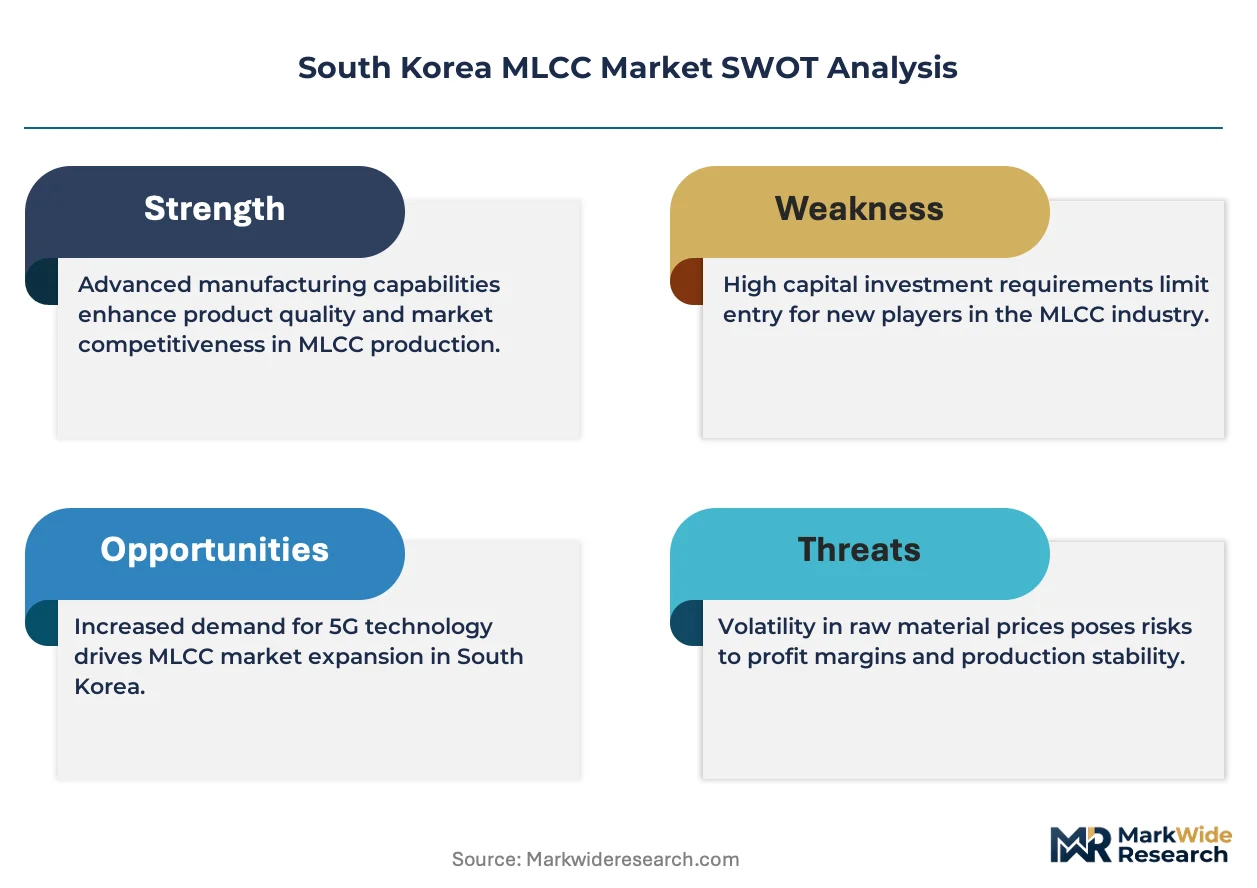
South Korea's MLCC market offers margin expansion through dielectric layer thinning below 0.3 micrometers, where proprietary co-firing expertise commands premium pricing from captive automotive customers.
For Market Incumbents: Deepen captive supply chain integration into barium titanate precursor sourcing to offset Japanese material supplier pricing power. Expand atomic-layer deposition licensing programs to tier-two domestic formulators before Chinese competitors replicate sub-micron layer stack capabilities. Lock in long-term capacity reservation agreements with Hyundai Motor Group's designated tier-ones to defend against emerging RF miniaturization specialists. For New Entrants and Emerging Players: MFDS material safety directives in South Korea open a window for specialized compliance service providers to accelerate qualification timelines for imported dielectric formulations. Target white-space in ultra-high voltage industrial grades above 3kV where domestic Korean production remains limited. Pursue joint development agreements with Sejong-based automotive module suppliers seeking second-source qualification for 800V inverter applications. For Investors and Strategic Acquirers: Consolidation pressure builds where co-firing process engineering talent scarcity constrains yield improvement programs across domestic fabrication lines. Mid-term viability through the next decade hinges on positioning ahead of system-in-package integration trends that absorb discrete MLCC value into domestic foundry output. Acquisition target archetype: specialized ceramic formulators with existing KATS dimensional tolerance certification and underutilized co-firing furnace capacity. Signal to watch: Seoul's national semiconductor cluster incentives redirecting captive capacity toward co-packaging with domestic foundry output.| Strategic Initiative | Industry Significance |
|---|---|
| Atomic-Layer Deposition Licensing | Proprietary thickness control technology transfers co-firing expertise to qualified domestic partners. |
| Sejong Production Base Expansion | Tax-advantaged greenfield capacity anchors automotive-grade qualification programs for export-bound tier-ones. |
| Dielectric Powder Sourcing Diversification | Reduced dependence on Japanese and Chinese barium titanate suppliers stabilizes input cost volatility. |
| System-in-Package Integration Partnership | Co-development with domestic foundries captures module-level value beyond discrete component sales. |
| AEC-Q200 Accelerated Qualification Program | Compressed validation timelines compress procurement windows for Hyundai Motor Group inverter applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with MLCC procurement managers at Hyundai Motor Group tier-one suppliers, dielectric formulation chemists at Gyeonggi-do fabrication facilities, and KATS certification engineers with secondary validation through SEC filings from Samsung Electro-Mechanics and LG Innotek, Korean customs trade data for barium titanate powder imports, and MFDS material safety directive documentation. Bottom-up capacity modeling and top-down demand estimation from EV platform production schedules were triangulated against foundry output projections.
Segment-weighting applied differential growth assumptions across dielectric formulations, voltage ratings, and end-user qualification tiers throughout the forecast period. The analytical framework modeled capacitance-voltage combinations, automotive versus consumer electronics procurement splits, and domestic versus export-bound shipment ratios. CAGRs were derived from layer-thinning technology diffusion curves and 800V architecture adoption patterns in premium EV segments. Forecast inputs included K-Battery strategy localization mandates and MFDS compliance timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under barium titanate supply disruption or co-firing equipment export control scenarios. Deviation in Seoul's national semiconductor cluster incentive allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
FPGA Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Global Precision Parts Market