
 IoT Processor Market | 2026-2036
IoT Processor Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Processor Market Foresight
The gap between premium automotive-grade processors and commodity smart home chips is shifting procurement strategies across the supply chain. Qualcomm Technologies leverages its modem-processor integration to dominate cellular IoT sockets in industrial gateways. NXP Semiconductors anchors its position through automotive safety-certified portfolios that sustain long design-in cycles. MediaTek competes aggressively on cost-optimized System on Chip solutions for consumer electronics volume tiers.
An IoT processor is a dedicated integrated circuit designed to execute computational workloads for connected devices, typically fabricated on process nodes ranging from 22nm to 5nm with power envelopes below 5W for battery-constrained deployments. Its primary purpose is to enable local data processing, protocol translation, and real-time decision-making at the network edge without continuous cloud dependency. Edge Computing represents the fastest-growing technology dimension as latency-sensitive applications in autonomous systems and predictive maintenance push inference closer to sensors. System on Chip architectures capture the deepest margin pools by consolidating radio, memory, and processing cores onto single die, while Microcontrollers retain volume leadership in cost-constrained smart metering and basic sensor nodes.
The FCC in the United States mandates RF emissions compliance for wireless-enabled processors, while the EU AI Act imposes algorithmic transparency requirements on edge AI chip deployments in European markets. ETSI standards for low-power wide-area networks further constrain hardware design choices for cellular IoT processors sold across EU member states. Stakeholders must monitor how divergent cybersecurity certification schemes between the United States and European Union fragment platform development roadmaps and test qualification budgets.
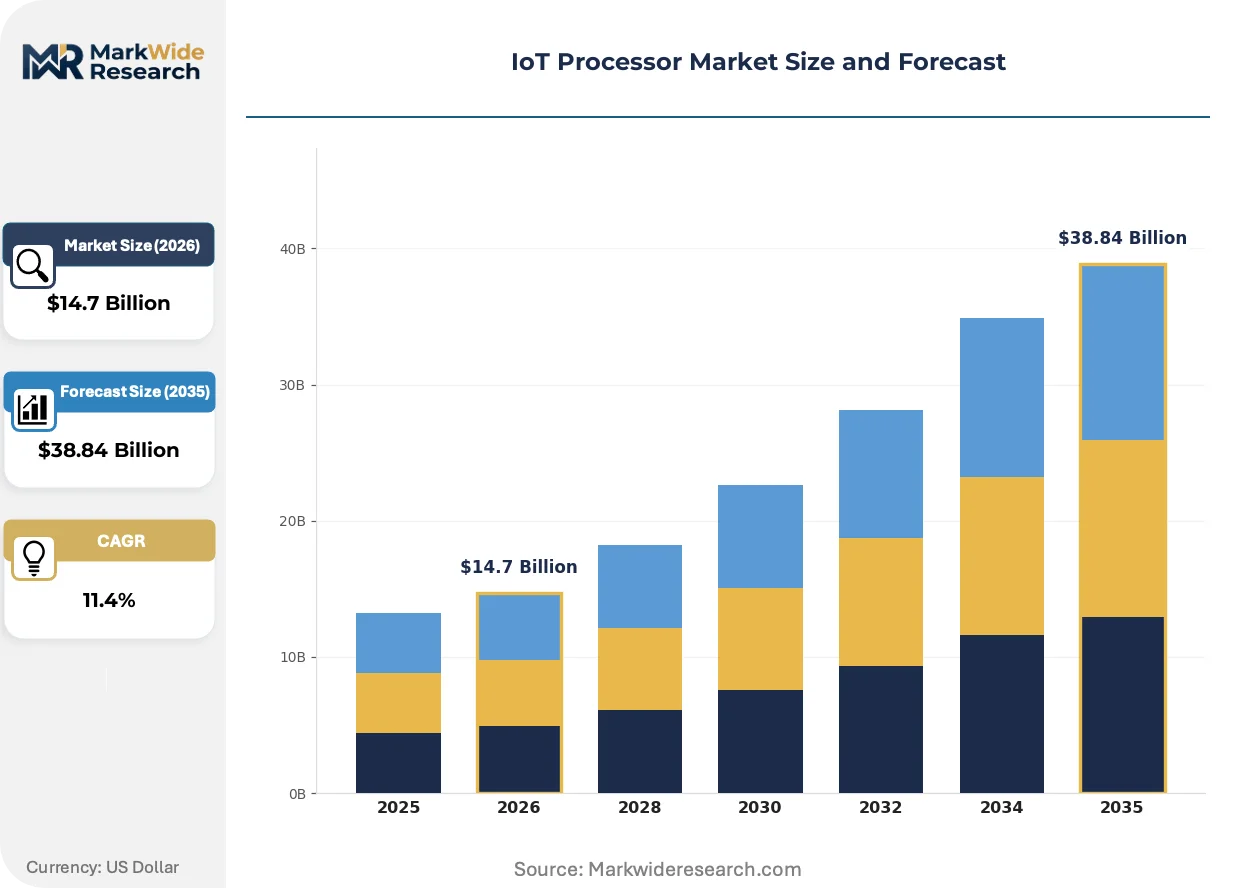
Market Dynamics
Edge computing workloads are compressing cloud dependency and forcing processor architectures toward on-die inference acceleration, while Taiwan's foundry concentration creates supply vulnerability for automotive and industrial buyers seeking qualified capacity.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European deployments now require documented edge AI decision pathways, pulling certified processor volumes into industrial automation and healthcare monitoring applications.
- Automotive functional safety certification:ISO 26262 ASIL-D requirements for autonomous driving systems extend design-in cycles and lock premium socket positions for qualified semiconductor suppliers.
- LPWAN protocol standardization:ETSI harmonization across EU member states reduces hardware fragmentation for cellular IoT processors serving smart metering and agricultural sensor networks.
Market Restraints
- Advanced node capacity concentration:Sub-7nm fabrication for high-performance edge AI processors depends on TSMC's Hsinchu and Taichung facilities, creating geographic single-source exposure.
- REACH substance restrictions:ECHA candidate list expansions for lead-free solder alternatives and halogen-free substrates constrain material choices and extend qualification timelines for European-bound products.
- Arm architecture licensing costs:Per-unit royalty structures for Cortex-M and Cortex-A cores compress margins on high-volume microcontroller deployments in cost-constrained consumer electronics.
Strategic Opportunities
- RISC-V open instruction set architecture:Custom core development without licensing fees enables differentiated security features and vertical optimization for industrial gateway and medical device applications.
- India PLI scheme for semiconductor manufacturing:Gujarat and Tamil Nadu fab incentives attract assembly and test investments, creating regional supply alternatives for domestic IoT device production.
- Digital twin integration with predictive maintenance:Real-time vibration and thermal inference at the edge opens processor sockets in heavy machinery and energy infrastructure previously served by cloud-only analytics.
Industry Challenges
- Multi-domain safety certification complexity:Automotive, medical, and industrial IoT processors now require simultaneous ISO 26262, IEC 62304, and IEC 61508 compliance, stretching engineering validation resources.
- Legacy system integration friction:Brownfield industrial deployments with Modbus and PROFIBUS fieldbuses demand protocol translation silicon that adds die area and power overhead without advancing core compute performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Processor Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, System on Chip, Digital Signal Processors, Field Programmable Gate Arrays Technology: Wireless Communication, Short-Range Communication, Cloud-Based Processing, Edge Computing End User: Consumer Electronics, Automotive, Industrial Automation, Smart Home Devices Application: Wearable Technology, Smart Metering, Precision Agriculture, Health Monitoring |
| Companies Covered | Qualcomm Technologies, Intel Corporation, Texas Instruments, NXP Semiconductors, MediaTek, Samsung Electronics, STMicroelectronics, Analog Devices, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Processor Market Shifts & Advancements
Heterogeneous integration is collapsing discrete component boundaries as chiplets, memory stacks, and radio modules merge onto single packages, redefining competitive advantage around system-level optimization rather than core frequency.
Chiplet-based modular architectures are unifying previously separate compute, memory, and I/O dies into interoperable 2.5D and 3D packages. Automotive OEMs in Germany and Japan are accelerating adoption for software-defined vehicle platforms that demand mid-cycle hardware upgradability. This unifying approach compresses time-to-market for domain-specific accelerators while fragmenting the traditional merchant silicon vendor landscape.
REACH substance restriction expansions are forcing substrate and interconnect material substitutions across European-bound processor shipments. ECHA's 2024 candidate list additions for persistent organic pollutants now cover flame retardants common in high-reliability packaging, compelling foundries to requalify mold compounds. Automotive safety-certified portfolios face the longest requalification timelines, creating temporary supply asymmetry between compliant and non-compliant product lines.
Contract manufacturers are consolidating procurement authority for processor selection away from OEM engineering teams toward dedicated supply chain functions with total-cost-of-ownership mandates. Foxconn and Jabil now specify silicon for a growing share of smart home and enterprise gateway builds based on logistics integration and firmware support terms rather than raw performance metrics. This concentration is most visible in Taiwan's electronics manufacturing cluster serving North American and European brand customers.
IoT Processor Market Segmentation
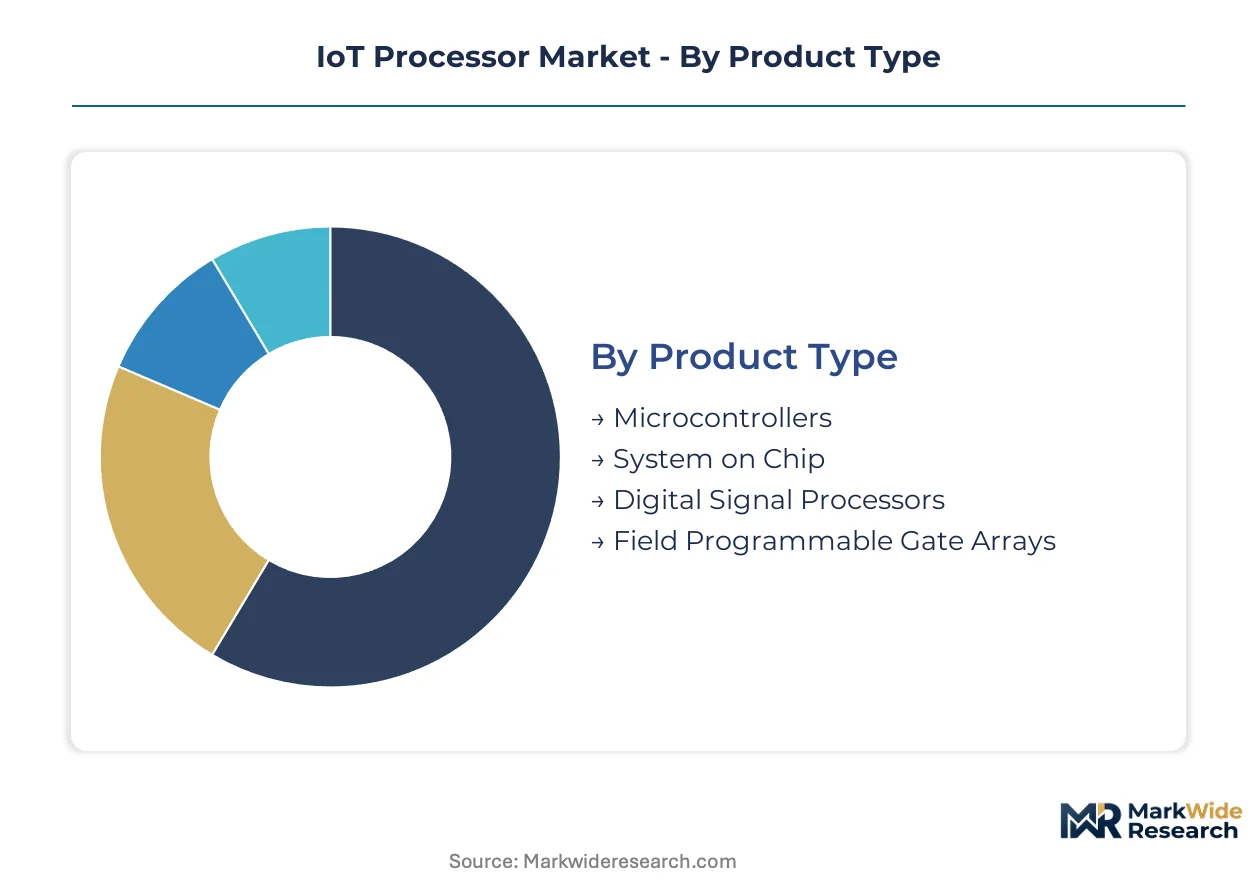
Processor selection in IoT deployments hinges on power budgets, latency requirements, and certification complexity. Segmentation reveals how automotive safety mandates and edge inference workloads pull silicon architectures in divergent directions.
Product Type:
Fab capacity for automotive-grade processors concentrates at TSMC's specialty nodes and Samsung's Austin facility, while microcontroller volumes flow through 40nm-90nm legacy lines.
- System on Chip:Monolithic integration of CPU, GPU, NPU, and radio subsystems onto single die eliminates board-level component count. German automotive OEMs and Japanese tier-1 suppliers concentrate procurement here for software-defined vehicle platforms demanding mid-cycle upgradability.
- Microcontrollers:Arm Cortex-M and RISC-V cores dominate this cost-optimized category with flash memory embedded alongside processing units. Smart metering deployments across EU member states and agricultural sensor networks in India drive volume concentration, though per-unit margins compress under royalty burdens.
- Digital Signal Processors:Specialized multiply-accumulate architectures accelerate audio and vibration analysis at the edge.
- Field Programmable Gate Arrays:Reconfigurable logic fabric enables protocol adaptation for brownfield industrial integration.
Today's leader: System on Chip. Tomorrow's challenger: Microcontrollers.
Technology:
Cost tiers separate cloud-dependent analytics from local inference, with latency-sensitive applications commanding premium silicon.
- Edge Computing:On-die neural accelerators execute inference within 10ms response windows for autonomous systems and predictive maintenance. Taiwan's foundry cluster processes the bulk of these orders, though automotive qualification cycles extend delivery timelines.
- Cloud-Based Processing:Thin-client architectures stream sensor data to centralized infrastructure, minimizing local compute requirements. Smart home hubs and basic wearables concentrate demand here where connectivity reliability exceeds local processing needs.
- Wireless Communication:Integrated cellular and LPWAN modems consolidate RF front-ends with baseband processing.
- Short-Range Communication:Bluetooth LE and Zigbee protocol stacks target battery-constrained proximity networks.
Edge Computing commands the steepest expansion trajectory as latency requirements harden across industrial and automotive specifications.
End User:
Customer type dictates certification burden, with automotive and medical buyers requiring multi-standard compliance that consumer electronics avoids.
- Automotive:ISO 26262 ASIL-D functional safety certification locks suppliers into extended validation cycles. NXP and Infineon anchor this segment through safety-certified portfolios that sustain decade-long production commitments from German and Japanese OEMs.
- Industrial Automation:Simultaneous IEC 61508 and cybersecurity certification requirements strain engineering resources. Predictive maintenance and digital twin integration pull edge-capable silicon into heavy machinery and energy infrastructure.
- Consumer Electronics:Cost-optimized SoC solutions from MediaTek and Unisoc dominate high-volume tiers with minimal certification overhead.
- Smart Home Devices:Matter protocol standardization is consolidating previously fragmented hardware requirements.
Automotive absorbs the deepest engineering investment per socket. Industrial Automation offers the fastest path to volume scaling for qualified suppliers.
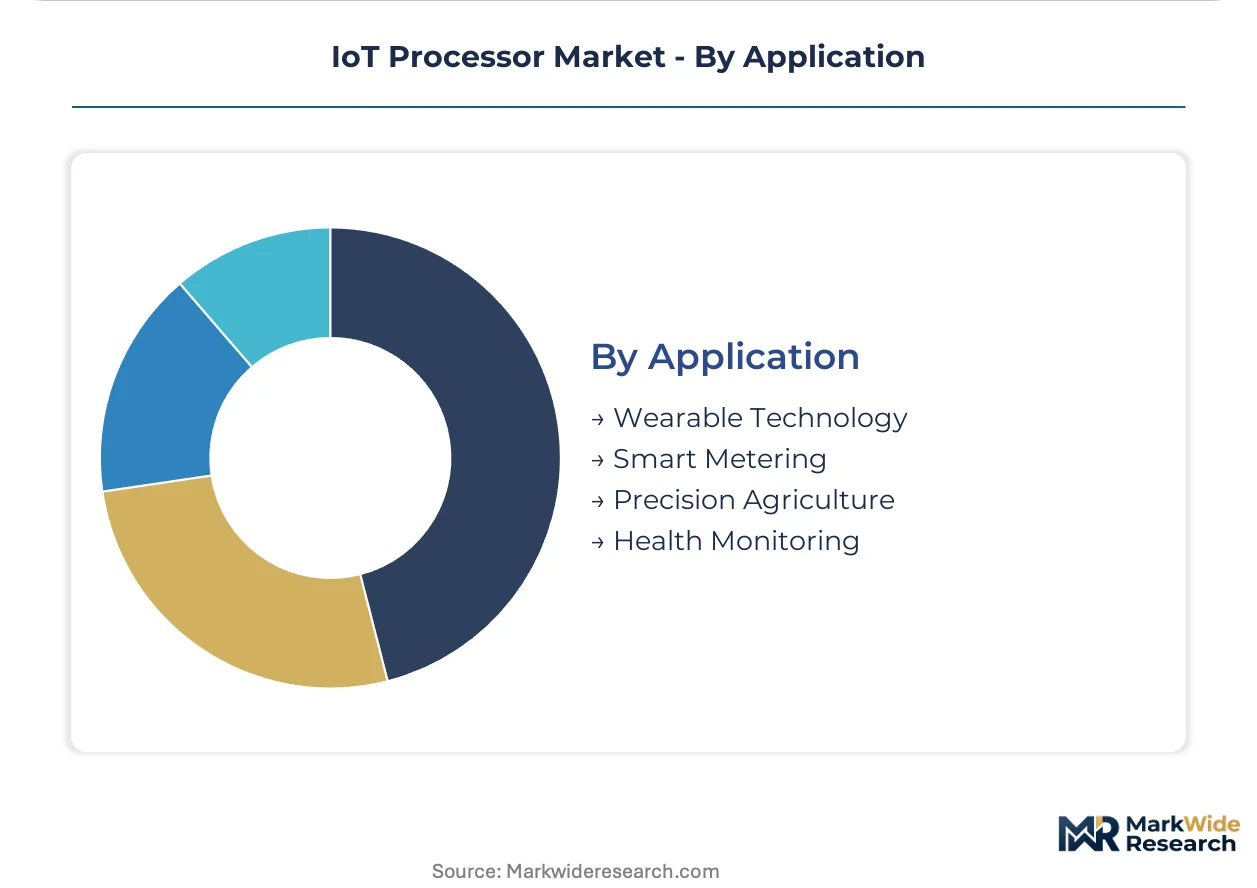
Application:
Volume maturity separates established metering infrastructure from emerging health and agricultural deployments.
- Smart Metering:ETSI-standardized LPWAN protocols enable decade-long battery life for utility deployments across EU member states. Sub-GHz radio integration and minimal processing requirements keep microcontroller architectures dominant here.
- Health Monitoring:FDA and EMA regulatory pathways for connected medical devices impose IEC 62304 software lifecycle requirements. Continuous glucose monitors and cardiac event recorders concentrate demand for ultra-low-power edge inference.
- Wearable Technology:Fitness bands and smartwatches balance display refresh demands against battery constraints.
- Precision Agriculture:Soil moisture and crop health sensors deploy across vast geographies with intermittent connectivity.
Smart Metering represents the volume anchor. Health Monitoring climbs fastest as regulatory clarity emerges for connected diagnostic devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Taiwan, Germany, and California anchor semiconductor design for edge computing workloads. Foundry capacity concentrates in Hsinchu and Taichung, while automotive OEMs in Stuttgart and Nagoya drive safety-certified processor demand.
United States
FCC RF emissions mandates and FDA medical device pathways shape processor certification for health monitoring and industrial gateway deployments. The IRA clean energy incentives pull edge-capable silicon into grid infrastructure and predictive maintenance applications. Austin's Samsung fab and Intel's Arizona expansion anchor domestic foundry investments for automotive-qualified capacity.
Germany
KBA automotive safety requirements and EU AI Act algorithmic transparency obligations extend validation cycles for autonomous driving processors. REACH substance restrictions on halogen-free substrates constrain packaging material choices for European-bound shipments. Stuttgart and Munich engineering centers concentrate R&D for ISO 26262 ASIL-D certified portfolios serving BMW, Mercedes-Benz, and Volkswagen platforms.
Japan
METI semiconductor revitalization funding and JIS industrial standards anchor domestic production for robotics and factory automation processors. PMDA regulatory clarity for connected medical devices opens sockets in continuous glucose monitors and cardiac event recorders. Nagoya and Tokyo design houses concentrate automotive safety engineering for Toyota, Honda, and Nissan tier-1 supply chains.
China
MIIT domestic semiconductor self-sufficiency targets and GB standards for industrial IoT reshape procurement toward local processor architectures. Dual carbon goals accelerate edge computing deployment for energy infrastructure monitoring and smart grid optimization. Yangtze River Delta fabs in Shanghai and Wuxi concentrate mature-node capacity for microcontroller volumes in smart metering and agricultural sensor networks.
India
PLI scheme incentives for semiconductor assembly and test attract investments in Gujarat and Tamil Nadu facilities. BIS certification requirements and CEA smart grid mandates drive microcontroller demand for utility deployments and renewable energy integration. Bangalore and Hyderabad engineering hubs concentrate embedded software development for industrial automation and medical device applications.
IoT Processor Market Competitive Landscape
Top-tier vendors anchor automotive safety-certified sockets, while cost-optimized consumer electronics specialists compete on volume scale. The market structures around three tiers: premium functional safety providers, mid-range industrial generalists, and high-volume microcontroller suppliers. Strategic archetypes include modem-processor integrators, safety-certified portfolio holders, and open-architecture RISC-V advocates. Competitive moves concentrate on foundry capacity reservations and multi-domain certification stacking.
Within the modem-integration tier, Qualcomm Technologies exemplifies cellular IoT gateway positioning. NXP Semiconductors and Infineon Technologies occupy the automotive safety-certified segment with ISO 26262 ASIL-D portfolios. MediaTek represents cost-optimized System on Chip scale for consumer electronics volume tiers.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| Intel Corporation |
| Texas Instruments |
| NXP Semiconductors |
| MediaTek |
| Samsung Electronics |
| STMicroelectronics |
| Analog Devices |
| Infineon Technologies |
| Others |
Supply & Pricing Matrix
Chiplet-based modular architectures are collapsing monolithic die economics while concentrating advanced packaging capacity in Taiwan and South Korea, simultaneously raising R&D amortization costs and tightening supply control among vertically integrated foundry operators serving automotive and industrial buyers.
Pricing Analysis
Bundled software-hardware service contracts dominate automotive and industrial sockets, while unbundled per-unit pricing prevails in consumer microcontroller tiers. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive processors from industrial-grade generalists and cost-optimized consumer SoCs. Price differentiation stems from certification grade and volume scale, with automotive buyers absorbing 40-60% premiums for functional safety documentation. Cost compression in consumer tiers is intensifying because RISC-V alternatives are displacing Arm royalty structures. Smart home device manufacturers exhibit highest price sensitivity, while German automotive OEMs prioritize supply security over unit economics.
Supply Chain Analysis
Reverse-logistics flows for automotive processors remain underdeveloped, creating stranded value in end-of-life safety-certified silicon that remanufacturing infrastructure could recover. Front-end fabrication concentrates in Taiwan, South Korea, and the United States, while back-end assembly and test spreads across Malaysia, Vietnam, and Mexico. Raw material dependencies include silicon wafers, advanced photoresists, and halogen-free substrate laminates constrained by REACH candidate list expansions. Single-source vulnerability at TSMC's Hsinchu and Taichung facilities for sub-7nm edge AI processors exposes automotive qualification timelines to geographic disruption. Distribution runs through authorized distributors serving tier-1 suppliers, with direct foundry relationships reserved for high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT processor market functions as a regulatory compounder where EU AI Act algorithmic transparency mandates and ISO 26262 functional safety requirements simultaneously extend validation cycles and deepen incumbent moats.
For Market Incumbents: Anticipate RISC-V open-architecture challengers eroding Arm royalty-dependent microcontroller margins by accelerating custom core development for industrial gateway sockets. Defensive consolidation should prioritize backward integration into advanced packaging capacity in Taiwan and South Korea, while stacking multi-domain certifications across automotive, medical, and industrial standards to extend design-in cycle capture. For New Entrants and Emerging Players: The price-point gap between premium ASIL-D automotive processors and economy consumer SoCs opens white-space targeting for mid-tier industrial automation sockets requiring IEC 61508 compliance without full automotive validation. India's PLI scheme assembly incentives offer the most penetrable geography for domestic IoT device production. A firmware-support-centric go-to-market angle can displace commodity procurement from contract manufacturers seeking reduced integration friction. For Investors and Strategic Acquirers: Valuations sit cheapest among RISC-V IP specialists with vertical optimization capabilities for medical device and energy infrastructure applications. Long-term viability over the coming decade hinges on regulatory certification stacking rather than raw performance benchmarks. Acquisition targets should display simultaneous ISO 26262 and IEC 62304 pathway progress. Monitor EU AI Act enforcement actions against non-compliant edge AI deployments as the signal for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Domain Certification Stacking | Simultaneous ISO 26262, IEC 62304, and IEC 61508 compliance deepens socket lock-in for automotive and medical buyers. |
| Chiplet Packaging Partnership | 2.5D and 3D integration alliances with TSMC or Samsung enable mid-cycle hardware upgradability for software-defined vehicles. |
| RISC-V Core Development | Custom instruction set architectures eliminate Arm royalty burdens and enable differentiated security features for industrial gateways. |
| India PLI Scheme Participation | Gujarat and Tamil Nadu assembly investments create regional supply alternatives for domestic IoT device production. |
| Digital Twin Integration | Edge inference capabilities for predictive maintenance open processor sockets in heavy machinery previously served by cloud analytics. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with automotive platform engineers, industrial automation procurement leads, semiconductor foundry planning officers, and medical device regulatory affairs specialists combined with secondary validation from SEC semiconductor filings, ETSI standardization documents, and customs trade data for processor import flows. Triangulation between bill-of-materials analysis for connected vehicle platforms and wafer start disclosures from Taiwan's foundry cluster ensures volume and value consistency across the projection horizon.
Input-output matrix framing maps processor architecture selection to application-specific latency requirements, power budgets, and certification burdens. Segmentation dimensions modeled include product type, edge computing versus cloud-dependent technology tiers, automotive-industrial-consumer end-user categories, and smart metering-health monitoring-wearable application clusters. CAGRs were derived from regression analysis of historical procurement patterns and foundry capacity expansion announcements, with automotive safety certification cycle extensions and EU AI Act compliance timelines as industry-specific forecast inputs.
Caveats apply where REACH substance restriction expansions or Taiwan geopolitical developments could materially shift the outlook for European-bound shipments and advanced node availability. Practitioners should monitor ECHA candidate list updates and TSMC specialty node allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
Global Heterogeneous Mobile Processing and Computing Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
Europe Neuromorphic Chip Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Superconducting Quantum Chip Market
Chipset and Processors
System on Chip (Soc) Market