
 Photosensitive Semiconductor Device Market | 2026-2036
Photosensitive Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Photosensitive Semiconductor Device Market Analytics
Market Context
Japan is rewriting competitive dynamics in photosensitive semiconductor fabrication through expanded cleanroom capacity in Hamamatsu and Kyushu. Sony Group Corporation leverages proprietary stacked CMOS architectures to sustain imaging leadership across smartphone and industrial vision systems. Samsung Electronics Co., Ltd. anchors high-volume image sensor supply through captive foundry scale in Pyeongtaek. Hamamatsu Photonics K.K. dominates photodiode production for medical and scientific instrumentation, while STMicroelectronics N.V. competes across automotive-grade optical sensors with European OEM qualification.
Technical Definition and Segment Structure
Photosensitive semiconductor devices convert incident photon energy into electrical signals through p-n junction excitation, with spectral sensitivity governed by bandgap engineering in silicon, indium gallium arsenide, or silicon carbide substrates. These components serve as the elemental detection layer in cameras, optical communication receivers, environmental monitoring equipment, and biomedical imaging platforms. Image sensors command the largest value pool within product type segmentation, while InGaAs technology captures premium margins in near-infrared industrial inspection and telecom applications. Medical device demand for high-sensitivity photodiodes is expanding fastest, though CMOS technology maintains volume leadership across consumer electronics and automotive vision systems.
Regulatory Environment and Outlook
FDA 510(k) clearance pathways shape design controls for photodiodes embedded in diagnostic imaging and pulse oximetry equipment, while EPA energy efficiency mandates constrain standby power budgets for optical sensors in building automation. Japan's METI funds domestic semiconductor material sovereignty programs that prioritize photosensitive device wafer supply chain resilience. Stakeholders must monitor how RoHS substance restrictions and emerging EU AI Act conformity requirements for machine vision systems reshape component qualification timelines and regional sourcing decisions.
Market Dynamics
Automotive LiDAR qualification timelines are compressing development cycles across the photosensitive semiconductor supply base, forcing foundries to synchronize process maturity with tier-one OEM validation gates.
Growth Catalysts
- Automotive Safety Mandates:NHTSA automatic emergency braking requirements and Euro NCAP vision-based scoring protocols are embedding CMOS image sensors into every new vehicle platform.
- Near-Infrared Industrial Inspection:InGaAs photodiode arrays are displacing silicon alternatives in semiconductor wafer defect detection systems across East Asian fabrication facilities.
- Japan's METI Semiconductor Resilience Program:Domestic wafer supply subsidies are expanding photodiode production capacity in Kyushu and Hamamatsu manufacturing clusters.
Market Restraints
- Indium Supply Concentration:InGaAs substrate production depends on Chinese indium refining capacity, creating single-source vulnerability for near-infrared sensor manufacturers.
- Cleanroom Capital Intensity:Stacked CMOS architectures require Class 10 cleanroom investments exceeding foundry depreciation cycles for sub-28nm nodes.
- RoHS Exemption Uncertainty:ECHA cadmium restrictions threaten quantum dot photodetector formulations in consumer imaging applications.
Strategic Opportunities
- India PLI Scheme for Electronics:Component-level incentives are attracting photodiode packaging investments for medical device exports to ASEAN markets.
- Hyperspectral Agriculture:Silicon carbide photodetectors paired with edge AI processors are enabling real-time crop stress monitoring in Brazilian and Australian precision farming operations.
- EU AI Act Conformity:Machine vision system certification requirements are creating premium tiers for automotive-grade optical sensors with documented bias testing.
Industry Challenges
- Compound Semiconductor Talent Gap:InGaAs epitaxy specialists command salary premiums exceeding 40% above silicon process engineers, constraining foundry expansion timelines.
- FDA 510(k) Iteration Cycles:Photodiode design modifications for pulse oximetry applications trigger 12-18 month requalification delays, freezing component specifications mid-development.
- Multi-Die Integration Complexity:Stacked CMOS bonding yields degrade when combining heterogeneous substrates from different wafer sources, requiring captive supply chain restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photosensitive Semiconductor Device Market |
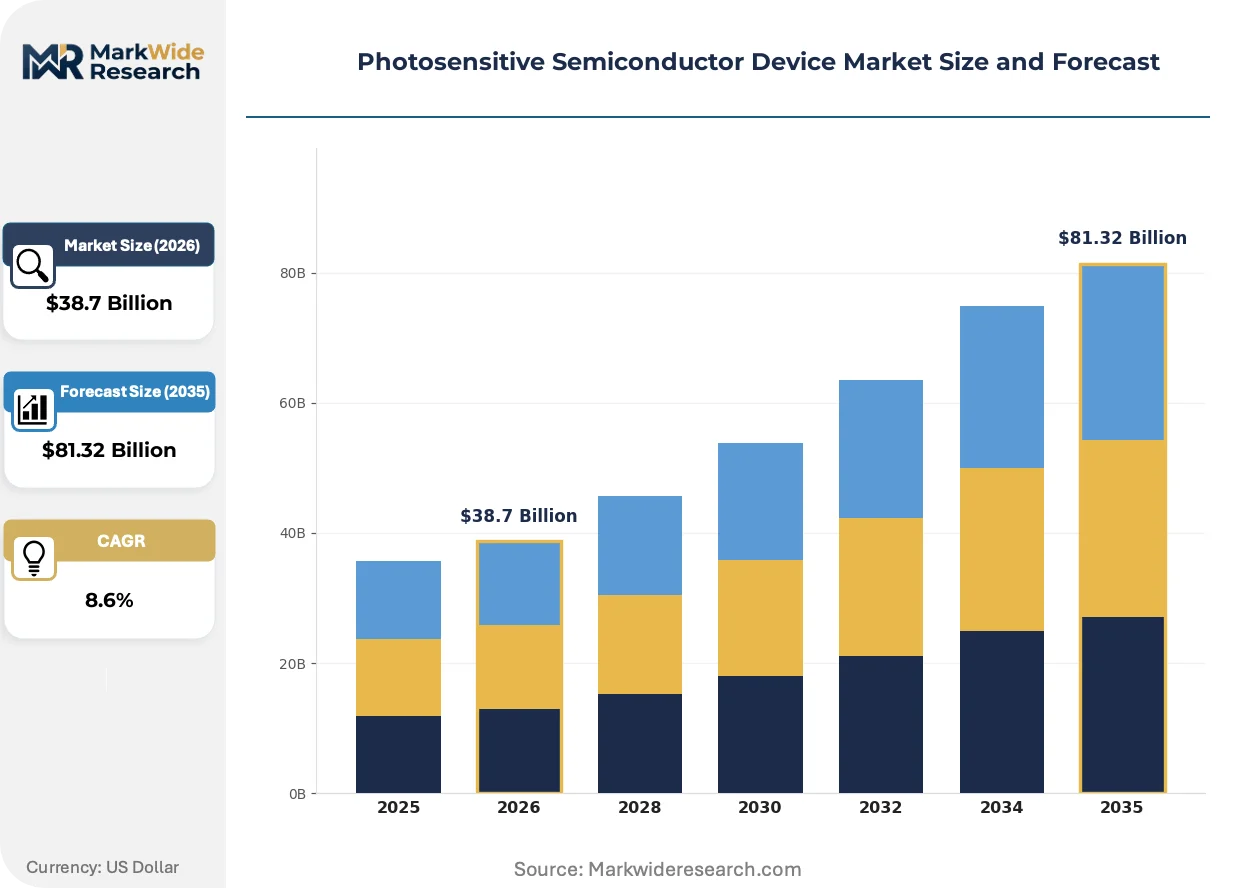
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Phototransistors, Image Sensors, Optical Sensors Technology: CMOS, CCD, InGaAs, SiC Application: Telecommunication, Consumer Electronics, Automotive, Medical Devices End User: Manufacturers, Research Institutions, Aerospace, Retailers |
| Companies Covered | STMicroelectronics N.V., Panasonic Corporation, Sony Group Corporation, Vishay Intertechnology Inc., Canon Inc., Samsung Electronics Co., Ltd., OmniVision Technologies, Inc., Asahi Kasei Corp., Hamamatsu Photonics K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photosensitive Semiconductor Device Market Evolving Landscape
Spectral range extension and packaging miniaturization are converging to unlock new detection modalities, while regulatory pressure on supply chain provenance is reshaping qualification protocols.
Silicon photonics is hybridizing with traditional CMOS image sensors to enable on-chip LiDAR beam steering without discrete mechanical components. Automotive tier-one suppliers in Germany and Japan are qualifying these integrated approaches for 2026 platform launches. The structural consequence is compressing the addressable market for discrete MEMS mirror suppliers while expanding wafer-level optics foundry revenue pools.
China's NMPA semiconductor certification protocols now mandate traceable carbon intensity reporting for imported photodiodes used in medical imaging equipment. Domestic manufacturers in Jiangsu and Zhejiang provinces are capturing share from European suppliers unable to document Scope 3 emissions. The affected segment is high-sensitivity photodiodes for endoscopy systems, where Japanese competitors are accelerating local production to maintain hospital procurement access.
Buyer consolidation among smartphone OEMs is collapsing image sensor negotiation leverage toward annual volume-commitment contracts with penalty clauses for forecast deviations. Samsung and Sony foundry divisions now require 18-month order visibility before allocating advanced node capacity. This pattern is most visible in South Korea and Vietnam assembly operations, where module houses face working capital strain from inventory pre-positioning requirements.
Photosensitive Semiconductor Device Market Segmentation
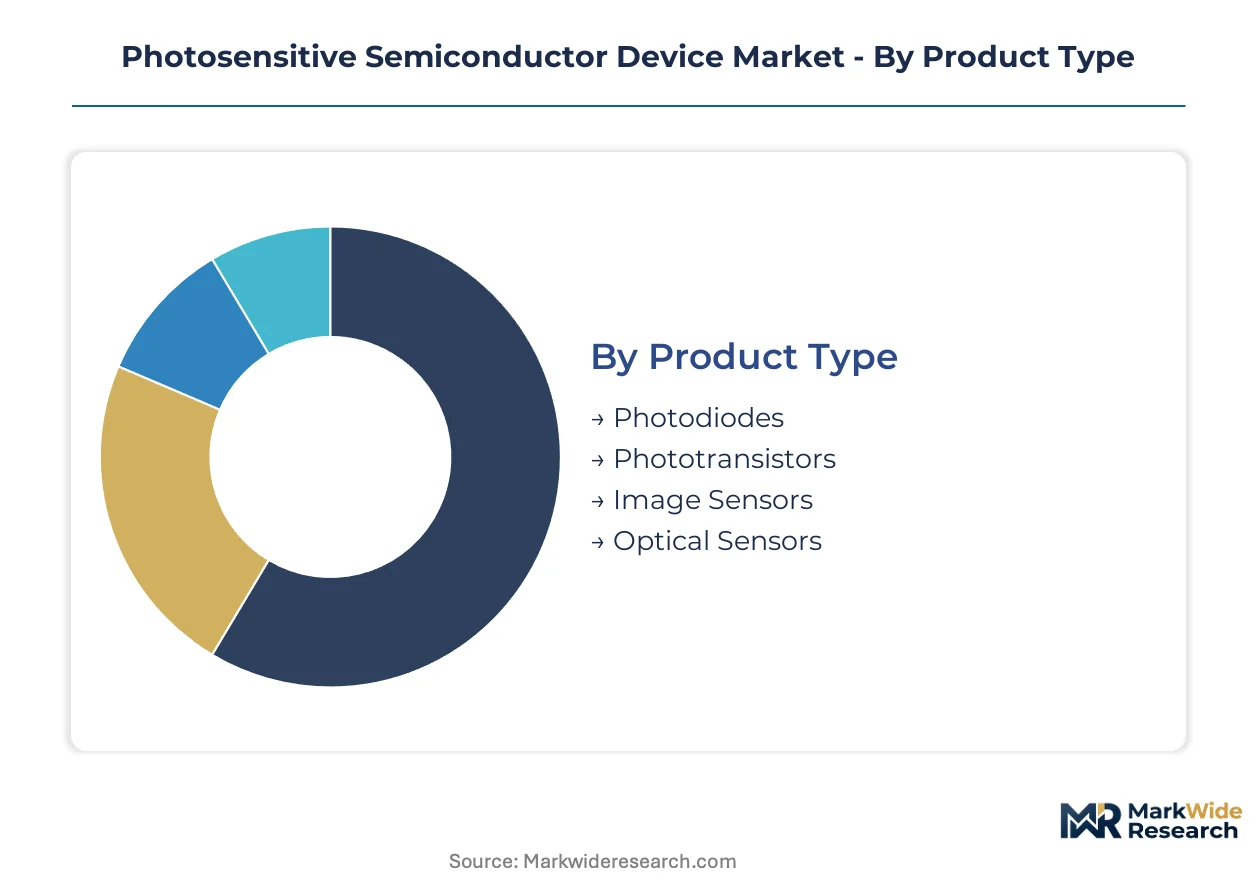
Photosensitive semiconductor devices span heterogeneous technical specifications and qualification timelines that fragment procurement strategies across end-use verticals. Component buyers prioritize spectral sensitivity ranges, package thermal tolerances, and automotive-grade reliability certifications when segmenting supplier evaluations. The analysis below maps how product architecture, substrate technology, application requirements, and buyer type stratify demand patterns and margin structures.
Product Type:
Cycle times vary dramatically across device architectures, with consumer image sensors refreshing annually while medical photodiodes lock specifications for multi-year platform lives.
- Image Sensors:Stacked CMOS architectures with backside-illuminated pixels capture visible and near-infrared spectra for smartphone cameras and automotive surround-view systems. Consumer electronics OEMs in South Korea and Vietnam drive volume procurement through 18-month order visibility contracts that strain module house working capital.
- Photodiodes:PIN and avalanche structures convert photon flux into current signals with quantum efficiency exceeding 90% in silicon and InGaAs formulations. Hamamatsu and Kyushu manufacturing clusters supply medical imaging and scientific instrumentation where FDA 510(k) clearances freeze designs for 12-18 month requalification cycles.
- Phototransistors:Bipolar gain stages amplify weak optical signals for industrial automation and consumer appliance presence detection.
- Optical Sensors:Integrated photodetector-amplifier assemblies serve building automation and environmental monitoring with constrained standby power budgets under EPA efficiency mandates.
Image sensors dominate installed base. Photodiodes are where expansion concentrates.
Technology:
Substrate selection determines spectral range, thermal performance, and foundry ecosystem access, with silicon variants commanding scale and compound semiconductors capturing premium positioning.
- CMOS:Complementary metal-oxide-semiconductor fabrication enables per-pixel analog-to-digital conversion and on-chip integration of image signal processors. Samsung's Pyeongtaek foundry and Sony's stacked architectures anchor supply for smartphone and automotive vision systems where NHTSA emergency braking mandates embed sensors in every vehicle platform.
- InGaAs:Indium gallium arsenide epitaxy extends sensitivity into short-wave infrared for semiconductor wafer inspection and telecom receivers. Chinese indium refining concentration creates single-source vulnerability while compound semiconductor talent gaps constrain foundry expansion timelines.
- CCD:Charge-coupled device technology persists in scientific imaging and legacy industrial vision systems requiring uniform pixel response.
- SiC:Silicon carbide substrates enable ultraviolet detection and high-temperature operation for precision agriculture and aerospace applications.
CMOS captures volume leadership. InGaAs is climbing the fastest.
Application:
Qualification intensity and procurement scale diverge sharply across end-use verticals, with automotive and medical segments imposing the most stringent reliability protocols.
- Automotive:LiDAR receivers and surround-view cameras require AEC-Q100 temperature cycling validation and ISO 26262 functional safety certification. German and Japanese tier-one suppliers are qualifying silicon photonics beam steering for 2026 platform launches, compressing demand for discrete MEMS components.
- Medical Devices:Pulse oximetry and diagnostic imaging equipment demand photodiodes with documented bias testing under EU AI Act conformity frameworks. China's NMPA now mandates traceable carbon intensity reporting, displacing European suppliers unable to document Scope 3 emissions.
- Consumer Electronics:Smartphone camera modules drive the largest absolute volume demand with annual specification refresh cycles.
- Telecommunication:Optical receivers for fiber infrastructure deploy InGaAs photodiodes in datacenter interconnects and long-haul networks.
Consumer electronics dominates installed base. Automotive is gaining share fastest.
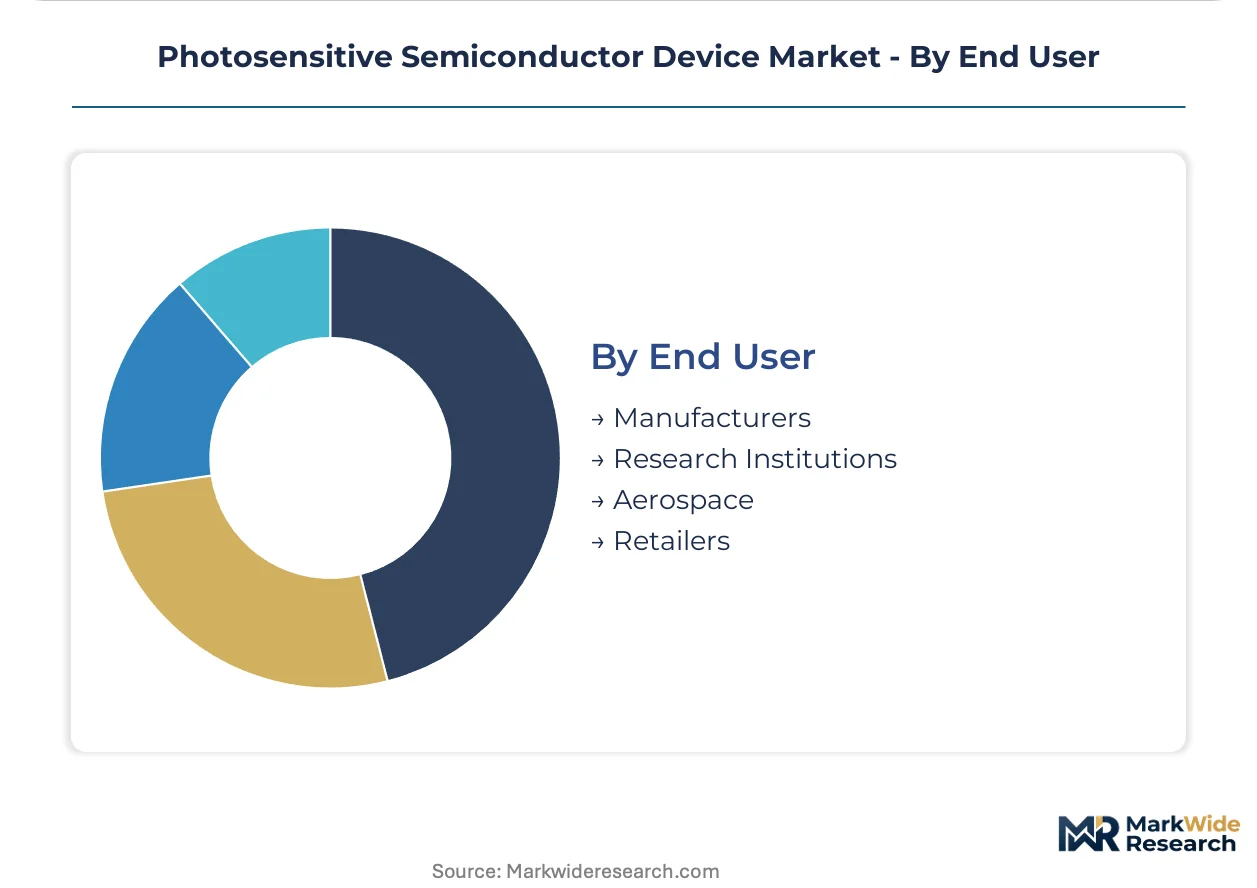
End User:
Procurement sophistication and technical specification authority concentrate differently across organizational types, fragmenting sales channel strategies.
- Manufacturers:Tier-one automotive suppliers and smartphone OEMs negotiate annual volume-commitment contracts with penalty clauses for forecast deviations, collapsing supplier leverage toward foundry allocation priority. Samsung and Sony divisions now require 18-month order visibility before releasing advanced node capacity.
- Research Institutions:National laboratories and university facilities procure scientific-grade photodetectors through grant-funded acquisition cycles with extended technical evaluation periods.
- Aerospace:Satellite and aircraft systems demand radiation-hardened devices with extended qualification timelines and captive supply chain documentation.
- Retailers:Distributor and e-commerce channels serve prototype development and maintenance-repair-operations demand with higher margin but fragmented volume.
Manufacturers dominate installed base. Research institutions are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication capacity for photosensitive semiconductors clusters in East Asian manufacturing corridors where cleanroom investments and compound semiconductor talent pools have achieved critical mass. Japan's METI subsidies and China's NMPA certification protocols are reshaping regional supply hierarchies.
Japan
Automotive LiDAR qualification timelines and medical imaging equipment demand drive photodiode consumption. METI's semiconductor resilience program funds expanded cleanroom capacity in Kyushu and Hamamatsu manufacturing clusters. Sony Group Corporation leverages stacked CMOS architectures from domestic foundries to supply smartphone and industrial vision systems.
China
Dual carbon goals and NMPA semiconductor certification protocols tighten efficiency benchmarks for imported photodiodes. Traceable carbon intensity reporting requirements displace European suppliers unable to document Scope 3 emissions. Jiangsu and Zhejiang provinces capture share in high-sensitivity photodiodes for endoscopy systems.
South Korea
Smartphone OEM buyer consolidation collapses image sensor negotiation leverage toward annual volume-commitment contracts. Samsung Electronics Co., Ltd. anchors high-volume CMOS supply through captive foundry scale in Pyeongtaek. Module houses in Vietnam assembly operations face working capital strain from 18-month order visibility requirements.
United States
NHTSA automatic emergency braking mandates embed CMOS image sensors into every new vehicle platform. FDA 510(k) clearance pathways shape design controls for photodiodes in diagnostic imaging and pulse oximetry equipment. EPA energy efficiency mandates constrain standby power budgets for optical sensors in building automation.
Germany
Euro NCAP vision-based scoring protocols accelerate automotive-grade optical sensor procurement. Tier-one suppliers qualify silicon photonics beam steering approaches for 2026 platform launches. ECHA cadmium restrictions under RoHS frameworks threaten quantum dot photodetector formulations in consumer imaging applications.
Photosensitive Semiconductor Device Market Competitive Landscape
Vertically integrated conglomerates and specialized component fabricators split the market across distinct capability tiers. Foundry-scale operators with captive wafer supply command volume leadership in consumer electronics and automotive qualification pipelines. Precision instrumentation specialists dominate medical and scientific segments where FDA 510(k) clearances freeze designs for extended requalification cycles. Competitive moves concentrate on backward integration into compound semiconductor epitaxy and strategic partnerships for silicon photonics beam steering development.
Among diversified electronics conglomerates, Sony Group Corporation and Samsung Electronics Co., Ltd. exemplify the foundry-integrated archetype with captive supply chain control over stacked CMOS architectures. Hamamatsu Photonics K.K. occupies a position within the precision instrumentation tier, representing specialists focused on high-sensitivity photodiodes for medical and scientific applications where quantum efficiency specifications command premium positioning.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Panasonic Corporation |
| Sony Group Corporation |
| Vishay Intertechnology Inc. |
| Canon Inc. |
| Samsung Electronics Co., Ltd. |
| OmniVision Technologies, Inc. |
| Asahi Kasei Corp. |
| Hamamatsu Photonics K.K. |
| Others |
Value Network & Pricing Analysis
Overcapacity in South Korean CMOS foundries is compressing spot pricing for consumer-grade image sensors while tightening contract terms for automotive-qualified components. Samsung's Pyeongtaek utilization rates below 75% are forcing foundries to absorb depreciation through volume discounts, yet AEC-Q100 certified sensors command 40% premiums through allocation priority.
Pricing Analysis
Euro NCAP vision-based scoring protocols dictate the pricing tier structure across automotive-grade optical sensors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified units from industrial-grade and consumer variants. Cost compression in standard-tier CMOS sensors is intensifying because smartphone OEM buyer consolidation demands 18-month order visibility with penalty clauses. Module houses in Vietnam assembly operations exhibit highest price sensitivity, while German tier-one automotive suppliers accept premium positioning for documented bias testing under EU AI Act conformity frameworks.
Supply Chain Analysis
Chinese indium refining concentration dominates raw material exposure for InGaAs photodiode manufacturers serving telecom and industrial inspection segments. Taiwan, South Korea, and Japan anchor wafer fabrication capacity, with compound semiconductor epitaxy drawing from Chinese indium, Japanese silicon carbide substrates, and German precursor chemicals. Single-source vulnerability in indium supply creates procurement hedge demand, while distribution runs through captive foundry-direct channels for high-volume automotive contracts and specialized distributors for medical device qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-software bundling in machine vision systems is accelerating faster than discrete component sales, with edge AI processor integration creating recurring calibration service revenue pools. Firmware update subscriptions for automotive LiDAR sensors now represent the fastest-expanding revenue layer.
For Market Incumbents: Build certification moats around FDA 510(k) and EU AI Act conformity documentation to freeze competitor design cycles. Sony and Samsung foundry divisions should expand Kyushu and Pyeongtaek cleanroom capacity ahead of automotive LiDAR qualification timelines. Hamamatsu Photonics K.K. must defend medical photodiode positioning through quantum efficiency specifications that trigger 12-18 month requalification delays for design modifications.
For New Entrants and Emerging Players: Indian medical device packaging corridors present underpenetrated demand for photodiode assembly serving ASEAN export markets. CDSCO registration pathways and PLI scheme incentives create accessible entry points against entrenched Japanese suppliers. Target precision agriculture applications in Brazil and Australia with silicon carbide photodetectors paired with edge AI processors, bypassing saturated consumer electronics procurement channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across InGaAs epitaxy operations as compound semiconductor talent gaps constrain foundry expansion timelines. Five-to-ten year viability favors precision instrumentation specialists with captive epitaxy capabilities and locked medical device platform relationships. Monitor NMPA carbon intensity reporting compliance as a signal for European supplier displacement in Chinese hospital procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Semiconductor Epitaxy | In-house InGaAs wafer production eliminates Chinese indium supply concentration risk for telecom receiver manufacturers. |
| Silicon Photonics Beam Steering Partnership | Automotive tier-one qualification for 2026 platform launches compresses discrete MEMS mirror addressable market. |
| FDA 510(k) Clearance Pathway Investment | Photodiode design control documentation freezes competitor specifications for pulse oximetry platforms. |
| Carbon Intensity Reporting Compliance Program | NMPA traceability requirements displace European suppliers in Jiangsu and Zhejiang hospital procurement. |
| Automotive LiDAR Allocation Priority Contracting | Eighteen-month order visibility terms strain module house working capital while securing foundry capacity. |
Research Methodology
The analysis maps CMOS image sensors, InGaAs photodiodes, silicon carbide detectors, and CCD legacy architectures, each validated through semiconductor foundry operations executives, automotive tier-one procurement leads, medical device regulatory affairs managers, and precision instrumentation R&D directors. Primary interview intelligence triangulates against SEC 10-K filings, METI subsidy disclosure records, NMPA certification registries, and Euro NCAP technical protocols. Bottom-up unit economics and top-down wafer capacity modeling converge through cross-referencing.
Assumption sets held regulatory timelines and cleanroom depreciation schedules fixed while varying indium price volatility and automotive platform adoption curves across the projection horizon. Segmentation dimensions span device architecture, substrate technology, application qualification intensity, and end-user procurement sophistication. CAGRs derive from wafer start forecasts, content-per-vehicle trajectories, and hospital equipment replacement cycles calibrated against foundry utilization reporting.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or Chinese rare earth export licensing would shift the trajectory. Forecasts embed assumptions about AEC-Q100 qualification pipeline throughput and FDA 510(k) review bandwidth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Bipolar Junction Transistors Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Global Inp Wafer Market