
 Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market | 2026-2036
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market Size, Share, and Industry Trends Forecast 2026-2036
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market Analytics
Capital-intensity divergence between captive foundry operators and fabless designers is redrawing competitive boundaries in advanced power packaging. Texas Instruments leverages vertically integrated 300mm analog fabrication to sustain margin structures that pure-play competitors cannot replicate. Infineon Technologies anchors European supply security through Dresden-based SiC and GaN capacity. Amkor Technology competes as the largest outsourced OSAT, controlling advanced flip-chip and wafer-level packaging routes for power-integrated devices.
Power Supply in Package and Power Supply on Chip denote highly integrated voltage conversion architectures that embed inductors, capacitors, and active switches within a single molded package or directly onto a monolithic die, achieving switching frequencies above 10 MHz and power densities exceeding 500 W per cubic inch for space-constrained electronics. DC-DC converters dominate shipment volumes owing to proliferation of point-of-load regulation in processor-centric systems, while gallium nitride technology captures the fastest expansion as its superior figure-of-merit enables smaller magnetics and higher efficiency at elevated frequencies. Silicon carbide occupies premium traction inverter and renewable energy slots where breakdown voltage requirements exceed 650 V.
FDA electromagnetic compatibility standards for medical equipment, EPA energy efficiency mandates under ENERGY STAR specifications, and FCC Part 15 emissions limits collectively shape product validation timelines and design architectures for PSiP and PwrSoC suppliers targeting North American markets. The EU Green Deal and REACH substance restrictions additionally constrain material selections for European-bound shipments. Stakeholders must monitor evolving MEE efficiency standards in China and dual carbon compliance timelines to anticipate where next-generation qualification requirements will tighten fastest.
Market Dynamics
Gallium nitride process nodes below 40nm are compressing magnetics requirements and forcing incumbent silicon MOSFET suppliers to accelerate roadmaps or exit high-frequency power conversion segments entirely.
Growth Catalysts
- ENERGY STAR 8.0 specifications:EPA mandates for data center equipment efficiency are compelling hyperscale operators to specify integrated power architectures that minimize conversion losses across multiple voltage rails.
- AI accelerator power budgets:NVIDIA and AMD reference designs for next-generation GPUs are mandating point-of-load regulators with transient response below 5 microseconds, favoring monolithic PwrSoC implementations over discrete alternatives.
- Dresden-Leipzig packaging corridor:European Commission funding through the Important Project of Common European Interest is expanding wafer-level packaging capacity for wide-bandgap devices, reducing lead times for automotive-qualified PSiP modules.
Market Restraints
- Epitaxial wafer supply concentration:80% of GaN-on-silicon epitaxy capacity resides with two merchant suppliers, creating vulnerability to allocation decisions during capacity ramps.
- Copper-molybdenum thermal interface costs:CTE-matched substrates required for high-reliability aerospace PSiP modules trade at 12-15x the cost of standard FR-4 alternatives, compressing margins in price-sensitive industrial segments.
- 650V silicon carbide price parity:SiC MOSFETs now match superjunction silicon performance below 600V, threatening GaN's addressable market in mid-voltage industrial drives and solar inverters.
Strategic Opportunities
- India PLI scheme for semiconductor packaging:Modified incentive structures covering compound semiconductor assembly create first-mover advantages for PSiP suppliers establishing Gujarat or Karnataka facilities before 2027 qualification deadlines.
- Autonomous vehicle zonal architectures:Centralized compute platforms with 48V distribution buses require isolated DC-DC converters at each zone controller, expanding addressable unit volumes by 4-6x per vehicle versus distributed 12V systems.
- EU F-Gas Regulation phase-down:Restrictions on sulfur hexafluoride in medium-voltage switchgear are pushing grid infrastructure toward solid-state circuit breakers with integrated gate drivers, opening new voltage classes for PSiP penetration.
Industry Challenges
- Magnetics design automation deficit:EDA tools for planar transformer optimization lag silicon circuit simulation by a decade, forcing power module designers into manual iteration cycles that extend development timelines by 6-9 months.
- AEC-Q100 Grade 0 qualification costs:Full automotive temperature range validation for PwrSoC devices requires 3,000+ device-hours of temperature cycling and HTOL testing, consuming $400K-$600K per product family before first revenue.
- Legacy 12V infrastructure incompatibility:Data centers with installed base of 12V server racks face forklift upgrade requirements to deploy 48V PSiP-based architectures, slowing replacement cycles despite efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market |
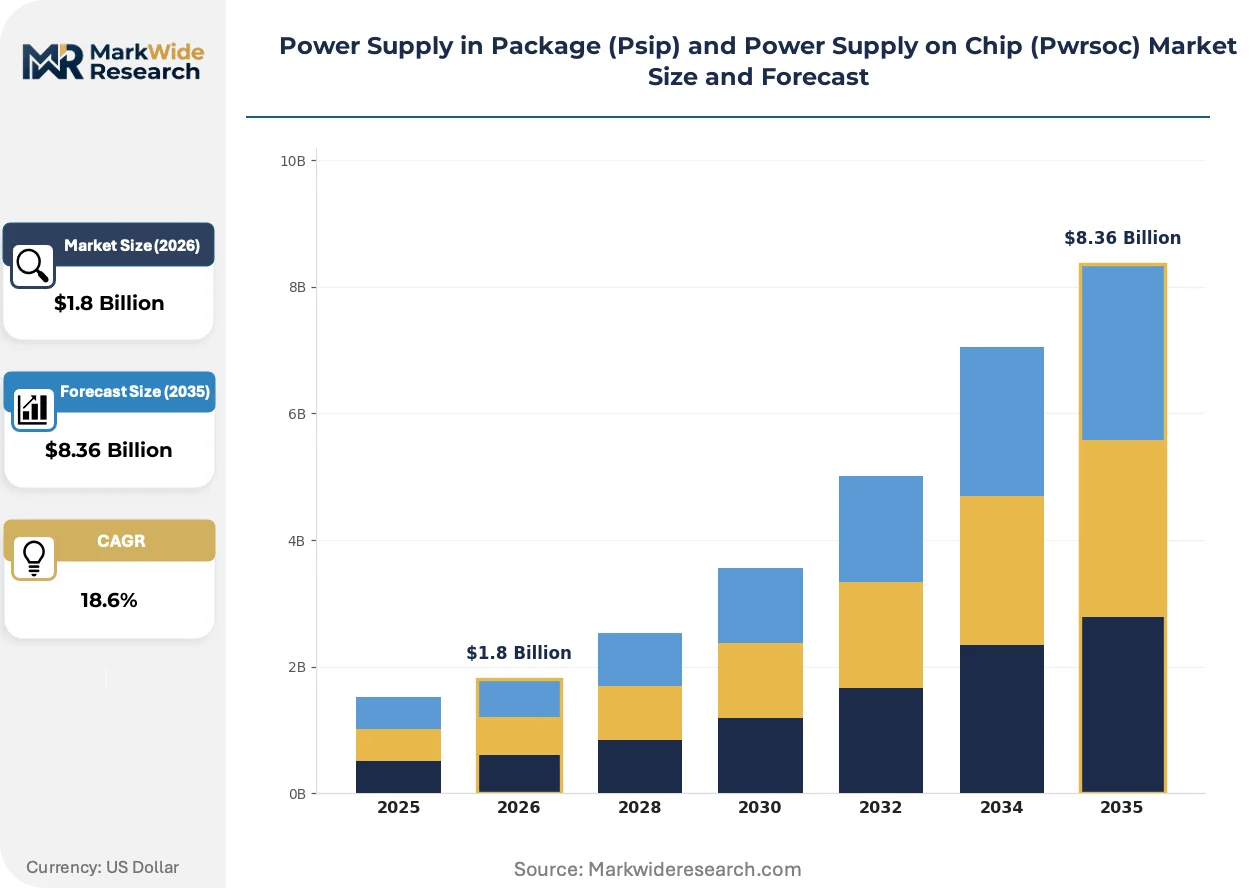
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC-DC Converters, DC-DC Converters, Voltage Regulators, Power Management ICs Technology: Silicon, Gallium Nitride, Silicon Carbide, Integrated Circuit End User: Consumer Electronics, Telecommunications, Automotive, Industrial Automation Application: Data Centers, IoT Devices, Medical Equipment, Renewable Energy Solutions |
| Companies Covered | Texas Instruments Incorporated, Infineon Technologies AG, Analog Devices, Inc., STMicroelectronics International N.V., Intel Corporation, ASE Group, Amkor Technology, Renesas Electronics Corporation, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market Evolving Landscape
Process-material convergence and regulatory efficiency mandates are compressing development cycles while expanding the performance envelope for integrated power conversion. Three developments dominate strategic planning.
GaN-on-silicon with p-GaN gate structures is supplanting cascode depletion-mode devices in sub-100V applications. Smartphone OEMs and notebook manufacturers have standardized on enhancement-mode GaN for 65W-140W adapter modules, collapsing the magnetics volume by 60% versus silicon equivalents. This transition is eroding the installed base advantage of established silicon suppliers and redistributing value toward epitaxy and packaging specialists.
REACH substance restrictions on lead-bearing solders and halogenated flame retardants are forcing material system redesigns across European-bound shipments. Mold compound suppliers have accelerated development of biphenyl-free epoxy formulations that maintain CTI 600 performance without bromine additives. Medical equipment and industrial automation segments face the tightest compliance timelines, with MDR technical documentation now requiring full material disclosure for power subsystem components.
Hyperscale procurement teams have consolidated vendor qualification lists to three approved sources per voltage class, compressing switching costs and intensifying pre-qualification engineering investment. Direct sourcing agreements now bypass traditional distribution for volumes above 500K units annually, transferring inventory risk to module suppliers. This concentration is most visible in the United States, where Meta, Microsoft, and Amazon collectively specify reference designs that determine foundry allocation priority for advanced packaging capacity.
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market Segmentation
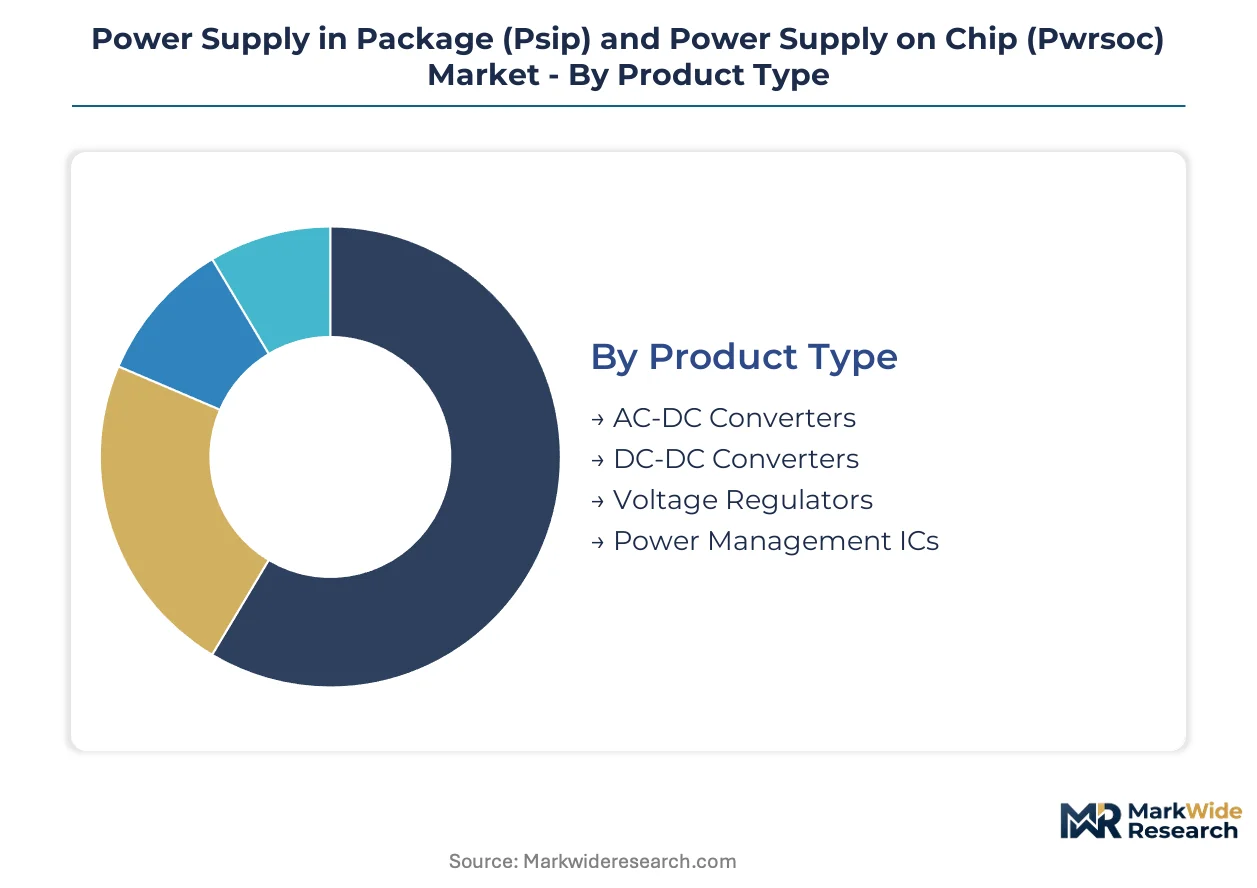
Segmentation in PSiP and PwrSoC markets reveals how voltage conversion architectures align with distinct thermal, frequency, and integration requirements. Each dimension—product topology, semiconductor technology, end-use sector, and deployment application—carries unique qualification barriers and procurement patterns that reshape vendor priorities.
Product Type:
Domestic demand concentrates in DC-DC architectures for server and automotive platforms, while AC-DC variants serve export-oriented consumer adapter markets bound for Asia-Pacific manufacturing hubs.
- DC-DC Converters:Point-of-load architectures embed inductors and switches within molded packages to achieve sub-10mm z-heights for processor-centric systems. Hyperscale data centers in the United States and Germany specify these modules for 48V-to-1V rail conversion, driven by ENERGY STAR 8.0 efficiency mandates that penalize multi-stage conversion losses.
- AC-DC Converters:Offline flyback and bridgeless totem-pole PFC circuits integrate GaN HEMTs with planar magnetics for 65W-240W adapter applications. Chinese and Vietnamese contract manufacturers dominate procurement volumes for notebook and smartphone OEMs, responding to EPA standby power regulations below 75mW.
- Voltage Regulators:Low-dropout and switching variants provide fine-grained load-line control for SoC cores.
- Power Management ICs:Multi-rail sequencers and supervisors coordinate system-level power states in complex electronics.
DC-DC converters command the established base. The steepest expansion runs through AC-DC architectures as GaN adapter penetration accelerates.
Technology:
Cost tiers separate mature silicon platforms from wide-bandgap alternatives, with pricing stratifying across performance, efficiency, and thermal handling specifications.
- Gallium Nitride:Enhancement-mode HEMTs with p-GaN gates achieve switching frequencies above 2MHz, collapsing magnetic component volumes by 60% versus silicon equivalents. Smartphone and notebook OEMs in Taiwan and South Korea have standardized on GaN for adapter modules, responding to EU Ecodesign efficiency tiers that eliminate marginal silicon designs.
- Silicon Carbide:Vertical trench MOSFETs and Schottky diodes serve 650V-1700V applications where breakdown voltage and thermal conductivity outweigh frequency optimization. German and Austrian industrial drive manufacturers anchor demand for traction inverter and renewable energy slots, constrained by AEC-Q101 and AQG324 automotive qualification timelines.
- Silicon:Superjunction and planar MOSFETs retain cost-sensitive industrial and appliance segments.
- Integrated Circuit:Bipolar-CMOS-DMOS monolithic processes combine control logic with power switches at sub-100V ratings.
Silicon platforms command the established base. The steepest expansion runs through gallium nitride as magnetics miniaturization rewards frequency scaling.
End User:
Customer type determines qualification intensity, with automotive and medical segments demanding traceable supply chains that industrial and consumer markets tolerate less.
- Automotive:Zonal E/E architectures with 48V distribution buses require isolated DC-DC converters at each domain controller, expanding unit volumes by 4-6x per vehicle versus legacy 12V systems. German OEMs and Tier-1 suppliers in Stuttgart and Munich drive qualification of AEC-Q100 Grade 0 devices, facing 3,000+ device-hours of temperature cycling validation.
- Data Center:Hyperscale operators in Ashburn, Frankfurt, and Singapore consolidate vendor lists to three approved sources per voltage class, transferring inventory risk to module suppliers through direct sourcing agreements above 500K annual units.
- Consumer Electronics:Smartphone and wearable OEMs prioritize thickness reduction and thermal dissipation in compact form factors.
- Industrial Automation:Programmable logic controllers and motor drives demand ruggedized packaging for extended temperature ranges.
Industrial automation commands the established base. The steepest expansion runs through automotive as electrification multiplies power conversion nodes per vehicle.
Application:
Volume concentration varies sharply, with data center procurement consolidating around few hyperscale specifications while IoT and medical segments fragment across numerous niche requirements.
- Data Centers:Rack-scale architectures mandate 48V intermediate bus conversion with transient response below 5 microseconds for AI accelerator power budgets. NVIDIA and AMD reference designs determine foundry allocation priority for advanced packaging capacity at TSMC and Intel facilities.
- Medical Equipment:Diagnostic imaging and patient monitoring systems require FDA electromagnetic compatibility validation and full material disclosure under EU MDR technical documentation. Swiss and German device manufacturers face REACH substance restrictions on lead-bearing solders and halogenated flame retardants.
- IoT Devices:Battery-powered sensors and edge nodes prioritize quiescent current minimization.
- Renewable Energy Solutions:Solar microinverters and energy storage systems balance efficiency with long-term reliability.
Data center applications command the established base. The steepest expansion runs through medical equipment as diagnostic electrification and portable care devices multiply regulated power subsystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Hyperscale data center operators in the United States absorb premium pricing for efficiency gains, while industrial buyers in China and India prioritize unit economics over switching frequency performance.
United States
Hyperscale cloud operators in Ashburn and Phoenix drive specification of 48V intermediate bus architectures for AI training clusters. EPA ENERGY STAR 8.0 mandates penalize multi-stage conversion losses, compelling direct sourcing agreements above 500K annual units. Meta, Microsoft, and Amazon procurement teams consolidate vendor lists to three approved sources per voltage class.
China
Domestic demand concentrates in export-oriented consumer adapter manufacturing for notebook and smartphone OEMs. MEE efficiency standards and dual carbon compliance timelines tighten fastest for data center equipment in Beijing and Shanghai. Yangtze River Delta packaging facilities expand GaN-on-silicon capacity to serve Taiwan-based ODMs.
Germany
Automotive electrification multiplies power conversion nodes per vehicle, with Stuttgart and Munich OEMs driving AEC-Q100 Grade 0 qualification. EU Green Deal and REACH substance restrictions constrain material selections for European-bound shipments. Dresden-based SiC and GaN capacity anchors European supply security for wide-bandgap devices.
India
Modified PLI scheme incentives covering compound semiconductor assembly create first-mover advantages for suppliers establishing Gujarat or Karnataka facilities. BIS certification requirements and CEA grid standards shape product validation timelines for industrial PSiP modules. Domestic data center construction in Mumbai and Hyderabad accelerates adoption of 48V rack-scale architectures.
South Korea
Seoul Capital Area smartphone and notebook OEMs have standardized on GaN for 65W-140W adapter modules. MFDS electromagnetic compatibility standards for medical equipment and KTL efficiency certifications shape export documentation. Busan-Ulsan packaging corridors expand wafer-level capacity for consumer electronics-bound PSiP devices.
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry operators commanding margin structures that fabless competitors cannot replicate. The market fragments across three strategic archetypes: vertically integrated analog fabricators, outsourced assembly and test providers, and wide-bandgap semiconductor specialists. Capacity expansion and strategic partnerships dominate competitive moves, with foundry allocation priority determining packaging access for advanced nodes.
Among integrated analog fabricators, Texas Instruments Incorporated and Infineon Technologies AG exemplify the vertically integrated archetype, with the former leveraging 300mm fabrication and the latter anchoring European supply security through Dresden-based capacity. Amkor Technology occupies a position within the outsourced assembly tier, controlling advanced flip-chip and wafer-level packaging routes for power-integrated devices.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| Analog Devices, Inc. |
| STMicroelectronics International N.V. |
| Intel Corporation |
| ASE Group |
| Amkor Technology |
| Renesas Electronics Corporation |
| NXP Semiconductors N.V. |
| Others |
Value Network & Pricing Analysis
Capacity reservation agreements with GaN epitaxy suppliers lock in wafer access and price visibility for packaging houses serving hyperscale data center operators, insulating qualified vendors from spot-market volatility while locking out second-tier competitors during allocation crunches.
Pricing Analysis
After-sales service contracts for field replacement and reliability monitoring drive lifetime value in aerospace and automotive PSiP modules. Three-tier pricing structure across AEC-Q100 Grade 0, Grade 1, and industrial-temperature tiers separates qualification-intensive automotive slots from cost-optimized consumer adapter volumes. Cost compression in standard-grade silicon platforms is intensifying because 650V SiC now matches superjunction performance below 600V. Industrial automation buyers in China exhibit highest price sensitivity, while German automotive OEMs absorb premiums for traceable supply chains.
Supply Chain Analysis
Strategic stockpiling of copper-molybdenum thermal interface substrates dominates aerospace and defense PSiP procurement, contrasting with just-in-time wafer-level packaging flows for consumer electronics. Manufacturing concentrates in Taiwan, South Korea, and Germany for advanced packaging capacity. Supply chains draw from GaN-on-silicon epitaxy, planar magnetic cores, and CTE-matched ceramic substrates. Single-source vulnerability concentrates in 80% merchant epitaxy capacity residing with two suppliers. Distribution runs through direct sourcing agreements above 500K annual units for hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as NVIDIA and AMD reference designs determine foundry allocation priority, making interoperability certification the primary gatekeeper for packaging capacity access rather than standalone technical performance.
For Market Incumbents: Secure AEC-Q100 Grade 0 qualification pipelines before European automotive OEMs consolidate vendor lists to three approved sources per voltage class. Threat from GaN process nodes below 40nm compressing magnetics requirements demands accelerated roadmap execution or segment exit. Backward integration into GaN epitaxy capacity anchors margin structures that fabless competitors cannot replicate.
For New Entrants and Emerging Players: FDA electromagnetic compatibility fast-track for medical equipment PSiP modules opens white-space penetration before incumbent qualification backlogs clear. Target diagnostic imaging and portable care device segments where MDR technical documentation requirements create compliance moats. Go-to-market angle centers on REACH-compliant material systems for European-bound shipments.
For Investors and Strategic Acquirers: Packaging specialists with captive GaN-on-silicon epitaxy partnerships represent the most defensible acquisition archetype as wafer-level capacity tightens. Long-term viability over the next decade rests on compound semiconductor assembly capabilities rather than legacy silicon platforms. Signal to watch is Intel and TSMC foundry allocation priority shifts for advanced packaging nodes serving AI accelerator power budgets.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Epitaxy Capacity Expansion | Captive wafer supply secures packaging allocation priority at TSMC and Intel facilities. |
| AEC-Q100 Grade 0 Qualification | Automotive OEM consolidation to three vendors per voltage class creates exclusionary moats. |
| REACH-Compliant Material Redesign | Biphenyl-free mold compounds unlock European medical equipment procurement pipelines. |
| Direct Sourcing Agreement Structure | Hyperscale operator contracts above 500K units transfer inventory risk to module suppliers. |
| Planar Transformer EDA Development | Magnetics design automation closes decade-long simulation gap with silicon circuit tools. |
Research Methodology
Initial hypotheses were tested against primary input from packaging process engineers, hyperscale data center procurement managers, automotive Tier-1 power electronics specialists, and GaN epitaxy operations directors and refined through secondary validation against SEC 10-K filings, EPA ENERGY STAR certification databases, hyperscaler capex disclosures, and AEC-Q100 qualification registries. Bottom-up shipment modeling triangulated against top-down semiconductor equipment spending patterns.
Variance decomposition across technology node transitions, regulatory compliance timelines, and foundry capacity allocation shifts structured the analytical framework. Segmentation dimensions modeled include product topology, semiconductor technology, end-use sector, and deployment application across the analysis window. CAGRs derived from shipment volume trajectories weighted by average selling price evolution, with GaN penetration curves and SiC price parity thresholds as key forecast inputs.
Underlying assumptions cover ENERGY STAR 8.0 enforcement timelines and dual carbon compliance trajectories in China, with deviation risk concentrated in epitaxial wafer supply allocation decisions during capacity ramps. Revision becomes warranted when GaN-on-silicon process node transitions accelerate beyond modeled substitution curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Europe Microcontroller Market