
 APAC Semiconductor Device for Processing Applications Market | 2026-2036
APAC Semiconductor Device for Processing Applications Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Semiconductor Device for Processing Applications Market Insights
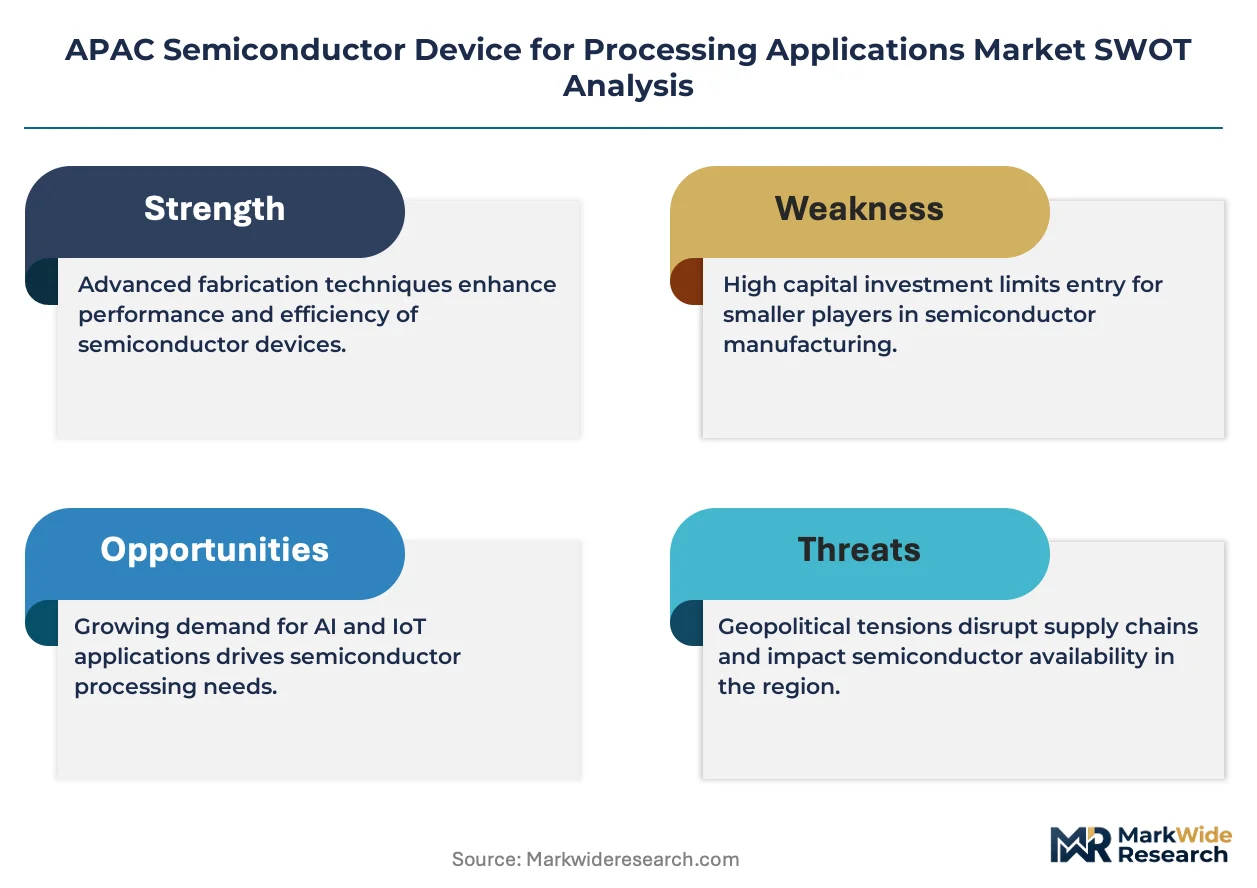
Advanced packaging and chiplet architectures is fragmenting traditional monolithic processor design across APAC foundries. Taiwan Semiconductor Manufacturing Company (TSMC) Limited anchors leading-edge node production through massive capital deployment in southern Taiwan. Samsung Electronics Co Ltd competes aggressively in memory and logic foundry services from its Pyeongtaek complex. Intel Corporation leverages packaging innovation and sovereign-fab partnerships to reposition its APAC supply footprint.
APAC semiconductor devices for processing applications are integrated circuits fabricated on silicon wafers using lithography, etching, and deposition processes, typically ranging from mature 28nm nodes to advanced 3nm geometries, engineered to execute computational, control, and signal-processing functions in electronic systems. Logic chips command the largest revenue pool as data-center and AI workloads expand across the region, while power management ICs are gaining structural importance from electrification trends in automotive and industrial segments. CMOS technology dominates volume production, though GaN is displacing legacy silicon in high-frequency power applications where efficiency thresholds are tightening.
China's MIIT enforces domestic semiconductor self-sufficiency targets through GB standards and subsidy frameworks, while South Korea's K-Battery and K-Semiconductor acts channel state support toward advanced node R&D. Japan's METI coordinates supply-chain resilience initiatives and export-control alignment with allied regimes. Stakeholders must weigh sovereign-capacity buildouts against the technical and cost advantages of established foundry ecosystems when committing long-term capacity agreements.
Market Dynamics
Foundry capacity concentration in Taiwan's Hsinchu Science Park and southern Taiwan mega-fabs is creating asymmetric supply risk across APAC processing chip procurement, forcing buyers to diversify sourcing despite node-technology dependencies.
Growth Catalysts
- Automotive electronics mandates:Electrification and ADAS penetration across China, South Korea, and Japan are pulling 28nm-7nm logic demand from foundries serving tier-1 automotive module suppliers.
- MIIT dual carbon enforcement:China's GB energy-efficiency standards for data centers are accelerating replacement cycles for legacy silicon with advanced-node processors.
- Chiplets and advanced packaging:Heterogeneous integration is enabling cost-effective performance scaling without sole reliance on EUV lithography shrinks.
Market Restraints
- EUV equipment chokepoint:ASML's monopoly on extreme ultraviolet lithography tools limits 3nm-5nm expansion to facilities with pre-existing equipment allocations.
- Raw wafer supply concentration:300mm silicon wafer production clusters in Japan and Taiwan create input vulnerability for logic and memory fabs across the region.
- Export control alignment friction:Japan's METI and South Korea's trade ministry face pressure to harmonize with US Commerce Department restrictions on China-bound advanced-node equipment.
Strategic Opportunities
- Southeast Asia backend expansion:Malaysia's Penang and Vietnam's northern provinces are attracting OSAT investment for 2.5D/3D packaging capacity to complement Taiwan front-end concentration.
- GaN power integration:Gallium nitride is penetrating server power supplies and EV onboard chargers where China's GB standards tighten efficiency minimums.
- Sovereign fab incentives:India's PLI scheme for semiconductor manufacturing is creating greenfield opportunity for mature-node processing device production.
Industry Challenges
- EUV technician scarcity:The specialized skillset for maintaining and calibrating extreme ultraviolet lithography systems is concentrated among a small cohort of engineers trained in Taiwan and the Netherlands.
- Legacy node stranded capacity:Foundries face margin compression on 28nm and larger geometries as depreciation schedules extend beyond original equipment lifetime assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Semiconductor Device for Processing Applications Market |
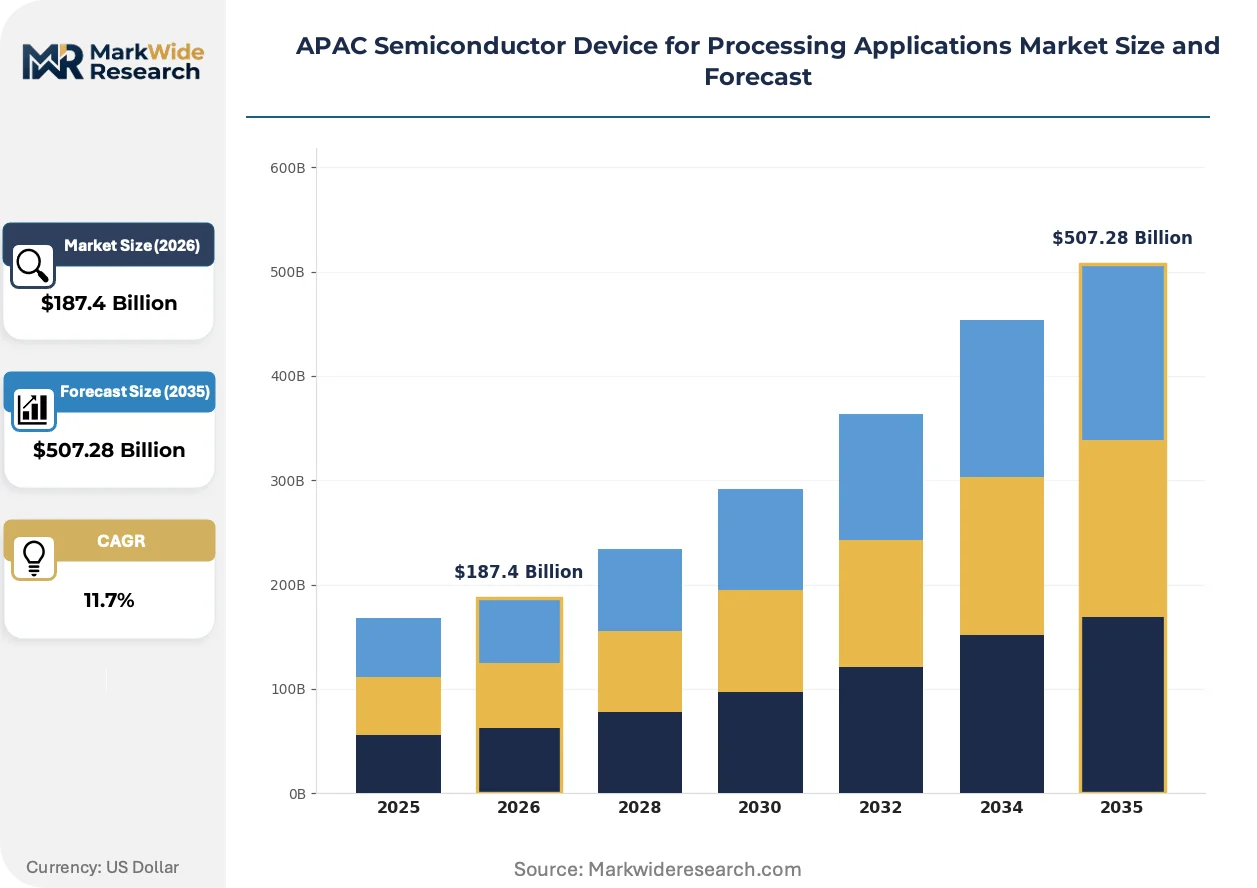
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Logic Chips, Memory Chips, Power Management ICs, Analog Chips Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications Technology: CMOS, BiCMOS, Bipolar, GaN End User: Manufacturers, OEMs, Retailers, Distributors |
| Companies Covered | Intel Corporation, Nvidia Corporation, Qualcomm Incorporated, STMicroelectronics NV, Taiwan Semiconductor Manufacturing Company (TSMC) Limited, Samsung Electronics Co Ltd, NXP Semiconductors NV, Renesas Electronics Corporation, Toshiba Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Semiconductor Device for Processing Applications Market Trends and Innovations
Processing device architectures are fragmenting across functional specialization, with packaging technology and materials science overtaking lithography as the primary vector for performance differentiation in APAC supply chains.
Gate-all-around transistor technology is migrating from planar FinFET designs to address power leakage at 3nm geometries. Samsung Electronics has deployed this architecture in its Pyeongtaek logic foundry for high-performance computing customers. The shift is compressing design-tool licensing timelines as EDA vendors recalibrate parasitic extraction models.
Japan's METI has coordinated supply-chain resilience subsidies with export-control alignment to allied technology regimes. Domestic equipment makers are receiving targeted support for deposition and etch tool development. Memory and logic fabs in Japan are responding by qualifying local alternatives to US and EU process equipment.
Direct procurement from foundries is displacing traditional distribution channels for large-scale cloud and automotive module buyers. Long-term capacity agreements now span 3-5 year horizons with pre-payment structures. This pattern is most visible in Taiwan and South Korea where hyperscale data-center operators negotiate directly with TSMC and Samsung foundry divisions.
APAC Semiconductor Device for Processing Applications Market Segmentation
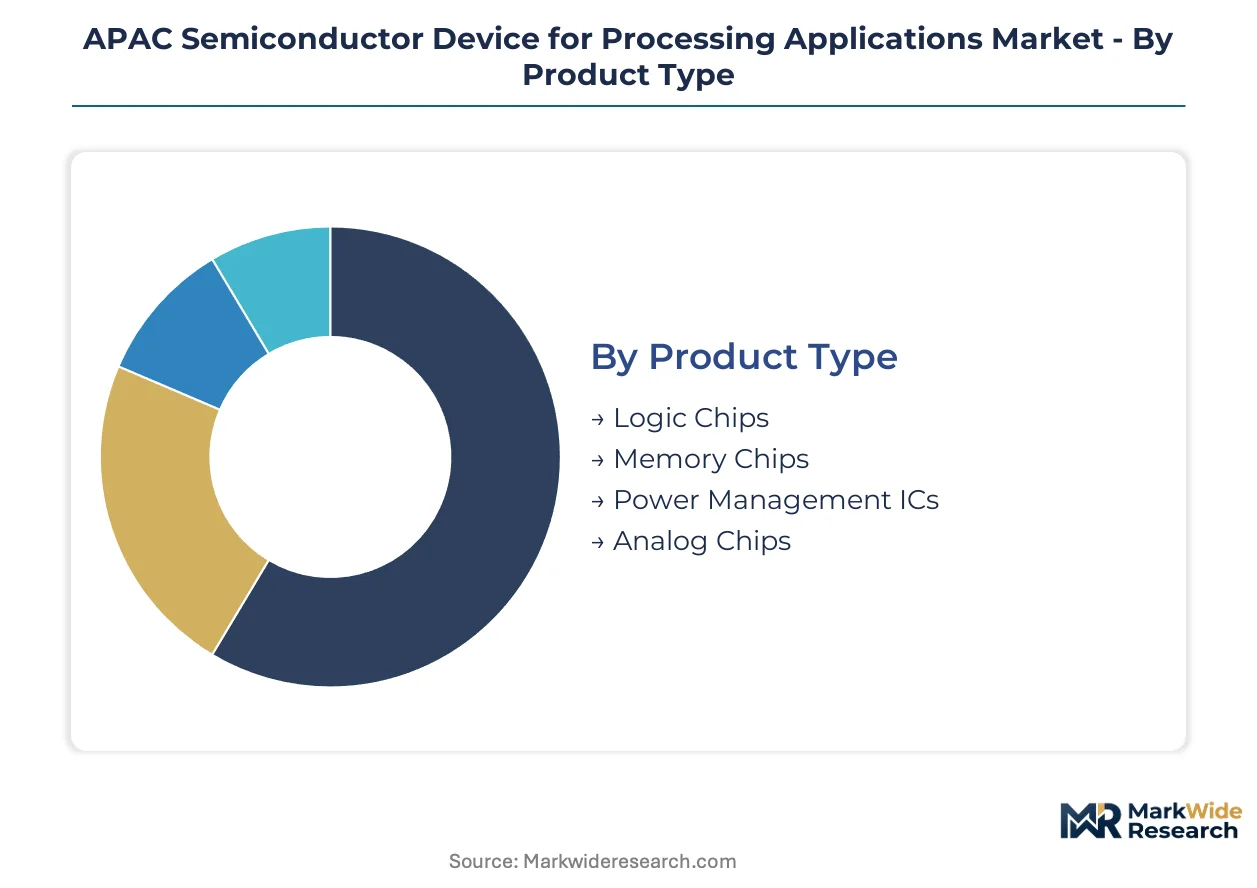
Processing device segmentation in APAC reflects divergent technical requirements across foundry nodes, packaging formats, and power envelopes. Buyers select architectures based on thermal constraints, lithography availability, and backend integration complexity rather than unit economics alone.
Product Type:
After-sales service intensity varies sharply across product categories, with logic and memory chips demanding specialized field application engineering while analog and power management devices require less ongoing technical support.
- Logic Chips:CMOS-based computational processors fabricated on 3nm-28nm nodes execute sequential and parallel operations for data centers and AI accelerators. Demand concentrates in Taiwan's Hsinchu Science Park cluster where TSMC anchors leading-edge production for hyperscale cloud operators in China and South Korea.
- Memory Chips:DRAM and NAND flash devices store volatile and persistent data through charge-based cell architectures. Samsung's Pyeongtaek complex and SK Hynix's Icheon fabs supply Chinese smartphone OEMs and Japanese automotive module makers facing just-in-time inventory mandates.
- Power Management ICs:Voltage regulators and battery charging circuits integrate GaN transistors for EV onboard chargers under China's GB efficiency standards.
- Analog Chips:Signal conditioning and conversion devices serve industrial sensor networks across Japan's automotive Tier-1 suppliers.
Logic chips hold the largest share; momentum sits with power management ICs as electrification tightens efficiency mandates.
Application:
Cost tier stratification separates premium automotive-grade devices from consumer electronics volumes, with industrial automation occupying a mid-tier reliability band.
- Consumer Electronics:Smartphones, tablets, and wearables drive 5nm-7nm logic demand from Chinese OEMs. Procurement concentrates in direct foundry agreements with TSMC and Samsung, bypassing traditional distribution.
- Automotive Electronics:ADAS processors and domain controllers require AEC-Q100 qualification at 28nm-14nm geometries. Japanese and South Korean module suppliers source from Taiwan foundries under long-term capacity agreements with penalty clauses for volume shortfalls.
- Industrial Automation:PLCs and motor controllers utilize mature-node MCUs with extended temperature ratings. China's MIIT smart manufacturing subsidies accelerate domestic foundry qualification for these devices.
- Telecommunications:Baseband processors and RF transceivers support 5G infrastructure deployment across India's Bharti Airtel and Japan's NTT networks.
Consumer electronics represents the dominant revenue pool; automotive electronics is expanding most quickly as electrification penetrates vehicle platforms.
Technology:
Volume concentration favors CMOS for digital logic, while margin differentiation accrues to GaN in power applications where efficiency thresholds are tightening.
- CMOS:Complementary metal-oxide-semiconductor technology dominates digital logic through planar and FinFET transistor architectures. Taiwan and South Korea foundries produce CMOS devices at 90% of regional logic volume.
- GaN:Gallium nitride wide-bandgap semiconductors displace silicon MOSFETs in server power supplies and EV chargers. Chinese foundries in Xiamen and Hefei are qualifying GaN-on-silicon processes for domestic power module suppliers.
- BiCMOS:Bipolar-CMOS integration serves precision analog-to-digital converters in Japanese industrial equipment.
- Bipolar:Legacy junction transistors persist in linear regulators for cost-sensitive consumer applications.
CMOS commands absolute volume; GaN is gaining share fastest as efficiency regulations harden across data center and automotive segments.
End User:
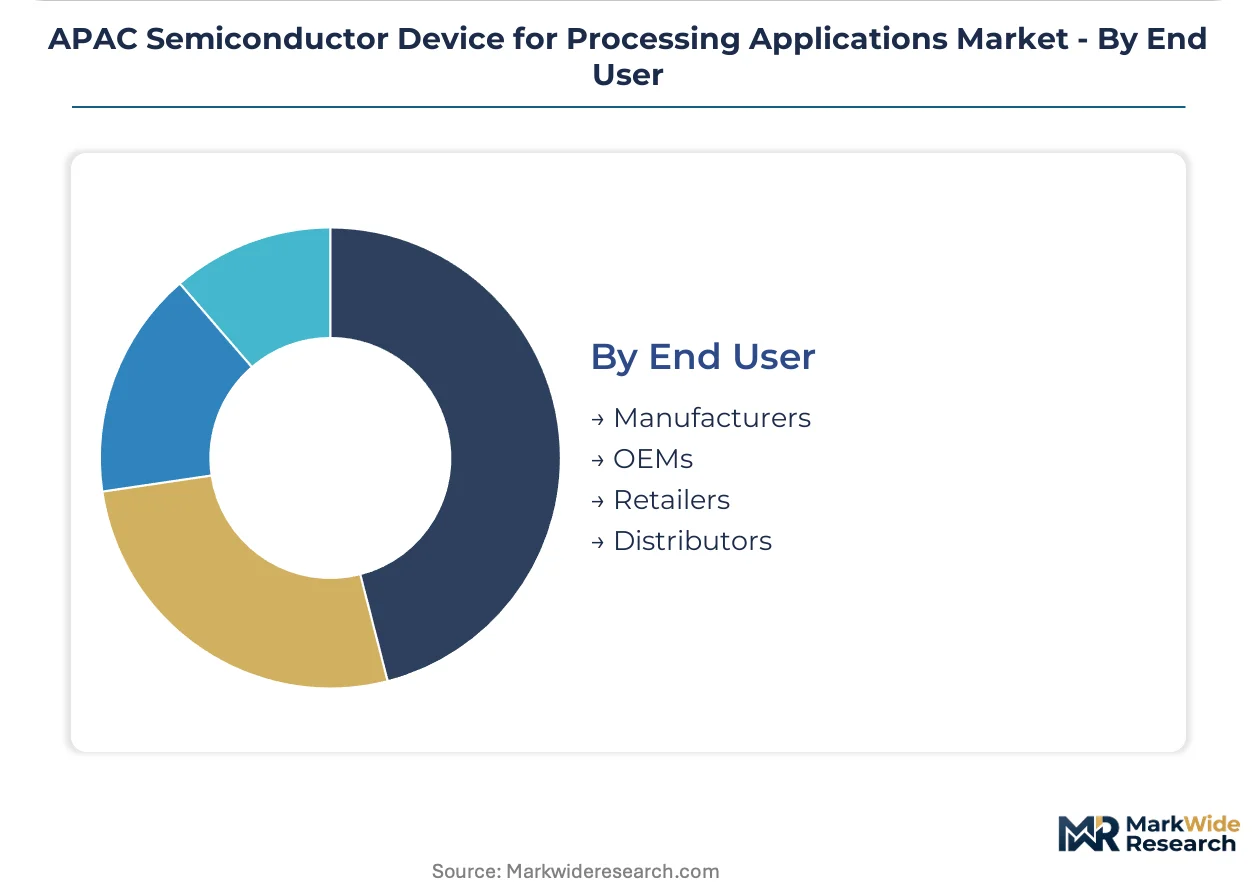
Customer type determines procurement modality, with manufacturers and OEMs negotiating direct foundry contracts while retailers and distributors handle spot-market residual demand.
- Manufacturers:Electronic product assemblers in Vietnam and Malaysia procure wafers for captive packaging operations. These buyers prioritize backend integration over front-end node access.
- OEMs:Original equipment manufacturers in China's Pearl River Delta specify custom processors for white goods and appliances. Their procurement teams maintain dual-source foundry relationships to mitigate Taiwan concentration risk.
- Retailers:Electronics distributors in Singapore and Hong Kong hold inventory for small-volume buyers lacking direct foundry access.
- Distributors:Channel partners aggregate demand from Indian and Indonesian contract manufacturers for mature-node devices.
Manufacturers and OEMs together dominate procurement value; distributors are climbing the fastest as Southeast Asia backend capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports advanced-node processors to Chinese hyperscale data centers and South Korean automotive module suppliers, creating the dominant trade corridor across the APAC semiconductor landscape. This flow pattern concentrates procurement leverage in Hsinchu and Tainan while exposing buyers to asymmetric supply risk.
China
Domestic foundry demand is accelerating from EV powertrain controllers and AI training clusters. MIIT enforces GB energy-efficiency standards that disqualify legacy silicon from new data-center deployments. Xiamen and Hefei fabs are qualifying GaN-on-silicon processes for power module suppliers serving BYD and CATL.
South Korea
Memory and logic demand is intensifying from automotive ADAS programs and 5G baseband procurement. The K-Semiconductor Act channels state support toward advanced node R&D and equipment localization. Samsung's Pyeongtaek complex anchors leading-edge DRAM and foundry output for Chinese smartphone OEMs.
Japan
Automotive-grade processor procurement is tightening from electrification mandates across Toyota and Honda supply chains. METI coordinates supply-chain resilience subsidies with export-control alignment to allied technology regimes. Kyushu's Kumamoto prefecture is attracting TSMC joint-venture investment for 28nm automotive logic capacity.
India
Mature-node demand is emerging from industrial automation and telecommunications infrastructure buildouts. The PLI scheme for semiconductor manufacturing is creating greenfield opportunity for 28nm-65nm processing device production. Gujarat's Dholera SIR and Karnataka's Mysuru corridor are attracting OSAT investment for backend packaging.
Vietnam
Backend assembly demand is scaling from regional diversification strategies by Taiwanese and South Korean foundries. The Ministry of Planning and Investment offers tax incentives for semiconductor packaging and testing facilities. Northern provinces including Bac Ninh and Thai Nguyen are attracting 2.5D/3D packaging capacity to complement Taiwan front-end concentration.
APAC Semiconductor Device for Processing Applications Market Competitive Landscape
On the supply side, the industry is bifurcated between capital-intensive leading-edge foundries and specialized mature-node fabricators. Taiwan and South Korea anchor the premium tier through massive EUV-equipped facilities, while Chinese and Southeast Asian players occupy cost-optimized segments. Two strategic archetypes dominate: integrated device manufacturers with captive fabrication and pure-play foundries serving fabless customers. Competitive moves center on sovereign-fab partnerships and advanced packaging capacity expansion.
Within the foundry tier, Taiwan Semiconductor Manufacturing Company Limited and Samsung Electronics Co Ltd exemplify scale-driven positioning through multi-billion dollar node transitions. Intel Corporation occupies a hybrid archetype that blends IDM heritage with foundry service expansion. These three entities anchor the competitive structure through divergent approaches to lithography access, geographic footprint, and customer segmentation.
| Leading Market Players |
|---|
| Intel Corporation |
| Nvidia Corporation |
| Qualcomm Incorporated |
| STMicroelectronics NV |
| Taiwan Semiconductor Manufacturing Company (TSMC) Limited |
| Samsung Electronics Co Ltd |
| NXP Semiconductors NV |
| Renesas Electronics Corporation |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
The Kaohsiung-Tokyo semiconductor freight corridor carries lithography equipment and processed wafers at rates that amplify Taiwan's supply concentration into downstream pricing power for Chinese hyperscale buyers. These logistics costs feed into three-tier pricing structures across premium, standard, and economy levels that separate AEC-Q100 automotive-grade devices from consumer electronics volumes.
Pricing Analysis
3nm-to-5nm leading-edge node premiums over 7nm-to-14nm mainstream geometries and 28nm-plus mature nodes create sharp price stratification across foundry outputs. Contract-based long-term offtake agreements with pre-payment structures dominate procurement between hyperscale operators and TSMC or Samsung foundry divisions. Price differentiation hinges on certification level — AEC-Q100 automotive qualification commands substantial premiums over consumer-grade JEDEC standards — and volume scale, with wafer-level commitments above ten-thousand units unlocking preferential slotting. Cost compression in mature-node 28nm geometries is intensifying because depreciation schedules now extend beyond original equipment lifetime assumptions, squeezing margin structures for Chinese domestic foundries. Contract manufacturers in Vietnam and Malaysia exhibit highest price sensitivity due to backend-heavy value capture, while automotive module suppliers in Japan and South Korea demonstrate lowest sensitivity given just-in-time inventory mandates and penalty clauses for volume shortfalls.
Supply Chain Analysis
300mm silicon wafer feedstock draws from Shin-Etsu and SUMCO production clusters in Japan, with polysilicon purification concentrated in China and Germany. Raw material dependencies center on high-purity silicon metal, photoresist chemicals from JSR and Tokyo Ohka Kogyo, and neon gas extraction from Ukrainian and Russian facilities. Single-source vulnerability permeates EUV lithography equipment where ASML's monopoly limits 3nm-to-5nm expansion to pre-existing equipment allocations. Distribution runs through direct foundry contracts for large-scale cloud and automotive module buyers, displacing traditional electronics distributors in Singapore and Hong Kong for leading-edge logic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field application engineering services and long-term capacity reservation contracts are expanding faster than hardware unit sales across APAC semiconductor procurement, creating substantial service-attach revenue pools for foundries and OSAT providers.
For Market Incumbents: Harden lithography equipment access through sovereign-fab partnerships in Japan's Kumamoto prefecture and India's Gujarat corridor to offset Taiwan concentration risk. Lock in multi-year neon and helium supply agreements with Ukrainian and Qatari extraction facilities before commodity volatility intensifies. Vertical integration into 2.5D/3D packaging capacity in Vietnam's Bac Ninh province addresses the emerging threat of Southeast Asian OSAT competitors capturing backend margin. For New Entrants and Emerging Players: India's 28nm-to-65nm mature-node production gap under the PLI scheme represents the most penetrable entry point for foundry greenfield investment. Malaysia's Penang backend packaging cluster offers white-space opportunity for GaN power module integration serving Chinese EV suppliers. A go-to-market angle anchored to MIIT GB energy-efficiency certification support accelerates qualification timelines with domestic power module makers. For Investors and Strategic Acquirers: Japan's METI export-control alignment with allied technology regimes reshapes the acquisition landscape toward equipment makers with deposition and etch tool development capabilities. Long-term viability over the analysis window favors targets with established backend packaging footprints in Southeast Asia rather than pure front-end node access. The signal to watch is TSMC's southern Taiwan mega-fab utilization rates as an early indicator of regional supply-demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | 2.5D/3D integration in Vietnam's northern provinces reduces Taiwan backend dependency for Chinese hyperscale customers. |
| Sovereign Fab Partnership | TSMC's Kumamoto joint-venture with Sony and Denso secures 28nm automotive logic supply for Toyota electrification programs. |
| GaN Process Qualification | Xiamen and Hefei foundries adopting GaN-on-silicon meet China's GB efficiency standards for BYD onboard chargers. |
| Long-term Capacity Agreement | Three-to-five year pre-payment structures with penalty clauses lock in wafer supply for South Korean automotive module suppliers. |
| EUV Technician Training Program | Taiwan-Netherlands engineering cohort expansion addresses lithography maintenance scarcity constraining 3nm node expansion. |
Research Methodology
Cross-validation between primary interviews with foundry operations executives, fabless design house CTOs, automotive Tier 1 procurement directors, and OSAT backend engineering leads anchors the qualitative findings. Secondary validation incorporates SEMI equipment shipment data, MIIT GB standard filings, Japan METI subsidy disclosures, and India PLI scheme participant announcements. Bottom-up wafer start projections and top-down electronics OEM procurement spend estimates complete the triangulation.
Calibration against historical node transition cycles and foundry utilization rate patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span product type (logic, memory, power management, analog), application (consumer electronics, automotive, industrial automation, telecommunications), technology node (3nm-to-28nm geometries), and end-user procurement modality (direct foundry, distributor, captive). CAGRs derive from weighted average of equipment spending trajectories and design win pipeline conversions. Industry-specific forecast inputs include EUV machine delivery schedules from ASML and Chinese domestic foundry buildout permits from MIIT.
Practitioners should monitor ASML equipment allocation delays, Japan METI export-control expansion scope, and China MIIT subsidy recalibration for early signals of forecast revision. Cross-checking against SEMI silicon wafer shipment benchmarks and foundry revenue guidance aggregates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
ATX Motherboards Market