
 India MLCC Market | 2026-2036
India MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
India MLCC Market Insights
Buyer concentration among Indian smartphone OEMs and tier-1 automotive suppliers is pivoting toward domestic MLCC sourcing as tariff structures favor local assembly. Samsung Electro-Mechanics leverages its Chennai manufacturing footprint to anchor supply contracts with major handset brands. TDK Corporation sustains R&D intensity in high-voltage dielectric formulations for EV powertrain applications. Murata Manufacturing Co., Ltd competes through specialized low-ESR product lines targeting 5G base station deployments.
Multilayer ceramic capacitors are passive electronic components constructed from alternating layers of ceramic dielectric and metal electrode materials, fired into monolithic structures that achieve capacitance densities exceeding ten microfarads per cubic millimeter; they function primarily for charge storage, noise filtering, and voltage stabilization in high-density circuit boards. The product type landscape shows SMD capacitors dominating volume while high-voltage radial variants capture concentrated margin pools in industrial inverter systems. End-user demand from automotive electrification and telecommunications infrastructure outpaces consumer electronics growth, with high-frequency technology segments expanding fastest due to millimeter-wave 5G rollouts.
BIS mandatory certification for electronic components and the PLI scheme for semiconductor manufacturing create compliance thresholds that filter import-dependent suppliers while accelerating domestic fab partnerships. CDSCO-equivalent medical device regulations and CEA power quality standards extend MLCC specification requirements into defibrillator and grid-tied inverter applications. Stakeholders must monitor PLI disbursement timelines and BIS testing capacity expansion to calibrate localization investment decisions against import parity economics.
Market Dynamics
The Production Linked Incentive scheme for semiconductor manufacturing is restructuring supplier qualification criteria across India's electronics ecosystem, forcing component vendors to localize dielectric powder processing and electrode firing capabilities or forfeit tier-1 OEM contracts.
Growth Catalysts
- PLI scheme disbursements:The government's performance-linked incentive payouts for semiconductor components are compressing payback periods for domestic MLCC fab investments. Tamil Nadu and Gujarat state governments are matching central subsidies with land and power concessions.
- Smartphone OEM localization mandates:Major handset brands operating in India face tariff escalation on fully-built device imports. These brands are now mandating domestic MLCC sourcing for PCB assembly within the Sriperumbudur cluster.
- EV powertrain electrification:Automotive battery management systems and onboard chargers require high-voltage ceramic capacitors withstanding 800V operating conditions. This dielectric specification is pulling capacity expansion toward automotive-grade formulations.
Market Restraints
- Barium titanate supply concentration:High-purity ceramic dielectric precursor materials remain concentrated among Japanese and Chinese chemical suppliers. Indian manufacturers face input cost volatility and extended lead times for nano-grade powder.
- BIS testing capacity bottlenecks:Mandatory certification for electronic components under Bureau of Indian Safety standards faces backlog at domestic laboratories. This regulatory friction delays product qualification timelines by four to six months.
- Aluminum electrolytic substitution in cost-sensitive segments:Consumer appliance manufacturers in price-competitive categories continue specifying wet electrolytic capacitors where ceramic alternatives would offer superior reliability.
Strategic Opportunities
- Medical device electrification:CDSCO-equivalent regulations for defibrillators and implantable cardiac devices are mandating high-reliability passive components. This emerging application offers margin premiums above consumer electronics benchmarks.
- 5G base station deployment:Millimeter-wave infrastructure rollouts by TRAI-licensed telecom operators require ultra-low ESR ceramic capacitors for RF filtering. This technology convergence creates specification windows for specialized dielectric formulations.
- Direct OEM contracting models:Tier-1 automotive suppliers and smartphone assemblers are bypassing traditional distribution channels. This channel innovation allows capacitor manufacturers to capture margin previously allocated to electronics distributors.
Industry Challenges
- Thin-film deposition expertise scarcity:The precision electrode layering process for high-capacitance-density MLCCs requires ceramic engineering specialists. Indian technical institutes currently produce limited graduates with this specific process knowledge.
- Legacy equipment integration complexity:Domestic manufacturers importing firing kiln and tape-casting equipment from East Asian suppliers face calibration mismatches with existing quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India MLCC Market |
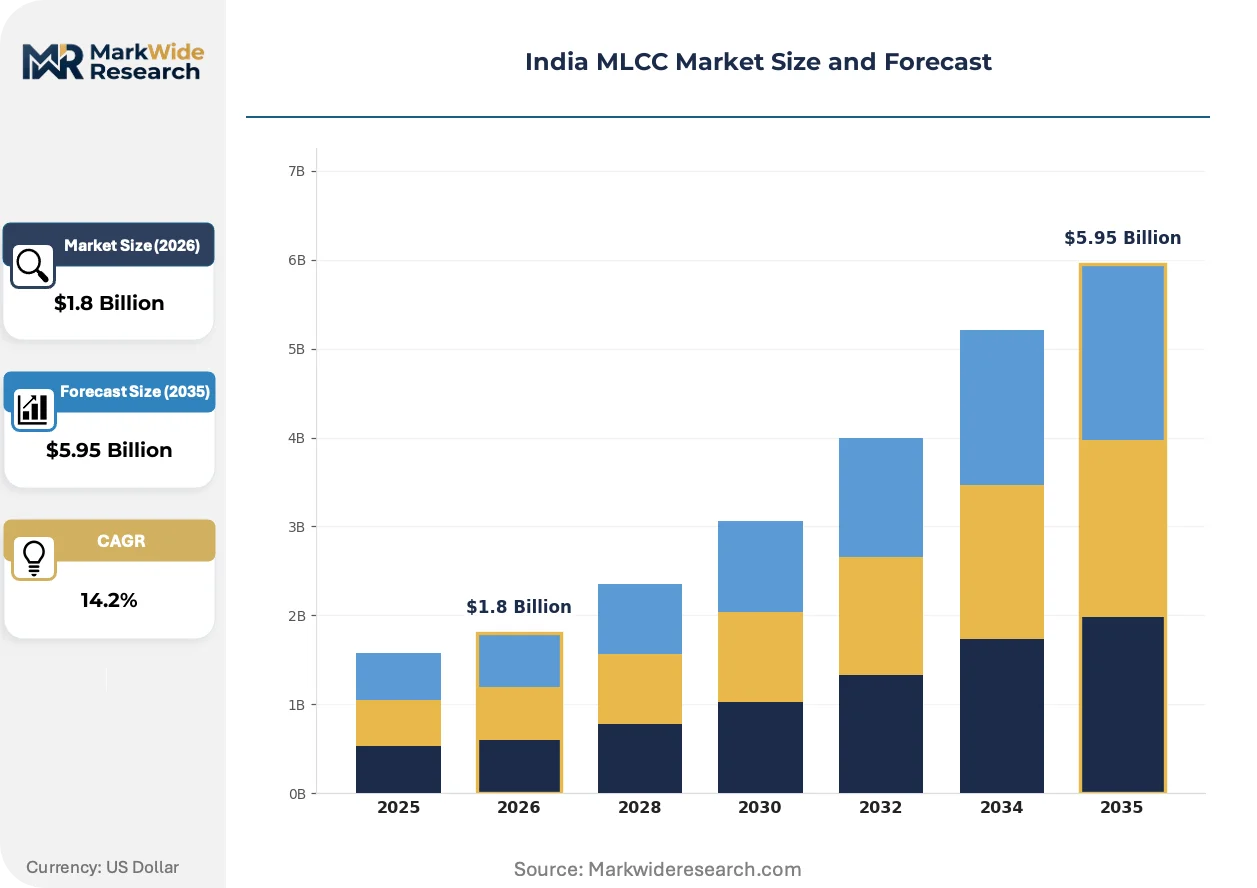
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer Ceramic Capacitors, Chip Capacitors, Radial Capacitors, SMD Capacitors End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: MLC Technology, High Voltage Technology, High Frequency Technology, Low ESR Technology Application: Power Supplies, Signal Processing, RF Applications, Filtering |
| Companies Covered | Kyocera AVX Components Corporation, Walsin Technology Corporation, Murata Manufacturing Co., Ltd, Yageo Corporation, Maruwa Co., Ltd, Samsung Electro-Mechanics, Taiyo Yuden Co., Ltd, Holy Stone Enterprise Co., Ltd, TDK Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India MLCC Market Trends and Innovations
Dielectric material science and regulatory compliance frameworks are compressing product development cycles while expanding specification requirements across automotive and telecommunications verticals.
High-voltage X7R and C0G dielectric formulations are consolidating as the dominant technology for EV powertrain applications. Automotive tier-1 suppliers in the Pune-Nashik corridor are qualifying these ceramic compositions for 800V battery systems. This dielectric consolidation is compressing the addressable market for lower-temperature-coefficient alternatives.
BIS mandatory certification for passive electronic components is tightening import pathways while accelerating domestic laboratory accreditation. The regulation requires destructive testing samples that consume production volumes during qualification. Medical device and automotive segments are responding by pre-qualifying multiple domestic suppliers to hedge against testing delays.
Smartphone OEMs are compressing supplier qualification cycles from eighteen months to nine months to match product refresh velocities. This behavioral shift is displacing traditional electronics distributors with direct manufacturer relationships. The Tamil Nadu electronics cluster exhibits the most visible concentration of this procurement model transformation.
India MLCC Market Segmentation
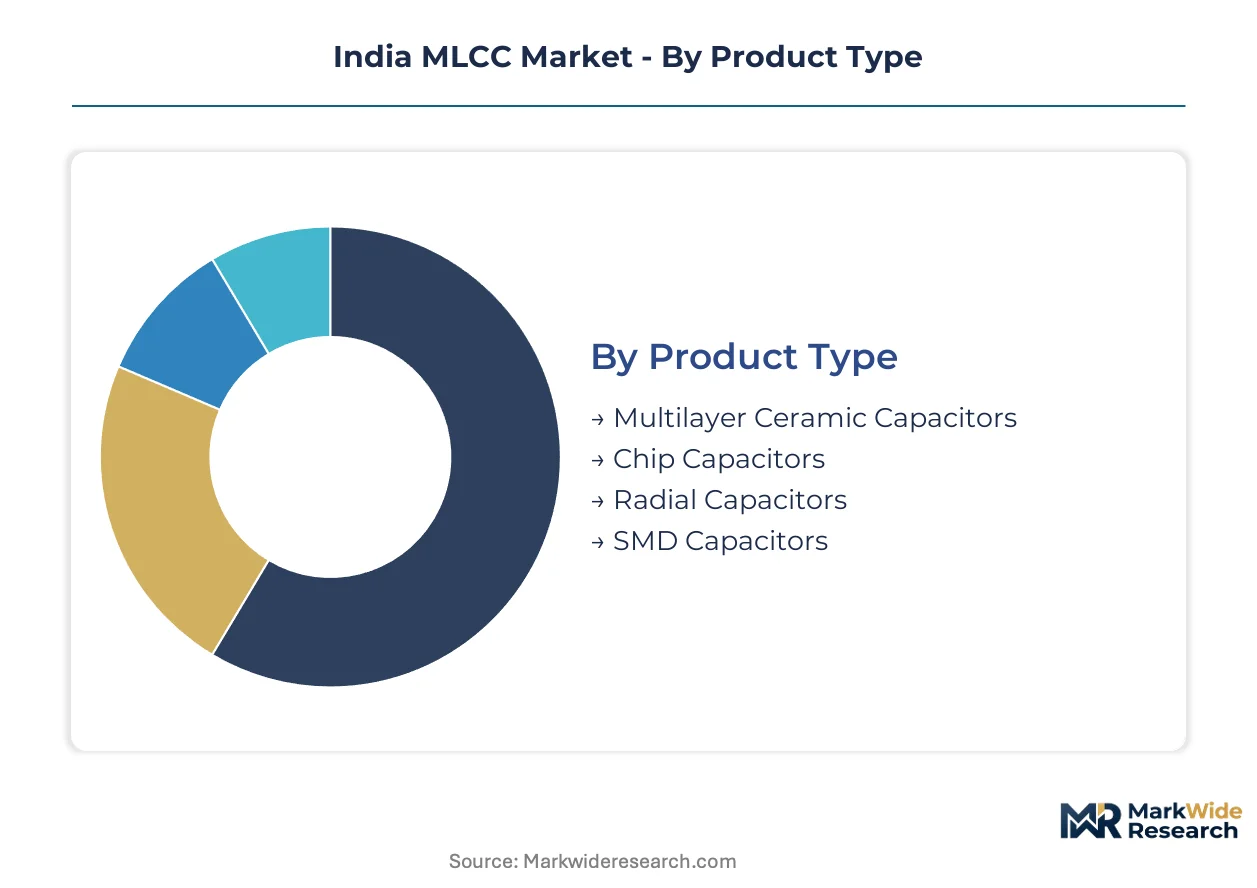
MLCC procurement in India diverges sharply across product architectures and end-use specifications, with BIS certification tiers and PLI scheme eligibility creating distinct qualification pathways for each segment category. Understanding these boundaries enables suppliers to calibrate dielectric formulations and electrode firing investments against addressable contract pools.
Product Type:
Buyers prioritize surface-mount compatibility and voltage withstand ratings when selecting capacitor architectures for PCB assembly operations.
- SMD Capacitors:Surface-mount devices integrate directly onto printed circuit boards through reflow soldering processes, eliminating lead-forming operations. Smartphone OEMs in Tamil Nadu's Sriperumbudur cluster specify these exclusively for handset motherboard assembly to match high-density packaging requirements. The form factor dominates volume procurement from domestic EMS providers.
- Chip Capacitors:These rectangular ceramic components feature end-blasted nickel-barrier terminations compatible with lead-free solder alloys. Demand concentrates in Gujarat's semiconductor ecosystem where chip-scale packaging for automotive sensor modules requires compact charge storage elements. The segment captures concentrated margin pools from tier-1 automotive suppliers.
- Multilayer Ceramic Capacitors:Broad category encompassing stacked dielectric constructions achieving high capacitance density through alternating ceramic and electrode layers.
- Radial Capacitors:Leaded through-hole configurations retain relevance in industrial inverter systems requiring mechanical stability under thermal cycling stress.
SMD capacitors lead on scale; chip capacitors lead on momentum as automotive electrification accelerates.
End User:
Application voltage requirements and reliability specifications segment the buyer base into distinct procurement behavior clusters.
- Automotive:Battery management systems and onboard chargers for electric vehicles demand X7R and C0G dielectric formulations rated for 800V operating conditions. Pune-Nashik corridor tier-1 suppliers are qualifying these compositions for powertrain electrification programs. The segment commands premium pricing above consumer electronics benchmarks.
- Consumer Electronics:Smartphone, tablet, and wearable device manufacturers drive high-volume demand for compact multi-layer constructions. Domestic assembly operations under PLI scheme incentives specify BIS-certified components from Chennai-area manufacturing footprints. Price compression remains intense as OEMs optimize bill-of-materials costs.
- Telecommunications:5G base station deployments by TRAI-licensed operators require specialized ceramic components for RF signal integrity.
- Industrial Equipment:Motor drives and power conversion systems specify high-voltage radial configurations for grid-tied inverter applications.
Consumer electronics leads on scale; automotive leads on momentum with the steepest expansion trajectory from EV adoption curves.
Technology:
Dielectric material science and electrode layering precision determine competitive positioning across specification tiers.
- High Frequency Technology:Millimeter-wave 5G infrastructure deployments require ultra-low equivalent series resistance for RF filtering performance. TRAI-licensed telecom operators are specifying these formulations for base station rollouts in urban corridors. The technology segment expands most quickly due to spectrum auction commitments.
- High Voltage Technology:Dielectric formulations withstand elevated electric field intensities without breakdown for EV powertrain applications. Automotive suppliers in the Pune-Nashik corridor qualify these for 800V battery systems and onboard charging modules. The specification tier captures concentrated automotive contract value.
- MLC Technology:Standard multilayer ceramic constructions serve mainstream consumer electronics and industrial applications.
- Low ESR Technology:Reduced equivalent series resistance improves power efficiency in switching regulator circuits.
MLC technology leads on scale; high frequency technology leads on momentum.
Application:
Circuit function requirements dictate capacitance tolerance, temperature coefficient, and voltage rating specifications.
- Power Supplies:Input filtering and output smoothing functions in AC-DC and DC-DC converters require high capacitance density with stable thermal characteristics. EV onboard chargers and smartphone adapters specify these for voltage ripple suppression. The application absorbs substantial volume from domestic EMS operations.
- RF Applications:Impedance matching and signal coupling in radio frequency circuits demand tight capacitance tolerance and low dielectric loss. 5G base station deployments by TRAI-licensed operators specify C0G and X7R formulations for millimeter-wave performance. The segment commands specification premiums.
- Signal Processing:Coupling and decoupling functions in analog and digital circuits.
- Filtering:EMI suppression and noise attenuation across frequency bands.
Power supplies lead on scale; RF applications lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramic engineering talent concentrates in Tamil Nadu's Sriperumbudur corridor and Gujarat's semiconductor corridor, anchoring India's MLCC manufacturing base. These workforce clusters feed dielectric formulation expertise into domestic fab operations. State-level industrial policies amplify central PLI scheme incentives.
Tamil Nadu
Smartphone OEM assembly operations and EMS providers drive concentrated demand for SMD capacitors. The state's Electronics Manufacturing Policy offers capital subsidies matching central PLI disbursements. Sriperumbudur hosts Samsung Electro-Mechanics' manufacturing footprint serving domestic handset brands.
Gujarat
Semiconductor fab investments and automotive sensor packaging create pull for chip-scale MLCC configurations. The state's Dholera Special Investment Region provides land and power concessions under its Electronics Policy. Dholera's semiconductor ecosystem is attracting dielectric powder processing partnerships.
Karnataka
Telecommunications infrastructure and 5G base station deployments generate demand for high-frequency ceramic formulations. The state's Electronics, IT and BT Department administers incentive packages for component manufacturing. Bengaluru's electronics R&D corridor hosts RF application design centers.
Maharashtra
Automotive tier-1 suppliers in the Pune-Nashik corridor qualify high-voltage dielectrics for EV powertrain systems. The state's Magnetic Maharashtra electronics policy extends production subsidies to passive component manufacturers. Pune's automotive electronics cluster is integrating 800V-rated ceramic capacitors.
Telangana
Defense electronics and aerospace applications require high-reliability MLCC specifications with extended temperature ranges. The state's T-Hub electronics policy supports component manufacturing through subsidized testing infrastructure. Hyderabad's defense electronics ecosystem is qualifying domestic suppliers for strategic applications.
India MLCC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's MLCC procurement landscape. The supplier base exhibits moderate concentration, with Japanese and Korean manufacturers holding established positions alongside emerging domestic fabricators. Two strategic archetypes dominate: integrated materials-to-components conglomerates controlling dielectric powder supply chains, and specialized capacitor manufacturers focusing on application-specific formulations. Capacity expansion and direct OEM contracting represent the prevailing competitive moves, displacing traditional distributor relationships.
Among Japanese manufacturers, Murata Manufacturing Co., Ltd and TDK Corporation exemplify the integrated conglomerate archetype with materials science capabilities spanning dielectric formulations. Samsung Electro-Mechanics occupies a position as the Korean specialist with established domestic manufacturing presence. These three anchors sit within different strategic tiers—Murata and TDK representing premium specification portfolios, Samsung Electro-Mechanics anchoring high-volume consumer electronics supply.
| Leading Market Players |
|---|
| Kyocera AVX Components Corporation |
| Walsin Technology Corporation |
| Murata Manufacturing Co., Ltd |
| Yageo Corporation |
| Maruwa Co., Ltd |
| Samsung Electro-Mechanics |
| Taiyo Yuden Co., Ltd |
| Holy Stone Enterprise Co., Ltd |
| TDK Corporation |
| Others |
Pricing and Supply Chain Analysis
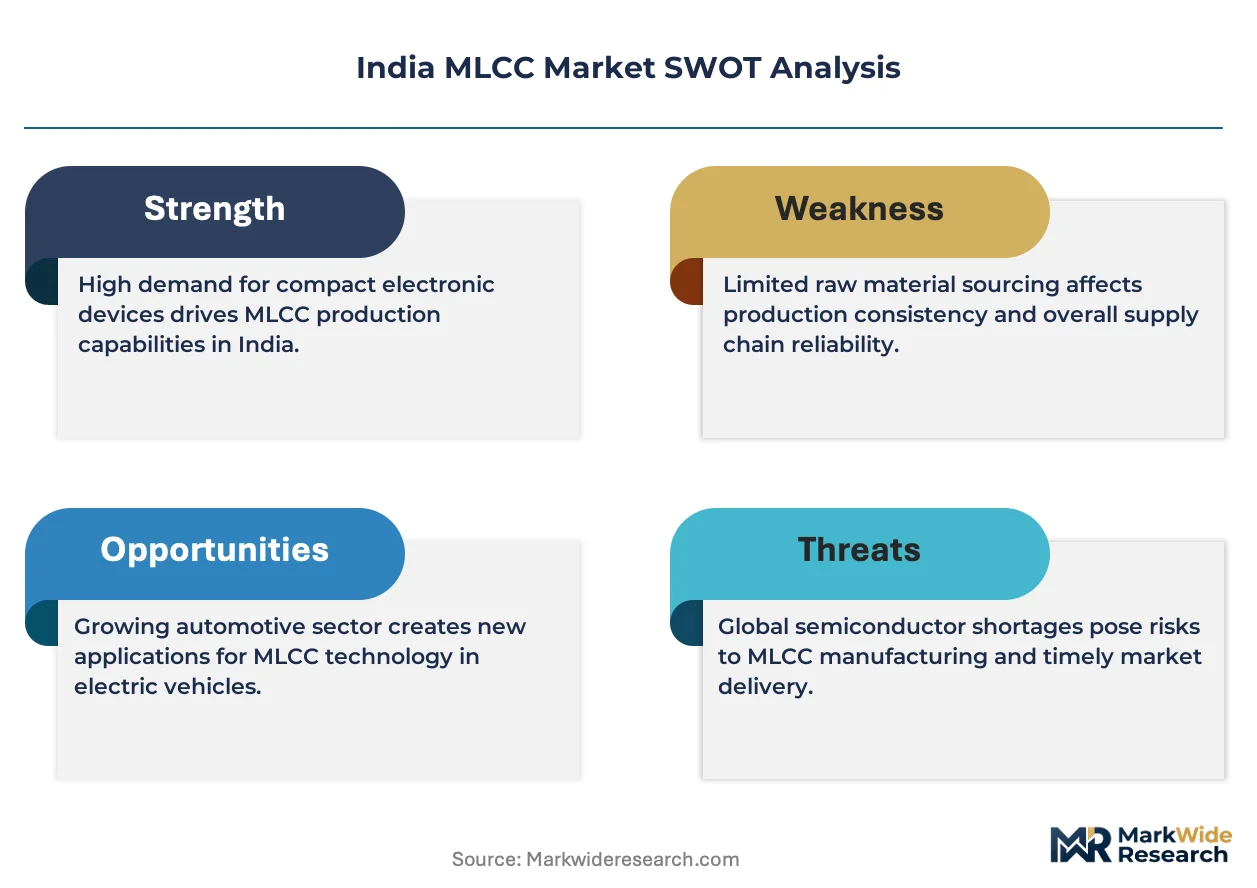
Nano-grade barium titanate powder flows from Japanese and Chinese chemical suppliers through dielectric formulation tiers before crystallizing into procurement premiums for automotive-grade MLCCs and cost-competitive pricing for consumer electronics volumes. This upstream concentration in ceramic dielectric precursors grants pricing leverage to powder specialists while compressing margins for Indian fabricators facing BIS certification overheads and PLI scheme compliance costs.
Pricing Analysis
Component-plus-certification bundling separates automotive-grade X7R formulations from unbundled consumer electronics spot purchases, with BIS testing fees and dielectric powder grade acting as the primary price differentiation drivers. Pricing pressure intensifies in smartphone SMD tiers as domestic EMS providers consolidate purchase volumes under PLI-linked contracts. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to 800V reliability requirements, while appliance manufacturers remain most sensitive given aluminum electrolytic substitution options.
Supply Chain Analysis
End-of-life electronics recovery flows remain nascent in India, with spent MLCCs from Tamil Nadu's Sriperumbudur cluster largely exiting formal reverse channels rather than feeding secondary material streams. Supply draws from Japan, South Korea, and China for high-purity barium titanate, nickel electrode pastes, and precision firing equipment. Single-source vulnerability concentrates in nano-grade dielectric powder where Japanese chemical houses dominate refinement capabilities. Distribution runs through direct OEM contracting models that displace traditional electronics distributors in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India MLCC market compounds steadily as domestic electronics manufacturing scales under tariff-protected assembly mandates and PLI scheme disbursements. This structural demand floor supports consistent capacity utilization for qualified suppliers.
For Market Incumbents: Hedge against aluminum electrolytic substitution in appliance segments by accelerating high-voltage dielectric R&D for EV powertrain qualification. Secure backward integration into barium titanate precursor partnerships with Japanese chemical suppliers to dampen input cost volatility. Prioritize BIS laboratory accreditation investments to compress certification timelines that currently delay contract awards.
For New Entrants and Emerging Players: High-frequency dielectric formulations for 5G base station deployments offer the most penetrable technology wedge given TRAI spectrum auction commitments and limited domestic RF-specialized competition. Target Karnataka's Bengaluru corridor where telecom infrastructure design centers cluster. Pursue direct contracting relationships with TRAI-licensed operators rather than distributor-dependent channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where thin-film deposition expertise scarcity constrains domestic high-capacitance-density production. The five-to-ten year viability window favors acquisition targets with captive dielectric powder processing partnerships or established BIS certification portfolios. Monitor PLI disbursement velocity as the critical inflection signal for localization investment payback periods.
| Strategic Initiative | Industry Significance |
|---|---|
| Dielectric Powder Backward Integration | Captive barium titanate supply secures margin against Japanese chemical supplier pricing power. |
| BIS Laboratory Accreditation Expansion | Domestic testing capacity cuts four-to-six month qualification delays threatening contract capture. |
| Direct OEM Contracting Model | Bypassing electronics distributors captures margin previously allocated to channel intermediaries. |
| High-Voltage Automotive Qualification | 800V X7R certification opens Pune-Nashik EV powertrain supplier contracts. |
| 5G RF Specialization Investment | Ultra-low ESR formulations target TRAI-licensed base station deployment specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dielectric formulation engineers, tier-1 automotive procurement leads, EMS operations directors, BIS certification officers, and PLI scheme administrators with secondary validation. Sources included BIS certification databases, TRAI spectrum auction disclosures, PLI disbursement records, customs import data for ceramic dielectric precursors, and SEC filings of listed capacitor manufacturers. Bottom-up capacity buildout estimates triangulated against top-down electronics production forecasts.
Segment-weighting applied differential growth assumptions across dielectric technology tiers, end-use verticals, and regional production clusters throughout the projection horizon. The analytical framework modeled product type, end user, technology specification, and application dimensions with state-level policy intensity as an overlay variable. CAGRs derived from capacity utilization trajectories, PLI incentive absorption rates, and import substitution elasticities rather than extrapolated historical trends.
The model holds under sustained PLI disbursement schedules and stable barium titanate supply conditions; deviation in BIS testing capacity expansion or Japanese chemical supplier pricing would shift trajectory. Forecasts reflect these base assumptions with acknowledged sensitivity to tariff policy adjustments and EV adoption curve revisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Gan-On-Silicon Market