
 Mobile Phone Semiconductor Market | 2026-2036
Mobile Phone Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Phone Semiconductor Market Foresight
Chiplet-based heterogeneous integration is tilting mobile semiconductor architectures away from monolithic dies toward disaggregated compute, memory, and I/O tiles. Qualcomm Technologies Inc leverages its Snapdragon platform to anchor premium-tier smartphone sockets through tightly coupled modem-RF systems. MediaTek Inc competes aggressively in mid-range and emerging-market chipsets with integrated 5G SoC designs that compress bill-of-material costs for OEMs.
Mobile phone semiconductors encompass application processors, modems, power management ICs, and memory chips fabricated on nodes ranging from mature 28nm to advanced 3nm FinFET, serving the core function of enabling wireless communication, multimedia processing, and energy-efficient compute in handheld devices. Application processors and memory chips together command the dominant share of semiconductor value in smartphones, with memory margins cyclically expanding and compressing around DRAM and NAND supply-demand balances. Power management ICs represent a structurally stable margin pool where analog-mixed signal expertise creates defensible supplier positions against digital-centric competitors.
The US FCC governs RF emission standards that directly shape modem and front-end module certification timelines, while EU REACH and RoHS restrict hazardous substances in semiconductor packaging and substrate materials. China's MIIT enforces domestic 5G spectrum allocation and equipment certification rules that influence baseband chip feature requirements for vendors serving that market. Stakeholders must monitor how export control frameworks and carbon-border adjustments recalibrate foundry location decisions and captive supply strategies across the value chain.
Market Dynamics
Chiplet disaggregation is forcing a fundamental restructuring of mobile semiconductor value chains as monolithic die economics collapse under reticle limits and yield constraints at 3nm and below.
Growth Catalysts
- 5G SoC Integration:Smartphone OEMs now mandate single-die modem-application processor combinations to reduce board space and power leakage. This compression is digitizing mid-tier device capabilities previously reserved for flagship tiers.
- EU REACH Substance Rules:Hazardous material restrictions on semiconductor packaging substrates are accelerating lead-free solder and halogen-free laminate adoption across European-bound production lines.
- Memory Demand Cyclicality:DRAM and NAND supply-demand imbalances create periodic margin expansion windows that fund foundry capacity expansion for logic chip production.
Market Restraints
- Advanced Node Concentration:Taiwan's advanced logic wafer fabrication cluster controls the majority of sub-5nm production, creating single-point-of-failure exposure for smartphone chip supply.
- EUV Lithography Capital Intensity:Each EUV scanner requires substantial capital outlay, constraining foundry entry and locking supply expansion to incumbent balance sheets.
- Analog-Mixed Signal Talent Scarcity:Power management IC design expertise concentrates in aging engineering populations without commensurate pipeline replenishment.
Strategic Opportunities
- India PLI Scheme:Production-linked incentive frameworks for electronics manufacturing are attracting semiconductor assembly and test capacity to diversify supply footprints.
- Automotive Edge AI Convergence:Smartphone-derived neural processing unit architectures are migrating into vehicle cockpit systems, opening adjacent revenue pools for mobile chip designers.
- China Dual Carbon Mandates:Foundry energy intensity regulations are accelerating renewable power purchase agreements and process efficiency investments that lower long-term operating costs.
Industry Challenges
- RF Front-End Modularization:Millimeter-wave antenna-in-package integration demands cross-domain expertise spanning semiconductor, substrate, and electromagnetic simulation disciplines that rarely coexist in single engineering teams.
- Export Control Compliance:Multilateral semiconductor manufacturing equipment restrictions fragment design tool access and complicate customer targeting for advanced node IP providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Phone Semiconductor Market |
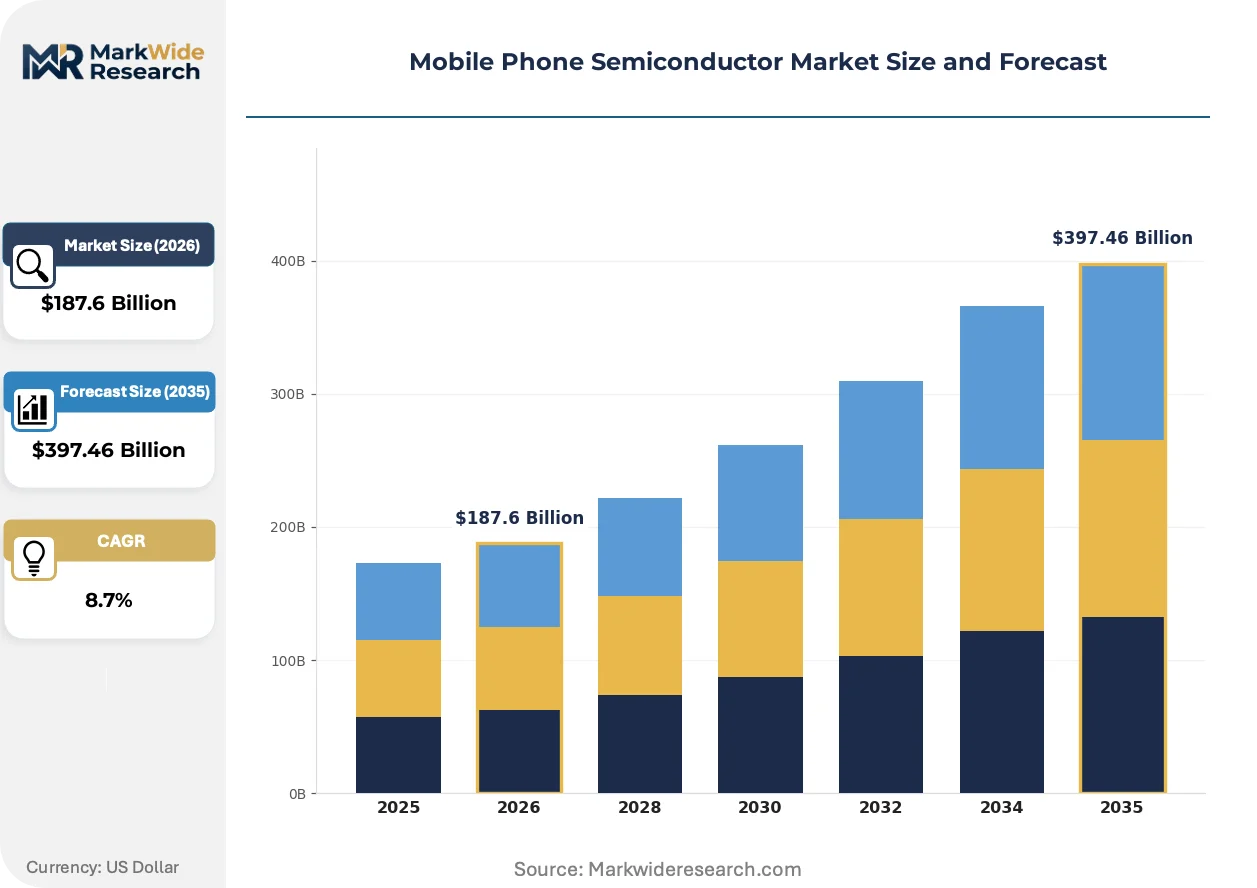
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application Processors, Modems, Power Management ICs, Memory Chips Technology: CMOS, FinFET, GaN, SoC End User: OEMs, Aftermarket Providers, Retailers, Distributors Form Factor: Surface Mount, Chip-on-Board, Ball Grid Array, Chip-on-Carrier |
| Companies Covered | Broadcom Inc, Skyworks Solutions Inc, Qualcomm Technologies Inc, Micron Technology Inc, Qorvo Inc, MediaTek Inc, NXP Semiconductors N.V., Huawei Technologies Co Ltd, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Phone Semiconductor Market Shifts & Advancements
Architectural decomposition and sovereign supply chain policies are converging to reshape how mobile compute, memory, and connectivity functions are packaged, sourced, and certified across handset value chains.
Die-to-die interconnect standards are digitizing heterogeneous integration roadmaps as Universal Chiplet Interconnect Express (UCIe) specifications enable mixing of compute tiles from disparate foundries and process nodes. Qualcomm and MediaTek are both evaluating chiplet-based Snapdragon and Dimensity architectures for 2026 flagship launches. This modularity is compressing time-to-market for feature upgrades while decoupling memory and logic refresh cycles.
China's MIIT 5G spectrum allocation rules are mandating domestic sub-6GHz and millimeter-wave band support that diverges from FCC and CEPT harmonization patterns. Baseband chip vendors must maintain parallel RF calibration firmware branches for China-bound versus export-oriented handset SKUs. This regulatory fragmentation is inflating validation engineering headcount and extending certification timelines for new modem platforms.
Smartphone OEM procurement is consolidating toward platform-level socket awards rather than discrete component sourcing, with Apple, Samsung, and Xiaomi negotiating multi-year application processor and modem bundle commitments. Direct foundry relationships are displacing traditional merchant semiconductor distribution for high-volume tier-one accounts. This concentration is most visible in South Korea and Taiwan, where captive supply agreements now govern the majority of premium-tier chipset allocation.
Mobile Phone Semiconductor Market Segmentation
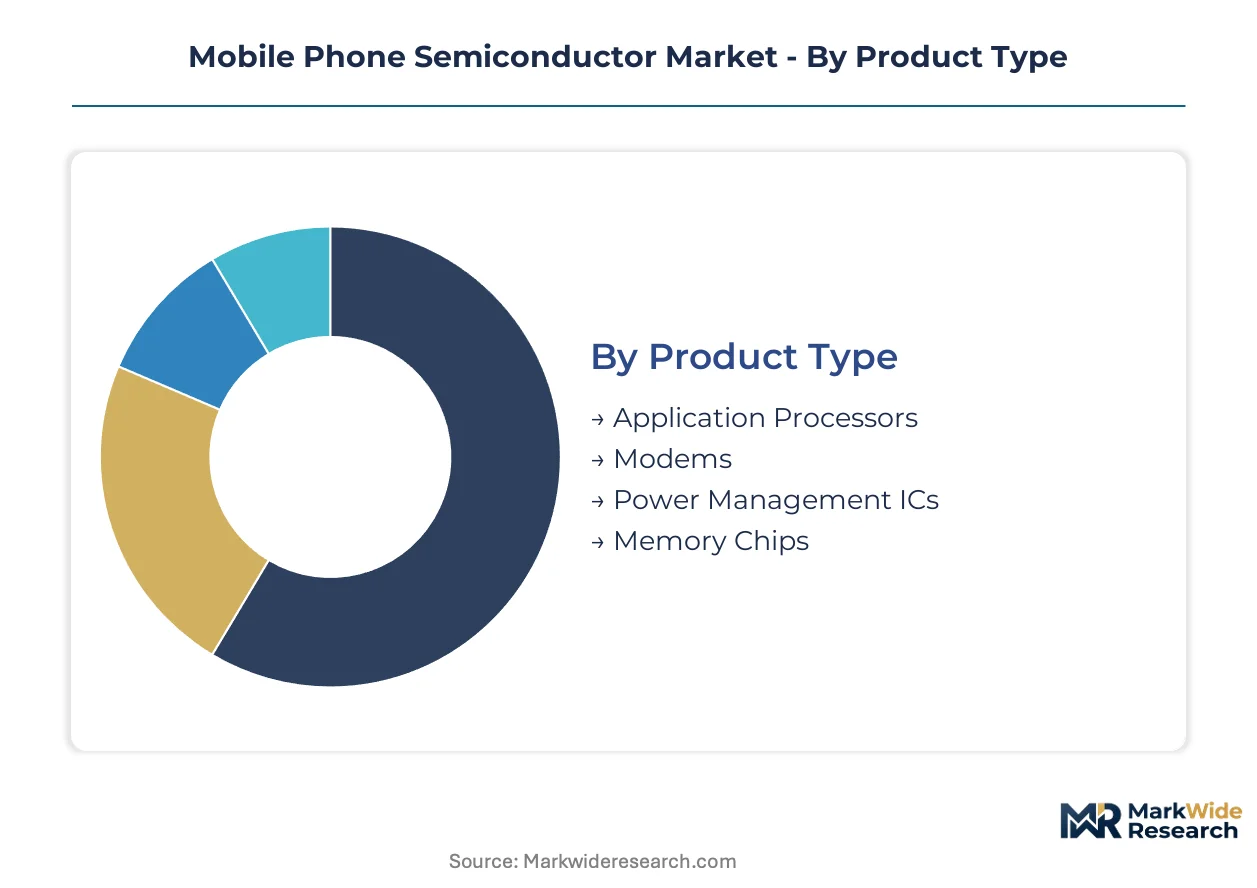
Mobile phone semiconductor procurement cycles vary dramatically across product categories, with memory and application processors refreshing on 12-18 month cadences while power management ICs and analog components often span 36-48 month design-ins. Understanding these velocity differentials helps suppliers align inventory strategies and R&D roadmaps with actual replacement demand patterns.
Product Type:
Application processors and memory chips turn over fastest as OEMs chase annual performance tiering, while power management ICs and modems embed for longer platform lifecycles due to certification inertia and analog design stability.
- Application Processors:These system-on-chip designs integrate CPU, GPU, and neural processing cores on advanced FinFET nodes. Qualcomm's Snapdragon and MediaTek's Dimensity families dominate premium and mid-tier sockets respectively, with 5G modem integration now mandatory for new design wins.
- Memory Chips:DRAM and NAND flash constitute the largest semiconductor cost stack in smartphones. Samsung and SK Hynix supply Korean and Chinese OEMs from their domestic fabrication corridors, with LPDDR5X and UFS 4.0 interfaces becoming baseline for flagship tier qualification.
- Modems:Standalone baseband processors persist in automotive and IoT tethering applications, though smartphone sockets increasingly demand integrated modem-AP combinations to compress board area and power budgets.
- Power Management ICs:Analog-mixed signal expertise concentrates in Texas Instruments, Qualcomm, and Dialog Semiconductor product lines, with multi-rail voltage regulators and battery fuel gauges representing structurally stable margin pools.
Memory chips anchor the volume base while application processors gain share at the steepest rate as heterogeneous integration expands their functional scope.
Technology:
Process node selection maps directly to cost tier and performance requirements, with foundry availability and EUV scanner access constraining supply elasticity at the leading edge.
- FinFET:Tri-gate transistor architecture at 5nm, 4nm, and 3nm nodes enables the power-performance density required for flagship smartphone application processors. TSMC's N3E and Samsung's 3GAE processes compete for Snapdragon and Exynos foundry allocation.
- CMOS:Mature planar processes at 28nm and above serve power management, display driver, and image signal processing functions where analog precision outweighs digital density. SMIC and GlobalFoundries maintain significant capacity for these nodes.
- SoC:System-on-chip integration compresses modem, application processor, and AI accelerator functions onto monolithic dies or emerging chiplet assemblies, reducing bill-of-material complexity for OEMs.
- GaN:Gallium nitride power devices penetrate fast-charging adapter and RF front-end applications, offering switching efficiency advantages over silicon counterparts in high-frequency power conversion.
CMOS sustains the broadest installed base while FinFET commands the premium pricing tier.
End User:
Direct OEM relationships displace traditional distribution as procurement concentrates among the top five smartphone manufacturers, though aftermarket channels retain relevance for repair ecosystems and emerging market refurbishment.
- OEMs:Apple, Samsung, Xiaomi, OPPO, and vivo negotiate multi-year chipset platform commitments directly with Qualcomm, MediaTek, and Samsung LSI. These accounts drive 70% of premium-tier semiconductor demand and set interface standards that cascade to mid-tier designs.
- Distributors:Arrow, Avnet, and regional specialists like WPG Holdings manage inventory and logistics for smaller OEMs and aftermarket providers, though their share compresses as direct foundry relationships expand.
- Aftermarket Providers:Independent repair shops and refurbishment operations source legacy chipsets for screen replacement and battery service workflows, particularly in India, Southeast Asia, and Latin American markets.
- Retailers:Consumer electronics chains and carrier stores represent minimal direct semiconductor procurement, functioning primarily as finished handset sales channels rather than component demand sources.
OEMs dominate procurement volume while aftermarket providers expand fastest as right-to-repair regulations strengthen.
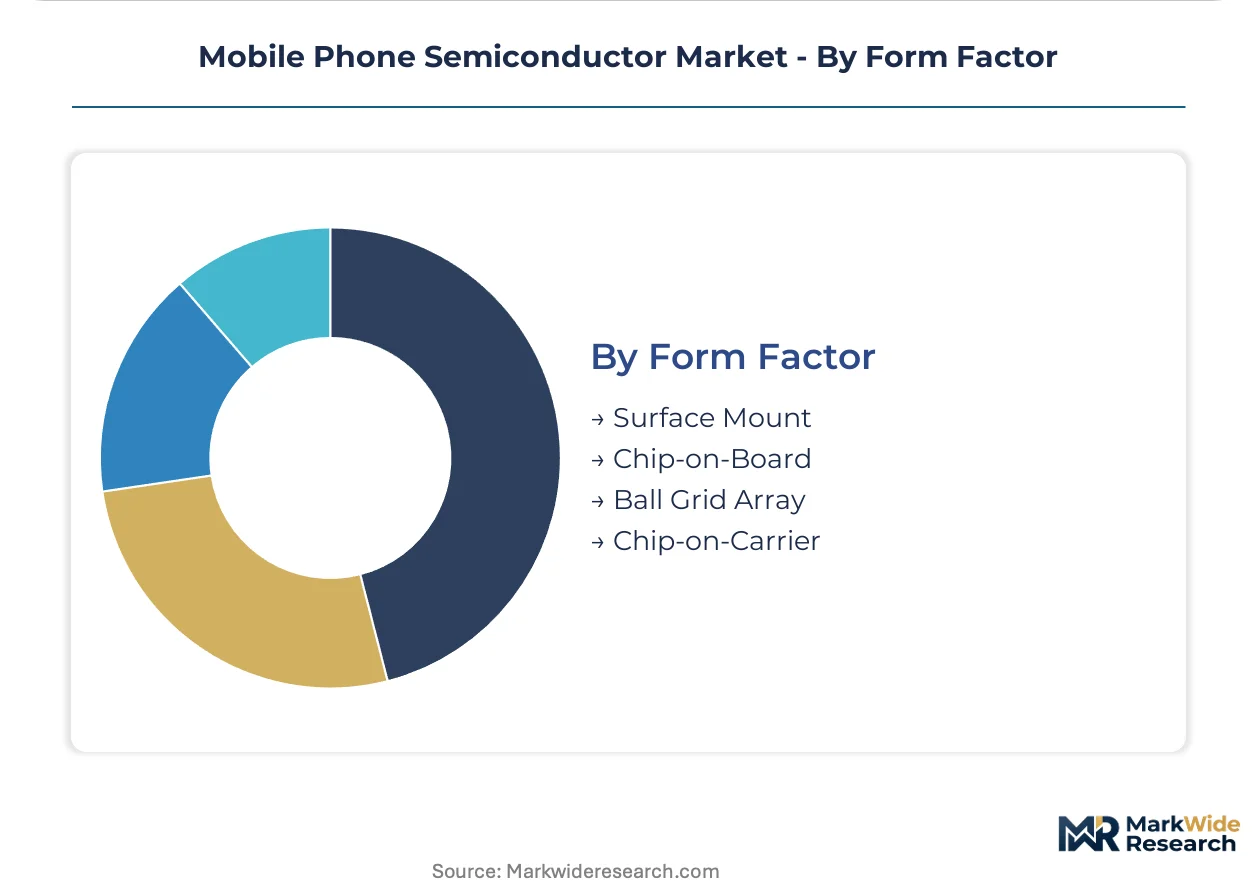
Form Factor:
Packaging selection balances thermal performance, signal integrity, and assembly automation requirements, with advanced smartphone designs driving migration toward denser interconnect schemes.
- Ball Grid Array:BGA packages with 0.4mm and 0.35mm pitch dominate application processor and memory deployments, enabling high pin counts in compact footprints. Flip-chip and wire-bond variants serve different cost-performance tiers.
- Surface Mount:QFN and small-outline packages persist for power management, audio codec, and sensor hub functions where pin counts remain modest and cost sensitivity is acute.
- Chip-on-Board:Direct die attach with wire bonding serves ultra-low-cost feature phones and select IoT tethering devices, minimizing package substrate costs at the expense of test coverage and reliability margins.
- Chip-on-Carrier:Emerging antenna-in-package and millimeter-wave RF modules employ glass or organic carriers to integrate passive components and antenna elements with active die, addressing 5G FR2 frequency requirements.
Ball grid array anchors high-volume production while chip-on-carrier formats climb fastest as millimeter-wave penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile phone semiconductor trade flows concentrate in export-heavy Asian manufacturing corridors, with import dependency rising in European and North American handset assembly hubs seeking supply chain diversification.
China
Domestic 5G subscriber penetration and MIIT spectrum allocation rules drive baseband chip demand for sub-6GHz and millimeter-wave bands. The country's dual carbon goals enforce renewable power purchase agreements for foundry operations. Yangtze River Delta fabrication clusters anchor advanced logic wafer production for domestic OEMs.
South Korea
Samsung and SK Hynix memory output supplies Korean and Chinese smartphone OEMs with LPDDR5X and UFS 4.0 components. MFDS equipment certification requirements shape RF front-end module validation timelines. Busan-Ulsan corridor memory fabrication facilities expand capacity amid DRAM pricing cyclicality.
United States
FCC RF emission standards govern modem and front-end module certification for North American-bound handsets. IRA clean energy manufacturing credits incentivize domestic semiconductor assembly investments. Texas and Arizona foundry projects attract Qualcomm and Intel mobile chip packaging commitments.
Taiwan
TSMC's N3E and advanced FinFET nodes supply Snapdragon and Dimensity flagship silicon to global OEMs. Export control compliance frameworks restrict EUV scanner maintenance access for China-bound production. Hsinchu Science Park anchors the world's densest advanced logic wafer fabrication cluster.
India
PLI scheme production-linked incentives attract semiconductor assembly and test capacity from Foxconn and Dixon Technologies. BIS certification requirements mandate local safety testing for imported chipsets. Gujarat and Tamil Nadu electronics manufacturing zones concentrate smartphone PCB assembly and chip packaging investments.
Mobile Phone Semiconductor Market Competitive Landscape
On the supply side, the industry is consolidating around platform-level socket awards rather than discrete component sourcing, with direct foundry relationships displacing traditional merchant semiconductor distribution. Three archetypes dominate: integrated fabless designers with captive modem-AP roadmaps, memory specialists with cyclical margin expansion capacity, and analog-mixed signal power management incumbents. Competitive moves center on multi-year OEM bundle negotiations and chiplet-based architecture licensing to compress time-to-market.
Among fabless platform architects, Qualcomm Technologies Inc and MediaTek Inc exemplify the integrated modem-application processor archetype, while Samsung Electronics occupies a hybrid position spanning memory, foundry, and captive handset silicon supply. These three anchors demonstrate how premium-tier socket concentration rewards scale in RF calibration firmware and heterogeneous integration roadmaps.
| Leading Market Players |
|---|
| Broadcom Inc |
| Skyworks Solutions Inc |
| Qualcomm Technologies Inc |
| Micron Technology Inc |
| Qorvo Inc |
| MediaTek Inc |
| NXP Semiconductors N.V. |
| Huawei Technologies Co Ltd |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
EUV lithography equipment access restrictions determine both the premium-to-economy pricing spreads across process nodes and the geographic clustering of foundry investments. Smartphone OEM procurement consolidation into multi-year platform bundles compresses margin negotiation leverage for second-tier suppliers while amplifying volume discounts for flagship-tier allocations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in wafer starts at fixed pricing for 12-18 month windows. Price differentiation stems from FinFET node certification grade and volume scale commitments, with 3nm-class silicon commanding substantial premiums over mature 28nm planar alternatives. Pricing pressure stems from memory cyclicality compressing DRAM and NAND margins that subsidize logic foundry expansion. Mid-range smartphone OEMs exhibit acute price sensitivity, while premium-tier accounts prioritize performance-per-watt over unit economics.
Supply Chain Analysis
Extended payment terms from smartphone OEMs to merchant semiconductor vendors now stretch 90-120 days, forcing suppliers to access supply-chain finance facilities. Geographic supply concentration centers on Taiwan, South Korea, and the United States for advanced logic and memory fabrication. Raw material dependencies draw from high-purity silicon wafers, EUV-grade photoresists, and noble gas feedstocks. Single-source vulnerability permeates sub-5nm foundry capacity where TSMC's N3E process dominates. Distribution runs through direct foundry relationships for tier-one OEMs, with regional distributors serving smaller handset manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analog-mixed signal engineering talent scarcity constrains power management IC supplier expansion, creating acquisition premiums for teams with established voltage regulator architectures. Foundry slot allocation now hinges on demonstrated RF calibration firmware expertise rather than pure digital design scale.
For Market Incumbents: Build captive modem-AP integration moats by securing multi-year socket commitments from top-five smartphone OEMs. Defensive moves should prioritize backward integration into RF front-end module design to offset MediaTek's Dimensity platform encroachment, while adding certified capacity in India under PLI frameworks to diversify tariff exposure. Channel control through direct foundry relationships remains essential against distributor disintermediation. For New Entrants and Emerging Players: Establish a beachhead in automotive edge AI convergence by licensing smartphone-derived NPU architectures for vehicle cockpit systems. The most penetrable white-space sits in India electronics manufacturing zones where assembly and test capacity expansion outpaces domestic chip design expertise. Go-to-market positioning should emphasize chiplet-based heterogeneous integration roadmaps that decouple memory and logic refresh cycles for cost-sensitive OEMs. For Investors and Strategic Acquirers: MIIT 5G spectrum allocation divergence reshapes the acquisition landscape by inflating validation engineering costs for China-bound versus export-oriented modem platforms. Long-term viability favors analog-mixed signal specialists with aging engineer pipelines and defensible multi-rail voltage regulator positions. Watch for EU REACH substance rule enforcement acceleration as the inflection signal triggering lead-free solder and halogen-free laminate substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Architecture Licensing | UCIe standard adoption enables mixing compute tiles from disparate foundries, compressing OEM time-to-market. |
| India PLI Capacity Expansion | Gujarat and Tamil Nadu electronics zones attract Foxconn and Dixon Technologies packaging investments. |
| RF Front-End Modularization | Millimeter-wave antenna-in-package integration demands cross-domain electromagnetic simulation expertise. |
| Renewable Power Purchase Agreements | China dual carbon mandates accelerate foundry energy efficiency investments lowering long-term operating costs. |
| Direct Foundry Relationship Consolidation | Apple, Samsung, and Xiaomi negotiate multi-year application processor and modem bundle commitments displacing distribution. |
Research Methodology
A standing panel of foundry operations executives, smartphone OEM procurement directors, RF calibration firmware engineers, and power management IC design leads provided ongoing calibration across the study period. Primary interview data combined with secondary validation from SEC filings, MIIT equipment certification records, EU REACH substance restriction databases, and customs trade flow statistics. Bottom-up wafer start projections and top-down smartphone shipment estimates were triangulated to anchor volume assumptions.
Scenario-bracketing framed optimistic and conservative demand trajectories across the analysis window without specifying discrete year markers. Segmentation dimensions modeled include process node tier, product category, end-user procurement archetype, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to historical foundry revenue and smartphone bill-of-material data, with memory pricing cyclicality and EUV scanner delivery schedules as key forecast inputs.
Stress conditions across export control enforcement intensity, memory supply-demand imbalances, and analog engineering talent attrition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about 5G subscriber penetration curves and foundry capacity expansion timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
Global Zener Diode Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Global Bipolar Power Transistor Market