
 Digital Tunable Capacitors Market | 2026-2036
Digital Tunable Capacitors Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tunable Capacitors Market Insights
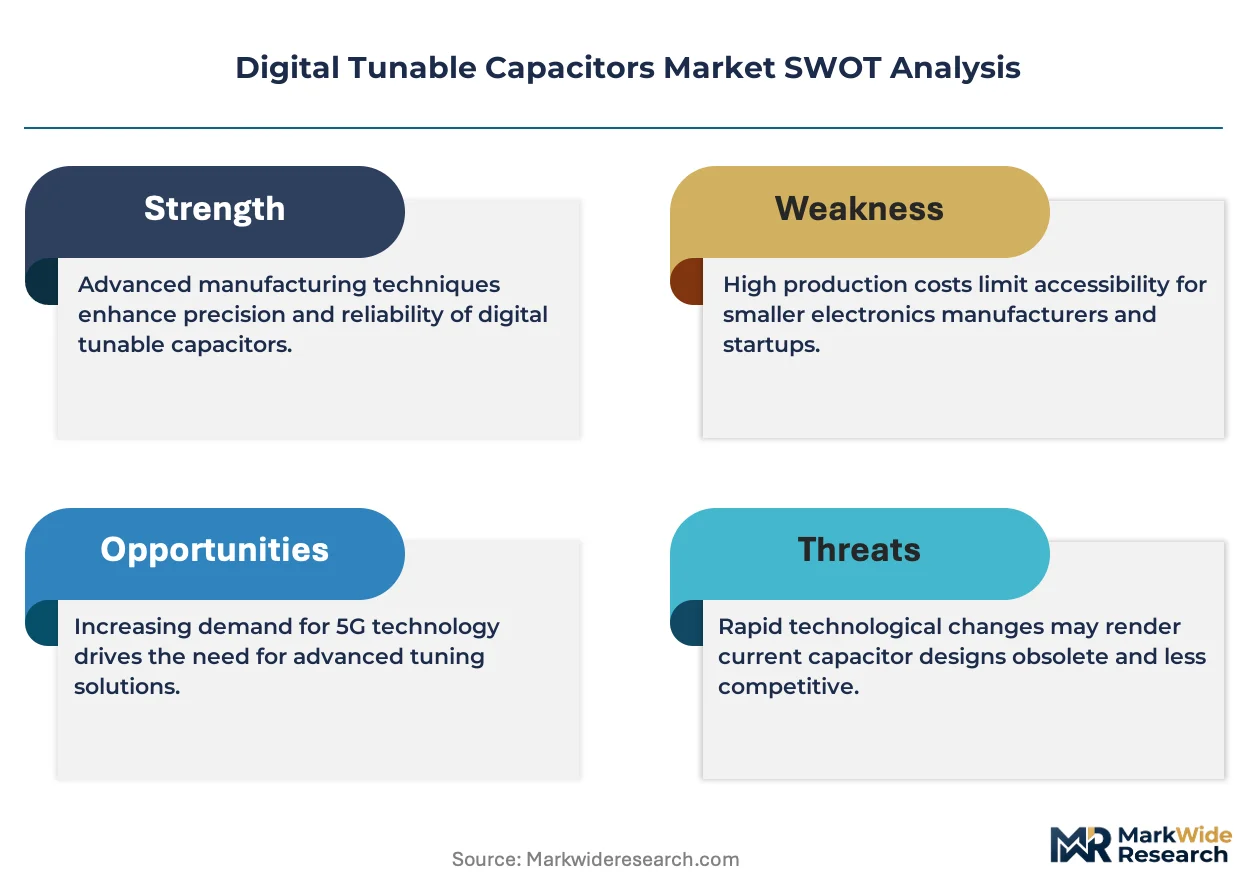
The Digital Tunable Capacitors Market is pivoting between premium MEMS-based solutions for 5G infrastructure and commodity varactor diodes serving legacy RF equipment. Peregrine Semiconductor leverages its SOI process expertise to dominate high-frequency applications. Murata Manufacturing anchors volume production through ceramic integration capabilities. Vishay Intertechnology competes across both tiers with broad catalog depth.
Digital tunable capacitors are voltage-controlled reactive components that adjust capacitance through applied bias signals, typically achieving tuning ratios from 2:1 to 10:1 across picofarad to nanofarad ranges for impedance matching and frequency agility in RF circuits. Their primary purpose is enabling dynamic signal optimization in wireless systems where static components cannot compensate for environmental or operational variation. MEMS capacitors command premium positioning due to superior linearity and Q-factor performance in millimeter-wave bands. RF Applications represents the fastest-expanding demand pool as radar and satellite communications adopt electronically steerable arrays. Software-Controlled technology is displacing analog bias networks in base station designs where remote calibration reduces field maintenance.
FCC Part 15 rules in the United States, ETSI EN 301 standards in Europe, and China's MIIT radio regulations collectively shape emission compliance requirements that dictate capacitor linearity specifications and filter architectures. REACH restrictions on hazardous substances influence electrode metallurgy choices and substrate material selection across manufacturing footprints. Stakeholders must monitor spectrum auction outcomes and corresponding device certification timelines to align R&D roadmaps with commercial deployment windows.
Market Dynamics
5G infrastructure deployment is compressing RF component redesign cycles as carriers race to activate millimeter-wave spectrum blocks, forcing capacitor suppliers to accelerate qualification timelines for antenna-integrated modules.
Growth Catalysts
- FCC spectrum reallocation:The United States regulator's ongoing auction of C-band and 3.45 GHz licenses is mandating rapid retuning of base station equipment, pulling demand for wide-tuning-range capacitors into active deployment phases.
- Electronically steerable arrays:Defense and satellite communications manufacturers are embedding MEMS tunable capacitors into phased-array radar systems to enable real-time beam steering without mechanical rotation.
- Samsung supply chain concentration:South Korea's vertically integrated electronics manufacturing cluster around Seoul is generating concentrated procurement volumes for smartphone antenna tuners.
Market Restraints
- Raw material concentration:High-purity silicon-on-insulator substrates for SOI-based capacitors rely on a limited supplier base concentrated in Taiwan and Japan, exposing buyers to allocation risk during semiconductor demand surges.
- REACH metallurgy constraints:European restrictions on nickel and cadmium in electrode materials are forcing redesigns of legacy varactor products, extending qualification timelines for replacement chemistries.
- Q-factor limitations in varactor diodes:Silicon junction capacitors exhibit insufficient linearity above 6 GHz, blocking their use in emerging 28 GHz and 39 GHz 5G bands where MEMS alternatives dominate.
Strategic Opportunities
- India telecom infrastructure:The country's PLI scheme for telecom equipment manufacturing is attracting capacitor suppliers to establish local assembly operations serving Reliance Jio and Bharti Airtel 5G rollouts.
- Automotive radar integration:Convergence of 77-81 GHz frequency-modulated continuous-wave radar with software-defined vehicle architectures is opening new socket opportunities for temperature-stable tuning elements.
- EU Green Deal compliance:The bloc's circular economy mandates for electronics are creating preference for field-reconfigurable RF components that extend hardware lifecycles through software updates.
Industry Challenges
- Millimeter-wave test infrastructure:Validating capacitor performance at 28 GHz and above requires vector network analyzers and probe stations that few contract manufacturers outside South Korea and the United States currently operate.
- Antenna subsystem integration:Module suppliers must coordinate electrical, thermal, and mechanical interfaces across MEMS foundries, ceramic substrate vendors, and baseband processor teams, compressing design cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tunable Capacitors Market |
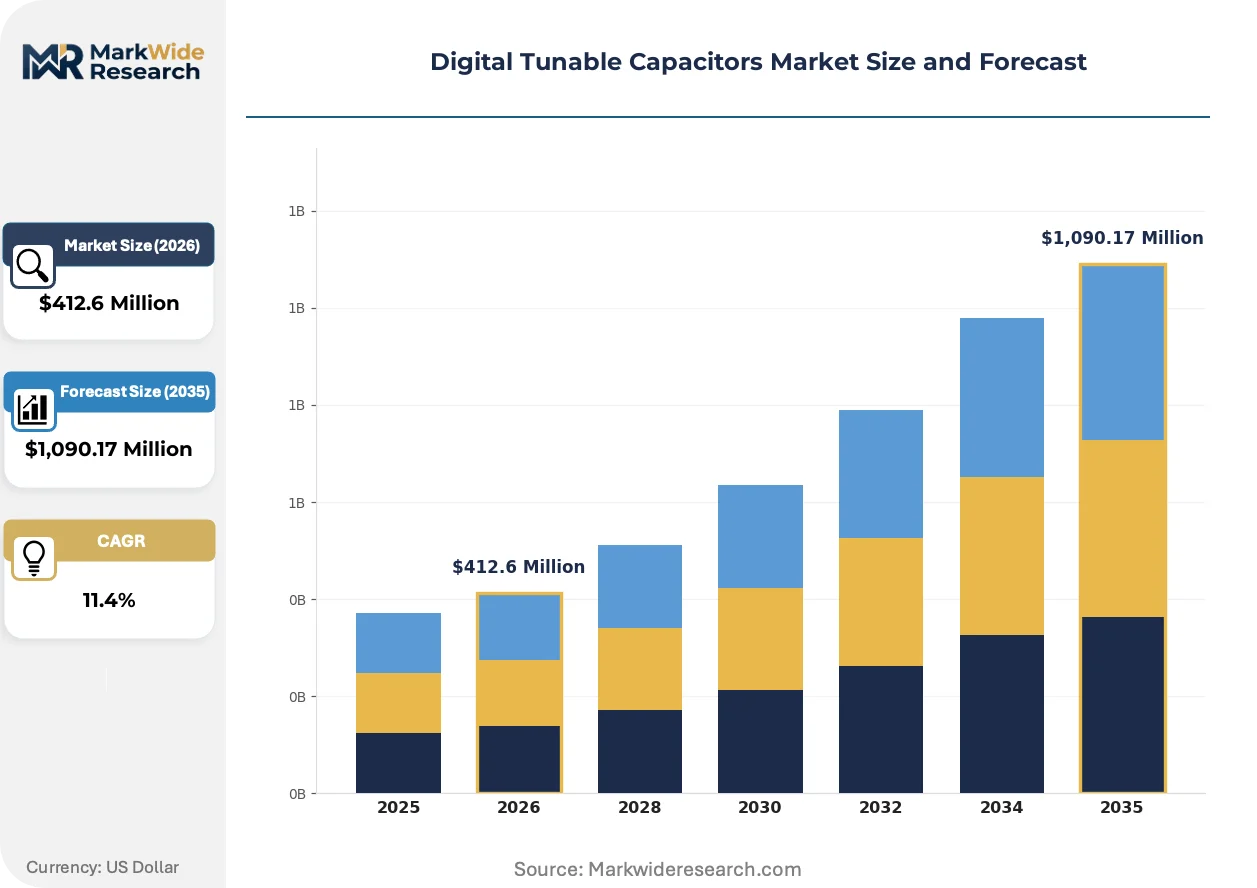
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,090.17 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Varactor Diodes, MEMS Capacitors, Integrated Capacitors, FET Tunable Capacitors Application: Wireless Communication, Signal Processing, RF Applications, Automotive Electronics End User: Telecommunications, Consumer Electronics, Aerospace, Defense Technology: Analog, Digital, Hybrid, Software-Controlled |
| Companies Covered | Peregrine Semiconductor, Murata Manufacturing, Vishay Intertechnology, AVX Corporation, TDK Corporation, Voltronics Corporation, Johanson Manufacturing, Sprague Goodman, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tunable Capacitors Market Trends and Innovations
RF front-end miniaturization is forcing component suppliers to embed intelligence directly into passive elements, eliminating discrete bias networks and enabling remote calibration through digital interfaces.
SOI-based digital tunable capacitors are converging with integrated bias generation and SPI control logic into single-die solutions. Smartphone OEMs are adopting these monolithic components to reduce bill-of-materials count in antenna tuning modules. This integration is compressing the addressable market for standalone controller ICs while elevating capacitor suppliers into subsystem architect roles.
ETSI EN 301 standards in Europe are tightening spurious emission limits for user equipment, forcing capacitor manufacturers to characterize intermodulation distortion across temperature and voltage corners. Filter designers are responding by specifying minimum second-harmonic rejection levels that disqualify conventional varactor diodes from premium handset sockets. German and French certification labs are reporting extended test queues as manufacturers rush to validate redesigned RF chains.
Defense procurement offices are consolidating vendor lists for electronically steerable arrays, awarding multi-year sole-source contracts to capacitor suppliers with proven space-heritage qualifications. This concentration is displacing spot-market purchasing patterns that previously characterized commercial satellite programs. The shift is most visible in United States Department of Defense programs, where Lockheed Martin and Northrop Grumman are locking in MEMS capacitor supply agreements spanning five-year horizons.
Digital Tunable Capacitors Market Segmentation
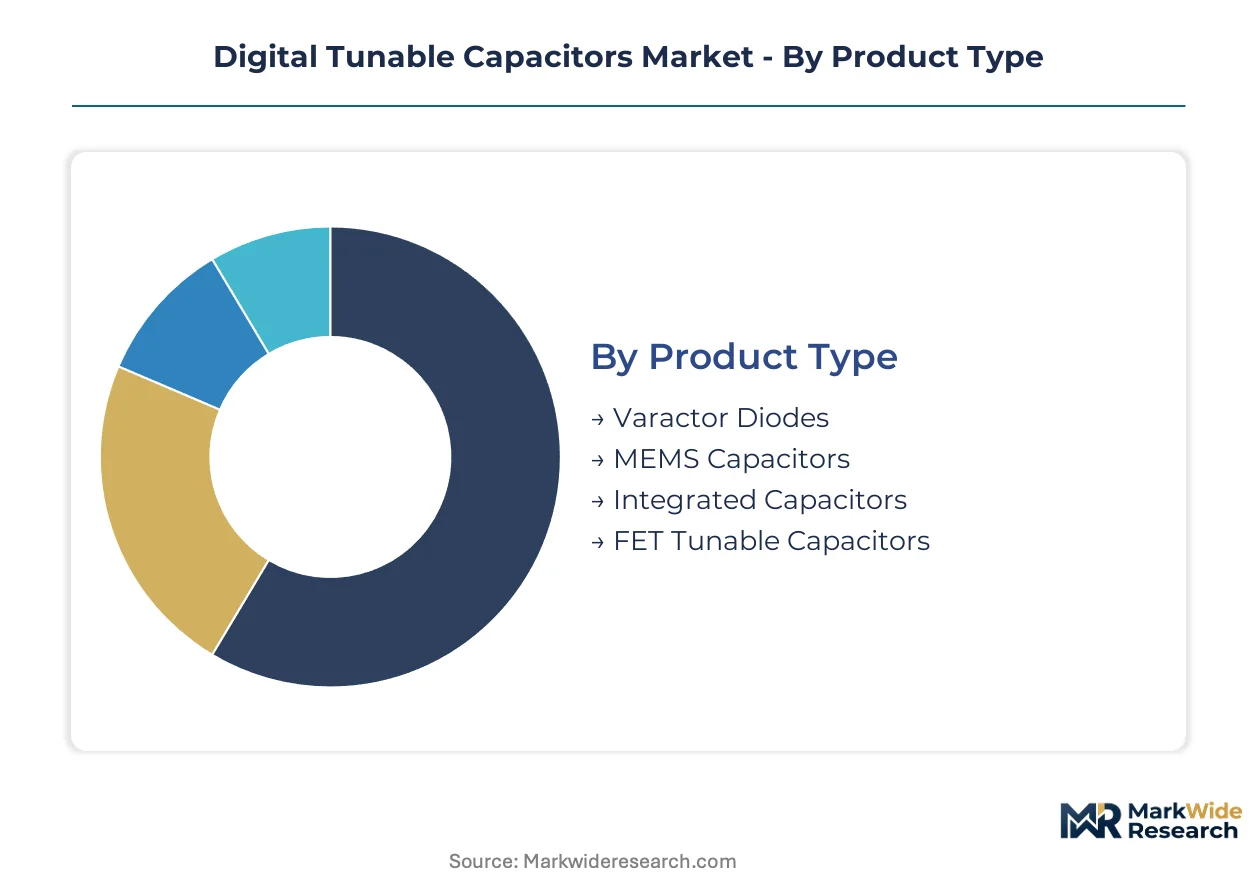
Component selection in tunable capacitors hinges on frequency range, linearity requirements, and integration complexity. Procurement patterns diverge sharply between commodity varactor applications and premium MEMS sockets where qualification cycles extend development timelines.
Product Type:
Supply concentration clusters around MEMS foundries with proven millimeter-wave processes, while varactor production disperses across legacy semiconductor fabs.
- Varactor Diodes:Silicon junction devices achieve capacitance modulation through reverse-bias voltage variation, typically spanning 2:1 to 10:1 tuning ratios. Demand concentrates in legacy cellular infrastructure across India and Southeast Asia where cost sensitivity overrides performance ceilings. REACH metallurgy constraints are forcing electrode material transitions that extend qualification timelines.
- MEMS Capacitors:Electrostatically actuated parallel-plate structures deliver superior Q-factors above 6 GHz with near-zero leakage current. South Korean smartphone manufacturers anchor procurement volumes for 5G antenna tuning modules. FCC spectrum reallocation is compressing redesign cycles for base station applications.
- Integrated Capacitors:Monolithic solutions combine tuning elements with bias generation and control logic on single die.
- FET Tunable Capacitors:MOS varactor structures leverage gate-channel capacitance modulation for moderate-frequency agility.
MEMS Capacitors absorb the bulk of installed capacity; Integrated Capacitors is expanding most quickly.
Application:
Margin profiles stratify across frequency bands, with millimeter-wave sockets commanding premium positioning against sub-6 GHz commodity volumes.
- RF Applications:Radar and satellite communications systems demand phase-coherent tuning across electronically steerable arrays. Defense procurement offices in the United States are consolidating vendor lists around space-heritage qualified suppliers. Multi-year sole-source contracts are displacing spot-market purchasing patterns.
- Wireless Communication:Smartphone antenna tuners require rapid impedance matching across fragmented spectrum allocations. Samsung and SK Hynix supply chains in South Korea generate concentrated component demand. ETSI EN 301 emission standards are tightening linearity specifications that disqualify conventional varactors.
- Signal Processing:Filter banks and matching networks in test equipment leverage voltage-tuned reconfigurability.
- Automotive Electronics:77-81 GHz radar modules require temperature-stable capacitance characteristics across operational extremes.
Wireless Communication commands the dominant revenue share; RF Applications shows the steepest expansion trajectory.
End User:
Customer concentration varies by certification burden, with aerospace and defense programs demanding multi-year qualification investments that lock out new entrants.
- Telecommunications:Base station OEMs and network equipment vendors drive volume procurement for 5G infrastructure deployment. India's PLI scheme for telecom manufacturing is attracting local assembly operations serving Reliance Jio and Bharti Airtel rollouts. TRAI spectrum auction timelines dictate component procurement cadences.
- Consumer Electronics:Smartphone and tablet manufacturers prioritize bill-of-materials reduction through antenna-integrated modules. South Korean manufacturing clusters around Seoul concentrate demand for compact tuning solutions. Software-defined calibration is displacing analog bias networks to reduce field maintenance.
- Aerospace:Satellite payload manufacturers require radiation-hardened components with proven orbital heritage.
- Defense:Phased-array radar programs demand high-reliability MEMS capacitors with military-grade qualification trails.
Telecommunications absorbs the bulk of installed capacity; Consumer Electronics is climbing the fastest.
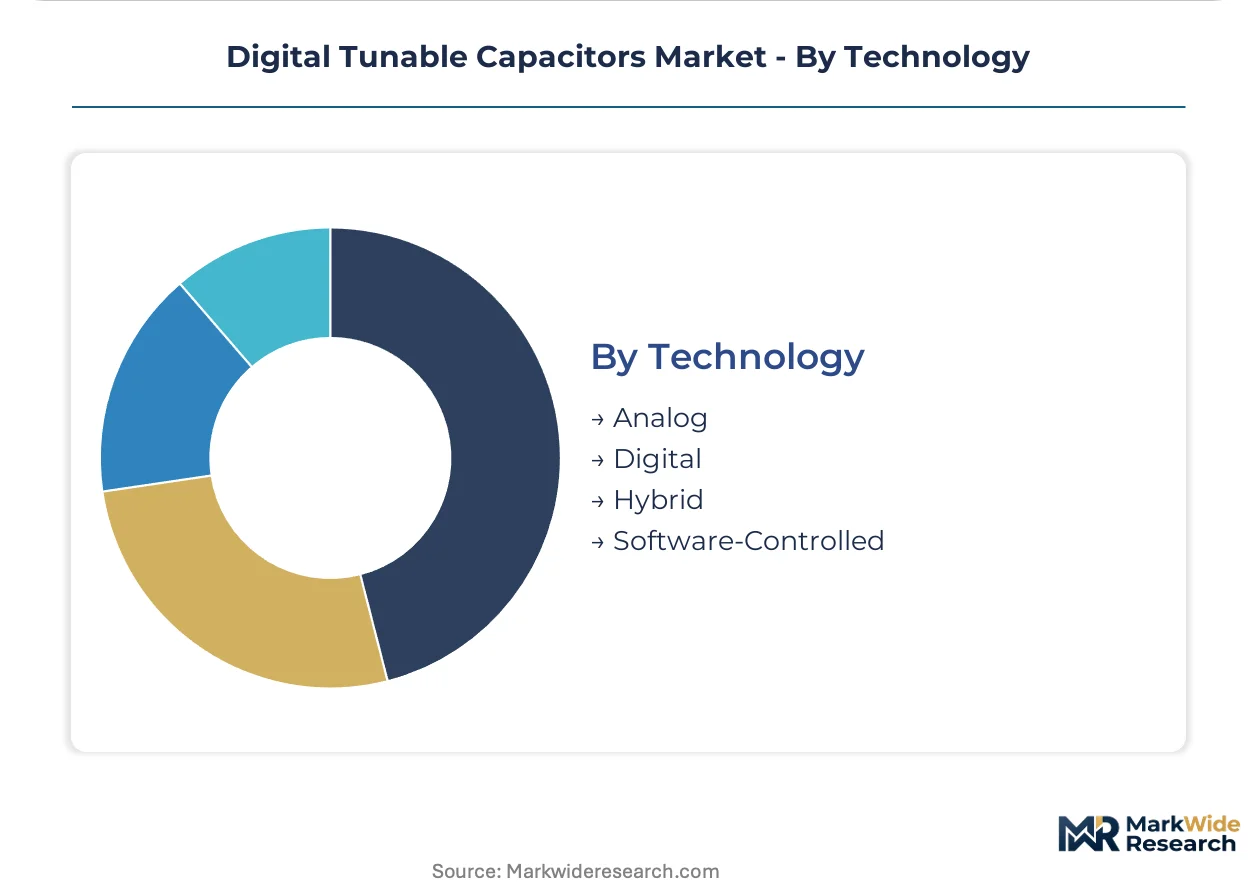
Technology:
Control architecture selection determines subsystem integration depth, with digital interfaces enabling remote calibration that reduces field service requirements.
- Software-Controlled:SPI and I2C interfaces enable remote parameter adjustment through baseband processor coordination. Base station designers across the United States and Europe are adopting these architectures to minimize tower climbs for maintenance. FCC Part 15 compliance testing now includes software-configured emission verification.
- Digital:Discrete logic-level control signals switch capacitor banks through decoder circuits with deterministic settling times.
- Analog:Continuous voltage bias networks dominate legacy equipment where processor integration is cost-prohibitive.
- Hybrid:Mixed-signal approaches combine analog tuning cores with digital coarse selection for wide-range agility.
Software-Controlled captures the dominant deployment share; Digital is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the most concentrated demand cluster for digital tunable capacitors, with Samsung and SK Hynix procurement networks generating procurement volumes that outpace individual European countries. Manufacturing gravity across this market splits between East Asian foundry capacity and North American defense qualification infrastructure.
United States
FCC spectrum reallocation in C-band and 3.45 GHz blocks is compressing RF component redesign cycles for base station OEMs. The Department of Defense is consolidating vendor lists around space-heritage qualified suppliers for phased-array radar programs. Boston-area RF design houses coordinate with West Coast MEMS foundries to accelerate antenna-integrated module qualification.
South Korea
Samsung Electronics and SK Hynix supply chains are driving concentrated procurement for smartphone antenna tuners. The national radio research agency certifies millimeter-wave components under local emission standards that exceed baseline international requirements. Seoul-Incheon manufacturing corridors host vertically integrated assembly operations serving 5G infrastructure export markets.
Germany
ETSI EN 301 standards are tightening spurious emission limits that disqualify conventional varactor diodes from premium handset sockets. The KBA and federal network agency coordinate type approval timelines for automotive radar integration. Bavarian automotive suppliers are qualifying temperature-stable tuning elements for 77-81 GHz frequency-modulated continuous-wave modules.
Japan
METI industrial policy supports domestic SOI process development for high-frequency capacitor applications. JIS standards govern reliability testing protocols that extend qualification timelines for space-rated components. Tokyo-Osaka industrial corridors maintain captive supply relationships with Taiwan substrate vendors to mitigate allocation risk.
India
TRAI spectrum auction timelines dictate component procurement cadences for Reliance Jio and Bharti Airtel 5G rollouts. The PLI scheme for telecom equipment manufacturing is attracting capacitor suppliers to establish local assembly operations. Maharashtra and Karnataka industrial zones are emerging as preferred locations for RF component testing and packaging facilities.
Digital Tunable Capacitors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct technology tiers in this market. Foundry-based MEMS manufacturers maintain process expertise barriers in millimeter-wave segments, while fabless specialists leverage SOI design libraries for rapid customer integration. Three archetypes dominate: vertically integrated ceramic substrate houses, SOI process specialists with defense heritage, and broad-catalog semiconductor distributors spanning both premium and commodity sockets. Competitive intensity centers on qualification timeline compression and antenna subsystem integration depth rather than unit cost alone.
Within the SOI process specialist tier, Peregrine Semiconductor exemplifies the defense-heritage qualification pathway that locks in multi-year supply agreements. Murata Manufacturing anchors the volume-production archetype through ceramic integration capabilities that serve consumer electronics procurement clusters. Vishay Intertechnology occupies a position spanning both premium MEMS and commodity varactor sockets through catalog breadth.
| Leading Market Players |
|---|
| Peregrine Semiconductor |
| Murata Manufacturing |
| Vishay Intertechnology |
| AVX Corporation |
| TDK Corporation |
| Voltronics Corporation |
| Johanson Manufacturing |
| Sprague Goodman |
| STMicroelectronics |
| Others |
Pricing and Supply Chain Analysis
High-purity silicon-on-insulator wafer pricing indices cascade through MEMS capacitor manufacturing, compressing margins for fabless designers while amplifying pricing power for vertically integrated foundries serving defense and smartphone OEMs. This raw-material cost pressure stratifies the market into three tiers: premium MEMS sockets anchored by South Korean procurement, standard SOI-based components for base station infrastructure, and economy varactor diodes for legacy cellular equipment.
Pricing Analysis
Yield-optimized unit economics anchor pricing for millimeter-wave MEMS capacitors, with Q-factor performance thresholds commanding substantial premiums over sub-6 GHz alternatives. Price differentiation separates radiation-hardened space-grade components from commercial smartphone tuners and commodity varactor diodes for Indian infrastructure. Cost compression in the varactor segment is intensifying because REACH-compliant electrode metallurgy extends qualification timelines and raises unit costs. Smartphone OEMs exhibit the least price sensitivity, prioritizing antenna-integrated module performance over component-level savings, while Indian telecom equipment vendors remain highly cost-conscious in base station procurement.
Supply Chain Analysis
Air freight premiums for SOI wafer shipments from Japan and Taiwan to South Korean assembly plants have compressed logistics budgets across capacitor suppliers. Manufacturing concentrates in Taiwan, South Korea, and Japan, with substrate fabrication feeding MEMS foundries in Seoul-Incheon corridors and Boston-area RF design houses. Raw material dependencies include high-purity silicon-on-insulator wafers, ceramic substrate materials, and precious-metal electrode chemistries. Single-source vulnerability in Taiwan's SOI substrate supply exposes buyers to allocation risk during semiconductor demand surges. Distribution runs through direct OEM contracts for premium MEMS sockets and authorized distributors for commodity varactor volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under acute SOI wafer supply constraints, with limited qualified substrate vendors propping pricing power for integrated foundry operators. Foundry capacity bottlenecks in millimeter-wave MEMS processes sustain margin premiums that commodity varactor manufacturers cannot replicate.
For Market Incumbents: To counter fabless competitors exploiting SOI design libraries, Peregrine Semiconductor and Murata Manufacturing should deepen captive supply relationships with Taiwan substrate vendors and accelerate qualification timelines for antenna-integrated modules. Defense-heritage suppliers must lock in multi-year sole-source agreements with Lockheed Martin and Northrop Grumman before procurement offices consolidate vendor lists further. For New Entrants and Emerging Players: Begin with India's PLI-subsidized telecom manufacturing zones, where Reliance Jio and Bharti Airtel 5G rollouts generate unmet demand for cost-optimized varactor alternatives. Target automotive radar integration in Germany's Bavarian supplier corridor, where temperature-stable tuning elements for 77-81 GHz modules face limited qualified competition. A licensing partnership with established MEMS foundries offers the fastest path to market without capital-intensive process development. For Investors and Strategic Acquirers: Distressed-cycle entries favor SOI process specialists with defense qualification trails in the United States, where multi-year procurement agreements provide revenue visibility through demand fluctuations. Long-term viability hinges on millimeter-wave test infrastructure ownership and antenna subsystem integration capabilities. Watch FCC spectrum auction outcomes as the critical inflection signal—accelerated C-band deployment would pull forward capacitor demand into active procurement phases.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Qualifies suppliers for Samsung's 5G antenna tuner procurement programs. |
| SOI Substrate Supply Agreement | Locks in wafer allocation from Taiwan vendors during semiconductor demand surges. |
| Defense Qualification Investment | Opens sole-source contract pathways with United States Department of Defense programs. |
| India PLI Manufacturing Localization | Positions suppliers for Reliance Jio and Bharti Airtel 5G infrastructure tenders. |
| Automotive Radar Certification | Qualifies temperature-stable capacitors for German OEM 77-81 GHz module integration. |
Research Methodology
Multi-period observation of FCC spectrum auction timelines, TRAI procurement cadences, and ETSI certification queues anchored the trend analysis, supplemented by interviews with RF component procurement managers at smartphone OEMs, base station equipment vendors, MEMS foundry process engineers, and defense program qualification officers. Secondary validation drew from FCC Part 15 filings, ETSI EN 301 test reports, METI industrial policy disclosures, and SEC 10-K supply chain disclosures from capacitor manufacturers. Bottom-up unit shipment estimates across varactor, MEMS, and integrated capacitor categories triangulated against top-down RF front-end market sizing.
Input-output matrices modeled demand drivers including 5G infrastructure deployment rates, electronically steerable array procurement cycles, and automotive radar integration timelines across the projection horizon. Segmentation dimensions included product architecture, frequency band application, end-user certification burden, and control interface technology. CAGRs derived from regression analysis of historical qualification-to-volume lag patterns and foundry capacity expansion schedules. Industry-specific forecast inputs incorporated SOI wafer pricing volatility and REACH metallurgy compliance transition timelines.
Underlying measurement precision varies by segment; MEMS capacitor forecasts carry tighter precision than varactor diode projections due to concentrated procurement visibility through Samsung and SK Hynix supply chains. Forecasts reflect documented assumptions regarding spectrum allocation timelines, foundry yield maturation curves, and regulatory compliance transition schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market