
 Field Effect General Purpose Transistors Market | 2026-2036
Field Effect General Purpose Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Field Effect General Purpose Transistors Market Foresight
The capability gap between foundry-dependent and vertically integrated transistor suppliers is collapsing. Taiwan Semiconductor Manufacturing Company leverages captive wafer capacity to dominate advanced MOSFET fabrication. Infineon Technologies anchors European automotive qualification pathways with in-house silicon and packaging control. Texas Instruments sustains broad catalog breadth across analog and mixed-signal JFET portfolios.
Field effect general purpose transistors are three-terminal semiconductor devices where channel conductivity modulates via an electric field applied to a gate terminal, typically fabricated on silicon or silicon carbide substrates with oxide or Schottky barrier isolation. They serve as fundamental building blocks for signal amplification, switching, and power management across electronic systems. MOSFET variants occupy the largest volume tier due to their scalability from milliwatt logic to megawatt power conversion. HEMT segments command premium positioning in RF telecommunications infrastructure where gallium nitride delivers superior electron mobility. Mixed-signal integration represents the fastest-growing technology dimension as system-on-chip designs merge analog sensing with digital control.
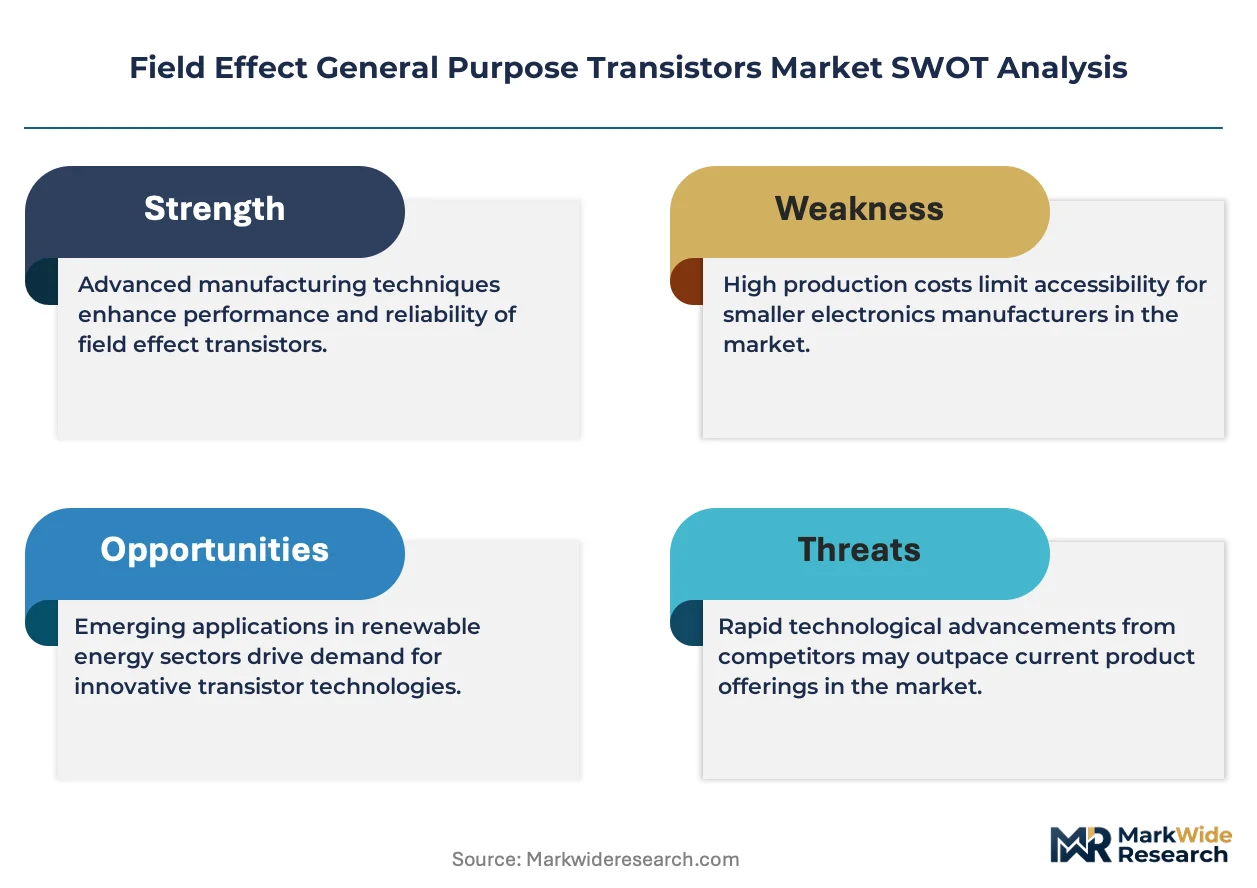
EPA efficiency standards and EU RoHS substance restrictions constrain material choices and mandate minimum switching performance thresholds for power electronics sold in regulated jurisdictions. Japan's METI guides domestic manufacturers toward JIS-certified reliability benchmarks that shape export qualification requirements. China's NMPA and GB standards enforce local testing protocols that gate market access for imported discrete components. Stakeholders must monitor evolving substrate material transitions from silicon to wide-bandgap compounds and assess qualification timeline exposure against customer certification windows.
Market Dynamics
Silicon carbide substrate transitions are compressing qualification timelines as automotive OEMs demand higher switching efficiency from power MOSFET suppliers.
Growth Catalysts
- EU F-Gas Regulation:Stricter efficiency mandates accelerate replacement of legacy switching components with advanced power MOSFETs in industrial refrigeration and HVAC systems.
- Automotive electrification:Electric drivetrain architectures consume three to five times more power transistors per vehicle than internal combustion platforms.
- East Asian manufacturing clusters:Taiwan and South Korea concentrate advanced foundry capacity that feeds downstream packaging and test facilities.
Market Restraints
- Silicon carbide wafer costs:Substrate prices remain four to eight times higher than equivalent silicon, compressing gross margins at module manufacturers.
- Taiwanese foundry concentration:Over 60% of advanced MOSFET fabrication capacity sits within earthquake and geopolitical exposure zones.
- Wide-bandgap material limitations:Gallium nitride HEMT devices face gate-oxide reliability challenges that restrict deployment in automotive safety-critical circuits.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor assembly and test attract MOSFET packaging investments outside traditional East Asian hubs.
- GaN-on-silicon convergence:Integration of gallium nitride epitaxy with standard silicon substrates enables cost-competitive RF power amplifiers for 5G infrastructure.
- Direct procurement from foundries:Power module manufacturers bypass traditional distributors to secure wafer supply through long-term capacity reservations.
Industry Challenges
- AEC-Q101 certification timelines:Automotive qualification cycles extend 18 to 24 months, misaligning with customer platform development windows.
- Compound semiconductor process engineering:Shortage of experienced technicians for SiC and GaN device fabrication constrains capacity expansion at IDM facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Effect General Purpose Transistors Market |
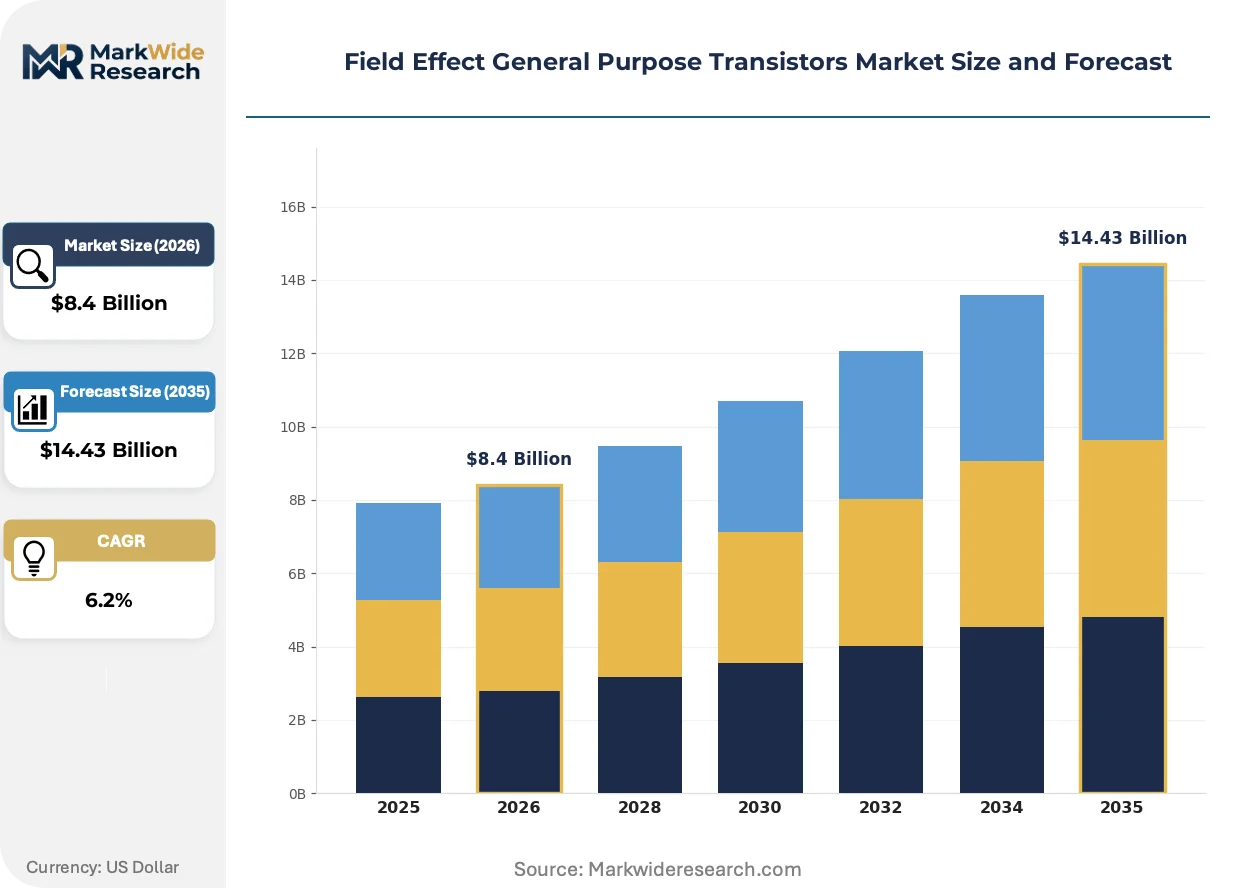
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JFET, MOSFET, MESFET, HEMT Technology: Analog, Digital, Mixed-Signal, Integrated Circuit End User: Telecommunications, Consumer Electronics, Automotive, Industrial Automation Application: Signal Amplification, Switching, Voltage Regulation, Power Management |
| Companies Covered | Taiwan Semiconductor Manufacturing Company, Texas Instruments, Nexperia, Toshiba, NXP Semiconductors, Infineon Technologies, STMicroelectronics, Alpha and Omega Semiconductor, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Effect General Purpose Transistors Market Shifts & Advancements
Substrate material transitions and packaging integration are collapsing traditional boundaries between discrete and modular power solutions.
Silicon carbide MOSFET technology enables megawatt-scale power conversion with switching losses below 10% of equivalent silicon IGBTs. Renewable energy inverter manufacturers and electric vehicle drivetrain suppliers are adopting SiC at the fastest clip. The technology is decomposing the historical voltage-current segmentation that separated discrete transistor markets from integrated power module categories.
China's dual carbon goals and NMPA efficiency certifications are forcing domestic manufacturers toward wide-bandgap material adoption ahead of international competitors. The policy framework creates preferential procurement pathways for locally tested components. Domestic EV battery management systems and charging infrastructure represent the most affected product categories, with tier-one suppliers accelerating in-house SiC device development.
System architects now specify transistor-plus-driver integrated solutions rather than sourcing discrete components separately. This specification pattern displaces traditional catalog distributors with direct semiconductor manufacturer relationships. The shift is most visible in industrial motor drive and solar inverter segments across Germany, Japan, and the United States.
Field Effect General Purpose Transistors Market Segmentation
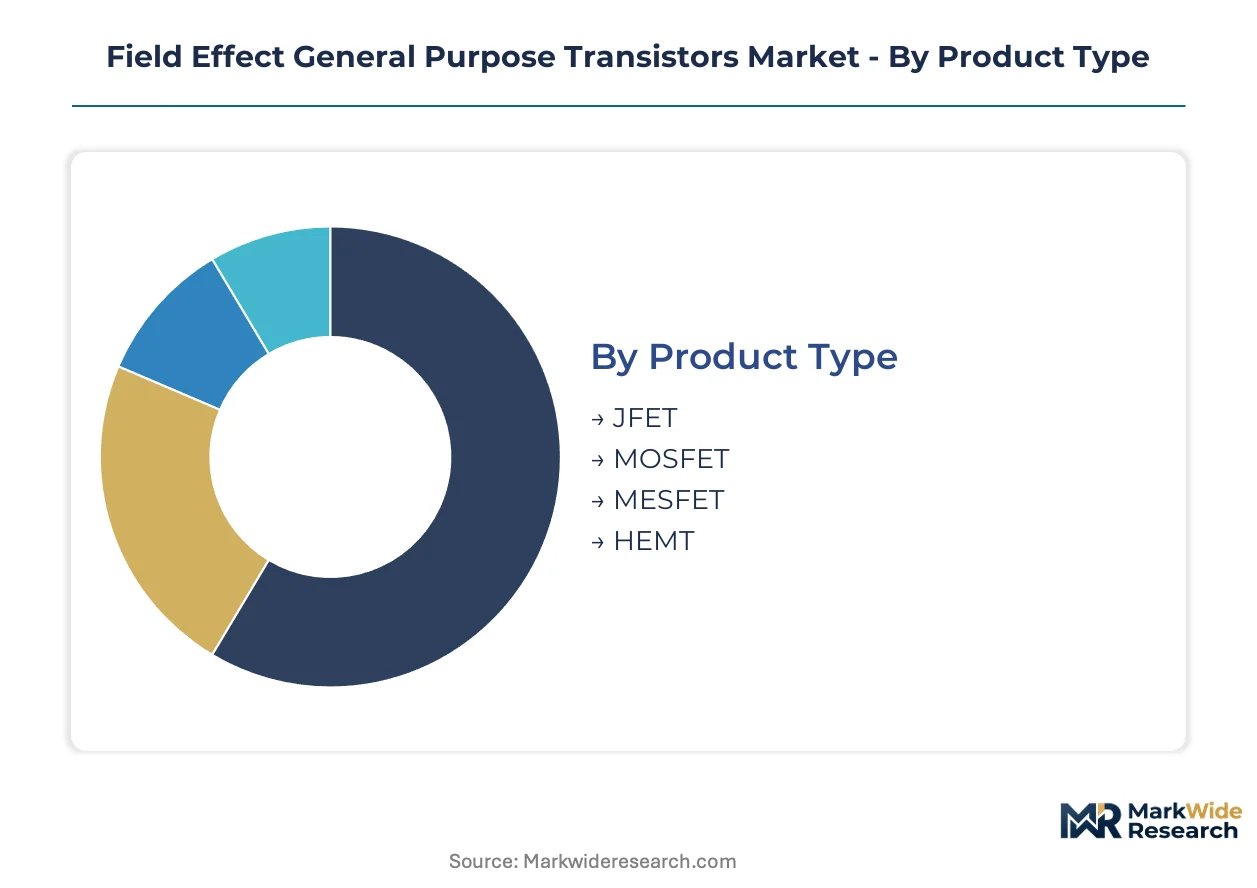
Segmentation in field effect transistors exposes where technology transitions concentrate value capture. Product architecture, integration depth, and end-use qualification requirements create divergent margin structures across the supply base.
Product Type:
Margin pools concentrate in wide-bandgap and high-frequency variants where substrate costs and process complexity erect barriers to entry.
- MOSFET:Metal-oxide-semiconductor field effect transistors dominate volume tiers through scalability from sub-milliwatt logic to megawatt power conversion. Automotive electrification in Germany and China's EV charging infrastructure are concentrating demand for silicon carbide MOSFETs that cut switching losses below silicon IGBT equivalents.
- HEMT:High-electron-mobility transistors leverage gallium nitride heterostructures to deliver electron velocities unmatched by silicon. 5G base station deployments in South Korea and Japan's NTT Docomo network expansions are absorbing GaN HEMT output for millimeter-wave power amplification.
- JFET:Junction field effect transistors maintain niche positioning in high-impedance analog front-ends where gate current must approach zero. Texas Instruments and Analog Devices anchor catalog supply for precision instrumentation.
- MESFET:Metal-semiconductor field effect transistors persist in legacy microwave applications and specialized military communications where established qualification pathways resist technology migration.
MOSFET holds installed capacity. HEMT is rotating up the share rankings.
Technology:
Integration depth determines whether transistor suppliers capture system-level value or remain component vendors.
- Mixed-Signal:Devices merging analog sensing with digital control are climbing the fastest as system-on-chip architectures displace discrete component sourcing. Automotive battery management systems in China's BYD and CATL supply chains require precision analog-to-digital conversion alongside power switching.
- Integrated Circuit:Monolithic integration of multiple transistor functions with passive elements serves space-constrained consumer electronics. Apple's supplier Foxconn and Samsung's device divisions specify IC-level power management for smartphone and tablet platforms.
- Analog:Discrete transistor implementations persist in industrial motor drives and renewable energy inverters where discrete failure modes simplify maintenance and replacement.
- Digital:Logic-optimized transistors for computing applications face margin compression from foundry commoditization at advanced nodes.
Analog retains the largest revenue base. Mixed-Signal is displacing discrete sourcing in new designs.
End User:
Qualification intensity and volume scale create divergent customer economics across application verticals.
- Automotive:AEC-Q101 certification and functional safety requirements extend sales cycles to 18-24 months but lock in multi-year supply agreements. Volkswagen's ID platform and Tesla's Fremont and Shanghai facilities consume power MOSFETs at three to five times the per-vehicle rate of combustion architectures.
- Industrial Automation:Siemens, ABB, and Schneider Electric specify transistor-plus-driver integrated solutions for motor control, collapsing traditional distributor relationships.
- Telecommunications:Huawei, Ericsson, and Nokia base station programs drive RF transistor demand with emphasis on thermal performance and linearity specifications.
- Consumer Electronics:High volume and short product lifecycles prioritize cost optimization over performance margins, pressuring supplier returns.
Automotive commands premium pricing tiers. Industrial Automation is consolidating procurement around integrated solutions.
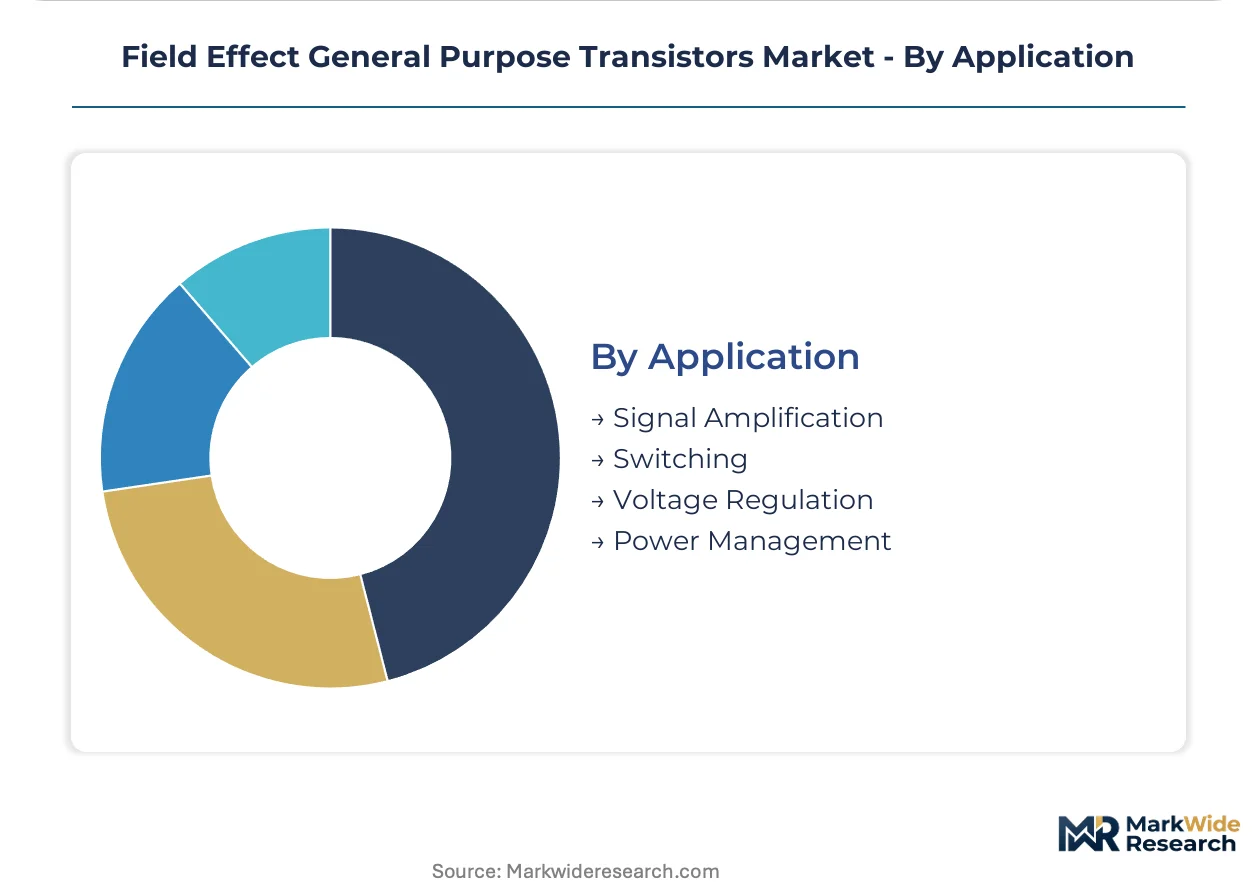
Application:
Functional specification determines whether transistors compete on switching speed, conduction efficiency, or linearity metrics.
- Power Management:DC-DC conversion and battery charging circuits in electric vehicles and portable electronics absorb the largest transistor volumes. Infineon's Munich facilities and STMicroelectronics' Grenoble operations anchor European supply for automotive power stages.
- Switching:Hard-switched power conversion in solar inverters and industrial drives demands low on-resistance and fast transition times where silicon carbide delivers measurable efficiency gains.
- Signal Amplification:RF front-ends for 5G and satellite communications require linear operation across wide bandwidths, favoring GaN HEMT and LDMOS technologies.
- Voltage Regulation:Low-dropout regulators and precision references serve analog power supply segments with emphasis on noise performance and thermal stability.
Power Management retains the deepest revenue base. Switching is gaining share through wide-bandgap material transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate pricing in Germany commands 40% premiums over equivalent Taiwanese foundry output, yet automotive qualification pathways in Stuttgart anchor European supply security. This asymmetry shapes where power MOSFET margins pool across the forecast horizon.
China
BYD and CATL battery management systems absorb silicon carbide MOSFETs at accelerating rates for domestic EV platforms. NMPA efficiency certifications and dual carbon goals enforce local testing protocols that gate market access for imported discrete components. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate advanced packaging and test facilities serving renewable energy inverter demand.
Germany
Volkswagen ID platform and Siemens industrial motor drives specify transistor-plus-driver integrated solutions that collapse traditional distributor relationships. EU F-Gas Regulation mandates stricter efficiency thresholds for industrial refrigeration and HVAC switching components. Infineon's Munich operations anchor European automotive qualification pathways with captive silicon and packaging control.
United States
Tesla's Fremont and Austin facilities consume power MOSFETs at three to five times the per-vehicle rate of combustion architectures. EPA efficiency standards constrain material choices and mandate minimum switching performance thresholds for power electronics sold in regulated jurisdictions. Texas Instruments sustains broad catalog breadth across analog and mixed-signal JFET portfolios from Dallas-area operations.
South Korea
Samsung's device divisions and Hyundai-Kia electric drivetrain programs drive RF transistor demand with emphasis on thermal performance specifications. 5G base station deployments by NTT Docomo network partners absorb gallium nitride HEMT output for millimeter-wave power amplification. Seoul Capital Area foundry clusters feed downstream packaging facilities with advanced MOSFET wafer capacity.
Japan
Toshiba and Renesas anchor domestic supply for precision instrumentation and automotive safety-critical circuits where gate-oxide reliability requirements restrict gallium nitride deployment. METI guides domestic manufacturers toward JIS-certified reliability benchmarks that shape export qualification requirements. Kansai region operations in Osaka and Kyoto concentrate legacy microwave and specialized military communications MESFET production.
Field Effect General Purpose Transistors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the field effect transistor supply base. Foundry-dependent specialists compete on volume scale and catalog breadth while vertically integrated IDMs capture premium tiers through automotive qualification control and substrate material transitions. Three archetypes dominate: captive foundry operators with wafer capacity leverage, European automotive-qualified IDMs with in-house silicon control, and broad-line analog specialists with mixed-signal integration depth. Competitive moves concentrate on long-term capacity reservations at Taiwanese foundries and backward integration into silicon carbide substrate supply.
Among Asia-Pacific foundry operators, Taiwan Semiconductor Manufacturing Company exemplifies the captive capacity archetype that dominates advanced MOSFET fabrication. Infineon Technologies and Texas Instruments occupy positions on the premium-tier vector, with the former representing European automotive qualification dominance and the latter anchoring broad catalog supply for precision analog applications. These three entities illustrate how geographic and structural positioning shapes competitive access to margin pools across automotive, industrial, and consumer verticals.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company |
| Texas Instruments |
| Nexperia |
| Toshiba |
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| Alpha and Omega Semiconductor |
| Vishay Intertechnology |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate substitution for silicon is redrawing procurement geography while inflating input costs for power module manufacturers. Taiwan Semiconductor Manufacturing Company and South Korean foundries capture margin from this material transition as automotive OEMs absorb four-to-eight-fold wafer premiums for efficiency gains.
Pricing Analysis
Configured-to-order silicon carbide MOSFETs command substantial premiums over standard silicon catalog parts, with automotive AEC-Q101 certification tiers adding further price stratification. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-economy levels separates margin pools, with certification investment and volume scale as primary differentiation drivers. Pricing pressure stems from silicon carbide substrate scarcity as Wolfspeed and Coherent constrain boule supply. Automotive OEMs show lowest price sensitivity given platform lock-in, while consumer electronics buyers drive hardest bargain.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates risk for over sixty percent of advanced MOSFET fabrication capacity housed in Hsinchu and Tainan Science Parks. Raw material flows draw from Japanese silicon wafer suppliers, German epitaxy equipment makers, and Chinese rare earth processors. Single-source dependency on Taiwanese foundry output for automotive-grade devices exposes tier-one module manufacturers to geopolitical disruption. Distribution runs through authorized distributors for catalog parts, while automotive and industrial segments increasingly favor direct foundry relationships with long-term capacity reservations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound semiconductor process engineering expertise has become the binding constraint as silicon carbide and gallium nitride transitions accelerate faster than technician training pipelines can replenish. Foundries and IDMs compete for finite talent pools while automotive qualification windows compress.
For Market Incumbents: Shield automotive qualification pathways by accelerating in-house silicon carbide substrate production before Wolfspeed and Coherent consolidate boule supply. Expand captive packaging capacity in Germany and the United States to offset Taiwanese foundry concentration risk. Lock multi-year wafer supply agreements with TSMC and Samsung Foundry before capacity reservations close to new entrants. For New Entrants and Emerging Players: Lead with GaN-on-silicon RF power amplifiers for 5G infrastructure where gallium nitride HEMT demand outruns incumbent capacity. India's PLI scheme for semiconductor assembly and test offers the most penetrable geographic entry point outside East Asian manufacturing clusters. Pursue direct procurement relationships with renewable energy inverter manufacturers seeking second-source qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed analog specialists possessing catalog breadth but lacking wide-bandgap material roadmaps. Five-to-ten-year viability hinges on successful substrate transition execution rather than legacy silicon market share. Watch Infineon's Munich silicon carbide expansion pace as the inflection signal for European automotive supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive boule production at Wolfspeed's Mohawk Valley facility reduces dependency on Japanese wafer imports. |
| Automotive AEC-Q101 Certification Acceleration | Compressed eighteen-month qualification cycles at Infineon align with Volkswagen ID platform development windows. |
| GaN-on-Silicon Epitaxy Partnership | Integration with standard silicon substrates enables cost-competitive RF amplifiers for Samsung 5G base station programs. |
| India PLI Scheme Manufacturing Entry | Assembly and test investments in Gujarat and Karnataka diversify packaging footprint beyond Taiwan earthquake zones. |
| Direct Foundry Capacity Reservation | Long-term wafer commitments with TSMC bypass distributor markups for power module manufacturers serving Tesla. |
Research Methodology
Operator-level perspectives from foundry process engineers, automotive tier-one procurement directors, power module design architects, and wide-bandgap materials scientists anchored the qualitative base. Primary fieldwork combined with secondary validation against SEC 10-K filings, SEMI equipment shipment data, and customs import records for silicon carbide substrates. Bottom-up transistor shipment modeling triangulated against top-down power electronics system demand across the analysis window.
Sensitivity analysis tested forecast robustness against silicon carbide substrate price trajectories and Taiwanese foundry utilization rates. Segmentation dimensions included product architecture, integration depth, end-use qualification intensity, and regional manufacturing cluster. CAGRs derived from volume-weighted average of segment growth rates applied to base year estimates. Forecast inputs incorporated EV drivetrain transistor content per vehicle and renewable energy inverter deployment pipelines.
Forecasts assume regulatory continuity in EU F-Gas efficiency mandates, EPA automotive emissions standards, and China's NMPA certification protocols; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as geopolitical stability in Taiwan Strait shipping lanes and silicon carbide substrate supply expansion timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market