
 Automotive Memory Market | 2026-2036
Automotive Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Memory Market Intelligence
Advanced Driver Assistance Systems is broadening its share of automotive memory consumption as Level-2-plus autonomy becomes standard in mid-range vehicle platforms. Samsung Electronics dominates high-bandwidth memory supply for camera fusion modules. SK Hynix leverages its DRAM process leadership to anchor contracts with German premium OEMs. Micron Technology specializes in automotive-grade NAND Flash with extended temperature tolerance for powertrain control.
Automotive memory encompasses volatile and non-volatile semiconductor storage engineered for operation across temperature extremes, with AEC-Q100 qualification and ISO 26262 functional safety compliance as baseline requirements. Flash Memory commands the largest volume position due to code storage demands in engine control and telematics units, while GDDR6 represents the fastest-expanding technology segment as sensor resolution and neural network inference throughput requirements multiply. EEPROM retains a stable margin pool in safety-critical parameter storage despite lower bit volumes.
FDA oversight of automotive health-monitoring subsystems, EPA emissions data logging mandates, and NHTSA crash-event recorder regulations collectively tighten memory retention and integrity specifications. The EU AI Act and CE marking requirements for autonomous decision systems impose additional traceability standards on memory components. Stakeholders must monitor how functional safety tiering and data sovereignty rules reshape qualification costs and supplier eligibility across target markets.
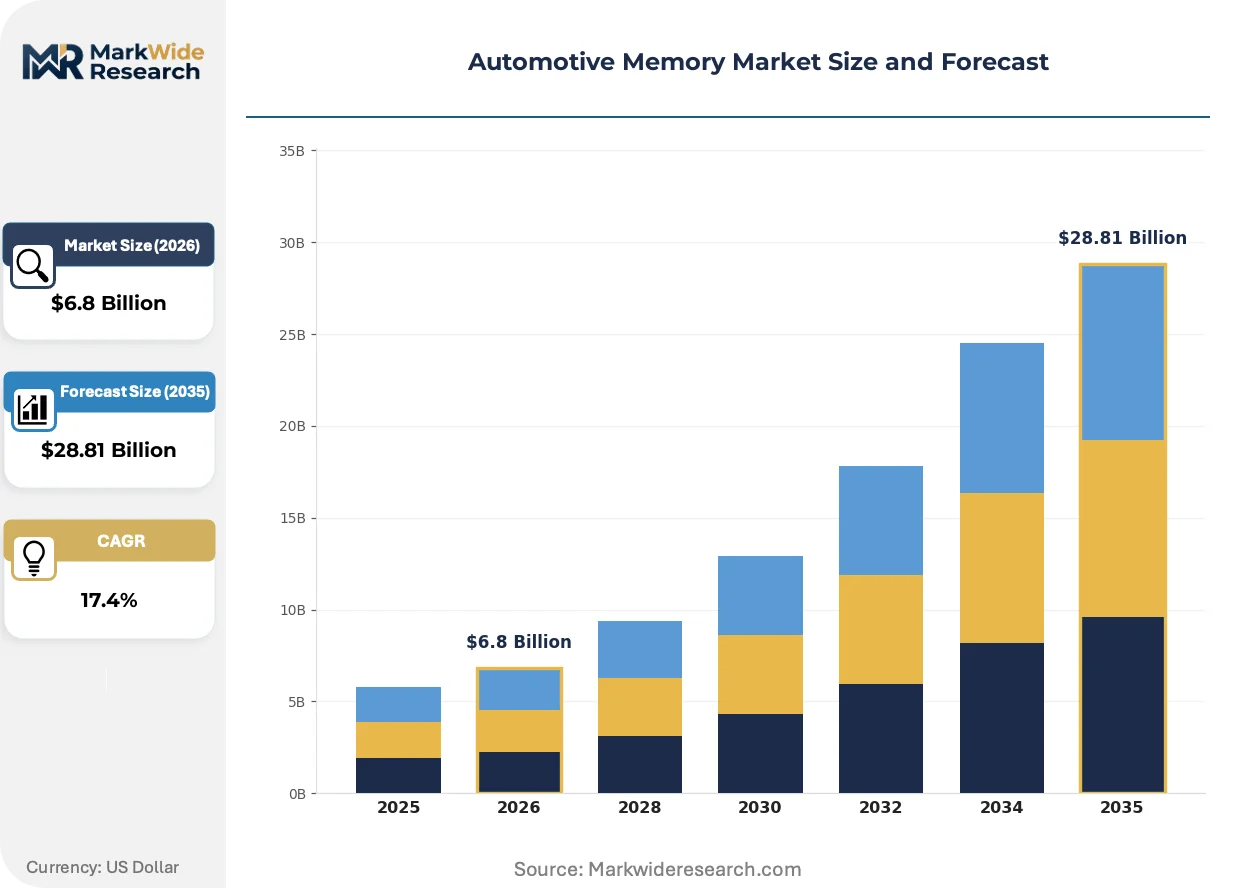
Market Dynamics
GDDR6 bandwidth requirements for autonomous sensor fusion are compressing qualification timelines while ISO 26262 functional safety mandates expand memory validation scope across Tier-1 suppliers.
Growth Catalysts
- Level-2-plus autonomy standardization:Mid-range vehicle platforms now embed camera fusion and neural inference modules that demand high-bandwidth memory architectures.
- EPA emissions data logging mandates:Powertrain control units require extended-temperature NAND Flash with guaranteed retention cycles for regulatory compliance.
- South Korea foundry investments:Advanced DRAM process nodes anchor supply security for German and US premium OEM contracts.
Market Restraints
- AEC-Q100 qualification costs:Extended temperature testing and burn-in cycles add 18-24 months to product launch timelines.
- Foundry concentration in East Asia:Memory wafer supply depends on fabrication clusters concentrated in South Korea and Taiwan.
- GDDR6 power envelope limitations:Thermal constraints in engine-bay installations cap bandwidth scaling for sensor fusion modules.
Strategic Opportunities
- India automotive semiconductor PLI scheme:Domestic memory packaging and testing investments attract OEMs diversifying from East Asian supply.
- In-cabin health monitoring integration:FDA oversight of vital-sign recording subsystems creates demand for medical-grade data retention memory.
- EU AI Act traceability requirements:Autonomous decision logging mandates open specification space for tamper-evident memory architectures.
Industry Challenges
- ISO 26262 ASIL-D certification timelines:Functional safety documentation for brake-by-wire and steer-by-wire systems extends engineering cycles.
- Legacy powertrain controller compatibility:New memory form factors must maintain pin compatibility with 10-15 year vehicle platform lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Memory Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, Flash Memory, SRAM, EEPROM Application: Infotainment Systems, Advanced Driver Assistance Systems, Engine Control Units, Telematics Technology: DDR4, GDDR6, NAND Flash, NOR Flash End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Infineon Technologies, Intel Corporation, SK Hynix, CXMT (ChangXin Memory Technologies), Marvell Technology, Samsung Electronics, Western Digital, Lam Research, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Memory Market Strategic Shifts & Innovations
Memory architectures are fragmenting across automotive subsystems as bandwidth, retention, and safety requirements diverge between autonomous driving, powertrain, and cabin electronics domains.
GDDR6 is overtaking LPDDR4 as the interface standard for camera fusion modules. Premium OEMs in Germany and the United States now specify GDDR6 for 8-megapixel surround-view systems. The technology is overtaking legacy DRAM in bandwidth-per-watt metrics, compressing supplier qualification lists to vendors with automotive-grade GDDR6 roadmaps.
The EU AI Act imposes algorithmic decision logging requirements on Level-3 autonomous systems. Memory components must retain inference inputs and outputs with cryptographic integrity for accident reconstruction. European premium OEMs are redesigning gateway architectures to isolate AI-black-box storage from infotainment memory domains.
Fleet operators now specify outcome-based memory warranties tied to vehicle-mileage rather than time-in-service. Leasing companies in the United States negotiate guaranteed replacement clauses for telematics NAND based on write-cycle accumulation. This consumption-pattern shift forces memory suppliers to model endurance degradation against actual driving profiles rather than standardized test benches.
Automotive Memory Market Segmentation
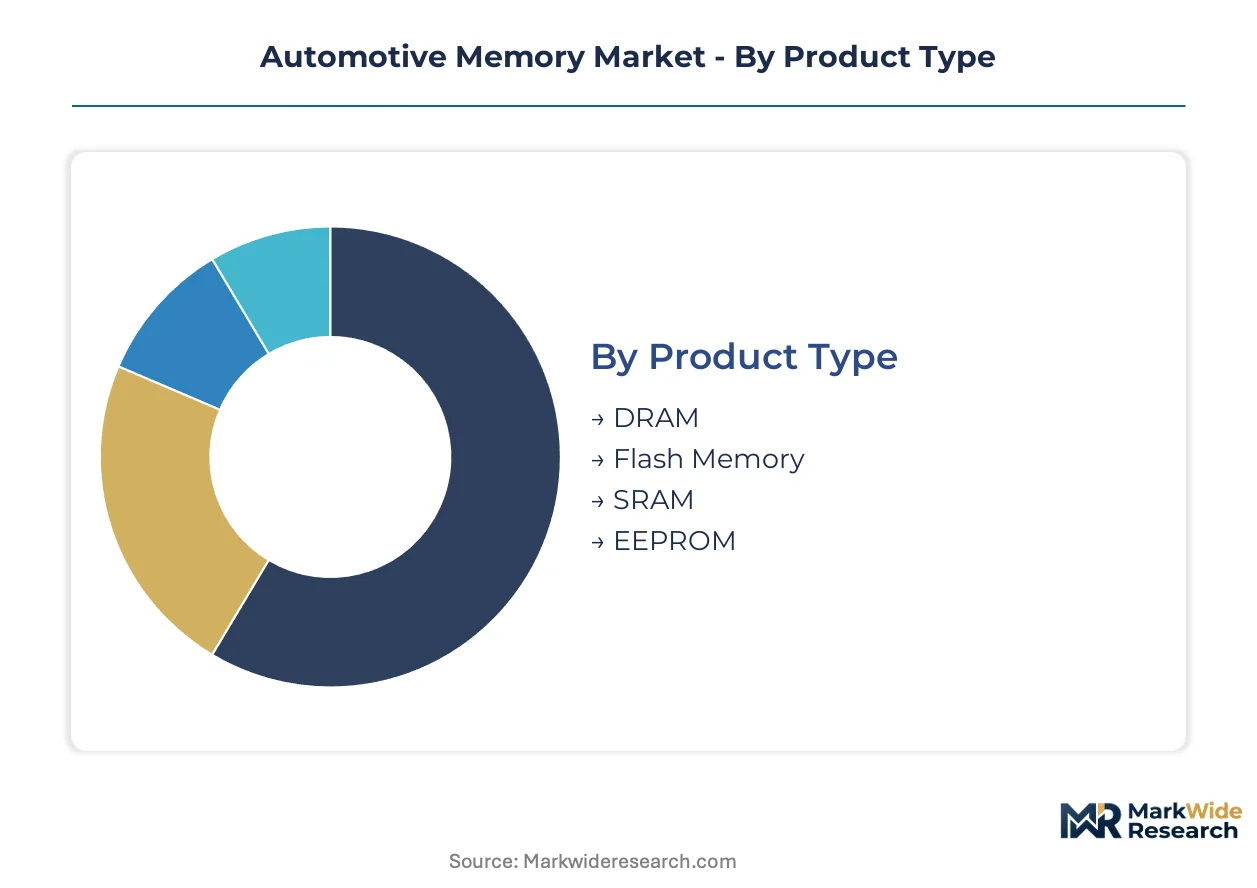
Automotive memory procurement splits across incompatible performance requirements. Powertrain controllers demand decade-long retention at temperature extremes. Sensor fusion modules prioritize bandwidth density over longevity. These divergent specifications fragment supplier portfolios and qualification investments.
Product Type:
Capital intensity concentrates in DRAM foundry conversions and 3D NAND stacking equipment, with process node transitions demanding multi-billion dollar fabrication commitments.
- DRAM:High-bandwidth volatile storage engineered for neural inference and camera fusion workloads. German premium OEMs now specify GDDR6-class DRAM for surround-view systems, compressing supplier lists to vendors with automotive-grade roadmaps.
- Flash Memory:Non-volatile NAND and NOR architectures dominate code storage and data logging applications. EPA emissions mandates in the United States require guaranteed retention cycles across extended temperature ranges for powertrain controllers.
- SRAM:Static random-access memory provides low-latency cache for safety-critical microcontrollers without refresh overhead.
- EEPROM:Electrically erasable programmable read-only memory retains calibration parameters and VIN data through power cycles.
Most installed capacity flows through Flash Memory. Expansion is steepest in DRAM.
Application:
Volume distribution tracks platform electrification timelines and autonomy feature penetration across vehicle classes.
- Advanced Driver Assistance Systems:Camera fusion and radar processing units consume GDDR6 bandwidth at rates exceeding legacy automotive DRAM standards. South Korean foundry investments anchor supply security for Level-2-plus platforms.
- Infotainment Systems:High-resolution displays and streaming architectures drive LPDDR4 and LPDDR5 adoption for cockpit electronics.
- Engine Control Units:Powertrain controllers require automotive-grade NAND Flash with ISO 26262 ASIL-D qualification for emissions compliance logging.
- Telematics:Connected vehicle gateways combine cellular modems with local storage for over-the-air update buffering and crash data retention.
Procurement volume concentrates in Engine Control Units. Climbing the fastest is Advanced Driver Assistance Systems.
Technology:
Interface selection determines qualification scope, with GDDR6 imposing the most demanding signal integrity and thermal validation protocols.
- GDDR6:Graphics-grade memory interface delivers bandwidth density for 8-megapixel sensor streams and real-time neural inference. German and United States OEMs specify this technology for next-generation fusion modules.
- NAND Flash:3D charge-trap and floating-gate architectures provide non-volatile storage density for telematics and powertrain logging subsystems.
- DDR4:Mainstream DRAM interface retains cost advantages for infotainment and body electronics where bandwidth requirements remain modest.
- NOR Flash:Byte-addressable non-volatile memory enables fast boot times for safety-critical microcontrollers in brake-by-wire systems.
Deployment breadth favors NAND Flash. Gaining share fastest is GDDR6.
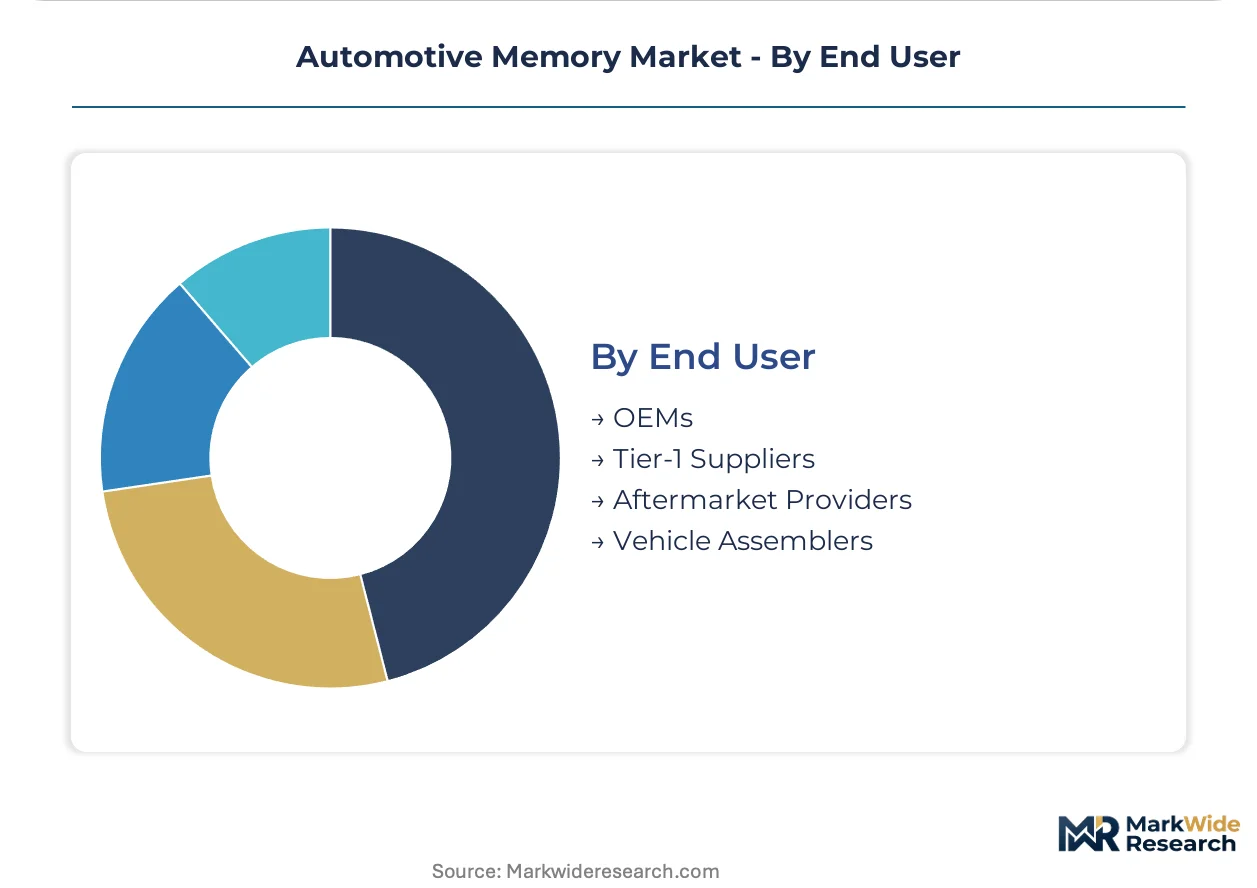
End User:
Procurement authority concentrates with vehicle assemblers and their captive Tier-1 electronics suppliers, fragmenting aftermarket participation.
- OEMs:Original equipment manufacturers direct memory specifications for flagship platforms and retain volume pricing leverage through consolidated purchasing.
- Tier-1 Suppliers:Bosch, Continental, and Denso anchor DRAM and Flash procurement for integrated cockpit and chassis control modules.
- Vehicle Assemblers:Contract manufacturers in emerging production regions source qualified memory through approved vendor lists.
- Aftermarket Providers:Independent service channels address replacement demand for telematics units and infotainment upgrades.
Contract value concentrates with Tier-1 Suppliers. Expanding most quickly is OEM direct procurement for autonomous driving platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting automotive memory packaging investments toward jurisdictions with streamlined qualification protocols. OEMs now weigh AEC-Q100 compliance costs against proximity to final vehicle assembly when siting memory test and module facilities.
United States
NHTSA crash-event recorder mandates and EPA emissions data logging requirements drive demand for extended-temperature NAND Flash. The CHIPS and Science Act directs federal incentives toward domestic DRAM foundry construction. Arizona and Texas anchor new packaging investments serving Detroit-based OEM qualification centers.
Germany
Premium OEMs specify GDDR6-class memory for Level-2-plus surround-view systems under KBA type-approval timelines. The EU AI Act imposes algorithmic decision logging requirements that reshape gateway architecture specifications. Bavaria and Baden-Württemberg concentrate Tier-1 electronics development for autonomous sensor fusion modules.
South Korea
Advanced DRAM process leadership anchors supply security contracts with German and United States premium vehicle platforms. Government-backed foundry investments accelerate automotive-grade GDDR6 qualification timelines. Seoul Capital Area and Busan-Ulsan clusters dominate high-bandwidth memory wafer fabrication and backend testing.
China
Domestic EV platform volumes drive localization requirements for powertrain controller Flash memory under MIIT automotive semiconductor guidelines. ChangXin Memory Technologies and Yangtze Memory Technologies anchor captive supply for local OEMs. Yangtze River Delta and Pearl River Delta clusters concentrate module packaging for BYD and NIO supply chains.
India
Automotive semiconductor PLI scheme incentives attract memory packaging and testing investments from OEMs diversifying East Asian supply exposure. BIS certification requirements for automotive electronics create parallel qualification pathways. Gujarat and Tamil Nadu emerge as backend hubs serving Maruti Suzuki and Hyundai Motor India module demand.
Automotive Memory Market Key Industry Players
Capacity expansion dominates the current landscape as foundries convert DRAM nodes to automotive-grade specifications. The supplier base concentrates around memory specialists with AEC-Q100 qualification track records and captive fab capacity. Three archetypes define positioning: integrated device manufacturers with captive fabrication, fabless specialists leveraging foundry partnerships, and diversified electronics conglomerates cross-leveraging consumer process technology. Strategic emphasis falls on backward integration into wafer supply and geographic diversification of backend testing.
Among integrated device manufacturers, Samsung Electronics, SK Hynix, and Micron Technology occupy positions defined by process node leadership and automotive qualification depth. Samsung exemplifies the diversified conglomerate archetype, cross-applying consumer DRAM advances to automotive GDDR6 roadmaps. SK Hynix represents the foundry-partnership model, anchoring German premium OEM contracts through DRAM specialization. Micron sits within the extended-temperature NAND niche, serving United States powertrain controller mandates. CXMT and Infineon occupy regional-specialist positions tied to domestic supply security objectives.
| Leading Market Players |
|---|
| Infineon Technologies |
| Intel Corporation |
| SK Hynix |
| CXMT (ChangXin Memory Technologies) |
| Marvell Technology |
| Samsung Electronics |
| Western Digital |
| Lam Research |
| Micron Technology |
| Others |
Cost & Logistics Intelligence
GDDR6-grade qualification tiering against legacy DRAM standards bifurcates supplier pricing power and procurement channel structures. German and United States OEMs now pay substantial premiums for automotive-grade GDDR6 with ISO 26262 ASIL-D certification, while commodity NAND Flash for powertrain controllers trades through consolidated Tier-1 distributor networks with compressed margins.
Pricing Analysis
Distributor margin layers for automotive memory compress as OEMs consolidate direct procurement for high-bandwidth components. Pricing stratifies across AEC-Q100 certification grades, with ASIL-D qualified GDDR6 commanding substantial premiums over standard-temperature DRAM. Cost compression in mid-range NAND Flash intensifies because foundry capacity expansion outpaces powertrain controller demand growth. Fleet operators and leasing companies exhibit highest price sensitivity, negotiating outcome-based warranties tied to vehicle mileage accumulation.
Supply Chain Analysis
Workforce availability constraints in South Korea and Taiwan foundry clusters limit automotive-grade DRAM conversion capacity. Wafer supply draws from fabrication centers concentrated in South Korea, Taiwan, and the United States, with backend testing and module packaging distributed across Malaysia, Vietnam, and Mexico. Silicon wafer and photoresist chemical dependencies create single-source vulnerability for advanced node production. Distribution runs through captive Tier-1 supplier channels with approved vendor list restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive memory offers margin-expansion pathways through GDDR6 premium-tier adoption and foundry process node cost-down curves as Level-2-plus autonomy standardizes.
For Market Incumbents: Anticipate qualification timeline compression as South Korean foundries accelerate automotive-grade GDDR6 roadmaps. Secure backward integration into wafer supply through captive fab capacity or long-term offtake agreements with DRAM specialists. Defend against fabless entrants by deepening AEC-Q100 certification track records and ISO 26262 functional safety documentation libraries. For New Entrants and Emerging Players: Begin with India automotive semiconductor PLI scheme incentives for backend packaging and testing investments. Target telematics NAND Flash replacement demand where fleet operators seek outcome-based warranties outside incumbent supply channels. Pursue go-to-market partnerships with emerging EV OEMs in China and India lacking captive memory qualification expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive-grade GDDR6 qualification capabilities concentrate among DRAM specialists with AEC-Q100 track records. Long-term viability favors integrated device manufacturers with captive foundry access and geographic diversification of backend testing. Monitor South Korea foundry investment announcements as inflection indicators for supply security contract awards from German and United States premium OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade GDDR6 Qualification | Captures premium OEM surround-view system contracts under KBA and NHTSA timelines. |
| Backward Integration into Wafer Supply | Secures DRAM allocation for German and United States platform engineering cycles. |
| India PLI Scheme Backend Investment | Diversifies test and packaging footprint away from East Asian concentration risk. |
| ISO 26262 ASIL-D Certification Expansion | Opens brake-by-wire and steer-by-wire memory specification opportunities. |
| Outcome-Based Warranty Product Development | Aligns with United States fleet operator procurement models for telematics NAND. |
Research Approach
Bottom-up vehicle platform content modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, automotive semiconductor foundry planners, and aftermarket distribution channel managers combined with secondary validation from AEC-Q100 qualification databases, EPA emissions regulation filings, NHTSA crash-event recorder mandates, and vehicle production registration data. Triangulation across supply-side wafer allocation disclosures and demand-side content-per-vehicle estimates anchors volume projections.
Historical trendline analysis of DRAM node transitions and NAND Flash stacking generation adoption informs the projection framework. Segmentation dimensions span product type, application subsystem, interface technology, vehicle class, propulsion architecture, and regional OEM tier. CAGRs derive from modeled content growth per autonomous driving level and electrification penetration curves. Forecast inputs include South Korea foundry investment announcements, German KBA type-approval timelines, and United States CHIPS Act incentive disbursement patterns.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, raw material price volatility, and autonomous driving regulatory framework delays. Forecasts reflect documented assumptions regarding qualification timeline stability and foundry yield ramp trajectories. Material deviation in NHTSA rulemaking, EU AI Act enforcement intensity, or South Korea-Taiwan supply disruption triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Automotive DRAM Market
Memory Chips
Nano RAM Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
MRAM Market
Memory Chips
Memory IC Market
Memory Chips
China Flash Memory Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
DDR RAM Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Global Dynamic Random Access Memory (DRAM) Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Memory Market
Memory Chips
ECC Memory Market
Memory Chips
Japan DRAM Market