
 IGBT and Super Junction MOSFET Market | 2026-2036
IGBT and Super Junction MOSFET Market Size, Share, and Industry Trends Forecast 2026-2036
IGBT and Super Junction MOSFET Market Intelligence
Software-defined power management is repositioning the value proposition beyond the physical component, enabling new functionalities in complex systems. Infineon Technologies AG leverages its significant manufacturing scale and R&D in automotive and industrial power control. STMicroelectronics competes effectively through its broad portfolio targeting consumer electronics and power supply applications. Meanwhile, Fuji Electric Co., Ltd. specializes in high-reliability IGBT modules for industrial motor drives and renewable energy infrastructure, sustaining a strong market presence in high-power segments.
An Insulated Gate Bipolar Transistor (IGBT) is a three-terminal power semiconductor device that combines the high input impedance of a MOSFET with the high current-handling capability of a bipolar transistor, often rated for voltages from 600V to over 6.5kV. A Super Junction MOSFET achieves very low on-state resistance by using a vertical structure of alternating P and N-type pillars. While IGBTs continue to dominate high-power applications like electric traction and motor drives, Super Junction MOSFETs are increasingly specified for high-frequency power supplies and renewable energy conversion systems due to superior switching efficiency.
Regulatory frameworks significantly influence component design and market access for power semiconductors. The EU's RoHS directive restricts the use of specific hazardous materials, while CE marking mandates conformity with health, safety, and environmental protection standards. In parallel, China's GB standards set compulsory requirements for electronics sold within its market. These regulations compel manufacturers to innovate in material science and ensure their devices meet stringent energy efficiency and reliability benchmarks. Success depends on aligning product development with evolving global standards for sustainability and performance.
Market Dynamics
The fundamental shift from traditional silicon to wide-bandgap semiconductor materials like silicon carbide is the central force shaping the market. This material science evolution redefines performance benchmarks for both IGBTs and Super Junction MOSFETs, impacting everything from device architecture to end-system design.
Growth Catalysts
- Government Decarbonization Policies:Mandates like China's dual carbon goals and the EU Green Deal accelerate investment in electric vehicles and renewable energy infrastructure, directly stimulating demand for high-efficiency power conversion components.
- Data Center Expansion:The proliferation of cloud computing and AI workloads requires power supplies with higher efficiency and power density, favoring the adoption of advanced Super Junction MOSFETs for their superior switching performance.
- Industrial Automation:Increasing electrification of factory equipment and robotics relies on high-power IGBT modules to provide precise and efficient control for industrial motor drives, a core application segment.
Market Restraints
- Substrate Supply Bottlenecks:The concentrated and limited supply of high-quality silicon carbide (SiC) wafers creates input cost volatility and potential production delays for next-generation wide-bandgap devices.
- Thermal Management Complexity:Higher switching frequencies and power densities in modern devices create significant thermal challenges, requiring more sophisticated and costly cooling solutions at the system level.
- Substitution from Integrated Solutions:The rise of highly integrated Intelligent Power Modules (IPMs) can reduce the addressable market for discrete IGBTs and MOSFETs in certain applications by abstracting component selection.
Strategic Opportunities
- Grid Modernization:The development of solid-state circuit breakers and transformers for utility grids presents a significant opportunity for new high-voltage IGBT and SiC MOSFET designs.
- GaN-on-Silicon Technology:Advances in Gallium Nitride (GaN) grown on silicon substrates offer a potential cost-effective pathway to high-frequency performance, creating an opening for devices targeting mid-power applications.
- Charging Infrastructure in Southeast Asia:The nascent but growing electric vehicle market in countries like Vietnam and Thailand creates a geographic white space for power modules tailored to local charging standards and grid conditions.
Industry Challenges
- Specialized Engineering Talent:A persistent shortage of power electronics engineers with deep expertise in wide-bandgap material physics, high-frequency circuit design, and advanced packaging constrains R&D velocity.
- Global Compliance Overhead:Manufacturers face significant costs and delays in certifying products to meet a divergent set of international requirements, including the EU's CE marking and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IGBT and Super Junction MOSFET Market |
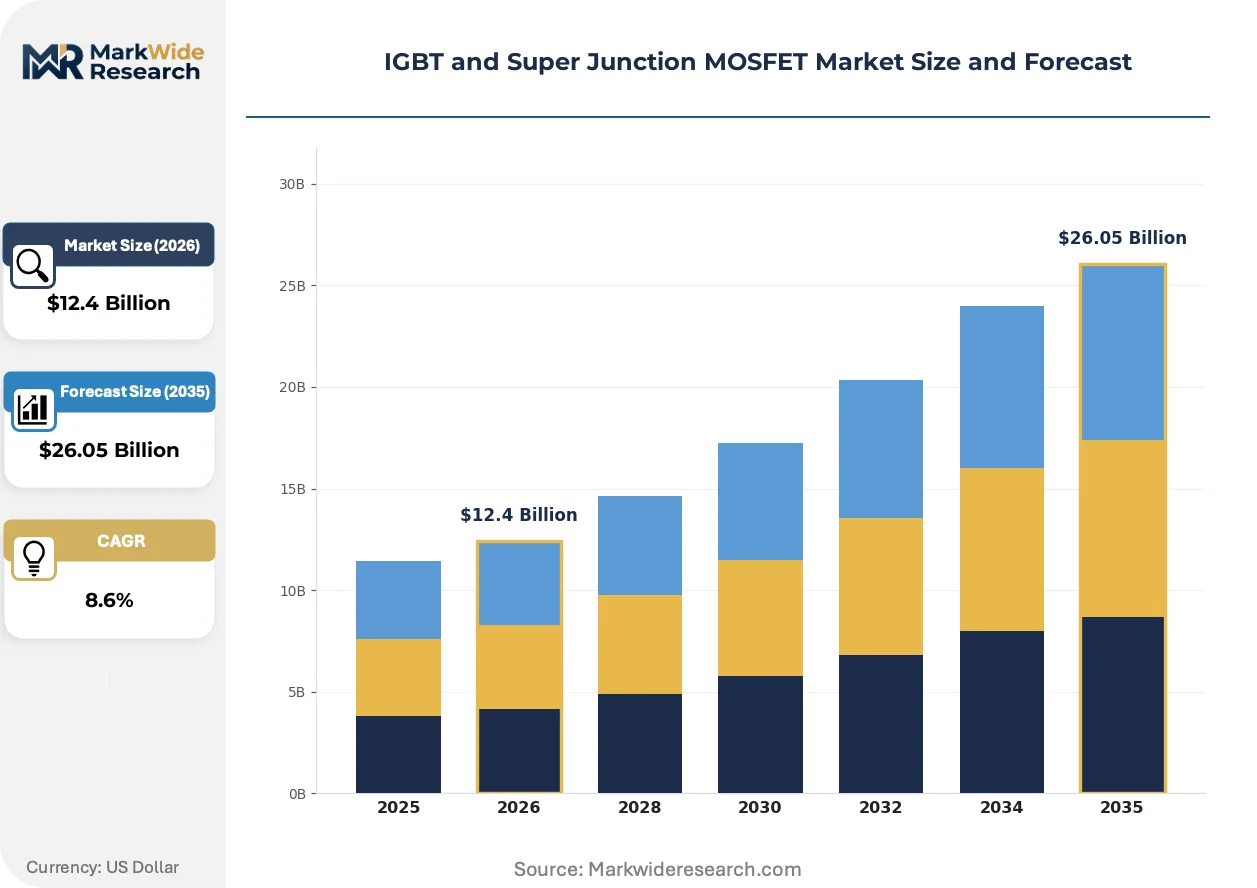
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insulated Gate Bipolar Transistor, Super Junction MOSFET, Planar MOSFET, Vertical MOSFET Technology: Trench Gate, Field-Stop, Punch-Through, Non-Punch-Through, CoolMOS, JFET Application: Renewable Energy Conversion, Electric Traction, Power Supplies, Motor Drives, Welding Machines End User: Consumer Electronics, Aerospace & Defense, Telecommunications, Renewable Energy Systems |
| Companies Covered | Mitsubishi Electric Corporation, Toshiba Electronic Devices & Storage Corporation, Infineon Technologies AG, ON Semiconductor, Semikron Danfoss, ROHM Co., Ltd., Fuji Electric Co., Ltd., Vishay Intertechnology, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IGBT and Super Junction MOSFET Market Strategic Shifts & Innovations
Technological advancement is defined by the pursuit of higher efficiency and power density, driven by material science innovation and more intelligent system integration. This evolution pushes device capabilities, enabling new functionalities in demanding end-use applications like electric vehicles and renewable energy systems.
Wide-bandgap materials such as silicon carbide (SiC) and gallium nitride (GaN) provide superior thermal conductivity and switching speed compared to conventional silicon. These materials are seeing rapid adoption in applications requiring high efficiency, including electric vehicle chargers and data center power supplies. This trend is integrating system-level benefits, such as reduced size of passive components and simplified cooling requirements, into the core value of the semiconductor device itself.
Regulatory frameworks like the EU's Ecodesign Directive are setting stricter mandatory minimum efficiency levels for electronics. This policy directly forces product manufacturers to design with more efficient power conversion stages, increasing the specification of advanced Super Junction MOSFETs and IGBTs. The industrial motor and external power supply segments are most affected, redesigning products to maintain market access in key economic blocs.
A notable behavioral shift is occurring as original equipment manufacturers in high-power sectors demand more application-specific power modules over discrete components. This change disrupts traditional distribution models, fostering direct collaboration between device makers and end-users in the automotive and industrial sectors. This co-development trend is most visible in the design of custom traction inverters for electric vehicles and converters for utility-scale solar farms.
IGBT and Super Junction MOSFET Market Segmentation
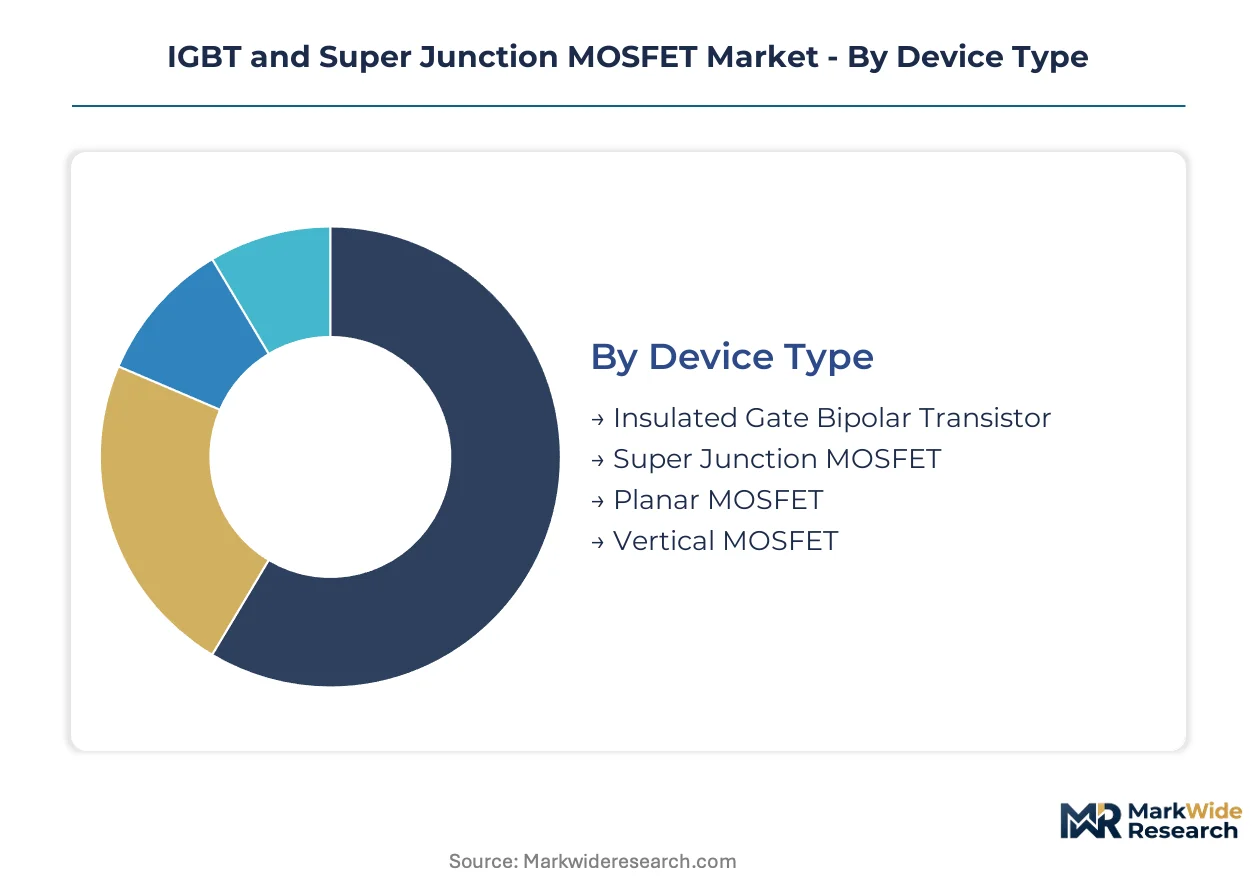
The IGBT and Super Junction MOSFET market exhibits distinct segmentation across device types, underlying technologies, diverse applications, and end-user industries. Understanding these categories is critical for manufacturers to align product development with specific performance requirements and demand concentrations.
Device Type:
The market delineates devices based on their fundamental semiconductor structure and operational characteristics, impacting power handling and switching efficiency.
- Insulated Gate Bipolar Transistor:This three-terminal power semiconductor combines MOSFET's high input impedance with a bipolar transistor's high current-handling capability. Demand concentrates in electric traction systems and industrial motor drives, driven by requirements for high voltage and current operation.
- Super Junction MOSFET:A device achieving very low on-state resistance through a vertical arrangement of alternating P and N-type pillars. Adoption accelerates in high-frequency power supplies and renewable energy conversion systems due to superior switching efficiency.
- Planar MOSFET:These devices feature a horizontal current flow path and are widely used in low-to-medium power applications.
- Vertical MOSFET:Characterized by a vertical current flow, these MOSFETs offer higher power density and are suitable for various power management tasks.
Mature deployment sits with Insulated Gate Bipolar Transistor. Newer deployment is concentrated in Super Junction MOSFET.
Technology:
Technological advancements underpin the performance characteristics of power semiconductors, influencing their suitability for specific power conversion challenges.
- Trench Gate:This technology integrates the gate structure into a trench, reducing on-state resistance and improving switching speed in both MOSFETs and IGBTs. Its efficiency benefits are particularly sought after in automotive power electronics for electric vehicles.
- Field-Stop:A critical design feature in IGBTs that creates a thin N-type layer to stop the electric field, enabling higher breakdown voltages and lower conduction losses. This design is crucial for high-power industrial applications like wind turbine converters.
- Punch-Through:This IGBT design allows for a thinner N-drift region, enhancing switching speed at the cost of higher saturation voltage.
- Non-Punch-Through:Offering a robust design with a thicker N-drift region, Non-Punch-Through IGBTs prioritize ruggedness and lower switching losses for specific industrial uses.
- CoolMOS:Infineon's proprietary Super Junction MOSFET technology optimizes on-state resistance for high-efficiency power supplies.
- JFET:Junction Field-Effect Transistors offer high input impedance and are used in specialized high-frequency and high-temperature applications.
The Trench Gate technology segment is expanding most quickly, while Non-Punch-Through maintains steady demand.
Application:
The end-use applications for IGBTs and Super Junction MOSFETs span diverse sectors, each demanding specific power management attributes from these components.
- Renewable Energy Conversion:Power conversion systems for solar inverters and wind power utilize these devices for efficient DC-AC and AC-DC conversion. Demand is driven by global decarbonization policies and grid modernization initiatives.
- Electric Traction:This application involves motor control in electric vehicles, hybrid electric vehicles, and railway systems, requiring robust and efficient power switching. China's expansive EV manufacturing base drives significant volume for these components.
- Power Supplies:From consumer electronics to industrial equipment, these devices regulate voltage and current for stable operation.
- Motor Drives:Industrial automation and robotics rely on IGBT modules for precise and efficient control of electric motors.
- Welding Machines:High-power IGBTs enable precise current control and high-frequency switching for advanced welding technologies.
High-power applications like Electric Traction drive substantial volume, with Renewable Energy Conversion exhibiting significant growth potential.
End User:
Different end-user industries integrate IGBTs and Super Junction MOSFETs into their products, reflecting varied requirements for power, efficiency, and reliability.
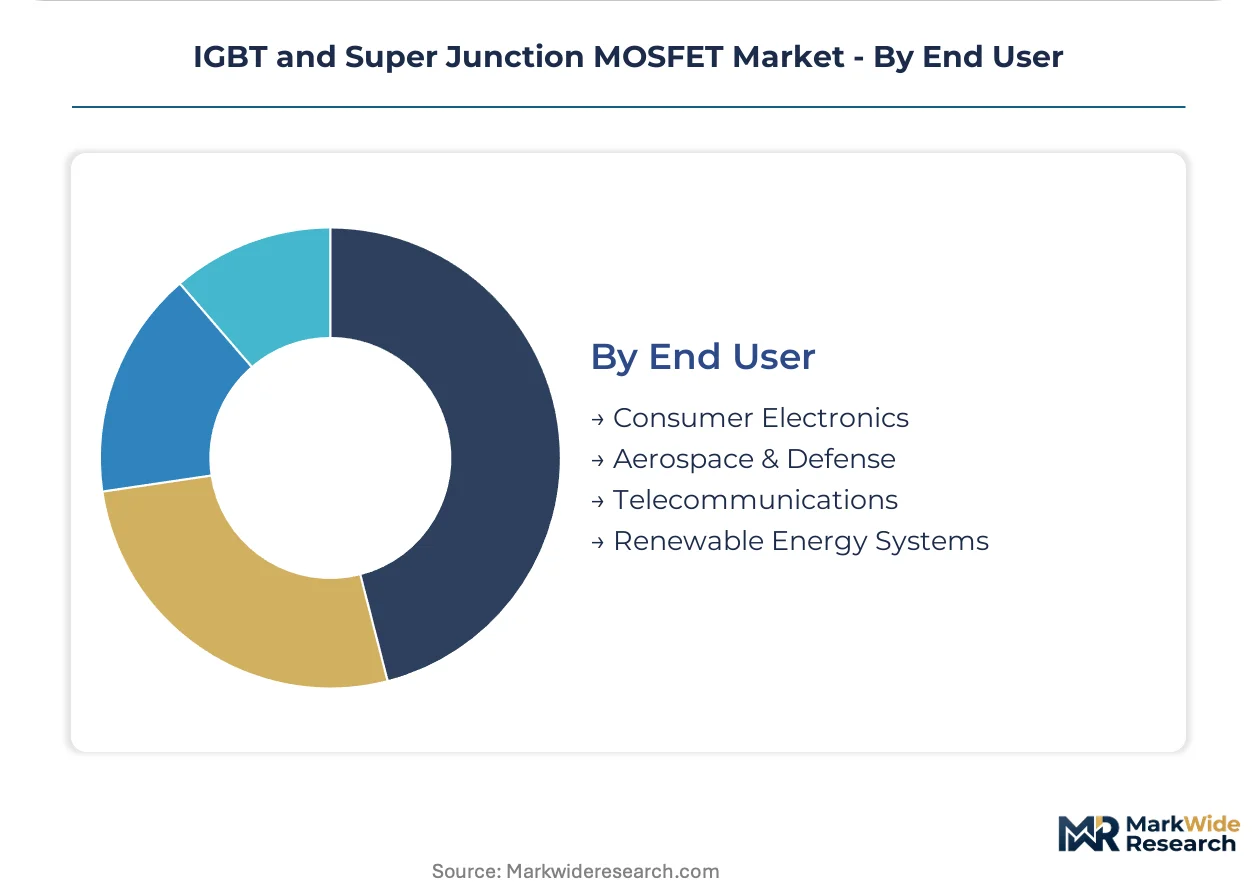
- Consumer Electronics:Devices such as power adapters, home appliances, and computing equipment incorporate these semiconductors for efficient power management. China's manufacturing base for consumer electronics drives substantial component procurement.
- Aerospace & Defense:High-reliability and rugged power modules are essential for avionics, radar systems, and military hardware. Stringent performance and durability standards characterize this segment.
- Telecommunications:Base stations, network infrastructure, and data centers use these components for power conversion and regulation.
- Renewable Energy Systems:This segment encompasses solar power plants, wind farms, and energy storage systems requiring robust power electronics.
The most dynamic expansion is observed in Renewable Energy Systems end-use, while Consumer Electronics maintains stable procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region in China serves as a critical hub for global power semiconductor demand. Its extensive manufacturing ecosystem for consumer electronics and electric vehicles drives significant component procurement. This concentration influences supply chain dynamics across the market.
China
China's expansive electric vehicle manufacturing and consumer electronics production drive substantial demand for advanced power semiconductors. The nation's dual carbon goals accelerate investment in renewable energy, further boosting component needs. In the Pearl River Delta, companies actively develop application-specific power modules for domestic and international markets. Local GB standards also influence component design and market access.
Germany
German automotive electrification initiatives and industrial automation projects create robust demand for high-efficiency IGBTs and Super Junction MOSFETs. The EU Green Deal mandates stringent energy efficiency, compelling manufacturers to adopt advanced power conversion stages. Bavaria houses significant R&D centers focusing on wide-bandgap materials for next-generation devices.
United States
The United States experiences strong demand from expanding data centers requiring high-efficiency power supplies and grid modernization efforts. The Inflation Reduction Act stimulates investment in renewable energy infrastructure, increasing the need for advanced power electronics. Silicon Valley startups and established firms in Texas innovate in GaN-on-Silicon technologies for mid-power applications.
Japan
Japanese industrial motor drives and renewable energy conversion systems generate consistent demand for high-reliability IGBT modules. METI's policies promote energy-efficient manufacturing, driving the adoption of advanced power semiconductors across various sectors. The Kansai region features specialized manufacturers developing high-voltage IGBTs for critical infrastructure projects.
IGBT and Super Junction MOSFET Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the IGBT and Super Junction MOSFET market, which exhibits a tiered structure. Integrated device manufacturers with significant R&D capabilities dominate high-volume segments. Specialized power module providers focus on niche applications requiring custom solutions. Capacity expansion in wide-bandgap materials and strategic partnerships for application-specific designs are prevalent competitive moves.
Within the integrated device manufacturer archetype, Germany's Infineon Technologies AG and Switzerland-based STMicroelectronics N.V. occupy significant positions, leveraging broad portfolios across automotive and consumer electronics. Japan's Fuji Electric Co., Ltd. exemplifies a specialist in high-reliability IGBT modules, anchoring its market presence in industrial motor drives and renewable energy infrastructure. These companies represent diverse approaches to technology development and market access within the power semiconductor landscape, reflecting varied strategic priorities from broad market coverage to deep application expertise.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Toshiba Electronic Devices & Storage Corporation |
| Infineon Technologies AG |
| ON Semiconductor |
| Semikron Danfoss |
| ROHM Co., Ltd. |
| Fuji Electric Co., Ltd. |
| Vishay Intertechnology |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Global decarbonization policies and stringent energy efficiency mandates are driving demand for advanced power semiconductors, compelling manufacturers to invest in novel materials and processes, which influences overall device pricing. This shift necessitates supply chain agility to meet evolving performance benchmarks.
Pricing Analysis
Cost-down pressure on conventional silicon-based power semiconductors accelerates as wide-bandgap materials gain traction across applications. The dominant pricing model combines long-term contract-based agreements for high-power industrial and automotive applications with per-unit transactional sales for consumer electronics. Price differentiation stems from quality grade, specific certifications like CE marking, and volume scale. While consumer electronics procurement exhibits high price sensitivity, aerospace and defense sectors prioritize reliability over cost.
Supply Chain Analysis
Single-source vulnerability sits with the concentrated supply of high-quality silicon carbide wafers, primarily sourced from a few specialized manufacturers in the United States and Europe. The supply chain for IGBTs and Super Junction MOSFETs draws from manufacturing hubs in China, Germany, and Japan. Key dependencies include high-purity silicon, SiC, and GaN substrates. Distribution runs through direct collaboration channels for application-specific power modules in automotive, while discrete components utilize established electronic component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IGBT and Super Junction MOSFET market is poised for consolidation, driven by the intense capital requirements for wide-bandgap material R&D and manufacturing scale. This pressure forces smaller, less capitalized players to seek strategic partnerships or exit.
For Market Incumbents: Cement leadership by aggressively investing in wide-bandgap material R&D and expanding manufacturing capacity, particularly for silicon carbide substrates. Deepen vertical integration into application-specific power module assembly to counter the threat of substitution from integrated solutions. Strategic partnerships for advanced packaging solutions can mitigate thermal management complexity. Focus R&D efforts on enhancing device performance under higher switching frequencies.
For New Entrants and Emerging Players: Begin with targeting niche, high-growth white spaces like GaN-on-Silicon technology for mid-power applications, which offers a cost-effective pathway to high-frequency performance. Focus on the nascent electric vehicle charging infrastructure in Southeast Asia, developing power modules tailored to local grid conditions. A go-to-market angle emphasizing localized support and compliance with regional standards can accelerate market penetration. Prioritize agile product development for rapid iteration.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized wide-bandgap material producers and advanced packaging firms given the critical role of power semiconductors in global decarbonization initiatives. The market offers long-term viability, underpinned by sustained demand from electric vehicles and renewable energy. Target acquisition archetypes include mid-cap companies with proprietary SiC or GaN substrate technologies. The signal to watch is the successful commercialization of next-generation GaN-on-Silicon devices in high-volume applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in SiC Wafer Production | Increases supply chain resilience and reduces input cost volatility for wide-bandgap devices. |
| Backward Integration into Power Module Assembly | Enhances control over critical manufacturing processes and improves application-specific design. |
| Joint Venture for Advanced Packaging Solutions | Accelerates innovation in thermal management, crucial for high-power density components. |
| Product Launch of GaN-on-Silicon Devices | Captures new market share in cost-sensitive mid-power and high-frequency applications. |
| Certification Investment for Global Standards | Ensures market access and compliance with diverse regulatory frameworks like CE marking. |
Research Approach
Multi-period observation of power semiconductor adoption rates and material science advancements anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research involved discussions with power electronics engineers, R&D directors, procurement managers, and regulatory compliance specialists. These insights were validated against secondary sources including government energy reports, automotive industry statistics, semiconductor association publications, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
An input-output matrix framework modeled market dynamics across the analysis window, projecting future growth based on identified drivers and restraints. The segmentation dimensions included device type, technology, application, end-user industry, and regional regulatory environment. Compound Annual Growth Rates were derived from historical data and projected market drivers like electric vehicle production volumes. Renewable energy capacity additions also served as critical forecast inputs.
Geopolitical trade tensions, raw material price volatility, and rapid technological disruptions are the dominant revision risks for these forecasts, which reflect specific underlying assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Wttx Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market