
 Spintronic Logic Devices Market | 2026-2036
Spintronic Logic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spintronic Logic Devices Market Analytics
REACH compliance is expanding the cost-of-entry calculus for spintronic logic device manufacturers targeting European electronics supply chains. Infineon Technologies leverages its established power semiconductor footprint to anchor spintronic R&D within German industrial clusters. Everspin Technologies Inc. sustains manufacturing scale for magnetic memory products that serve as commercial proving grounds for spin logic integration. Crocus Technology specializes in magnetic sensor-to-logic process migration, positioning its foundry capabilities for downstream device qualification.
Spintronic logic devices exploit electron spin rather than charge to encode and process binary states, typically employing magnetic tunnel junctions with oxide barrier thicknesses below two nanometers to achieve tunnel magnetoresistance ratios exceeding 100 percent. These devices target non-volatile computing applications where zero standby power and instant-on operation replace conventional volatile CMOS architectures. Magnetoresistive RAM products currently dominate near-term revenue streams due to existing fabrication infrastructure and qualification pathways. Spin-orbit torque devices represent the fastest-growing technology category as research consortia demonstrate sub-nanosecond switching with energy-per-bit figures approaching femtojoule targets. Hybrid spintronics architectures concentrate margin pools at the interface between foundry process development and fabless design houses.
FDA oversight of medical device data integrity intersects with spintronic non-volatile memory applications in implantable diagnostics, while FCC electromagnetic compatibility rules shape packaging and shielding specifications for telecommunications deployments. EPA hazardous substance restrictions influence magnetic material sourcing and end-of-life recovery obligations for manufacturers operating across North American supply chains. Stakeholders must monitor foundry capacity allocation between legacy CMOS nodes and emerging spin-compatible processes to secure wafer starts for qualification batches.
Market Dynamics
Spintronic logic device commercialization hinges on foundry capacity allocation between legacy CMOS nodes and emerging magnetic-compatible process flows, with qualification timelines stretching across multiple semiconductor fabrication cycles.
Growth Catalysts
- AI accelerator demand:Data centers require non-volatile logic architectures that eliminate standby power consumption during inference workloads.
- REACH compliance:European electronics supply chains now mandate hazardous substance documentation that favors spintronic alternatives to volatile memory chemistries.
- Spin-orbit torque switching:Research consortia demonstrate sub-nanosecond operation with femtojoule energy-per-bit targets, opening paths to CMOS replacement.
Market Restraints
- Magnetic material sourcing:Rare earth element concentration in Chinese processing facilities creates supply vulnerability for tunnel junction electrodes.
- Process tool scarcity:Atomic layer deposition chambers for sub-two-nanometer oxide barriers face 18-month lead times from single-source equipment vendors.
- CMOS ecosystem lock-in:Established design automation flows and IP libraries retard migration to spin-based logic families.
Strategic Opportunities
- Medical implant diagnostics:FDA oversight of device data integrity creates preference for non-volatile memory in pacemakers and continuous glucose monitors.
- Telecommunications edge nodes:FCC electromagnetic compatibility rules favor spintronic packaging approaches that reduce shielding mass.
- Hybrid architecture services:Fabless design houses capture margin pools by bridging foundry process development with application-specific spin logic integration.
Industry Challenges
- Magnetic tunnel junction metrology:Defect detection at sub-nanometer oxide thicknesses requires electron microscopy capabilities scarce in commercial test facilities.
- Multi-physics simulation talent:Device modeling demands simultaneous mastery of spin transport, thermal management, and circuit timing closure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spintronic Logic Devices Market |
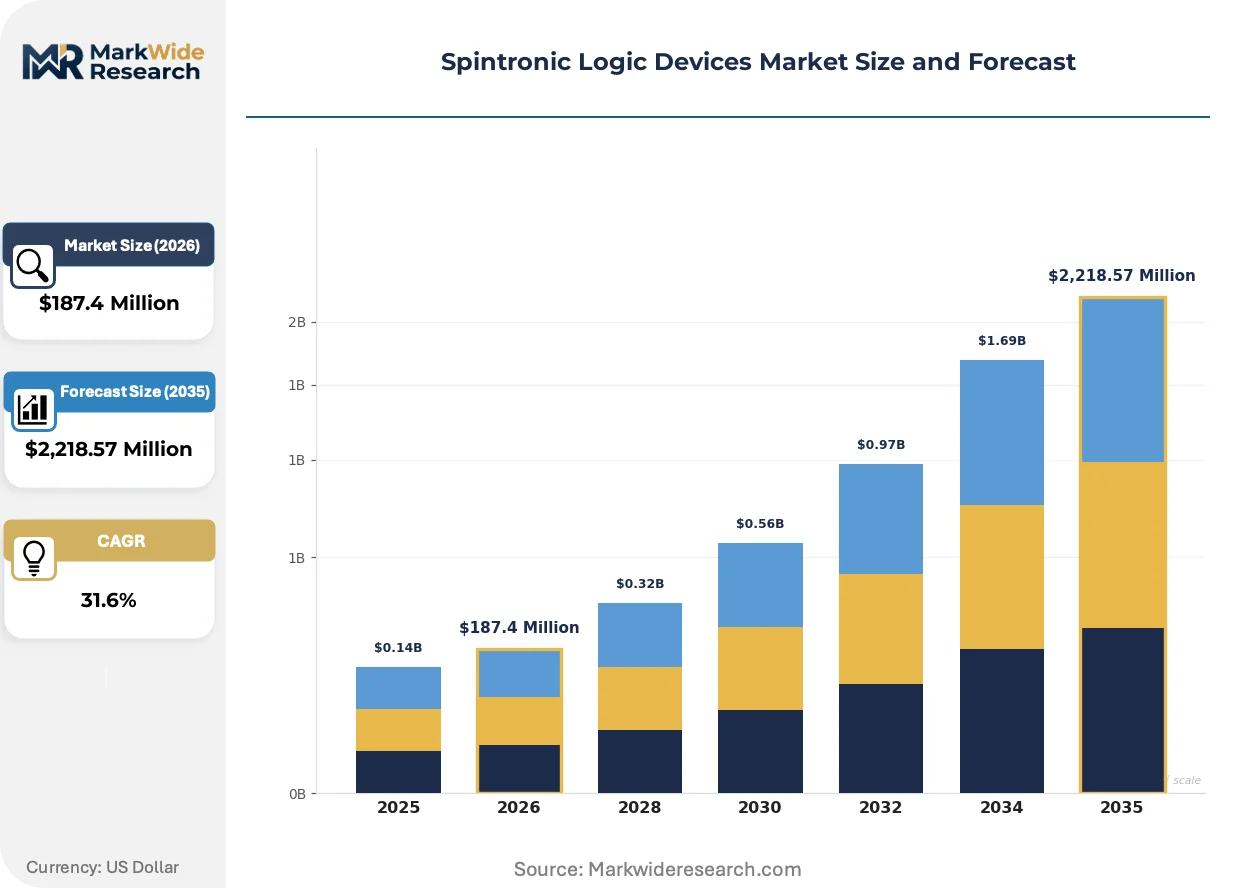
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetoresistive RAM, Spin Transistor, Spin-Orbit Torque Devices, Quantum Dot Spintronics Technology: Charge-Based, Spin-Based, Hybrid Spintronics, Magnetic Tunnel Junction Application: Consumer Electronics, Data Storage, Telecommunications, Automotive Electronics End User: Telecom Industry, IT Sector, Military, Aerospace |
| Companies Covered | Applied Spintronic Technology, Inc., Infineon Technologies, Everspin Technologies Inc., Futek Advanced Sensor Technology Inc., Kistler Group, NVE Corporation, Spintec, PCB Piezotronics, Crocus Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spintronic Logic Devices Market Evolving Landscape
Process migration from magnetic sensor fabrication to logic-grade qualification is compressing development timelines. Device architectures now prioritize compatibility with existing back-end-of-line metallization rather than demanding wholly new fabrication paradigms.
Perpendicular magnetic tunnel junctions with cobalt-iron-boron free layers are modularizing across foundry offerings. Memory manufacturers in Taiwan and South Korea pilot these structures for embedded non-volatile cache applications. The technology is modularizing what were previously discrete memory and logic supply chains into unified process flows.
EPA hazardous substance restrictions under TSCA Section 6 are tightening magnetic material recovery obligations. North American manufacturers must document end-of-life rare earth reclamation pathways or face exclusion from federal procurement channels. Defense and aerospace subsystems suppliers absorb the steepest compliance costs.
Specification-driven procurement now dominates data center infrastructure buying. Hyperscale operators issue functional requirements for zero-standby-power logic rather than prescribing CMOS-compatible pinouts. This pattern concentrates most visibly in Virginia and Singapore colocation markets where carbon intensity regulations intersect with density constraints.
Spintronic Logic Devices Market Segmentation
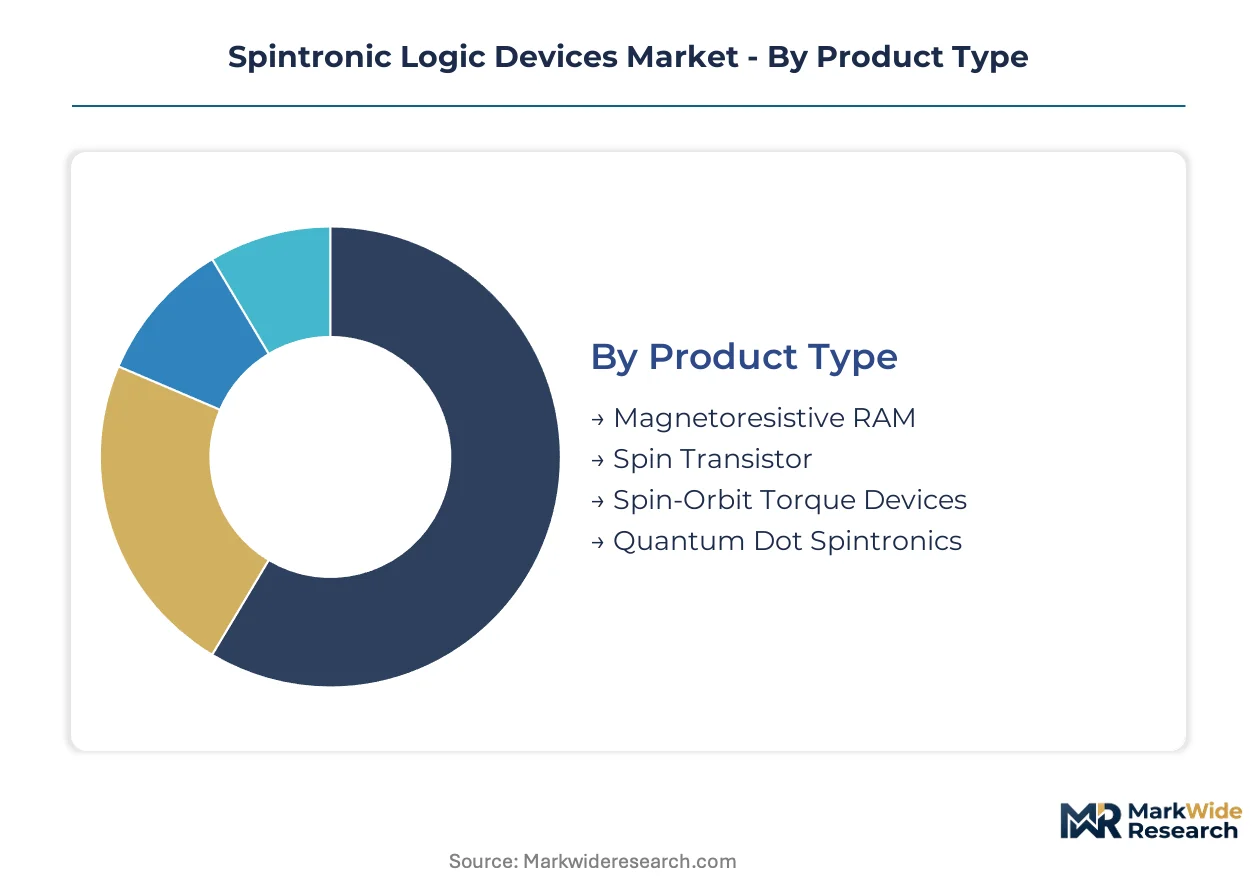
Spintronic logic devices fragment across four critical dimensions that determine foundry process compatibility, qualification timelines, and margin capture. Product type and technology choices anchor capital allocation decisions, while application and end-user segmentation governs regulatory exposure and volume scaling pathways.
Product Type:
Supply concentration in magnetic tunnel junction fabrication capacity currently favors established memory architectures over emerging logic variants.
- Magnetoresistive RAM:Non-volatile memory cells built on one-transistor-one-magnetic-tunnel-junction architectures leverage existing 300mm foundry infrastructure. Data center cache hierarchies in Virginia and Singapore absorb the majority of qualified wafer starts as hyperscale operators mandate zero-standby-power alternatives to SRAM.
- Spin-Orbit Torque Devices:These structures exploit spin-orbit coupling in heavy metal underlayers to achieve sub-nanosecond switching without external magnetic fields. Research consortia in Japan and Germany demonstrate femtojoule-per-bit operation, positioning this category for CMOS replacement in edge AI inference engines where energy constraints dominate.
- Spin Transistor:Field-effect devices with spin-polarized source-drain channels remain confined to laboratory demonstrations at IBM Zurich and Tohoku University.
- Quantum Dot Spintronics:Single-electron spin qubit implementations require dilution refrigeration infrastructure available only at national quantum computing facilities.
Today's leader: Magnetoresistive RAM. Tomorrow's challenger: Spin-Orbit Torque Devices.
Technology:
Cost tier stratification separates qualified production flows from exploratory research architectures.
- Magnetic Tunnel Junction:Perpendicular MTJs with cobalt-iron-boron free layers and magnesium oxide barriers below 1.5nm thickness dominate commercial roadmaps. Taiwan and South Korean foundries qualify these structures for embedded non-volatile cache at 22nm nodes and above.
- Hybrid Spintronics:CMOS-spin integration schemes concentrate margin pools at the interface between legacy logic nodes and magnetic back-end processing. Fabless design houses in Austin and Munich capture value by bridging process development with application-specific integration.
- Spin-Based:Pure spin logic without charge transport remains pre-commercial, constrained by signal amplification requirements.
- Charge-Based:Conventional CMOS with spintronic augmentation offers near-term retrofit pathways for existing fabrication lines.
Hybrid Spintronics is climbing the fastest as foundries seek incremental revenue from mature node capacity.
Application:
Volume concentration in data infrastructure creates procurement leverage that reshapes device specifications.
- Data Storage:Enterprise SSD controllers and storage-class memory hierarchies specify non-volatile cache to eliminate power-loss data protection overhead. Hyperscale operators in Northern Virginia issue functional requirements rather than pinout specifications, accelerating architectural freedom.
- Telecommunications:Edge node deployments favor spintronic packaging that reduces electromagnetic shielding mass under FCC rules. Base station manufacturers in Finland and South Korea pilot embedded magnetic memory for firmware storage.
- Automotive Electronics:Powertrain controllers and ADAS subsystems require AEC-Q100 qualification pathways that remain underdeveloped for spin logic.
- Consumer Electronics:Smartphone application processors maintain CMOS lock-in due to design automation ecosystem constraints.
Telecommunications is gaining share fastest as 5G infrastructure refresh cycles align with non-volatile memory roadmaps.
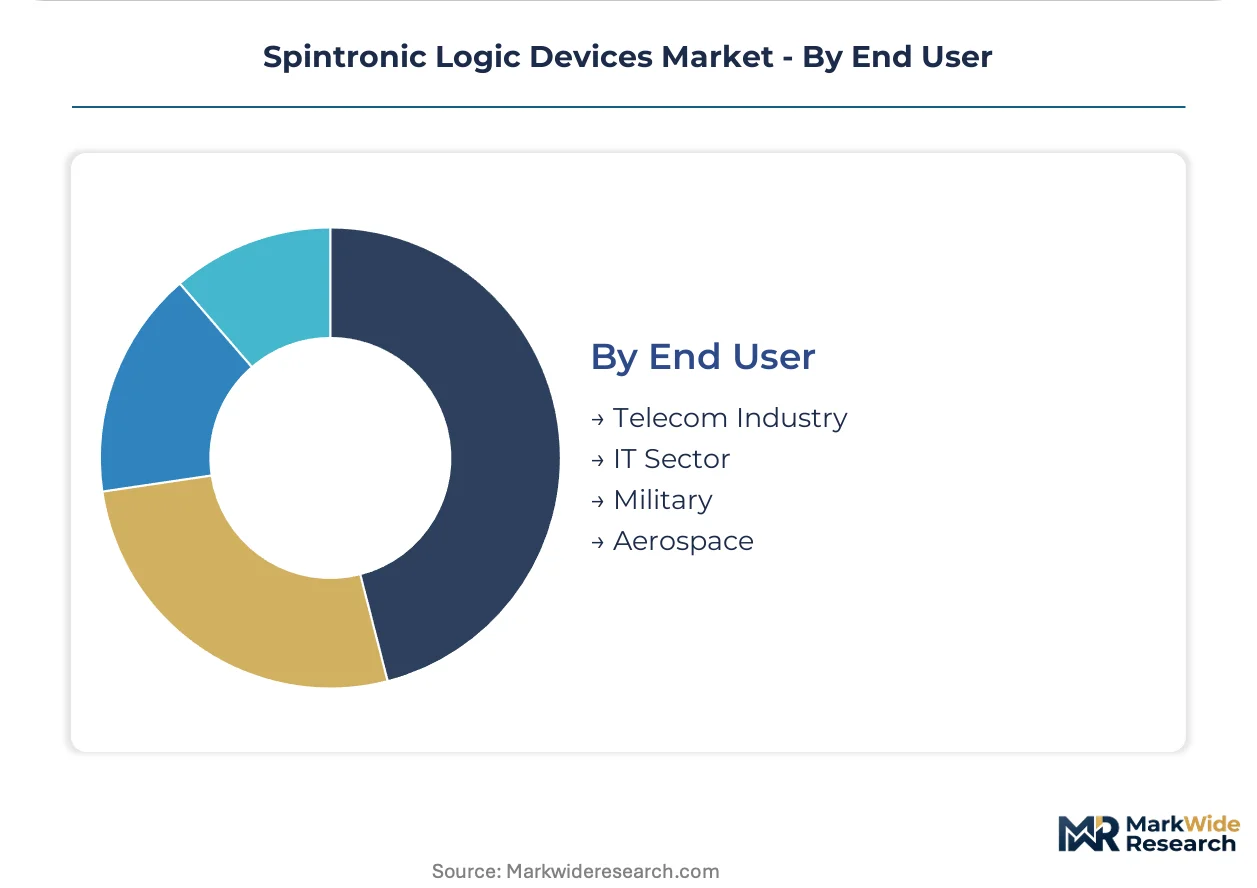
End User:
Customer type determines regulatory burden and procurement security clearance requirements.
- IT Sector:Cloud infrastructure operators drive specification evolution through direct foundry engagement, bypassing traditional component distribution channels.
- Telecom Industry:Equipment vendors face dual pressure from carbon intensity regulations and density constraints in Singapore and Amsterdam colocation markets.
- Military:Radiation hardness requirements favor spintronic intrinsic immunity to single-event upsets, though ITAR compliance restricts supplier pools.
- Aerospace:Satellite subsystem manufacturers prioritize non-volatile memory for configuration storage across power cycling events.
IT Sector procurement is expanding most quickly as vertical integration into custom silicon accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized magnetic device fabrication expertise concentrates in Germany, Japan, and the United States, with emerging process development activity in Taiwan and South Korea. National quantum computing initiatives and defense microelectronics programs anchor workforce development across these geographies.
United States
Hyperscale data center operators in Northern Virginia drive specification evolution for zero-standby-power logic architectures. FDA oversight of medical device data integrity creates procurement preference for non-volatile memory in implantable diagnostics. The Greater Boston corridor hosts concentrated spin-orbit torque research consortia bridging university laboratories with foundry pilot lines.
Germany
Automotive powertrain controller manufacturers seek AEC-Q100 qualified non-volatile alternatives to embedded flash. REACH compliance mandates from ECHA expand documentation burdens for magnetic material sourcing across European electronics supply chains. Industrial clusters in Bavaria anchor Infineon's spintronic R&D within established power semiconductor fabrication infrastructure.
Japan
Edge AI inference engine developers demand sub-nanosecond switching with femtojoule energy-per-bit performance. METI funding for post-CMOS computing architectures accelerates national laboratory consortia demonstrations. The Tohoku University corridor maintains concentrated academic-foundry collaboration on perpendicular magnetic tunnel junction process migration.
Taiwan
Foundry capacity allocation between legacy CMOS nodes and magnetic-compatible flows determines commercialization timelines for fabless design houses. The central bank's technology sector lending facilities support capital equipment procurement for atomic layer deposition chambers. Hsinchu Science Park clusters memory manufacturers piloting embedded non-volatile cache at 22nm nodes.
South Korea
Telecommunications equipment vendors face carbon intensity regulations and density constraints in Singapore and Amsterdam colocation markets. The national semiconductor support program under the Ministry of Trade, Industry and Energy prioritizes beyond-CMOS device architectures. Samsung and SK Hynix operations in Gyeonggi Province concentrate back-end metallization process development for hybrid spintronics integration.
Spintronic Logic Devices Market Competitive Landscape
The competitive structure tilts toward diversified semiconductor conglomerates with captive magnetic memory product lines. Foundry-dependent fabless design houses and specialized magnetic sensor fabricators occupy secondary tier positions. Two strategic archetypes dominate: integrated device manufacturers leveraging existing 300mm infrastructure, and technology licensors bridging research consortia with commercial qualification pathways. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure atomic layer deposition tool allocations.
Among United States-based memory specialists, Everspin Technologies Inc. and NVE Corporation occupy positions within the established non-volatile product tier. Infineon Technologies AG represents the integrated European conglomerate archetype, anchoring spintronic R&D within broader power semiconductor operations. Crocus Technology exemplifies the sensor-to-logic migration specialist, positioning foundry capabilities for downstream device qualification in magnetic sensing applications.
| Leading Market Players |
|---|
| Applied Spintronic Technology, Inc. |
| Infineon Technologies |
| Everspin Technologies Inc. |
| Futek Advanced Sensor Technology Inc. |
| Kistler Group |
| NVE Corporation |
| Spintec |
| PCB Piezotronics |
| Crocus Technology |
| Others |
Value Network & Pricing Analysis
Migration from magnetic sensor fabrication to logic-grade qualification is compressing development timelines while simultaneously concentrating cost economics in Taiwan and South Korean foundry clusters. Atomic layer deposition chamber scarcity feeds directly into wafer pricing power for qualified magnetic tunnel junction production.
Pricing Analysis
Foundry service bundling versus unbundled process development contracts splits pricing structures across the spintronic logic device landscape. Three-tier pricing structure across premium, standard, and economy levels reflects qualification status, with AEC-Q100 certification commanding substantial premiums over industrial-grade alternatives. Pricing pressure stems from hyperscale data center operators issuing functional specifications rather than pinout requirements, forcing margin compression in standardized product tiers. Fabless design houses exhibit highest price sensitivity due to captive foundry allocation competition, while defense subsystem integrators absorb premium pricing with minimal negotiation leverage.
Supply Chain Analysis
Regional distribution centers in Hsinchu Science Park and Gyeonggi Province anchor hub-and-spoke patterns for magnetic-compatible wafer outputs. Rare earth element processing in Chinese facilities, cobalt-iron-boron alloy production in Japanese industrial corridors, and magnesium oxide barrier precursor synthesis in German chemical clusters constitute critical input dependencies. Single-source vulnerability concentrates in atomic layer deposition equipment vendors with eighteen-month lead times. Distribution runs through direct foundry engagement channels that bypass traditional component distribution networks for qualified volume allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spintronic logic devices function as a stable compounder anchored by irreversible data center demand for zero-standby-power architectures. Infrastructure buildout in Northern Virginia and Singapore colocation markets sustains predictable volume trajectories.
For Market Incumbents: Deepen captive magnetic memory product lines to defend against spin-orbit torque device displacement from research consortium demonstrations. Prioritize atomic layer deposition tool allocation commitments in Taiwan and South Korean foundry partnerships. Invest in AEC-Q100 qualification pathways to capture automotive powertrain controller substitution demand before embedded flash alternatives mature.
For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in telecommunications edge node deployments creates accessible entry territory. Target FCC electromagnetic compatibility specification work for base station firmware storage applications. Pursue hybrid architecture services that bridge foundry process development with application-specific integration for fabless design houses in Austin and Munich corridors.
For Investors and Strategic Acquirers: Valuations sit cheapest among sensor-to-logic migration specialists with demonstrated foundry qualification capabilities. Five-to-ten year viability hinges on successful perpendicular magnetic tunnel junction process migration from laboratory to commercial production. Monitor foundry capacity allocation announcements between legacy CMOS nodes and magnetic-compatible flows as the critical inflection signal for volume scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Process Qualification | Secures wafer starts at 22nm nodes for embedded non-volatile cache production in Taiwan. |
| Atomic Layer Deposition Tool Allocation | Locks in sub-two-nanometer oxide barrier fabrication capacity from single-source equipment vendors. |
| AEC-Q100 Certification Pathway | Opens automotive powertrain controller and ADAS subsystem procurement channels in Germany. |
| Hybrid Architecture Service Development | Captures margin pools at the interface between mature CMOS nodes and magnetic back-end processing. |
| REACH Compliance Documentation | Maintains European electronics supply chain access under ECHA hazardous substance mandates. |
Research Methodology
Direct dialogue with foundry process engineers, fabless design house technical leads, magnetic memory product managers, and hyperscale data center procurement officers grounded qualitative assessment. Secondary validation drew from SEC semiconductor capex disclosures, ECHA REACH registration databases, FDA medical device filings, and foundry equipment utilization reports. Bottom-up and top-down triangulation reconciled wafer start projections with end-use demand aggregation.
Bottom-up volume modeling segmented across product type, technology tier, application vertical, and end-user category throughout the forecast period. Perpendicular magnetic tunnel junction adoption curves, spin-orbit torque device research milestone timelines, and foundry capacity allocation shifts between legacy CMOS and magnetic-compatible nodes informed growth trajectory derivation. CAGRs reflect installed base substitution dynamics for SRAM in data center cache hierarchies and embedded flash in automotive controllers.
Caveats apply where foundry capacity reallocation decisions, rare earth export restriction implementations, or spin-orbit torque device technical milestone failures could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market