
 Silicon-Based Anode Market | 2026-2036
Silicon-Based Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon-Based Anode Market Analytics
China's GB standards for battery cell safety is pivoting the cost-of-entry calculus for anode suppliers seeking to serve domestic EV OEMs. Amprius Technologies leverages its proprietary silicon nanowire architecture to sustain manufacturing scale in Fremont, California. Sila Nanotechnologies anchors its position through in-house production of nano-composite silicon particles, while Group14 Technologies differentiates via its silicon-carbon composite platform developed in Woodinville, Washington.
Silicon-based anodes are lithium-ion battery electrodes incorporating silicon as the primary active material, typically alloyed with carbon or structured as porous composites to accommodate volume expansion exceeding 300% during lithiation; they deliver specific capacities above 3,500 mAh/g versus 372 mAh/g for conventional graphite, enabling extended driving ranges in electric vehicles. Composite anodes currently lead commercial shipments because their carbon matrix mitigates pulverization during charge cycles. Electric vehicle applications command the deepest margin pools as OEMs negotiate multi-year supply agreements with performance-linked pricing.
The EU's Battery Regulation and ECHA's REACH framework impose stringent due diligence on carbon intensity and material sourcing, compelling anode producers to document supply chain provenance. China's SAMR enforces GB standards that mandate thermal runaway propagation resistance, directly influencing silicon anode binder and electrolyte compatibility requirements. Japan's METI coordinates national R&D consortia targeting solid-state battery integration with silicon-dominant anodes. Stakeholders must monitor how solid-state battery technology matures, as this transition could render current liquid-electrolyte silicon anode formulations obsolete or create entirely new qualification pathways.
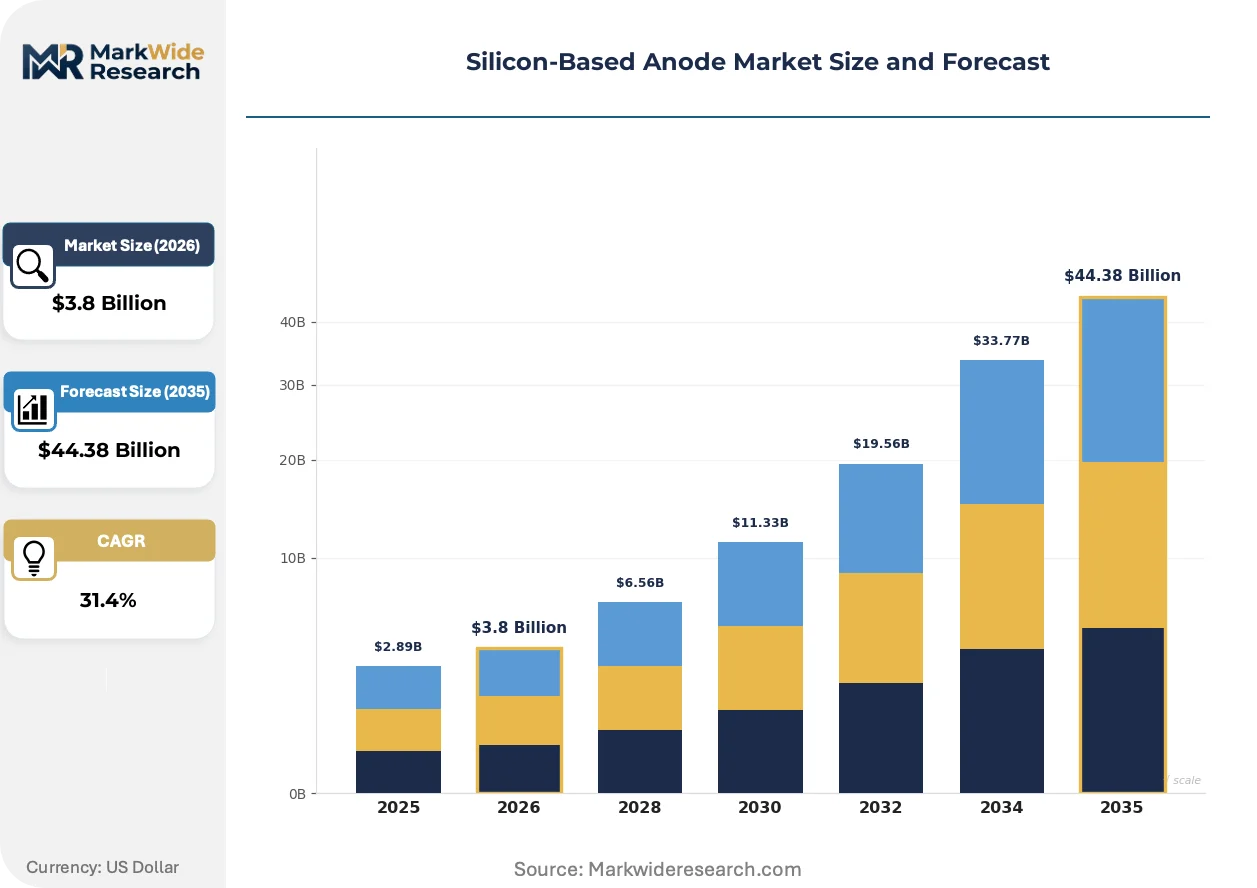
Market Dynamics
Volume procurement of silicon-dominant anodes is concentrating around South Korea's Gwangyang-Pohang battery cluster as cell OEMs lock in multi-year supply agreements tied to energy density milestones.
Growth Catalysts
- EU Battery Regulation carbon-footprint mandates:Tier-1 anode suppliers must document supply chain provenance, creating first-mover advantage for producers with verified low-carbon production routes.
- China's dual carbon goals:Domestic EV OEMs accelerate qualification of silicon-carbon composites to meet GB standards for thermal runaway resistance while reducing cell-level emissions.
- Solid-state battery integration:METI-coordinated R&D consortia in Japan are validating silicon-dominant anode compatibility with sulfide-based electrolytes, opening qualification pathways for next-generation cell architectures.
Market Restraints
- Silicon feedstock price volatility:Metallurgical-grade silicon prices fluctuate with solar PV demand cycles, compressing anode producer margins during polysilicon capacity expansions.
- Single-source binder dependency:Polyacrylic acid supply concentrates among three specialty chemical producers in Germany and Japan, creating input vulnerability for composite anode scaling.
- Graphite cost-performance floor:Synthetic graphite from China's Shandong province sustains sub-$10/kg pricing, anchoring incumbent anode economics against silicon premium positioning.
Strategic Opportunities
- US Inflation Reduction Act clean vehicle credits:Domestic content requirements for battery components create procurement pull for North American silicon anode production.
- India PLI scheme for ACC batteries:Cell manufacturing incentives are attracting anode material suppliers to Gujarat and Tamil Nadu industrial corridors ahead of localized EV production scale-up.
- Silicon nanowire-solid electrolyte convergence:Interface engineering breakthroughs are enabling dry electrode processing that eliminates solvent-based coating capex.
Industry Challenges
- Electrochemical engineer scarcity:Silicon anode development requires rare expertise in solid-electrolyte interphase modeling, with talent concentrated among a handful of national laboratory and university programs.
- Cell OEM qualification timelines:Automotive battery validation protocols demand 24-36 month cycle testing, freezing formulation iterations and delaying revenue recognition.
- Pre-lithiation IP thickets:Patent estates covering stabilized lithium metal powder integration span multiple assignees, complicating freedom-to-operate for composite anode architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon-Based Anode Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Anodes, Pure Silicon Anodes, Silicon Oxide Anodes, Silicon Alloy Anodes End User: Electric Vehicle Manufacturers, Consumer Electronics, Energy Storage Systems, Aerospace Applications Technology: Lithium-Ion Batteries, Solid-State Batteries, Hybrid Batteries, Flow Batteries Application: Grid Storage, Portable Electronics, Electric Vehicles, Industrial Applications |
| Companies Covered | Amprius Technologies, Sila Nanotechnologies, Group14 Technologies, Nexeon Limited, Enevate Corporation, Enovix Corporation, NanoGraf Corporation, XG Sciences, OneD Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon-Based Anode Market Evolving Landscape
Silicon anode technology is bifurcating between incremental composite formulations for near-term EV deployment and disruptive nanostructured architectures targeting solid-state integration.
Porous silicon-carbon composites are consolidating as the dominant commercial platform. Automotive cell producers specify these materials for 2025-2027 model year platforms. The technology is compressing qualification timelines by leveraging existing graphite electrode manufacturing infrastructure.
REACH substance restrictions on fluorinated binders are forcing reformulation of silicon anode electrolyte systems. ECHA's 2023 PFAS restriction proposals directly impact polyvinylidene fluoride usage. European anode suppliers are accelerating waterborne binder validation to maintain market access.
Long-term supply agreements are displacing spot market purchasing for silicon anode materials. Korean cell producers now contract directly with silicon feedstock refiners, bypassing traditional trading houses. This pattern is most visible in binding arrangements between Gwangyang-based cathode-anode clusters and Qinghai polysilicon producers.
Silicon-Based Anode Market Segmentation
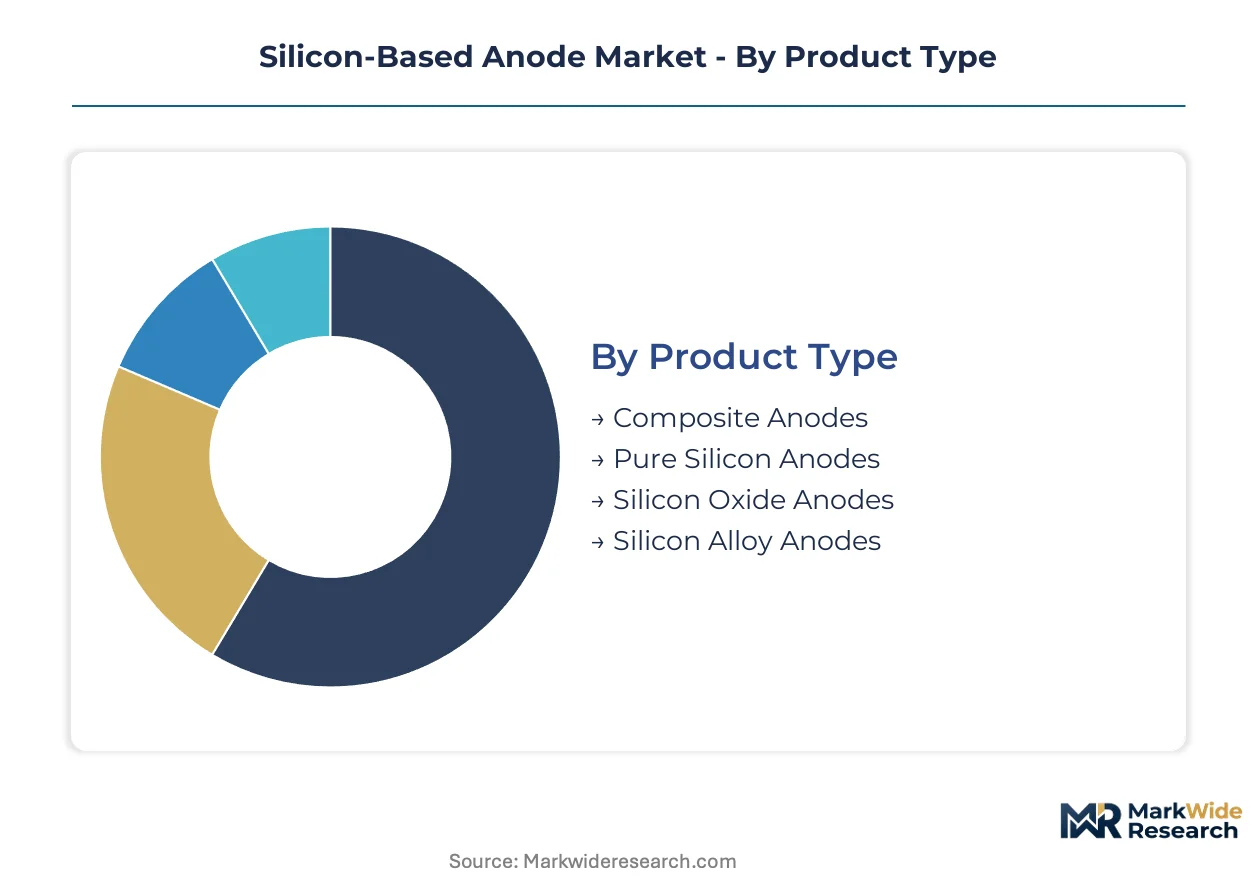
Silicon-based anode procurement patterns diverge sharply across product architectures and end-use specifications. Automotive qualification protocols impose distinct certification burdens that reshape segment prioritization for material suppliers.
Product Type:
Composite Anodes carry GB standard thermal runaway certification requirements for China-bound EV supply chains, while Pure Silicon Anodes face extended NHTSA validation cycles for US automotive integration.
- Composite Anodes:Carbon matrix structures accommodating silicon volume expansion through porous architectures. Electric vehicle manufacturers in South Korea's Gwangyang-Pohang cluster specify these materials for 2025-2027 platform launches, leveraging existing graphite electrode coating infrastructure to compress qualification timelines.
- Pure Silicon Anodes:High-capacity formulations exceeding 3,500 mAh/g specific capacity with minimal carbon dilution. Silicon nanowire architectures from Fremont, California production lines target solid-state battery integration where sulfide electrolyte compatibility reduces interface engineering burdens.
- Silicon Oxide Anodes:SiO-based composites offering intermediate capacity retention with reduced first-cycle losses.
- Silicon Alloy Anodes:Metallurgical blends with tin or aluminum for mechanical stress distribution.
Composite Anodes sits at the top of the volume ranking, with Pure Silicon Anodes climbing the fastest.
End User:
Customer concentration patterns split between long-cycle automotive contracts and high-margin aerospace specifications with discrete procurement volumes.
- Electric Vehicle Manufacturers:Multi-year supply agreements tied to energy density milestones dominate procurement. Cell OEMs in South Korea and China lock in silicon-carbon composite volumes through direct feedstock refiner arrangements, bypassing spot market intermediaries.
- Consumer Electronics:Smartphone and laptop producers specify silicon-dominant anodes for premium device segments where cycle life requirements remain below automotive thresholds.
- Energy Storage Systems:Grid-scale battery integrators prioritize cost-per-kWh metrics over energy density maximization.
- Aerospace Applications:Satellite and aviation battery systems demand extreme gravimetric energy density with radiation-hardened specifications.
Electric Vehicle Manufacturers commands the deepest margin pools, with Aerospace Applications expanding most quickly on a percentage basis.
Technology:
Electrolyte chemistry determines silicon anode formulation compatibility and manufacturing process requirements.
- Lithium-Ion Batteries:Liquid electrolyte systems with established polyacrylic acid binder supply chains. ECHA REACH PFAS restrictions are forcing waterborne binder reformulation among European anode suppliers to maintain market access.
- Solid-State Batteries:Sulfide and oxide electrolyte architectures eliminating dendrite formation risks. METI-coordinated Japanese R&D consortia validate silicon-dominant anode compatibility with dry electrode processing that eliminates solvent-based coating capital expenditure.
- Hybrid Batteries:Mixed electrolyte systems combining liquid ionic conductivity with solid-state safety features.
- Flow Batteries:Redox-active silicon suspensions for stationary storage with decoupled power-energy scaling.
Lithium-Ion Batteries retains dominant shipment volumes, with Solid-State Batteries gaining share fastest through METI-funded qualification pathways.
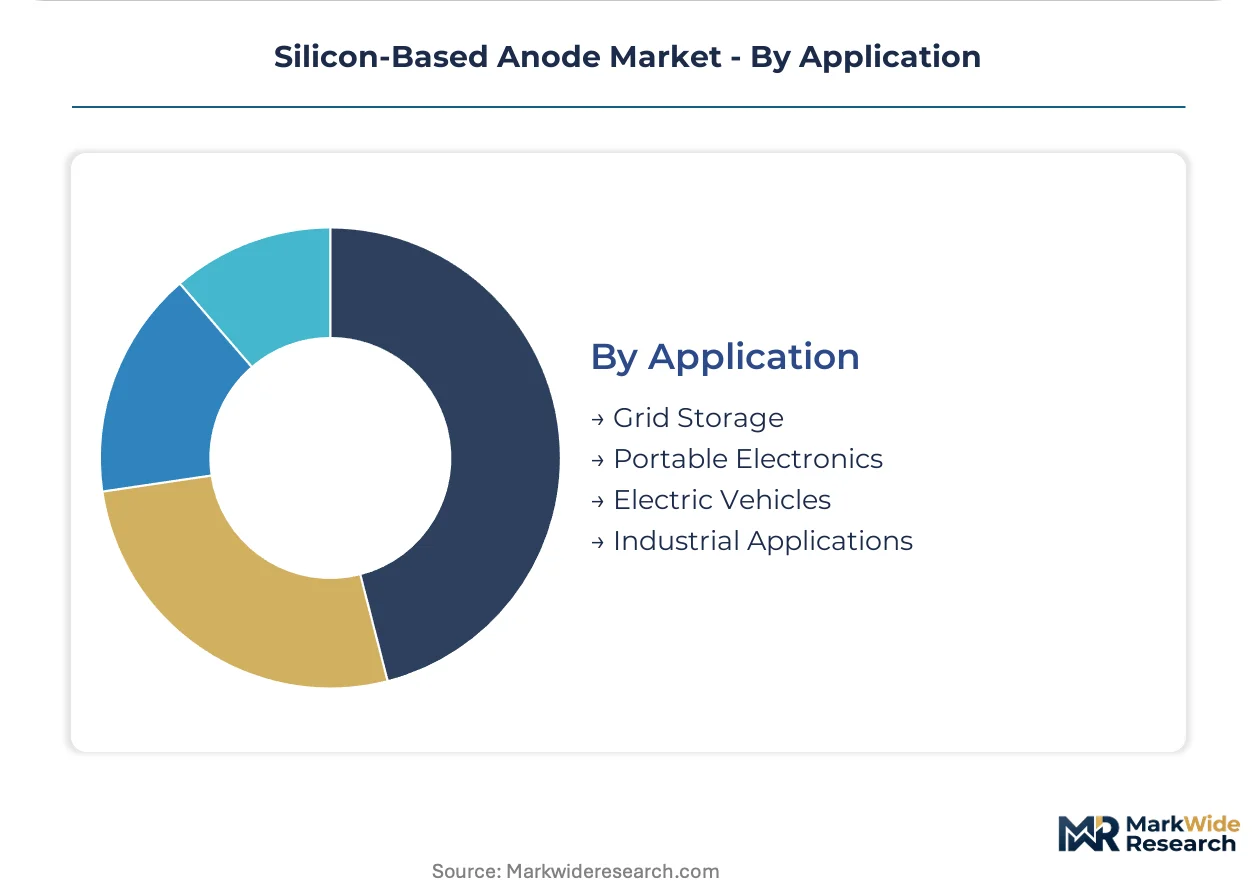
Application:
Deployment context dictates performance specifications and regulatory exposure for silicon anode integration.
- Electric Vehicles:Extended range requirements drive silicon-dominant anode penetration in premium battery pack configurations. US Inflation Reduction Act domestic content provisions create procurement pull for North American anode production serving Detroit and Fremont assembly operations.
- Portable Electronics:Volume-constrained devices prioritize volumetric energy density over gravimetric metrics.
- Grid Storage:Cycle life and capital cost optimization favor lower-silicon-content composite formulations.
- Industrial Applications:Forklift and mining equipment batteries with opportunity charging protocols.
Electric Vehicles leads absolute consumption, with Portable Electronics showing the steepest expansion trajectory as foldable device form factors proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon-based anode manufacturing originated in Japanese electronics corridors during the 1990s lithium-ion commercialization wave, then migrated to Chinese materials hubs as EV demand scaled. Today's production geography reflects this dual heritage: established Japanese R&D infrastructure alongside Chinese volume manufacturing and emerging North American capacity.
China
Domestic EV OEMs at BYD and CATL drive silicon-carbon composite procurement to meet SAMR-enforced GB standards for thermal runaway resistance. The dual carbon goals mandate cell-level emissions disclosure, compelling anode producers to document supply chain provenance through MEE carbon accounting frameworks. Qinghai polysilicon refiners now contract directly with Gwangyang-based Korean cell clusters, bypassing traditional trading intermediaries.
South Korea
LG Energy Solution and Samsung SDI anchor multi-year supply agreements tied to energy density milestones above 300 Wh/kg. MFDS battery safety certifications impose electrolyte compatibility requirements that reshape silicon anode binder selection. The Gwangyang-Pohang cathode-anode cluster concentrates volume procurement, with POSCO Chemical expanding silicon-carbon composite capacity to serve 2025-2027 automotive platform launches.
United States
IRA clean vehicle credits create procurement pull for domestic anode production serving Detroit and Fremont assembly operations. NHTSA validation cycles for pure silicon anode formulations extend 24-36 months, freezing formulation iterations for automotive qualification. Amprius Technologies maintains silicon nanowire production in Fremont, California, targeting solid-state battery integration pathways.
Japan
Panasonic and Toyota accelerate silicon-dominant anode development for solid-state battery timelines. METI-coordinated R&D consortia validate sulfide electrolyte compatibility with nano-structured silicon architectures, opening qualification pathways for 2028-2030 cell commercialization. Nagoya-based materials suppliers concentrate dry electrode process engineering expertise.
Germany
BMW and Volkswagen negotiate performance-linked pricing for silicon-carbon composites in premium EV platforms. ECHA REACH PFAS restrictions force waterborne binder reformulation, eliminating polyvinylidene fluoride from European anode supply chains. BASF and specialty chemical producers in Ludwigshafen control polyacrylic acid supply, creating input concentration for composite anode scaling.
Silicon-Based Anode Market Competitive Landscape
The competitive structure tilts toward technology-differentiated specialists rather than diversified materials conglomerates. Three to five venture-backed firms control proprietary architectures, while established chemical giants supply feedstock and binders without direct anode competition. Two strategic archetypes dominate: nanostructured silicon developers pursuing solid-state integration, and composite formulators leveraging existing graphite infrastructure. Capacity expansion and strategic partnerships with cell OEMs constitute the primary competitive moves, with qualification timelines acting as the decisive barrier to entry.
Among North American technology developers, Amprius Technologies, Sila Nanotechnologies, and Group14 Technologies occupy distinct positioning within the silicon anode landscape. Amprius exemplifies the nanowire architecture specialist targeting aerospace and solid-state pathways. Sila represents the nano-composite particle approach with in-house production capabilities. Group14 anchors the silicon-carbon composite platform segment developed in Washington State. These three firms illustrate the technology bifurcation between incremental composite formulations and disruptive nanostructured architectures.
| Leading Market Players |
|---|
| Amprius Technologies |
| Sila Nanotechnologies |
| Group14 Technologies |
| Nexeon Limited |
| Enevate Corporation |
| Enovix Corporation |
| NanoGraf Corporation |
| XG Sciences |
| OneD Material |
| Others |
Value Network & Pricing Analysis
Venture-backed technology specialists concentrated in California and Washington State anchor supply-side ownership patterns, enabling pricing discipline through proprietary architectures that resist commoditization. Long-term offtake agreements between Korean cell OEMs and Qinghai polysilicon refiners now displace spot market intermediaries, compressing margin capture for trading houses while securing volume commitments for anode producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs silicon anode procurement, with automotive qualification grade and volume scale as the primary differentiation drivers. Cost compression in standard-grade composites is intensifying because synthetic graphite from Shandong province sustains sub-$10/kg pricing, anchoring incumbent economics. Energy storage system integrators exhibit the highest price sensitivity due to cost-per-kWh optimization mandates, while aerospace battery producers accept premium positioning for radiation-hardened specifications.
Supply Chain Analysis
Polyacrylic acid binder supply rests on specialty chemical producers concentrated in Germany and Japan, creating single-source vulnerability for composite anode scaling. Metallurgical-grade silicon feedstock draws from Qinghai polysilicon refiners and solar PV capacity cycles, while carbon matrix precursors source from petroleum coke processors in China and the United States. Tariff exposure on Chinese anode materials threatens cost structures for North American cell producers. Distribution runs through direct refiner-to-OEM contracts that bypass traditional chemical trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicon-based anode market reads as a late-cycle quality story where procurement is shifting toward premium-grade composites certified for GB standard thermal runaway resistance. Electric vehicle OEMs now specify silicon-dominant materials for extended-range platforms, elevating qualification grade over unit cost in supplier selection.
For Market Incumbents: Cement proprietary binder formulations and electrolyte compatibility IP to defend against waterborne reformulation mandates under ECHA REACH restrictions. Deepen upstream control over Qinghai polysilicon supply through captive offtake structures, locking in feedstock cost visibility against solar PV demand cycles. For New Entrants and Emerging Players: Tier 2 Korean cell producers represent the most penetrable channel partner type for qualification-fast-track partnerships outside the Gwangyang-Pohang cluster concentration. Target India's Gujarat and Tamil Nadu industrial corridors ahead of localized ACC battery manufacturing scale-up under the PLI scheme, leveraging performance-linked pricing models to bypass incumbent volume commitments. For Investors and Strategic Acquirers: Valuations sit cheapest among nano-composite particle specialists with in-house production capabilities but unproven automotive qualification timelines. The five-to-ten-year viability window favors acquisition targets holding dry electrode process patents for solid-state integration pathways. Watch for METI consortium disclosure of sulfide electrolyte compatibility breakthroughs as the inflection signal triggering strategic buyer competition.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Korean cell OEMs lock in Qinghai polysilicon volumes through direct refiner contracts, bypassing trading intermediaries. |
| Backward Integration | Anode producers secure captive polyacrylic acid supply from Ludwigshafen specialty chemical producers to mitigate input concentration risk. |
| Capacity Expansion | POSCO Chemical scales silicon-carbon composite output in Gwangyang to serve 2025-2027 automotive platform launches. |
| Technology Licensing | Sila Nanotechnologies licenses nano-composite particle production to Indian anode suppliers under PLI scheme localization requirements. |
| Joint Venture | Amprius Technologies partners with sulfide electrolyte developers to validate silicon nanowire-solid-state battery integration pathways. |
Research Methodology
Direct dialogue with cell OEM procurement directors, anode producer technical R&D leads, specialty chemical supply managers, and EV platform engineers grounded this analysis in operational reality. Secondary validation drew from SAMR GB standard filings, ECHA REACH restriction proposals, METI R&D consortium disclosures, Korean customs trade data, and SEC 10-K filings from listed battery material suppliers. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity announcements and automotive platform launch schedules.
Bottom-up modeling segmented the market by product architecture, end-use qualification grade, electrolyte chemistry compatibility, and regional regulatory cluster. Top-down validation anchored aggregate demand to electric vehicle production forecasts and battery pack energy density roadmaps across the projection horizon. CAGRs derived from weighted average of historical capacity expansion rates and OEM procurement commitment trajectories, with silicon feedstock price volatility and qualification timeline delays as key sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery commercialization timelines and ECHA PFAS restriction enforcement severity. Forecasts reflect assumptions about automotive qualification protocol stability and Korean-Chinese feedstock trade flow continuity. A small set of named triggers—METI sulfide compatibility validation, IRA domestic content rule refinement, and Indian PLI scheme beneficiary announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Asia-Pacific MLCC Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Spintronic Logic Devices Market