
 Semiconductor Market | 2026-2036
Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Market Intelligence
Direct semiconductor procurement from cloud hyperscalers is reconfiguring how foundries allocate wafer starts and negotiate long-term supply agreements. TSMC leverages captive capacity commitments from its largest customers to sustain pricing power across advanced nodes. Samsung Electronics anchors memory supply through vertical control of DRAM and NAND fabrication. Intel competes for foundry market share by positioning its IDM 2.0 model as a geographically diversified alternative.
Semiconductors are solid-state electronic devices fabricated from silicon, gallium arsenide, or compound substrates, engineered to control electron flow through integrated circuits with feature sizes now measured in angstroms for the most advanced processors. Their primary purpose spans computation, data storage, signal processing, and power conversion across virtually all electronic systems. Logic chips dominate value capture at the leading edge where FinFET and emerging gate-all-around architectures command premium pricing. Memory chips operate through pronounced cyclicality with supply adjustments from SK Hynix and Micron Technology determining industry profitability. Analog chips and sensors occupy stable margin pools in automotive and industrial applications where qualification timelines create defensive moats.
The EPA regulates hazardous substance reporting for U.S. fabrication facilities, while REACH and RoHS constrain material composition across European supply chains. China's GB standards and MIIT directives shape local procurement and import substitution trajectories for domestic chip consumption. Stakeholders must monitor how export control alignments between the U.S. Commerce Department and allied regulators fragment equipment and materials access across competing manufacturing zones.
Market Dynamics
Automotive electrification and AI compute expansion are pulling wafer allocation away from consumer electronics toward power management and high-performance logic, forcing foundries to renegotiate long-term capacity contracts with tier-one automotive suppliers.
Growth Catalysts
- EU Chips Act capital subsidies:Germany and France are attracting greenfield fab investments through direct state aid, accelerating 300mm capacity expansion for automotive-grade chips.
- Gate-all-around transistor architecture:This nanosheet design enables continued power-performance scaling at 2nm nodes, sustaining premium pricing for advanced logic foundry services.
- Sensor fusion demand from ADAS:Tier-1 automotive suppliers are procuring multi-die chiplets for lidar and camera processing, expanding addressable silicon content per vehicle.
Market Restraints
- Extreme ultraviolet lithography equipment concentration:ASML's monopoly on EUV systems creates single-source dependency for nodes below 7nm, constraining foundry expansion timelines.
- Neon gas supply vulnerability:Ukrainian purification facilities supply critical laser gases for deep-UV lithography, exposing fabs to geopolitical supply interruptions.
- REACH substance restrictions:ECHA constraints on per- and polyfluoroalkyl substances limit wet chemistry options for advanced etching processes in European facilities.
Strategic Opportunities
- India's semiconductor PLI scheme:Gujarat and Karnataka are offering capital expenditure rebates for display and chip assembly facilities, attracting first-mover packaging investments.
- Photonic-electronic monolithic integration:Silicon photonics convergence with CMOS logic enables co-packaged optics for datacenter interconnects, opening new process development vectors.
- Direct foundry relationships from cloud hyperscalers:Amazon Web Services and Microsoft Azure are bypassing traditional distributors to secure dedicated wafer starts at TSMC and Samsung.
Industry Challenges
- Process engineer talent scarcity:Atomic-layer deposition and epitaxy specialists command premium compensation, constraining R&D velocity at emerging foundries.
- Automotive AEC-Q100 qualification timelines:Zero-defect reliability testing extends product introduction cycles to 18-24 months, compressing revenue recognition windows.
- Legacy node equipment obsolescence:200mm tool refurbishment costs exceed new 300mm equipment economics, stranding capacity for mature analog and power devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Market |
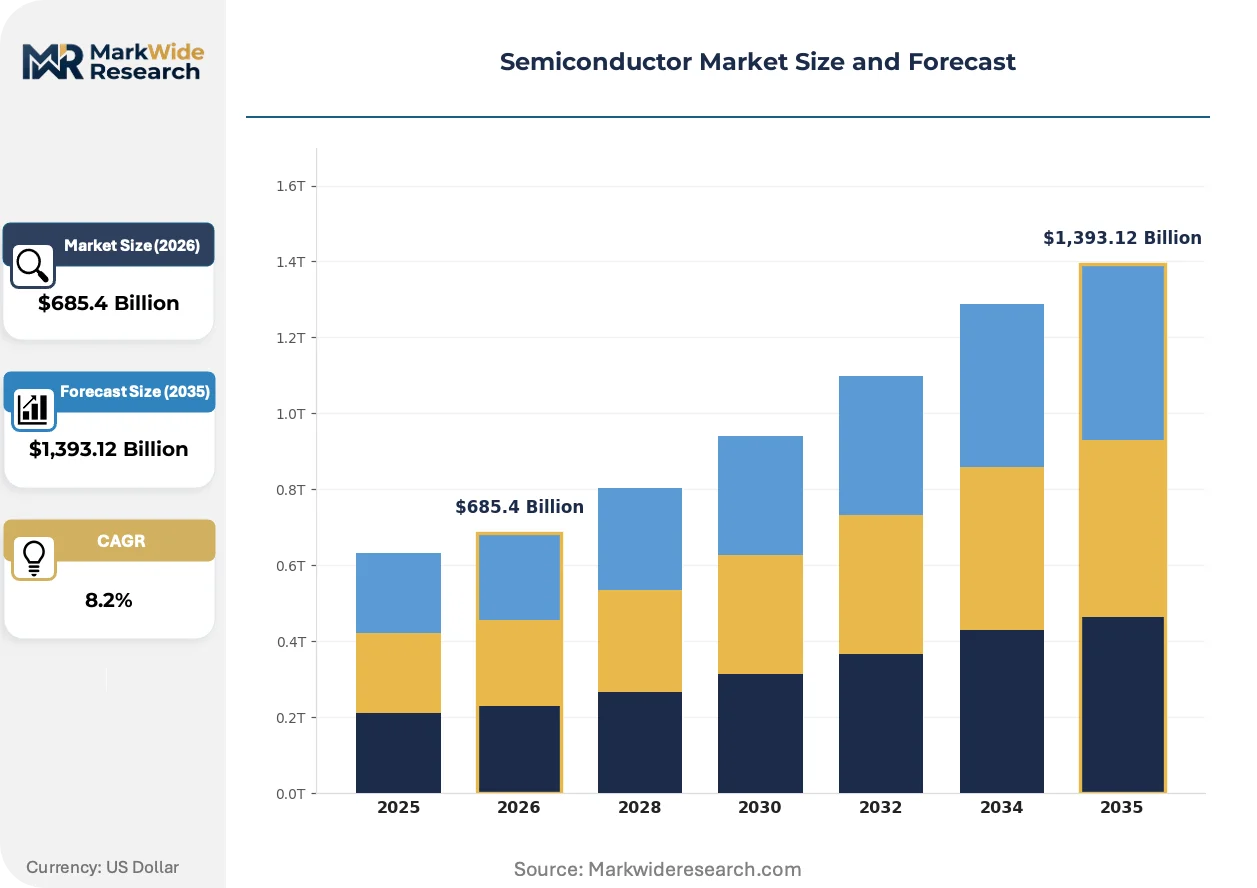
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,393.12 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Logic Chips, Memory Chips, Analog Chips, Microcontrollers, Sensors Technology: CMOS, FinFET, SOI, Bipolar, Gallium Nitride Application: Consumer Electronics, Data Centers, Telecommunications, Aerospace, Industrial Equipment End User: OEMs, Electronic Manufacturing Services, Fabless Companies, Foundries, System Integrators |
| Companies Covered | Intel, Samsung Electronics, NVIDIA, QUALCOMM, SK Hynix, TSMC, AMD, Micron Technology, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Market Strategic Shifts & Innovations
Chiplet-based disaggregation is virtualizing traditional monolithic processor design, enabling heterogeneous integration across process nodes and foundry sources while compressing time-to-market for complex SoCs.
Gate-all-around nanosheet transistors are virtualizing FinFET scaling limitations by enabling tighter electrostatic control at atomic dimensions. Apple and NVIDIA are adopting these architectures for mobile and datacenter accelerators. This transition is compressing design-rule complexity into standardized tile interfaces, accelerating foundry process migration.
EPA hazardous substance reporting under TSCA Section 8(a) is tightening disclosure requirements for perfluorinated compounds used in etching and cleaning processes. Fabrication facilities must now quantify fugitive emissions of PFAS precursors. Memory manufacturers in the United States are accelerating dry process chemistry substitution to preempt enforcement actions.
Hyperscaler direct procurement is displacing traditional component distribution for advanced logic and memory. Amazon, Google, and Microsoft negotiate multi-year wafer commitments directly with TSMC and Samsung, bypassing Broadcom and Marvell in some socket categories. This pattern concentrates most visibly in North American cloud infrastructure deployment.
Semiconductor Market Segmentation
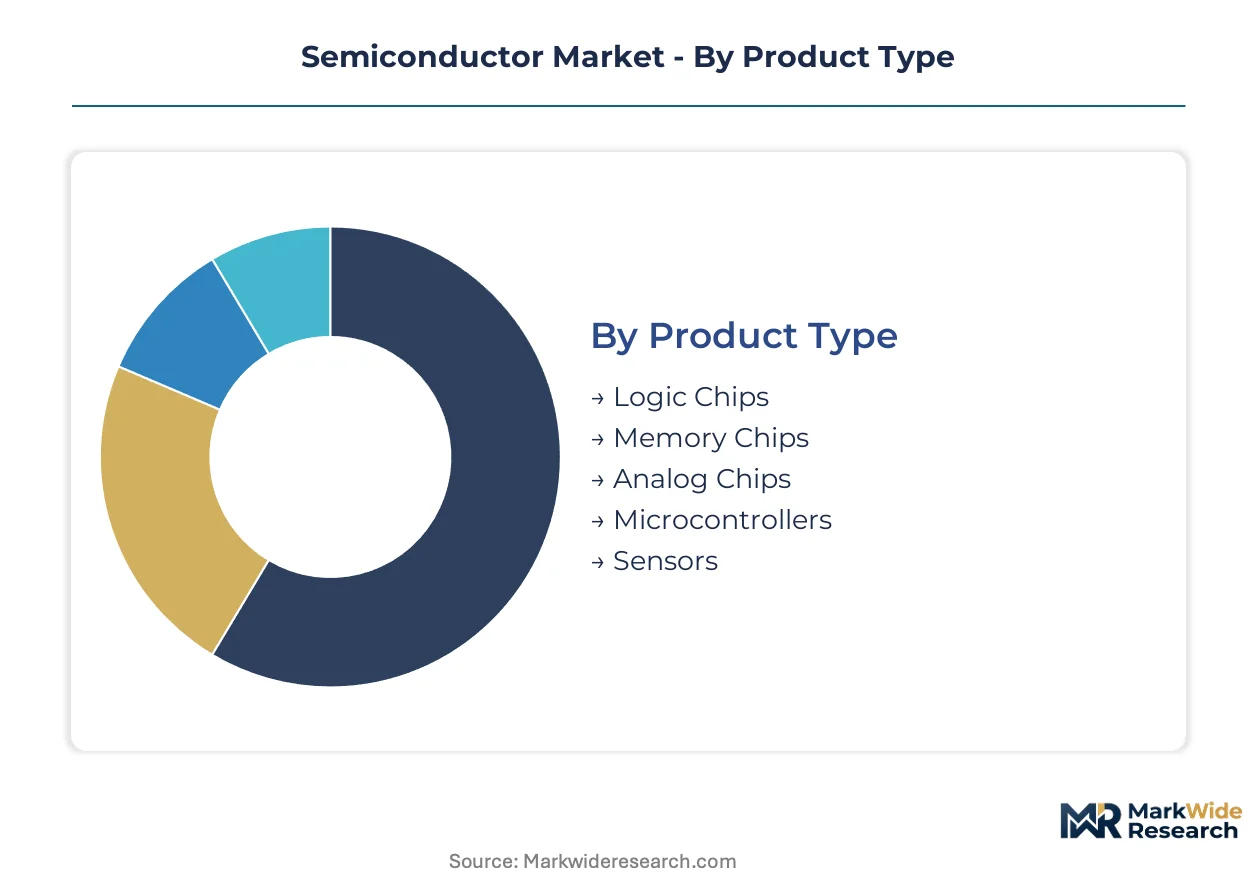
Semiconductor segmentation reveals how fabrication economics and end-use requirements fragment supply chains. Each dimension—product architecture, process technology, application workload, and customer integration model—creates distinct margin pools and capacity allocation priorities.
Product Type:
Use-case spectrum spans high-volume computation engines to specialized sensing elements, each demanding unique process nodes and qualification protocols.
- Logic Chips:Processors and system-on-chip devices fabricated at the leading edge, currently transitioning from FinFET to gate-all-around architectures. Datacenter AI accelerators from NVIDIA and Google concentrate demand for TSMC's most advanced nodes, tightening wafer allocation and sustaining premium pricing.
- Memory Chips:DRAM and NAND flash storage devices operating through pronounced supply cycles. SK Hynix and Micron adjust bit output to manage inventory absorption, with high-bandwidth memory stacks gaining share in AI training clusters.
- Analog Chips:Power management and signal conditioning circuits using mature nodes. Automotive AEC-Q100 qualification requirements extend design-in cycles, creating defensive margin pools.
- Microcontrollers:Embedded control units integrating processor cores with peripheral interfaces. Industrial automation and automotive body electronics anchor procurement volumes.
- Sensors:Image, motion, and environmental sensing devices combining MEMS structures with CMOS readout circuits. Lidar and camera fusion for ADAS expands silicon content per vehicle.
Established volume favors Memory Chips; emerging adoption favors Sensors.
Technology:
Cost tier stratification separates commodity production from leading-edge development, with each architecture commanding distinct equipment depreciation schedules.
- CMOS:Complementary metal-oxide-semiconductor remains the foundational process for digital logic and mixed-signal integration. Taiwan and South Korea concentrate the most advanced CMOS fabrication capacity.
- FinFET:Three-dimensional transistor architecture enabling continued scaling at 7nm and 5nm nodes. Apple and AMD processors anchor demand before the transition to nanosheet structures.
- SOI:Silicon-on-insulator substrates reduce parasitic capacitance for RF and low-power applications. European foundries specialize in SOI for automotive radar and 5G infrastructure.
- Bipolar:Traditional junction transistor technology for high-voltage and high-frequency analog circuits. Power amplifiers and voltage regulators sustain niche demand.
- Gallium Nitride:Wide-bandgap compound semiconductor for power conversion and RF amplification. Electric vehicle onboard chargers and 5G base stations accelerate adoption.
CMOS captures dominant investment; Gallium Nitride climbs the fastest.
Application:
Customer type fragmentation separates high-volume consumer procurement from mission-critical industrial qualification requirements.
- Consumer Electronics:Smartphones, PCs, and wearables driving historical volume concentration. Demand cyclicality forces foundries to maintain flexible capacity buffers.
- Data Centers:Cloud computing infrastructure and AI training clusters. Hyperscaler direct procurement bypasses traditional distribution channels.
- Telecommunications:Baseband processors, RF front-ends, and optical transceivers. 5G deployment cycles and Open RAN architectures reshape component sourcing.
- Aerospace:Radiation-hardened and high-reliability components for satellites and defense systems. Extended qualification timelines and dual-source requirements sustain specialized foundries.
- Industrial Equipment:Programmable logic controllers, motor drives, and factory automation controllers. Long product lifecycles create demand for mature node continuity.
Data Centers command fastest capacity expansion; Industrial Equipment provides steadiest procurement visibility.
End User:
Supply concentration varies dramatically across integration models, from captive fabrication to pure-play outsourcing arrangements.
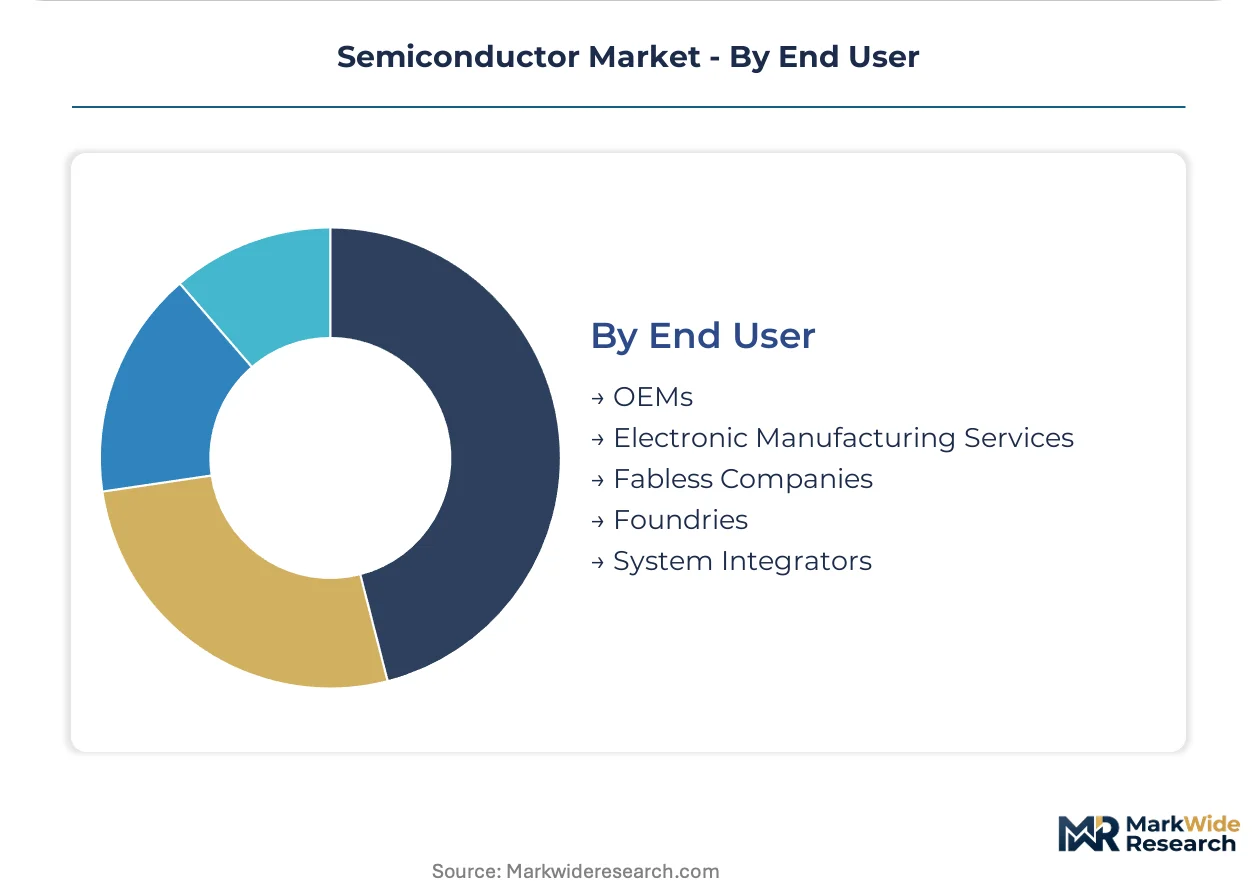
- OEMs:Original equipment manufacturers with internal semiconductor design teams. Apple and Tesla develop proprietary silicon while contracting fabrication.
- Electronic Manufacturing Services:Contract assemblers managing component procurement and board integration. Foxconn and Jabil consolidate purchasing leverage.
- Fabless Companies:Design houses without fabrication assets. Qualcomm and Broadcom negotiate wafer commitments at leading foundries.
- Foundries:Pure-play manufacturers offering process technology to external customers. TSMC and GlobalFoundries compete on node availability and geographic diversification.
- System Integrators:Solution providers combining hardware, software, and services. Defense and telecommunications integrators impose stringent supply chain traceability requirements.
Fabless Companies concentrate design innovation; Foundries capture manufacturing value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan commands unmatched pricing power at the leading edge, while the United States and Germany subsidize greenfield capacity to erode that advantage. Foundry economics fragment across three regulatory zones with divergent subsidy intensity and equipment access protocols.
United States
Arizona and Texas attract TSMC and Samsung greenfield investments through CHIPS Act disbursements. EPA hazardous substance reporting under TSCA Section 8(a) tightens PFAS disclosure for etching chemistry. Intel anchors IDM 2.0 expansion in Oregon and Ohio while negotiating foundry service contracts with external customers.
Taiwan
Hsinchu Science Park concentrates the densest leading-edge foundry output globally. The National Science and Technology Council coordinates industrial policy without direct subsidy matching. Tainan hosts TSMC's most advanced nanosheet ramp while Taichung expands specialty node capacity for automotive qualification.
Germany
Dresden's Silicon Saxony cluster anchors European logic and memory packaging investments. EU Chips Act state aid approvals accelerate 300mm cleanroom construction. Bavaria attracts equipment supplier headquarters while federal KfW development loans supplement regional matching funds.
South Korea
Pyeongtaek and Yongin host Samsung's DRAM and foundry expansion responding to AI accelerator demand. METI-aligned tax credits support R&D depreciation for gate-all-around process development. SK Hynix concentrates high-bandwidth memory output in Icheon for hyperscaler procurement.
Japan
Kumamoto hosts TSMC-Japan Advanced Semiconductor Manufacturing joint ventures for mature node security. METI's semiconductor revitalization fund subsidizes Rapidus 2nm pilot line construction in Hokkaido. Kyoto equipment suppliers concentrate lithography component fabrication.
Semiconductor Market Key Industry Players
Integrated device manufacturers and pure-play foundries split the market along captive-versus-merchant fabrication lines. Memory specialists and fabless design houses complete a four-archetype structure with divergent capital intensity requirements. Consolidation concentrates at the leading edge where EUV equipment scarcity enforces oligopoly, while mature nodes fragment across regional specialists. Dominant competitive moves include geographic diversification through subsidy arbitrage and strategic partnerships for advanced packaging co-development.
Within the foundry tier, TSMC and Samsung Electronics exemplify scale-driven process leadership, while Intel occupies a transitional position bridging IDM heritage with merchant service expansion. Among memory fabricators, SK Hynix and Micron Technology represent divergent geographic exposure to Chinese market access restrictions. These five entities anchor competitive dynamics across logic and memory supply chains.
| Leading Market Players |
|---|
| Intel |
| Samsung Electronics |
| NVIDIA |
| QUALCOMM |
| SK Hynix |
| TSMC |
| AMD |
| Micron Technology |
| Broadcom |
| Others |
Cost & Logistics Intelligence
ASML's monopoly on extreme ultraviolet lithography equipment determines both the premium commanded by leading-edge foundry services and the geographic concentration of advanced node production. This single-source dependency compresses margin spreads at mature nodes while amplifying pricing power for EUV-capable manufacturers.
Pricing Analysis
Configured-to-order pricing for automotive-grade chips with AEC-Q100 qualification commands substantial premiums over standard consumer logic. Three-tier pricing structure across premium, standard, and economy levels stratifies by process node sophistication, with gate-all-around architectures at 2nm extracting maximum value. Cost compression in mature analog nodes is intensifying because 200mm equipment refurbishment economics favor new 300mm capacity additions. Automotive OEMs exhibit lowest price sensitivity due to zero-defect reliability requirements, while consumer electronics distributors face acute margin pressure from hyperscaler direct procurement bypassing traditional channels.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for equipment and materials procurement. Leading-edge wafer fabrication concentrates in Taiwan, South Korea, and the United States, while neon gas purification for deep-UV lasers draws from Ukrainian facilities and specialty chemical precursors rest on German and Japanese suppliers. Single-source vulnerability for EUV systems constrains foundry expansion timelines regardless of subsidy availability. Distribution runs through direct foundry relationships with cloud hyperscalers and tier-one automotive suppliers, displacing traditional component distributors for advanced logic categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor platform economics are shifting toward chiplet-based disaggregation, where standardized tile interfaces enable heterogeneous integration across foundry sources and compress time-to-market for complex system-on-chip designs.
For Market Incumbents: Entrench pricing power at leading-edge nodes through captive capacity commitments from hyperscaler customers, while accelerating geographic diversification into Germany and Japan to preempt subsidy arbitrage by competitors. Defend against emerging foundry entrants by deepening process engineer talent pools in atomic-layer deposition and epitaxy specializations.
For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Karnataka semiconductor packaging corridors, where PLI capital expenditure rebates offset first-mover disadvantages. Target mature-node analog and power management segments where AEC-Q100 qualification timelines create defensive moats against scale competitors. Pursue direct relationships with industrial automation OEMs seeking supply chain traceability alternatives to concentrated Asian sourcing.
For Investors and Strategic Acquirers: EU Chips Act state aid approvals and CHIPS Act disbursements reshape the acquisition landscape toward geographically diversified fabrication assets. Long-term viability centers on foundries with demonstrated gate-all-around process development or established high-bandwidth memory packaging capabilities. Monitor ASML equipment delivery schedules as the critical inflection signal for capacity expansion feasibility across competing manufacturing zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Gate-All-Around Process Migration | TSMC and Samsung's nanosheet ramp sustains premium pricing power at 2nm nodes. |
| Geographic Manufacturing Footprint Expansion | Intel's Ohio and TSMC's Arizona fabs diversify supply beyond Taiwan concentration. |
| High-Bandwidth Memory Stack Development | SK Hynix and Micron capture AI training cluster demand through advanced packaging. |
| Photonic-Electronic Monolithic Integration | Silicon photonics convergence enables co-packaged optics for datacenter interconnects. |
| Automotive Qualification Investment | AEC-Q100 certification extends design-in cycles and protects margin pools. |
Research Approach
Desk research of SEC filings from foundry and memory manufacturers, equipment supplier order backlogs, and hyperscaler capital expenditure disclosures preceded structured interviews with fab operations directors, automotive tier-one procurement leads, and cloud infrastructure hardware engineers. Foundry utilization rates and wafer pricing data from Taiwan and South Korea anchored bottom-up volume estimates, while top-down triangulation against end-use equipment shipment forecasts validated segment allocations.
Assumptions held fixed include current EUV equipment delivery schedules and existing export control alignments between the U.S. Commerce Department and allied regulators, while subsidy disbursement timing and automotive electrification penetration curves were varied across scenarios. Segmentation modeling incorporated product architecture, process technology node, application workload intensity, and customer integration model dimensions. CAGRs were derived from regression analysis of historical foundry revenue against equipment capex cycles, with AI accelerator demand and automotive silicon content per vehicle serving as primary forecast inputs.
Sensitivities concentrate around ASML equipment delivery delays, neon gas supply disruptions from geopolitical conflict, and REACH substance restriction expansions affecting wet chemistry options. Forecasts reflect these documented assumptions and acknowledge that regulatory fragmentation across competing manufacturing zones could substantially revise capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
India Semiconductor Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Chiplets Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Gaas Wafer Market
Semiconductors
North America Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Smartphone Battery Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Europe Semiconductor Market