
 Cooled IR Camera Market | 2026-2036
Cooled IR Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Cooled IR Camera Market Intelligence
Modular sensor packaging is restructuring buyer choice in the cooled infrared sector, as defense integrators now specify swapable dewar-detector assemblies rather than fixed-configuration units. Leonardo DRS leverages its vertically integrated cryocooler manufacturing to control lead times for military contracts. Teledyne FLIR anchors its position through sustained R&D investment in strained-layer superlattice architectures. L3Harris Technologies differentiates by dominating the airborne gimbal integration segment, where cooled MWIR cores face extreme thermal cycling demands.
Cooled infrared cameras employ Stirling-cycle mechanical refrigerators to maintain focal plane arrays below 77 Kelvin, eliminating thermally generated noise that blinds uncooled alternatives at longer wavelengths or finer spatial resolutions. Their primary commercial purpose spans military target acquisition, industrial gas leak detection, and scientific thermography where NETD below 25 millikelvin proves essential. MWIR configurations lead defense procurement volumes due to atmospheric transmission windows and jet exhaust contrast signatures, while SWIR adoption accelerates in semiconductor wafer inspection where silicon becomes translucent. Dual-band architectures command premium positioning as they fuse MWIR target discrimination with LWIR thermal context in a single aperture.
FDA device regulations govern medical thermography applications in the United States, while ITAR export controls constrain cross-border transfer of cryocooled focal plane technology with sub-25 micron pitch. The EU AI Act introduces conformity obligations for autonomous surveillance platforms deploying cooled infrared analytics at border crossings. Stakeholders must monitor how emerging quantum dot FPA fabrication displaces traditional MCT epitaxy, as this materials transition could rewrite supplier qualification timelines and military certification pathways.
Market Dynamics
Mercury cadmium telluride epitaxy constraints are forcing defense integrators toward strained-layer superlattice alternatives, compressing supplier qualification timelines while NATO procurement agencies accelerate thermal imaging contracts.
Growth Catalysts
- ITAR-controlled cryocooler exports:United States defense procurement agencies sustain premium cooled sensor acquisition through Pentagon modernization budgets, insulating domestic manufacturers from price competition.
- EU AI Act conformity obligations:Autonomous surveillance platforms deploying cooled infrared analytics at Schengen border crossings face mandatory certification, creating captive demand for qualified suppliers.
- Mercury cadmium telluride sensitivity thresholds:Detector material advancements enable long-wave infrared capture below 25 millikelvin NETD, opening scientific thermography applications previously inaccessible to cooled architectures.
Market Restraints
- Indium antimonide substrate volatility:Cryogenic detector fabrication depends on concentrated rare earth supply chains subject to export quota disruptions.
- Stirling-cycle mechanical refrigerator complexity:Precision cryocooler manufacturing requires specialized vacuum brazing capabilities concentrated among European and North American suppliers.
- ITAR cross-border transfer constraints:Sub-25 micron pitch focal plane technology faces licensing delays that extend contract fulfillment timelines by 12-18 months.
Strategic Opportunities
- Semiconductor wafer inspection SWIR adoption:Silicon transparency at short-wave infrared wavelengths creates unmet demand for cooled alternatives to incumbent indium gallium arsenide sensors.
- Dual-band architecture premium positioning:MWIR-LWIR fusion in single apertures commands pricing power in airborne gimbal integration where target discrimination and thermal context must coexist.
- Industrial gas leak detection regulatory mandates:EPA methane monitoring requirements and EU F-Gas Regulation enforcement expand commercial thermography beyond defense-dependent revenue pools.
Industry Challenges
- Cryogenic engineering talent scarcity:Stirling-cycle thermodynamics expertise concentrates among aging specialists in defense-adjacent research institutions.
- Military certification pathway rigidity:MIL-STD-810 environmental testing and MIL-PRF-38534 qualification timelines resist compression even as procurement cycles accelerate.
- Legacy dewar-detector assembly integration:Modular swapable architectures demand retroactive compatibility with fielded platforms carrying decade-old mechanical interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooled IR Camera Market |
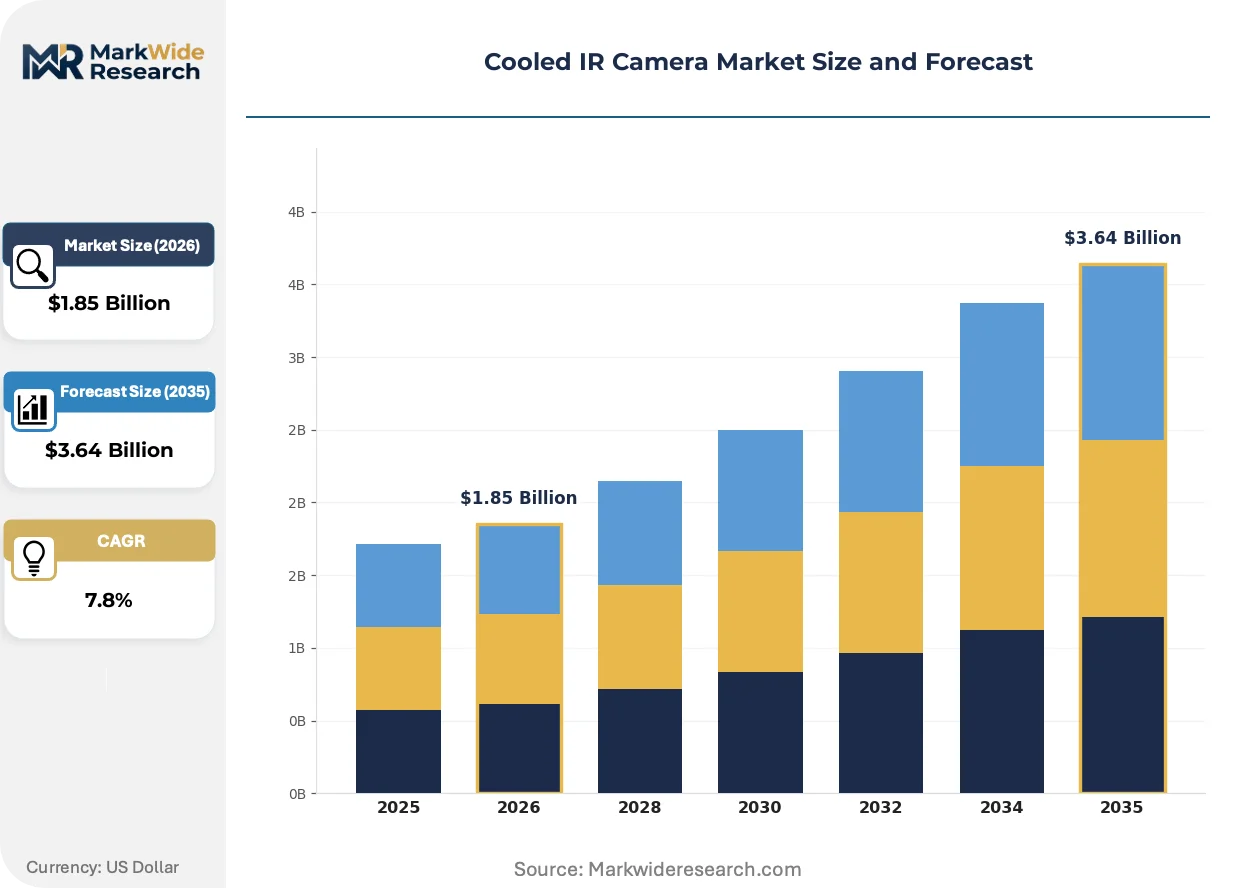
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MWIR, LWIR, SWIR, Dual-Band Technology: Quantum Dot, CMOS, CCD, FPA End User: Defense, Aerospace, Industrial, Research Application: Surveillance, Fire Detection, Search & Rescue, Thermal Imaging |
| Companies Covered | Leonardo DRS, Jenoptik, Teledyne FLIR, InfraTec GmbH Infrarotsysteme, Hamamatsu Photonics, L3Harris Technologies, Thales Group, Xenics, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooled IR Camera Market Strategic Shifts & Innovations
Three forces are restructuring the cooled infrared sector: detector material transitions, autonomous surveillance regulatory mandates, and procurement model fragmentation between defense integrators and commercial industrial buyers.
Strained-layer superlattice architectures are modularizing focal plane array design by enabling bandgap engineering without mercury cadmium telluride's lattice-matching constraints. Defense procurement agencies in the United States and United Kingdom are specifying these alternatives for next-generation targeting pods. The technology is modularizing supplier qualification pathways, allowing foundries with compound semiconductor experience to enter cryogenic imaging without MCT epitaxy infrastructure.
EU AI Act conformity obligations for autonomous border surveillance are mandating algorithmic transparency in thermal analytics platforms. This regulatory pressure compresses development cycles for cooled infrared OEMs serving Schengen perimeter security contracts. Airborne gimbal integrators face the steepest compliance burden, as their platforms must demonstrate explainable decision-making in threat-classification workflows.
Defense integrators are fragmenting their supplier bases to mitigate ITAR-driven delivery risk. Prime contractors now dual-source cryocooler assemblies and maintain qualified second-source detector inventories. This behavioral shift is most visible in United States Navy and Air Force contracts, where procurement officers explicitly evaluate supply chain resilience alongside unit cost and technical performance.
Cooled IR Camera Market Segmentation
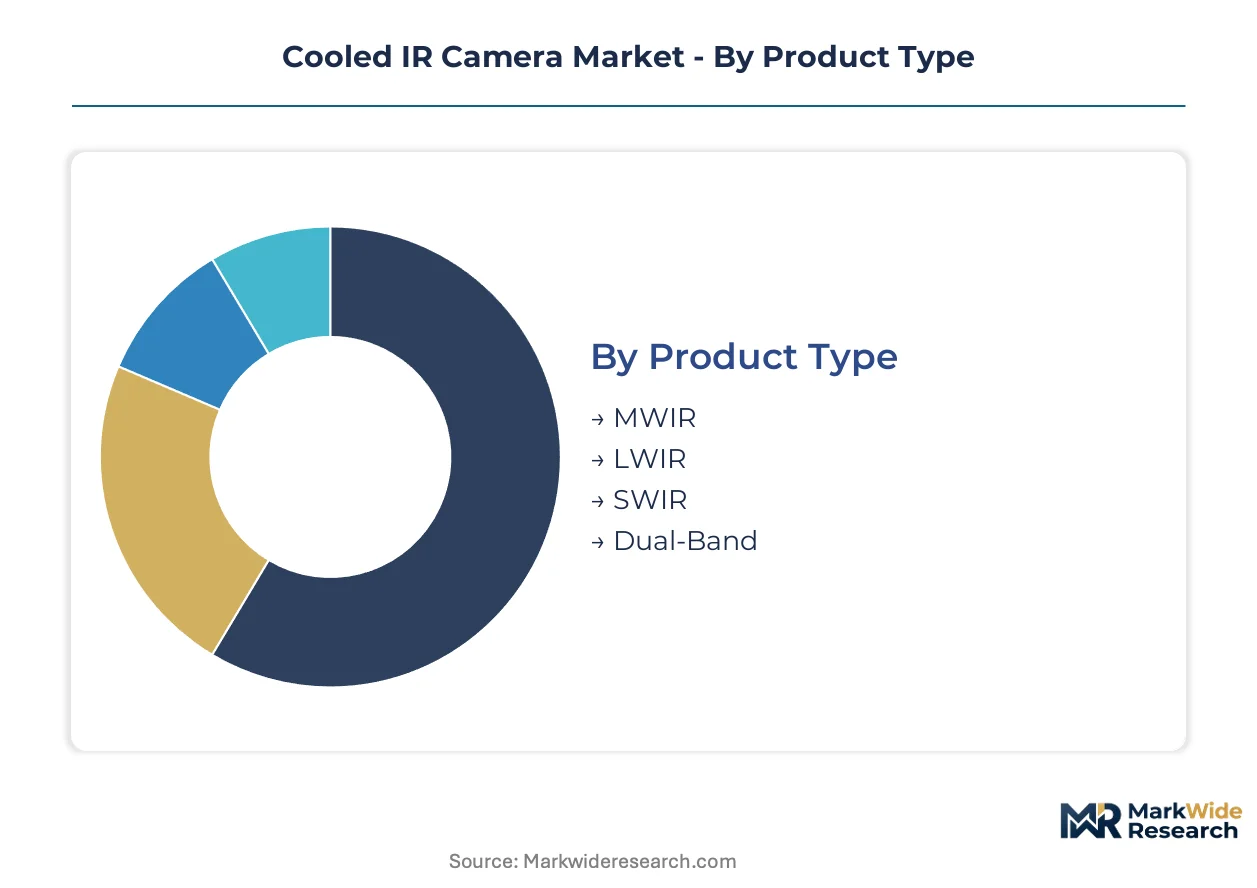
Cooled IR camera procurement patterns diverge sharply across wavelength bands and detector architectures. Defense integrators prioritize atmospheric transmission windows and cryogenic noise thresholds, while industrial buyers weigh unit cost against NETD specifications for gas leak detection.
Product Type:
Buyer differentiation hinges on target contrast requirements versus atmospheric conditions in the deployment theater.
- MWIR:Atmospheric transmission windows at 3-5 microns enable jet exhaust signature detection against cold sky backgrounds. Pentagon targeting pod contracts concentrate procurement volumes here, though mercury cadmium telluride epitaxy constraints compress supplier qualification timelines.
- LWIR:Long-wave configurations capture thermal emissions from human targets and vehicle engines through obscurants. Border surveillance agencies in the United States and United Kingdom specify these for persistent perimeter monitoring where diurnal temperature swings demand consistent performance.
- SWIR:Short-wave bands exploit silicon wafer transparency for semiconductor defect inspection. Industrial buyers in Japan and South Korea drive adoption as an alternative to incumbent indium gallium arsenide sensors.
- Dual-Band:MWIR-LWIR fusion architectures command premium positioning in airborne gimbal integration where target discrimination must coexist with thermal context acquisition.
MWIR leads volumes today; dual-band configurations are gaining share fastest.
Technology:
Detector material transitions are fragmenting supplier qualification pathways across compound semiconductor foundries.
- Quantum Dot:Colloidal synthesis methods enable bandgap tuning without lattice-matching constraints of epitaxial mercury cadmium telluride. Defense procurement agencies in NATO member states are accelerating qualification timelines for these alternatives.
- CMOS:Complementary metal-oxide-semiconductor readout circuits dominate cost-sensitive industrial thermography where NETD requirements exceed 50 millikelvin.
- CCD:Charge-coupled device architectures persist in scientific instrumentation requiring uniform pixel response across large focal plane arrays.
- FPA:Focal plane array packaging integrates detector layers with cryogenic interconnects; modular swapable dewar-detector assemblies now dominate military specifications.
Quantum dot architectures show the steepest expansion trajectory; FPA packaging commands the dominant revenue share.
End User:
Budget cycles and certification rigidity separate defense procurement from commercial deployment timelines.
- Defense:Pentagon modernization budgets sustain premium cooled sensor acquisition through ITAR-controlled supply chains. NATO thermal imaging contracts for border surveillance and threat detection anchor demand concentration.
- Aerospace:Airborne gimbal integrators face extreme thermal cycling demands; MIL-STD-810 environmental testing resists compression even as procurement cycles accelerate.
- Industrial:EPA methane monitoring requirements and EU F-Gas Regulation enforcement expand thermography beyond defense-dependent revenue pools.
- Research:Scientific thermography applications demand NETD below 25 millikelvin for materials characterization and astronomical observation.
Defense leads volumes today; industrial end users are climbing the fastest.
Application:
Regulatory mandates and operational tempo dictate sensor specification priorities across use cases.
- Surveillance:EU AI Act conformity obligations for autonomous border platforms mandate algorithmic transparency in thermal analytics workflows. Schengen perimeter security contracts impose the steepest compliance burden on cooled infrared OEMs.
- Fire Detection:Industrial facility operators specify cooled MWIR cores for hydrocarbon flame detection where false alarm immunity proves critical.
- Search & Rescue:Human signature detection through foliage and debris drives LWIR adoption for disaster response coordination.
- Thermal Imaging:General-purpose thermography spans predictive maintenance, building envelope analysis, and medical diagnostics governed by FDA device regulations in the United States.
Surveillance leads volumes today; fire detection is expanding most quickly.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cooled infrared camera industry traces its commercial roots to United States defense laboratories that pioneered mercury cadmium telluride detector epitaxy during the Cold War. Military procurement networks subsequently scaled production across NATO member states and East Asian industrial centers.
United States
Pentagon modernization budgets sustain the largest concentration of premium cooled sensor acquisition worldwide. ITAR export controls administered by the State Department constrain cross-border transfer of cryocooled focal plane technology with sub-25 micron pitch. Defense integrators cluster around Boston-Cambridge research corridors and Dallas-Fort Worth aerospace manufacturing hubs.
Germany
Industrial thermography demand from automotive and chemical manufacturing sectors drives cooled MWIR adoption for predictive maintenance. The EU F-Gas Regulation enforces methane monitoring requirements that expand commercial deployment beyond defense applications. Precision optics manufacturers concentrate in Baden-Württemberg and Bavaria, supplying cryogenic dewar assemblies to continental integrators.
Japan
Semiconductor wafer inspection applications generate unmet demand for cooled SWIR alternatives to incumbent indium gallium arsenide sensors. METI industrial technology roadmaps prioritize focal plane array packaging automation to reduce unit costs. Hamamatsu Photonics anchors detector manufacturing in Shizuoka Prefecture, serving scientific instrumentation markets across East Asia.
United Kingdom
Border surveillance agencies specify LWIR configurations for persistent perimeter monitoring where diurnal temperature swings demand consistent performance. Ministry of Defence thermal imaging contracts for threat detection and target acquisition anchor procurement volumes. Airborne gimbal integration specialists concentrate in southern England, supplying NATO targeting pod programs.
Israel
Defense procurement agencies prioritize dual-band architectures that fuse MWIR target discrimination with LWIR thermal context in single apertures. National security doctrine emphasizes autonomous surveillance platform deployment at contested borders. Electro-optics engineering talent concentrates in Tel Aviv metropolitan research parks, feeding specialist component supply to Western defense primes.
Cooled IR Camera Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification complexity and cryogenic engineering capability. The vendor base stratifies into three tiers: defense-integrated primes with captive cryocooler manufacturing, specialist detector foundries serving dual-use markets, and industrial thermography assemblers sourcing modular subsystems. Dominant competitive moves include backward integration into Stirling-cycle refrigerator production and strategic partnerships with compound semiconductor foundries to secure strained-layer superlattice supply.
Within the defense-integrated tier, Leonardo DRS, Teledyne FLIR, and L3Harris Technologies exemplify archetypes of vertical manufacturing control. Leonardo DRS represents European-owned prime contracting with in-house cryocooler capabilities. Teledyne FLIR occupies a position bridging commercial thermal imaging heritage with defense specification requirements. L3Harris Technologies anchors the airborne gimbal integration segment where extreme thermal cycling demands separate qualified suppliers from aspirants. These three entities sit within a qualification landscape where MIL-STD-810 environmental testing and MIL-PRF-38534 certification timelines resist compression.
| Leading Market Players |
|---|
| Leonardo DRS |
| Jenoptik |
| Teledyne FLIR |
| InfraTec GmbH Infrarotsysteme |
| Hamamatsu Photonics |
| L3Harris Technologies |
| Thales Group |
| Xenics |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
Defense-integrated primes with captive cryocooler manufacturing anchor pricing discipline through backward integration into Stirling-cycle refrigerator production, insulating premium tiers from commodity-margin pressure while procurement officers dual-source to compress contract fulfillment timelines. Pentagon modernization budgets sustain premium cooled sensor acquisition through ITAR-controlled supply chains, creating pricing power concentration among qualified military suppliers.
Pricing Analysis
Three-tier pricing structure across ITAR-restricted defense, dual-use commercial, and industrial thermography levels separates procurement by certification complexity and cryogenic performance thresholds. Price differentiation hinges on MIL-PRF-38534 qualification status and NETD specifications below 25 millikelvin, with airborne gimbal integrators commanding premiums for extreme thermal cycling resilience. Cost compression in industrial thermography tiers is intensifying because CMOS readout circuits displace cooled architectures above 50 millikelvin thresholds. Defense procurement agencies exhibit lowest price sensitivity; semiconductor wafer inspection buyers in Japan and South Korea drive hardest unit-cost negotiations.
Supply Chain Analysis
Domestic-content mandates in United States ITAR regulations and EU defense procurement directives are reshaping sourcing toward qualified foundries within NATO member states, fragmenting previously concentrated mercury cadmium telluride epitaxy supply. Manufacturing gravity centers on United States, Germany, and Israel for cryogenic detector fabrication, with precision optics and dewar assemblies drawing from Baden-Württemberg and Boston-Cambridge clusters. Raw material dependencies rest on indium antimonide substrates, rare earth cryocooler alloys, and mercury cadmium telluride precursor chemicals. Single-source vulnerability concentrates in European vacuum brazing capabilities for Stirling-cycle refrigerators. Distribution runs through defense prime contractors and industrial thermography OEMs with modular subsystem sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in dual-band architecture premiumization and strained-layer superlattice cost-down curves as detector material transitions rewrite supplier economics. Quantum dot FPA fabrication and modular dewar-detector packaging automation represent the primary cost compression vectors.
For Market Incumbents: Acquire compound semiconductor foundry capacity with strained-layer superlattice expertise to secure alternative detector supply outside mercury cadmium telluride constraints. Defense integrators face procurement cycle acceleration against rigid MIL-STD-810 environmental testing timelines; backward integration into cryocooler manufacturing compresses lead times and protects margin position from ITAR licensing delays that extend contract fulfillment. For New Entrants and Emerging Players: Direct-to-defense procurement officer digital platforms bypass incumbent prime contractor gatekeeping for modular swapable dewar-detector assemblies. Industrial gas leak detection in Germany and Japan offers most penetrable white-space as EPA methane monitoring requirements and EU F-Gas Regulation enforcement expand thermography beyond defense-dependent revenue pools. Position through semiconductor wafer inspection SWIR adoption as silicon transparency creates unmet demand for cooled alternatives to indium gallium arsenide sensors. For Investors and Strategic Acquirers: Valuations sit cheapest among specialist detector foundries serving dual-use markets with compound semiconductor experience but lacking cryogenic imaging certification. Long-term viability framing favors suppliers positioned for quantum dot FPA displacement of traditional MCT epitaxy across the analysis window. Acquisition target archetype: modular packaging specialists with automated focal plane array assembly capabilities. Watch strained-layer superlattice military qualification timelines as inflection indicator for supplier re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryocooler Manufacturing | Captive Stirling-cycle refrigerator production insulates defense primes from European vacuum brazing bottlenecks and ITAR licensing delays. |
| Strained-Layer Superlattice Qualification Acceleration | NATO procurement agencies in United States and United Kingdom specify these alternatives to compress supplier timelines beyond MCT epitaxy constraints. |
| Modular Dewar-Detector Assembly Standardization | Swapable architectures dominate military specifications and enable retroactive compatibility with decade-old fielded platform interfaces. |
| Dual-Band Architecture Premium Positioning | MWIR-LWIR fusion in single apertures commands pricing power in airborne gimbal integration for target discrimination with thermal context. |
| Industrial Thermography Channel Expansion | EPA methane monitoring and EU F-Gas Regulation enforcement expand revenue pools beyond Pentagon modernization budget dependence. |
Research Approach
Bottom-up defense procurement and industrial thermography modeling reconciled against top-down cryogenic detector and cryocooler supply tracking forms the analytical core of this study. Primary interviews with thermal imaging program officers at Pentagon procurement agencies, cryogenic engineering directors at defense primes, compound semiconductor foundry operations leads, and industrial facility maintenance directors combined with secondary validation. Secondary sources include ITAR licensing databases, MIL-STD-810 environmental test records, EU defense procurement directive filings, and customs trade data for mercury cadmium telluride precursor chemicals.
Historical trendline analysis across detector material transitions, procurement cycle compression, and regulatory mandate expansion informed projection framework construction. The model segments by wavelength band, detector architecture, end-user budget cycle, and application regulatory intensity, with CAGRs derived from elasticity-adjusted procurement volume trajectories. Forecast inputs incorporate EU AI Act conformity obligation timelines for autonomous border surveillance and quantum dot FPA fabrication scale-up curves.
The model assumes a particular technology adoption path; alternative pathways for strained-layer superlattice or quantum dot focal plane array displacement of mercury cadmium telluride epitaxy would alter the outlook. Forecasts reflect assumptions regarding ITAR licensing velocity, rare earth export quota stability, and cryogenic engineering talent pipeline renewal. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Biophotonics Market
Imaging
Chemical Imaging Systems Market
Imaging
Video Processing Solutions Market
Imaging
Global AI in Computer Vision Market
Imaging
Machine Vision System and Services Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
PET Imaging Systems Market
Imaging
LCD Digital Microscope Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Mobile Imaging Market
Imaging
Contact Image Sensor Market
Imaging
Hyperspectral Imaging Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Microwave Imaging Market
Imaging
Widefield Imaging Systems Market