
 Mosfet Power Transistors Market | 2026-2036
Mosfet Power Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Mosfet Power Transistors Market Foresight
Automotive OEMs are rotating procurement priority from consumer electronics buyers toward electrification platforms. Infineon Technologies AG anchors European supply through in-house SiC crystal growth and module assembly. Toshiba Corporation dominates discrete MOSFET supply for industrial motor drives across Northeast Asian manufacturing clusters. ON Semiconductor specializes in automotive-qualified trench MOSFETs for battery management and thermal management subsystems.
MOSFET power transistors are voltage-controlled switching devices fabricated on silicon, silicon carbide, or gallium nitride substrates, engineered for drain-source breakdown voltages from 20 V to over 1,200 V and switching frequencies exceeding 100 kHz in hard-switched topologies. Their primary purpose is efficient power conversion across DC-DC, DC-AC, and AC-DC stages in energy-intensive equipment. N-channel devices lead unit volume due to lower on-resistance per die area, while SiC and GaN technologies capture expanding margin pools in EV inverters and server power supplies where efficiency thresholds exceed silicon limits. Automotive Electronics applications now outpace traditional Power Supplies segments in design-in velocity across Tier-1 supplier portfolios.
The EPA, EU Green Deal framework, and China's MIIT dual carbon goals collectively tighten efficiency mandates for power conversion stages in vehicles, data centers, and grid-tied storage systems. REACH and RoHS restrictions on hazardous substances in semiconductor packaging constrain material choices and qualify alternative molding compounds. Stakeholders must monitor SiC substrate supply allocation between automotive and energy storage buyers as capacity commitments crystallize over the forecast horizon.
Market Dynamics
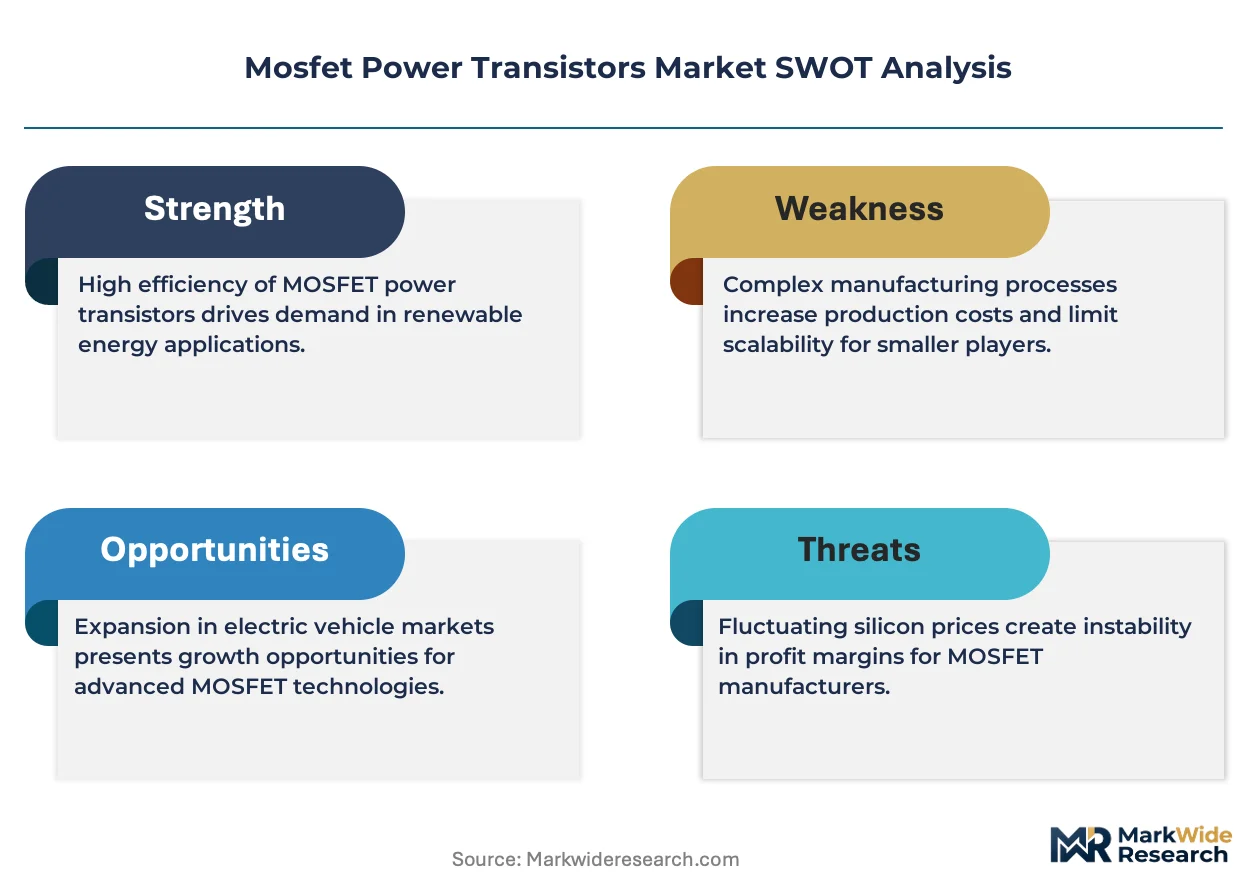
The MOSFET power transistor market pivots on substrate allocation battles between automotive traction inverters and hyperscale data center power supplies. SiC wafer foundries face binding capacity constraints as EV OEMs lock in multi-year supply agreements ahead of 2030 fleet electrification targets.
Growth Catalysts
- EPA Vehicle Emissions Standards:Tightened tailpipe regulations in the United States force powertrain electrification, accelerating SiC MOSFET qualification for 800 V architectures.
- China MIIT Dual Carbon Goals:Domestic automotive OEMs and wafer foundries scale vertical capacity to achieve power semiconductor self-sufficiency, concentrating demand within Chinese manufacturing clusters.
- Silicon Carbide Substrate Technology:6-inch and 8-inch SiC crystal growth advances reduce defect density, enabling higher current density modules for EV traction inverters.
Market Restraints
- Substrate Supply Concentration:SiC boule production concentrates among limited crystal growth specialists, creating allocation bottlenecks for automotive module assemblers.
- REACH and RoHS Compliance:Hazardous substance restrictions in semiconductor packaging constrain leadframe and molding compound material choices, extending qualification timelines.
- Gallium Nitride Substitution:GaN HEMTs capture sub-650 V applications in server power supplies, compressing silicon superjunction MOSFET margin pools in consumer electronics.
Strategic Opportunities
- Grid-Tied Energy Storage:Utility-scale battery inverters require high-voltage SiC modules for bidirectional power conversion, opening white space beyond automotive demand.
- EU Green Deal Industrial Plan:Carbon border adjustments and clean technology manufacturing incentives attract MOSFET module assembly investment into European production corridors.
- AI Data Center Power Density:GPU rack power budgets exceeding 100 kW drive adoption of 48 V intermediate bus architectures using GaN and SiC switching devices.
Industry Challenges
- Power Electronics Talent Scarcity:Shortage of engineers proficient in wide-bandgap device characterization and thermal management slows product development cycles.
- AEC-Q101 Certification Burden:Automotive qualification protocols for MOSFETs require extended temperature cycling and humidity testing, stretching time-to-revenue for new device families.
- Legacy Silicon Inventory Rationalization:Tier-1 suppliers face working capital pressure from stranded planar MOSFET stock as customers migrate to trench and superjunction architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosfet Power Transistors Market |
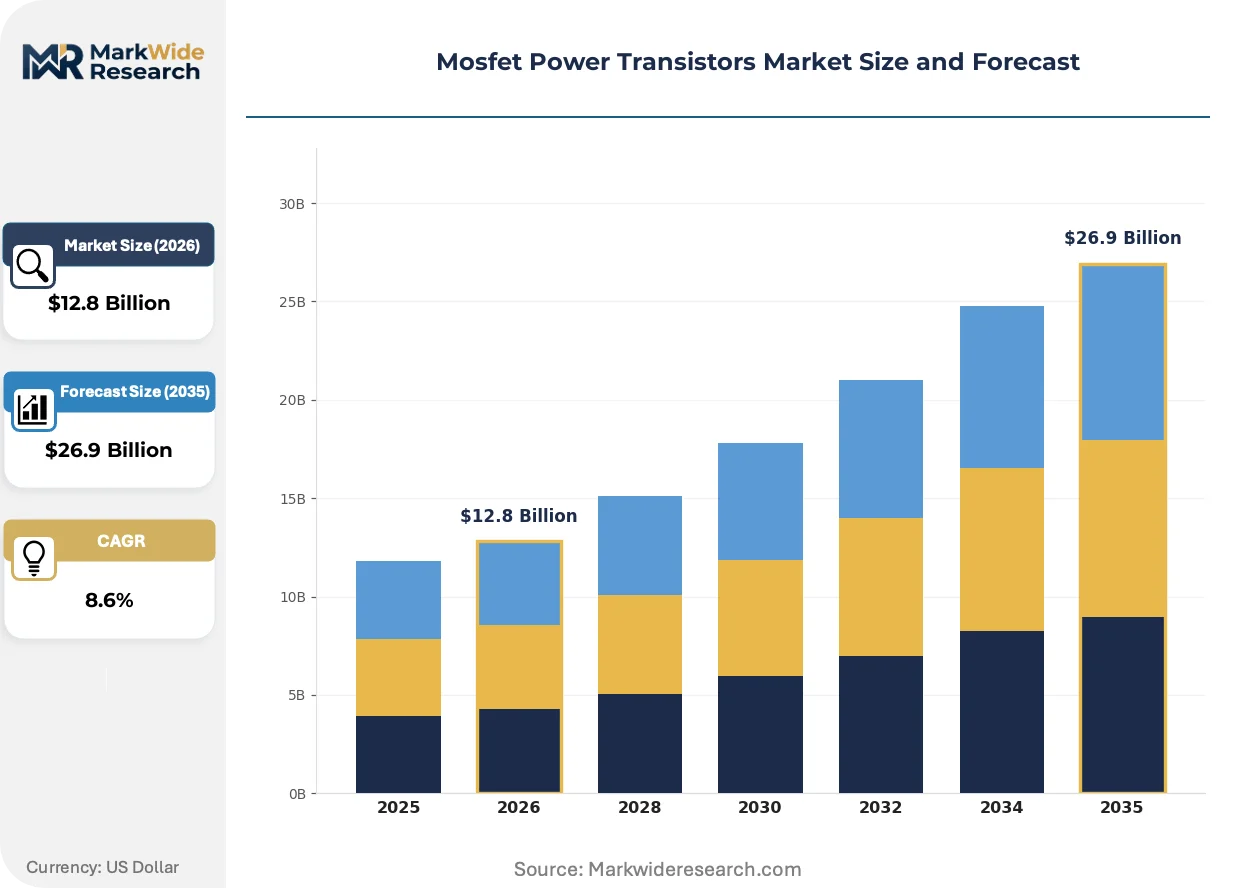
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N-channel, P-channel, Half-bridge, Full-bridge Application: Power Supplies, Motor Drives, Inverter Systems, Automotive Electronics End User: Industrial Automation, Consumer Electronics, Telecommunications, Energy Sector Technology: Si-based, SiC, GaN, Hybrid |
| Companies Covered | Vishay Intertechnology Inc., Toshiba Corporation, Infineon Technologies AG, Mitsubishi Electric Corporation, NXP Semiconductors, Texas Instruments, ON Semiconductor, Renesas Electronics Corporation, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosfet Power Transistors Market Shifts & Advancements
Device architecture evolution and regulatory efficiency mandates are compressing switching losses while expanding voltage ratings. The competitive frontier shifts from die shrink to system-level integration of gate drivers and protection circuits.
Trench gate SiC MOSFET designs are miniaturizing cell pitch dimensions below 2 microns, reducing specific on-resistance per unit area. Automotive inverter manufacturers at BYD and Hyundai Motor Group adopt these devices for 800 V battery electric platforms. This geometry compression enables module footprint reduction without sacrificing current handling, accelerating platform consolidation around standardized power stage dimensions.
The EU Green Deal framework tightens embodied carbon reporting requirements under CSRD for semiconductor manufacturing supply chains. Module assemblers must now document Scope 3 emissions from SiC substrate production through to end-of-life recycling. European automotive electronics suppliers face the steepest compliance burden, driving preferential sourcing from crystal growth facilities with verified renewable energy procurement.
Direct contracting between automotive OEMs and SiC substrate manufacturers is displacing traditional distribution channels for high-voltage power devices. Tier-1 inverter suppliers lose procurement leverage as Volkswagen Group and Ford Motor Company negotiate multi-year wafer supply agreements directly with foundries. This channel compression is most advanced in Germany and the United States, where fleet electrification targets concentrate purchasing power among volume OEMs.
Mosfet Power Transistors Market Segmentation
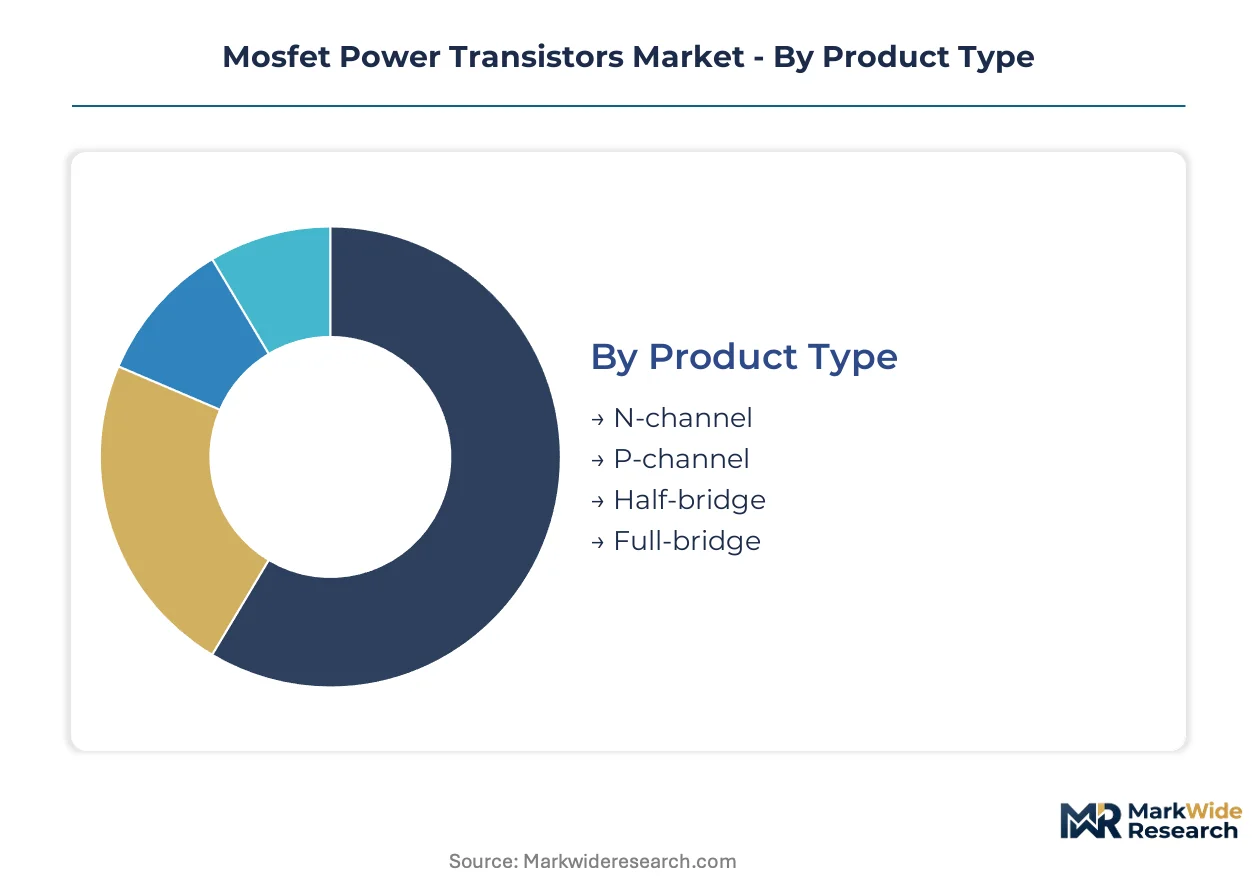
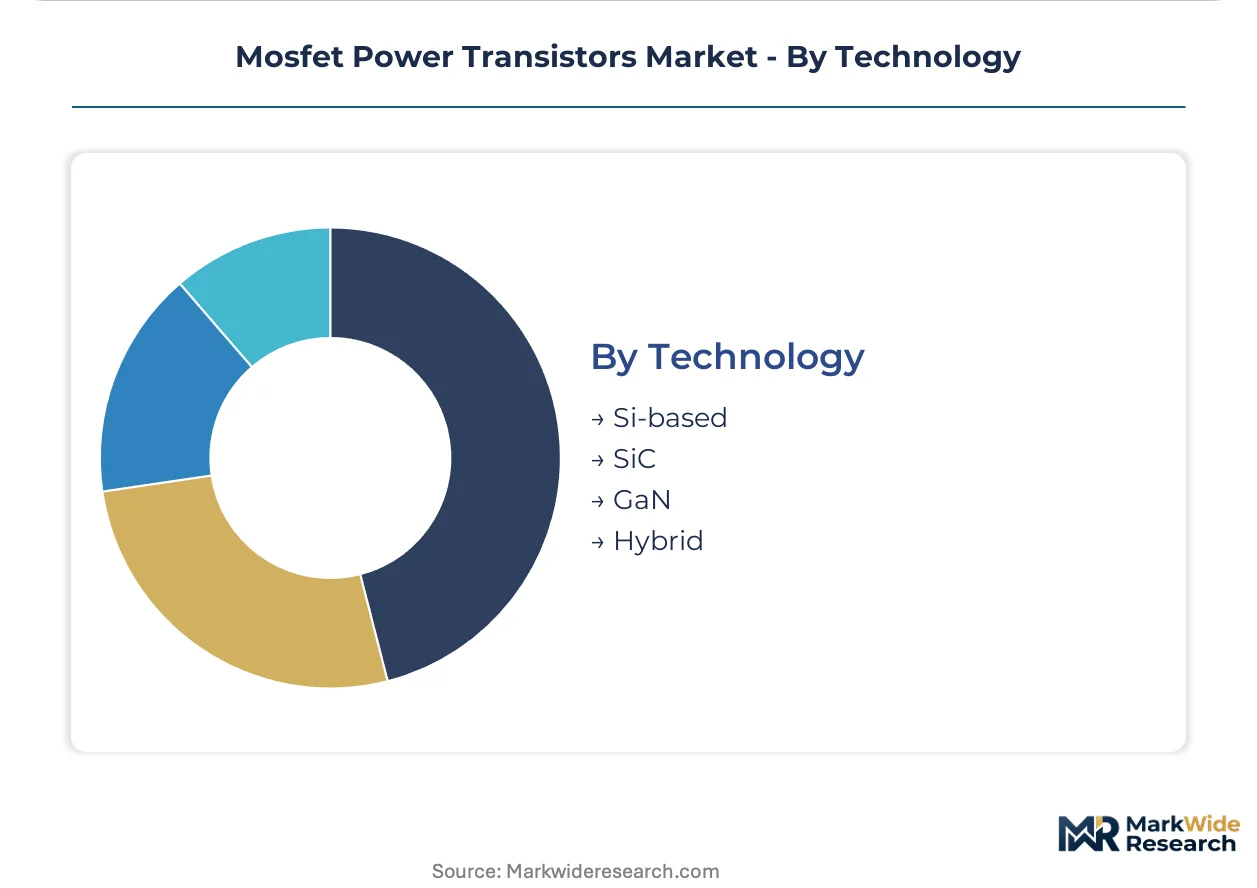
Segmentation reveals how substrate technology, channel architecture, and end-use voltage requirements fragment procurement patterns across the MOSFET power transistor market. Regulatory efficiency mandates in automotive and data center applications are compressing legacy silicon segments while accelerating wide-bandgap technology qualification timelines.
Product Type:
EPA vehicle emissions standards and EU Green Deal efficiency thresholds differentiate channel architecture selection by voltage class and switching frequency requirements.
- N-channel:Lower on-resistance per die area makes these devices the default for high-current applications. EV traction inverter manufacturers at BYD and Hyundai Motor Group specify trench-gate N-channel SiC MOSFETs for 800 V battery platforms, where reduced conduction losses directly extend vehicle range.
- P-channel:Higher on-resistance limits deployment to low-side switching in half-bridge configurations where simplified gate drive circuitry offsets efficiency penalties. Industrial motor drive suppliers in Chinese manufacturing clusters specify these for cost-sensitive auxiliary power stages.
- Half-bridge:Integrated high-side and low-side devices reduce external component count in DC-DC converters. Server power supply vendors adopt these for intermediate bus architectures where power density exceeds 100 W per cubic inch.
- Full-bridge:Four-switch configurations enable bidirectional power flow in grid-tied energy storage inverters. Utility-scale battery integrators specify these for 1500 V DC bus systems requiring synchronous rectification.
Established volume favors N-channel; emerging adoption favors Full-bridge.
Application:
End-use power density requirements stratify device selection by switching frequency and thermal management complexity.
- Power Supplies:AC-DC and DC-DC conversion stages in computing and telecommunications equipment. GaN HEMTs displace silicon superjunction devices in sub-650 V server power supplies where efficiency thresholds exceed 96%.
- Motor Drives:Variable frequency drives for industrial automation and HVAC systems. Toshiba Corporation dominates discrete MOSFET supply for Northeast Asian manufacturing clusters requiring 600-1200 V blocking capability.
- Inverter Systems:DC-AC conversion for solar photovoltaic and energy storage installations. Utility-scale deployments require high-voltage SiC modules capable of 1500 V DC input handling.
- Automotive Electronics:Battery management, thermal management, and traction inverter subsystems. ON Semiconductor specializes in automotive-qualified trench MOSFETs for these applications where AEC-Q101 certification is mandatory.
Power Supplies retain the largest installed base; Automotive Electronics climbs the fastest.
End User:
Customer procurement scale and qualification burden shape supplier relationships and pricing structures.
- Industrial Automation:Motor drives, robotics power stages, and factory automation equipment. German and Japanese machinery OEMs specify devices with extended temperature ranges for harsh manufacturing environments.
- Consumer Electronics:Smartphone chargers, laptop adapters, and white goods power stages. GaN substitution compresses silicon MOSFET margins in sub-100 W applications where cost sensitivity dominates.
- Telecommunications:Base station power supplies and data center infrastructure. 5G deployment drives demand for intermediate bus converters using 48 V architectures.
- Energy Sector:Solar inverters, wind turbine converters, and grid-tied storage systems. Direct OEM contracting with SiC substrate manufacturers is displacing traditional distribution channels for these high-voltage applications.
Industrial Automation maintains procurement volume leadership; Energy Sector shows steepest expansion trajectory.
Technology:
Substrate material selection determines efficiency ceiling, thermal performance, and cost structure across voltage classes.
- Si-based:Planar and trench silicon MOSFETs serve cost-optimized applications below 200 kHz switching frequency. Legacy inventory rationalization pressures Tier-1 suppliers as customers migrate to superjunction architectures.
- SiC:6-inch and 8-inch crystal growth advances reduce defect density, enabling higher current density modules. Infineon Technologies AG anchors European supply through in-house SiC crystal growth and module assembly.
- GaN:HEMT structures excel in sub-650 V applications requiring switching frequencies above 500 kHz. AI data center GPU rack power budgets exceeding 100 kW drive 48 V intermediate bus adoption.
- Hybrid:Multi-die packages combining silicon and wide-bandgap devices optimize cost-performance tradeoffs. These configurations bridge the gap during customer transition periods.
Si-based retains volume dominance; SiC gains share fastest in high-voltage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs export SiC MOSFET modules to North American EV assembly plants, establishing a dominant westbound trade corridor in high-voltage power semiconductors.
China
Domestic wafer foundries and automotive OEMs scale vertical capacity for power semiconductor self-sufficiency. MIIT dual carbon goals accelerate silicon carbide qualification timelines for 800 V battery platforms. Manufacturing clusters in Shanghai and Shenzhen concentrate module assembly operations for BYD and domestic EV producers.
Germany
Infineon Technologies AG anchors European supply through in-house SiC crystal growth and module assembly. EU Green Deal carbon border adjustments attract MOSFET module assembly investment into production corridors. Bavarian industrial zones host qualification facilities serving Volkswagen Group and BMW electrification platforms.
United States
EPA vehicle emissions standards tighten tailpipe regulations, forcing powertrain electrification and SiC MOSFET adoption. Ford Motor Company negotiates multi-year wafer supply agreements directly with foundries. Michigan and Texas manufacturing corridors concentrate Tier-1 inverter supplier operations.
Japan
Toshiba Corporation dominates discrete MOSFET supply for industrial motor drives across Northeast Asian manufacturing clusters. METI efficiency mandates push superjunction device adoption in factory automation equipment. Nagoya and Osaka industrial basins concentrate power semiconductor packaging operations.
South Korea
Hyundai Motor Group adopts trench-gate N-channel SiC MOSFETs for 800 V battery electric platforms. Domestic battery integrators source high-voltage modules for grid-tied energy storage inverters. Gyeonggi-do semiconductor clusters expand SiC substrate processing capacity.
Mosfet Power Transistors Market Competitive Landscape
Player mix skews toward integrated device manufacturers with captive substrate capabilities and fabless specialists licensing wide-bandgap process technology. Market structure concentrates around European and Asian conglomerates with backward integration into SiC crystal growth. Two strategic archetypes dominate: vertically integrated substrate-to-module suppliers and fabless design houses partnering with foundry networks. Competitive moves center on multi-year supply agreements locking wafer capacity and direct OEM contracting displacing traditional distribution channels.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics exemplify the substrate-integrated archetype with in-house SiC crystal growth operations. Toshiba Corporation occupies a position representing Japanese conglomerates with historical strength in discrete silicon devices and industrial motor drive applications. ON Semiconductor sits within the automotive-qualified specialist tier, anchoring North American supply for battery management and thermal management subsystems requiring AEC-Q101 certification.
| Leading Market Players |
|---|
| Vishay Intertechnology Inc. |
| Toshiba Corporation |
| Infineon Technologies AG |
| Mitsubishi Electric Corporation |
| NXP Semiconductors |
| Texas Instruments |
| ON Semiconductor |
| Renesas Electronics Corporation |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Eight-inch SiC crystal growth scale economies concentrate wafer supply among three dominant foundries, compressing margin pools for module assemblers lacking captive boule production while elevating price floors for automotive-qualified trench devices. This concentration dynamic feeds directly into procurement leverage shifts as EV OEMs negotiate multi-year supply agreements.
Pricing Analysis
Silicon superjunction, SiC trench-gate, and GaN HEMT generations command distinct price bands reflecting efficiency thresholds and substrate scarcity. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer electronics tiers differentiates by AEC-Q101 certification status and thermal cycling performance. Pricing pressure stems from gallium nitride substitution in sub-650 V server power supplies, eroding silicon margins. Consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
SiC boule growth capacity in Germany, Japan, and the United States constitutes the primary chokepoint constraining module assembly expansion. Raw material dependencies encompass high-purity silicon carbide powder, graphite crucibles, and specialized epitaxial growth equipment. Single-source vulnerability concentrates in 6-inch and 8-inch substrate supply, where qualification timelines exceed eighteen months. Distribution runs through direct OEM contracting for high-voltage automotive modules, displacing traditional semiconductor distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride HEMTs threaten silicon superjunction incumbents in sub-650 V applications, forcing defensive repositioning around wide-bandgap qualification timelines and automotive certification barriers.
For Market Incumbents: Secure captive SiC crystal growth capacity or multi-year wafer supply agreements before 2030 fleet electrification targets crystallize. Deepen AEC-Q101 certification pipelines to defend automotive module share against fabless entrants lacking thermal cycling expertise. Prioritize backward integration into substrate production over margin expansion in commoditized silicon discrete segments.
For New Entrants and Emerging Players: Application-specific gate driver integration represents the service-layer gap where incumbents under-serve mid-voltage industrial motor drive customers. Target grid-tied energy storage inverter manufacturers requiring 1500 V bidirectional modules, where direct OEM contracting protocols remain unsettled. Lead with system-level reference designs bundling protection circuits and thermal management rather than discrete die sales.
For Investors and Strategic Acquirers: Fabless design houses with licensed wide-bandgap process technology and existing automotive Tier-2 relationships present the most defensible acquisition profile. Long-term viability hinges on substrate allocation security rather than die-level innovation alone. Monitor SiC wafer foundry capacity commitment announcements as the critical inflection signal for module assembler margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term SiC Wafer Supply Agreement | Ford Motor Company and Volkswagen Group direct contracting with foundries locks capacity ahead of 800 V platform ramps. |
| AEC-Q101 Certification Pipeline Expansion | ON Semiconductor and STMicroelectronics qualification investments defend automotive module share against unqualified entrants. |
| Gate Driver Integration Development | System-level reference designs bundling protection circuits differentiate module assemblers in industrial motor drive segments. |
| Grid-Tied Energy Storage Module Qualification | Utility-scale battery inverter deployments at 1500 V open white space beyond automotive demand concentration. |
| Backward Integration into SiC Crystal Growth | Infineon Technologies AG in-house boule production insulates European supply from substrate allocation bottlenecks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with power electronics engineers, automotive Tier-1 procurement managers, SiC wafer foundry operations directors, and inverter system architects; and secondary validation through SEC semiconductor filings, EPA vehicle emissions regulatory dockets, EU Green Deal implementation documents, and MIIT dual carbon policy releases. Bottom-up device shipment estimates and top-down OEM platform electrification targets were triangulated against foundry capacity expansion announcements.
Across the analysis window, the forecasting framework modeled segmentation by substrate technology, channel architecture, voltage class, and end-use application intensity. CAGRs were derived from OEM platform rollout schedules, foundry capacity commissioning timelines, and regulatory efficiency mandate phase-in dates. Specific inputs encompassed EV traction inverter content per vehicle, data center GPU rack power density trajectories, and industrial motor drive replacement cycles.
Underlying assumptions cover SiC substrate yield improvement curves and automotive qualification timeline stability, with deviation risk concentrated in gallium nitride substitution velocity and China MIIT policy enforcement intensity. Practitioners should keep alternative scenarios live as EPA vehicle emissions standard stringency and EU carbon border adjustment implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Advanced IC Substrates Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Global Thermoelectric Modules Market