
 East Asia Automotive Semiconductors Market | 2026-2036
East Asia Automotive Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
East Asia Automotive Semiconductors Market Foresight
China's dual carbon goals is shifting procurement priorities across East Asian automotive supply chains toward high-efficiency power semiconductors. Infineon Technologies AG leverages its SiC module expertise to anchor premium EV inverter contracts with Chinese OEMs. Renesas Electronics Corp dominates microcontroller supply for Japanese tier-1 suppliers through captive fab capacity in Naka and Kofu. Samsung Electronics Co Ltd extends its foundry services into automotive-grade nodes to compete for Korean EV platform silicon.
Automotive semiconductors are integrated circuits engineered to operate across temperature ranges from minus 40 to 150 degrees Celsius, fabricated on silicon and silicon carbide substrates for power management, sensing, and real-time control in vehicle systems. Power Devices command the largest revenue pool due to inverter and onboard charger proliferation in battery electric architectures, while Analog ICs sustain the fastest expansion trajectory driven by battery management system precision requirements. Embedded Systems technology leads unit shipments across combustion and electrified platforms, though Electric Drive applications capture disproportionate margin concentration as voltage architectures climb toward 800V.
METI in Japan, China's MIIT, and South Korea's MFDS collectively enforce automotive semiconductor reliability standards that gate market access for non-qualified suppliers. These frameworks mandate AEC-Q100 qualification and ISO 26262 functional safety certification, effectively filtering component ecosystems to established players with validation infrastructure. Stakeholders must monitor how China's GB standards evolution and Japan's JIS roadmap updates reshape interoperability requirements for cross-border vehicle platforms.
Market Dynamics
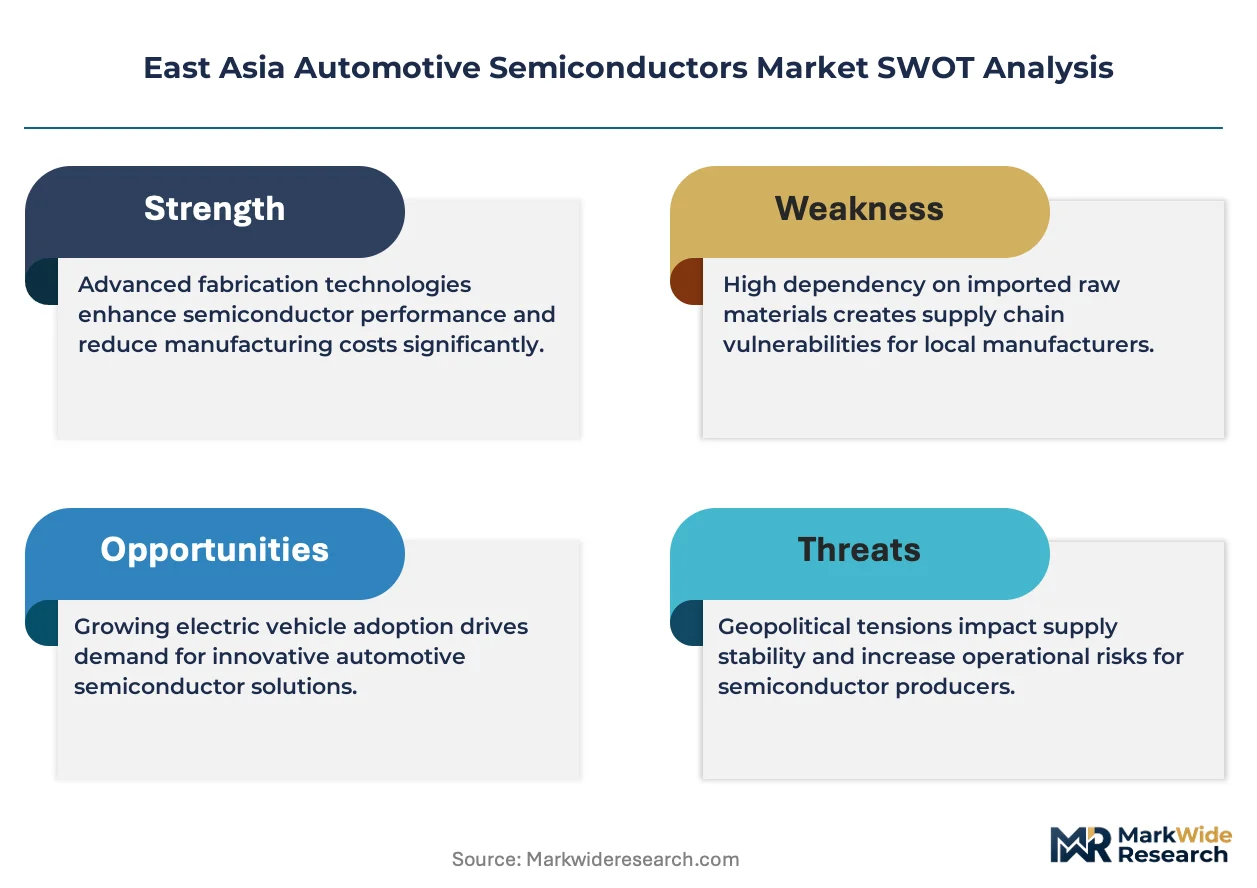
Powertrain electrification is forcing a wholesale recalibration of semiconductor specifications across East Asian automotive supply chains, as 800V architectures and silicon carbide adoption redefine thermal, efficiency, and reliability baselines for component suppliers.
Growth Catalysts
- China's dual carbon goals:National mandates for carbon peak and neutrality are accelerating procurement of high-efficiency power semiconductors across domestic OEM supply chains, with particular emphasis on inverter-grade silicon carbide modules.
- 800V platform proliferation:Premium battery electric vehicle architectures are multiplying semiconductor content per vehicle by 2-3x versus 400V systems, concentrating demand in wide-bandgap power devices and isolated gate drivers.
- South Korea's Pyeongtaek corridor:Foundry and memory semiconductor clustering is creating captive automotive-grade wafer capacity, reducing lead times for domestic EV platform suppliers.
Market Restraints
- Silicon carbide substrate shortage:Limited 6-inch SiC boule supply from specialist crystal growers is constraining module output expansion, with substrate costs representing 50-70% of device bill-of-materials.
- Japan's captive fab concentration:Renesas Electronics and Toyota-affiliated suppliers maintain vertically integrated production, limiting foundry access for fabless entrants and reinforcing supply concentration risk.
- AEC-Q100 qualification timelines:Extended validation cycles for Grade 0 automotive components create 18-24 month product introduction barriers, filtering out suppliers lacking dedicated reliability infrastructure.
Strategic Opportunities
- China's Yangtze River Delta clustering:Shanghai-Suzhou-Hangzhou semiconductor ecosystem is attracting foreign module packaging investments to serve domestic EV OEMs with localized supply.
- ISO 26262 functional safety certification:ASIL-D qualified microcontrollers command 40-60% price premiums, creating margin expansion for suppliers investing in safety architecture design capabilities.
- Battery management system precision requirements:Cell-level voltage and temperature monitoring ICs are opening analog semiconductor specialization opportunities distinct from power device commoditization pressures.
Industry Challenges
- Compound semiconductor process engineering talent:SiC MOSFET fabrication expertise remains concentrated among veterans of telecom and defense substrate programs, with automotive-specific defect density control skills in acute shortage.
- Legacy 12V/48V system coexistence:Electrified platforms must maintain dual-voltage architectures during transition decades, multiplying semiconductor SKU complexity and inventory management burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Asia Automotive Semiconductors Market |
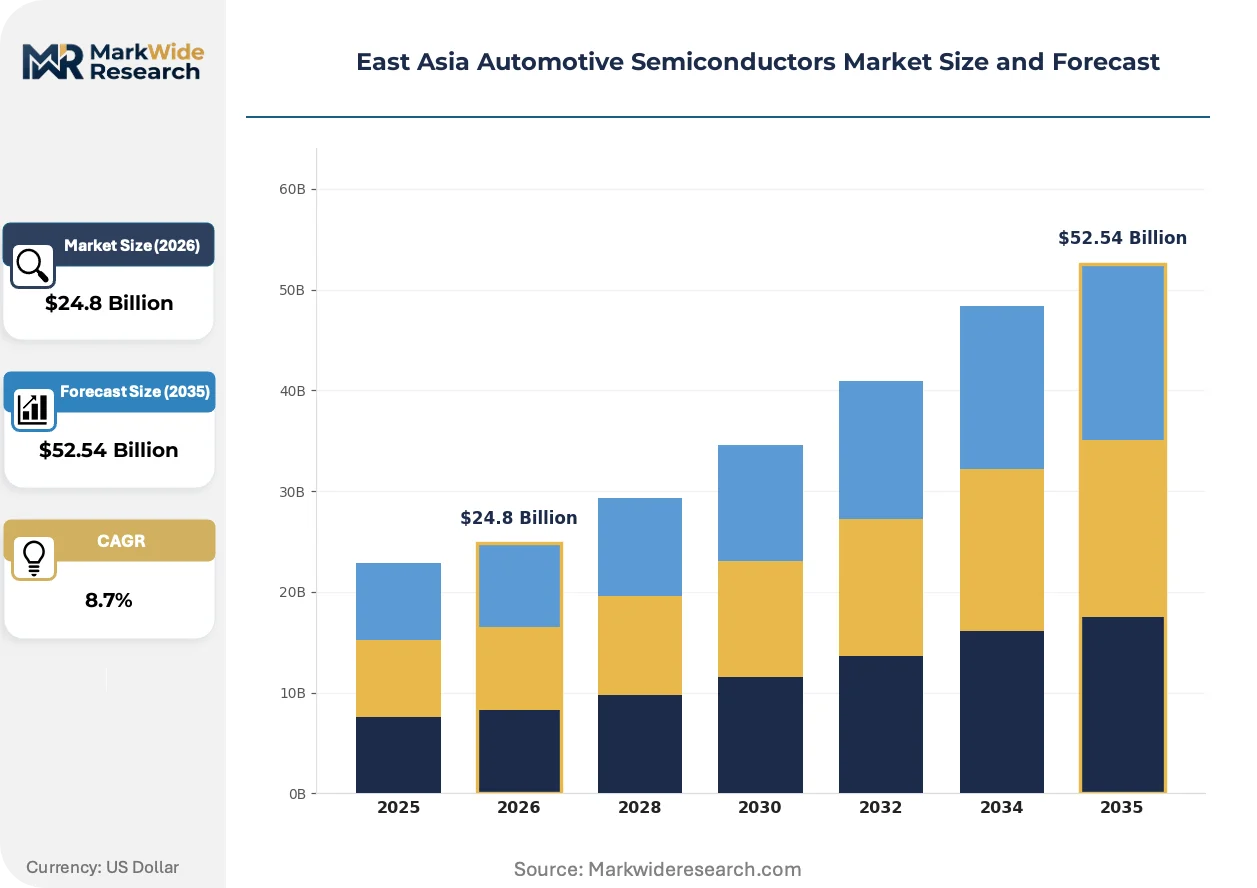
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
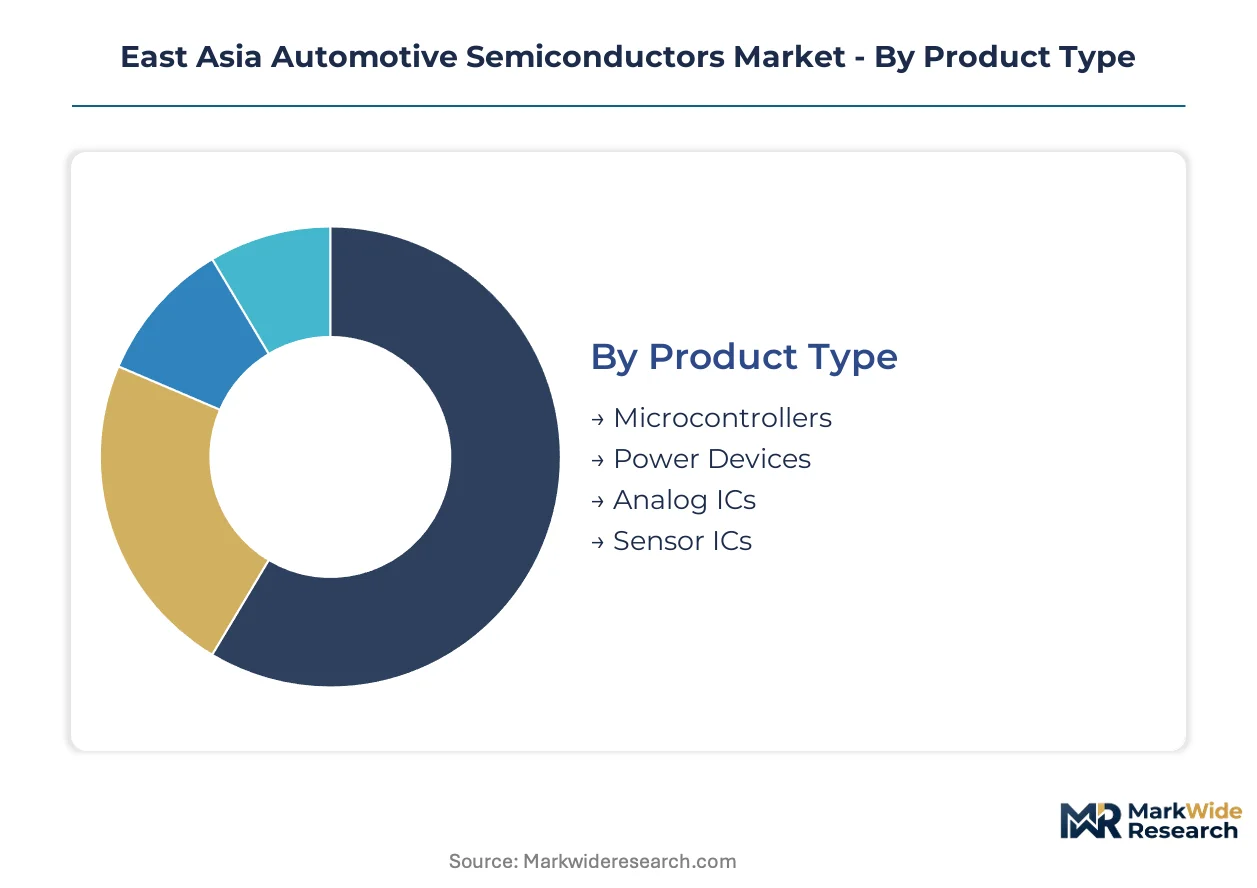
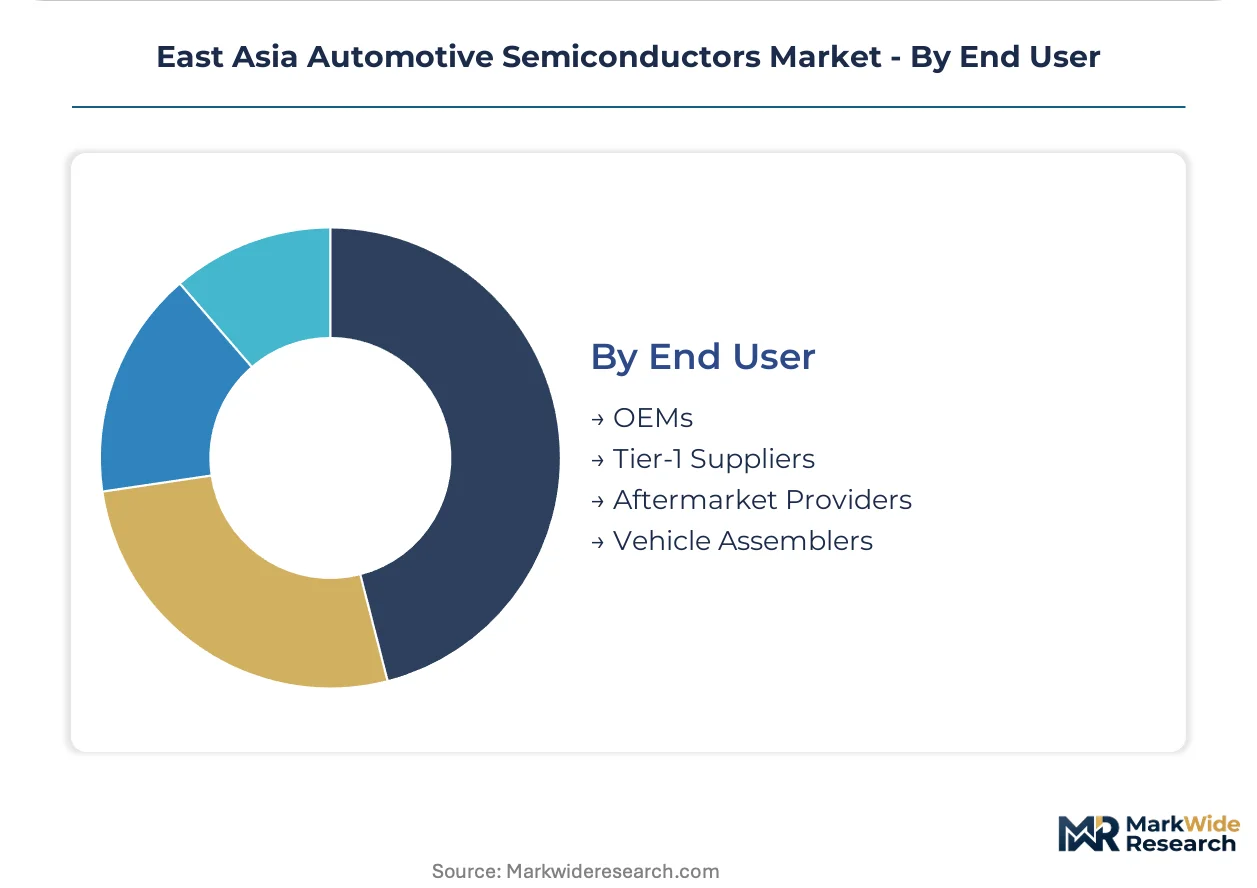
| Segmentation | Product Type: Microcontrollers, Power Devices, Analog ICs, Sensor ICs Technology: Embedded Systems, ADAS, Infotainment, Electric Drive Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | NXP Semiconductors NV, Renesas Electronics Corp, Infineon Technologies AG, STMicroelectronics NV, Texas Instruments Inc, ROHM Co Ltd, Analog Devices Inc, Toshiba Corporation, Samsung Electronics Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Asia Automotive Semiconductors Market Shifts & Advancements
Silicon carbide power electronics are rewriting competitive boundaries in East Asian automotive semiconductors, as substrate quality, module packaging, and system integration capabilities become decisive differentiators beyond traditional silicon process leadership.
Silicon carbide MOSFETs enable inverter switching frequencies above 100kHz with 70% lower switching losses than silicon IGBTs. Chinese OEMs including BYD and NIO are specifying SiC inverters for 2024-2025 platform launches. This is rewriting supplier selection criteria toward substrate sourcing relationships and module thermal management expertise rather than legacy silicon foundry scale.
METI's semiconductor and digital industry strategy is tightening automotive component efficiency mandates through 2030 technology roadmaps. Japanese tier-1 suppliers must demonstrate 50% power loss reduction in traction inverters versus 2020 baselines. Hybrid and plug-in hybrid platforms face disproportionate compliance burden as they maintain dual powertrain semiconductor requirements.
Chinese OEMs are consolidating inverter and onboard charger procurement around domestic module suppliers with captive SiC sourcing. BYD Semiconductor and StarPower are displacing Infineon and STMicroelectronics in mid-market BEV platforms. Tier-1 inverter suppliers in Japan and Korea are responding with joint ventures to secure substrate offtake agreements rather than merchant market purchases.
East Asia Automotive Semiconductors Market Segmentation
Semiconductor upgrade cycles in East Asian automotive platforms vary dramatically by electrification architecture. Component replacement timelines and specification thresholds differ between legacy combustion systems and emerging 800V electric drive platforms.
Product Type:
Upgrade urgency separates mature microcontroller architectures from emerging wide-bandgap power technologies requiring immediate specification jumps.
- Power Devices:Silicon carbide MOSFETs and IGBT modules manage traction inverter switching with thermal tolerance beyond 150 degrees Celsius. China's Yangtze River Delta clustering concentrates procurement for domestic EV platforms, constrained by 6-inch SiC substrate availability from specialist crystal growers.
- Analog ICs:Battery management system precision circuits monitor cell-level voltage and temperature with millivolt accuracy. South Korean OEMs are driving the steepest demand acceleration for isolated gate drivers and current sensing amplifiers in Pyeongtaek corridor supply chains.
- Microcontrollers:Real-time control units execute engine management and chassis functions across AEC-Q100 qualified nodes.
- Sensor ICs:Magnetic position sensors and pressure transducers enable powertrain feedback loops in hybrid architectures.
Volume placements concentrate in Microcontrollers; the faster expansion belongs to Analog ICs.
Technology:
Cost tier stratification separates premium electric drive silicon from commoditized embedded controllers serving mass-market combustion platforms.
- Electric Drive:800V inverter architectures demand SiC MOSFET integration with isolated gate drivers and advanced thermal substrates. Japan's METI efficiency mandates are tightening loss-reduction requirements for traction inverters through 2030 roadmaps.
- ADAS:Sensor fusion processors and radar signal chains enable automated emergency braking and lane-keeping across ASIL-B and ASIL-D safety grades. Chinese OEMs are specifying domestic AI accelerators for camera-perception stacks in premium passenger vehicles.
- Embedded Systems:Legacy 16-bit and 32-bit MCUs persist in body control and HVAC modules across 12V electrical architectures.
- Infotainment:Display drivers and audio DSPs support connected cockpit experiences with moderate automotive qualification thresholds.
Revenue margins peak in Electric Drive; Embedded Systems sustain the highest unit volumes across East Asian production lines.
Application:
Customer type fragmentation splits procurement between fleet operators demanding total-cost optimization and private buyers prioritizing performance specifications.
- Electric Vehicles:Battery-only architectures maximize semiconductor content per vehicle with dedicated BMS, inverter, and OBC silicon. China's dual carbon goals are channeling state procurement incentives toward pure-electric platforms in the Yangtze River Delta manufacturing belt.
- Hybrid Vehicles:Dual powertrain maintenance multiplies semiconductor SKU burden across 12V, 48V, and high-voltage domains simultaneously. Japanese tier-1 suppliers face disproportionate compliance burden under METI roadmaps requiring parallel combustion and electrified component development.
- Passenger Vehicles:Private ownership patterns drive feature differentiation through infotainment and comfort electronics.
- Commercial Vehicles:Fleet uptime requirements prioritize reliability-certified powertrain controllers over advanced driver assistance.
Production volumes dominate Passenger Vehicles; Hybrid Vehicles face the most complex qualification timelines across dual-voltage architectures.
End User:
Supply concentration tilts toward captive tier-1 relationships in Japan against more fragmented OEM-direct procurement patterns emerging in China.
- Tier-1 Suppliers:Denso, Hyundai Mobis, and CATL-affiliated integrators consolidate inverter and BMS procurement with multi-year silicon supply agreements. South Korea's Pyeongtaek corridor foundry investments are shortening lead times for domestic tier-1 platform sourcing.
- OEMs:BYD, Toyota, and Hyundai are bringing power module design in-house through semiconductor joint ventures and captive packaging investments. China's MIIT localization requirements are accelerating domestic OEM vertical integration into SiC substrate sourcing.
- Vehicle Assemblers:Contract manufacturers execute final integration with limited semiconductor specification authority.
- Aftermarket Providers:Replacement controller modules and diagnostic tools serve aging vehicle parc with reduced qualification stringency.
Procurement authority is concentrating in OEMs; tier-1 suppliers retain strongest position in Japanese keiretsu supply structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Japan and South Korea while consumption gravity shifts toward China's EV manufacturing belt. This divergence is reshaping procurement patterns across East Asian supply chains.
China
BYD and NIO are scaling 800V inverter platforms requiring SiC MOSFET modules at volume. MIIT localization mandates are tightening domestic content thresholds for automotive semiconductors. The Yangtze River Delta clustering around Shanghai-Suzhou-Hangzhou is attracting foreign packaging investments to serve domestic OEMs.
Japan
Toyota-affiliated suppliers maintain vertically integrated microcontroller production for hybrid powertrains. METI efficiency roadmaps mandate 50% inverter loss reduction versus 2020 baselines through 2030. The Kanto region around Tokyo anchors Renesas captive fab capacity in Naka and Kofu.
South Korea
Hyundai Mobis is consolidating multi-year silicon supply agreements for domestic EV platforms. MFDS automotive reliability standards gate market access through AEC-Q100 and ISO 26262 certification requirements. The Pyeongtaek semiconductor corridor is expanding foundry capacity to shorten lead times for tier-1 suppliers.
Taiwan
TSMC is extending automotive-grade node production to serve fabless power semiconductor designers. The island's national semiconductor strategy prioritizes automotive qualification infrastructure investment. Hsinchu Science Park clustering concentrates advanced packaging expertise for wide-bandgap devices.
East Asia Automotive Semiconductors Market Competitive Landscape
The competitive structure tilts toward integrated device manufacturers with captive fab capacity and long-standing automotive qualification infrastructure. Vertically integrated Japanese suppliers and European power semiconductor specialists occupy premium positions in microcontroller and SiC module supply. Three archetypes dominate: captive fab integrators, fabless designers with foundry partnerships, and substrate-to-module specialists. Capacity expansion and strategic substrate offtake agreements constitute the primary competitive vectors as SiC supply constraints persist.
Among European power semiconductor specialists, Infineon Technologies AG and STMicroelectronics NV exemplify the substrate-sourcing archetype, anchoring premium inverter module positions through crystal grower relationships. Within the Japanese captive-fab tier, Renesas Electronics Corp occupies a position representing microcontroller supply concentration for tier-1 keiretsu structures. ROHM Co Ltd sits within the integrated substrate-to-device specialist category, reflecting vertical control over SiC boule production.
| Leading Market Players |
|---|
| NXP Semiconductors NV |
| Renesas Electronics Corp |
| Infineon Technologies AG |
| STMicroelectronics NV |
| Texas Instruments Inc |
| ROHM Co Ltd |
| Analog Devices Inc |
| Toshiba Corporation |
| Samsung Electronics Co Ltd |
| Others |
Supply & Pricing Matrix
China's dual carbon goals gate both qualified supply and premium-tier pricing access across East Asian automotive semiconductor procurement. MIIT localization mandates enforce domestic content thresholds that filter non-certified suppliers, while METI efficiency roadmaps in Japan tier pricing by demonstrated loss-reduction performance in traction inverters.
Pricing Analysis
ASIL-D functional safety certification anchors value-based pricing for automotive microcontrollers in East Asian supply chains. Three-tier pricing structure across ASIL-D premium, ASIL-B standard, and non-qualified economy levels separates Renesas captive-fab supply from foundry-sourced alternatives. Cost compression in mid-market SiC modules is intensifying because Chinese OEMs are consolidating procurement around domestic suppliers with captive substrate sourcing. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while premium passenger EV buyers absorb ASIL-D premiums for inverter-grade silicon.
Supply Chain Analysis
Reverse-logistics flows for automotive semiconductor qualification failures concentrate refurbishment activity in Taiwan's Hsinchu Science Park packaging ecosystem. Raw material supply draws from Japanese SiC boule growers, Korean memory-grade wafer foundries, and Chinese rare-earth magnet processors for sensor assemblies. Single-source vulnerability pervades 6-inch SiC substrate supply from specialist crystal growers. Distribution runs through tier-1 supplier consolidation points in Japan's keiretsu structures against OEM-direct procurement patterns emerging in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Asian automotive semiconductors constitute a vertical-integration race where substrate-to-module control determines margin capture. Players are pursuing upstream SiC boule sourcing agreements as the decisive downstream lever for inverter platform wins.
For Market Incumbents: Hedge against Chinese OEM vertical integration by locking multi-year substrate offtake with specialist crystal growers before domestic competitors secure captive supply. Accelerate ASIL-D certification pipelines for next-generation gate drivers to defend premium positioning against emerging fabless designers targeting mid-market BEV platforms. For New Entrants and Emerging Players: Tier-2 Korean EV battery suppliers represent the most penetrable channel partner type for analog IC specialization in cell monitoring and thermal sensing. Target white-space opportunities in 48V mild-hybrid architectures where dual-voltage requirements outpace incumbent SKU breadth. Pursue foundry partnerships with Pyeongtaek corridor capacity holders to bypass AEC-Q100 infrastructure barriers. For Investors and Strategic Acquirers: Infineon losing mid-market BEV inverter share to BYD Semiconductor is the leading indicator that substrate-captive module specialists will consolidate premium positions. Five-to-ten-year viability favors integrated substrate-to-device players with crystal grower relationships over fabless designers exposed to foundry allocation volatility. Monitor tier-1 supplier joint venture announcements for SiC sourcing as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Substrate Sourcing Agreement | Crystal grower relationships determine module output capacity amid 6-inch boule shortage. |
| ASIL-D Certification Investment | Functional safety qualification enables 40-60% price premiums in microcontroller supply. |
| Yangtze River Delta Packaging Investment | Foreign module assembly localization serves MIIT domestic content requirements. |
| Foundry Partnership for Automotive Nodes | Pyeongtaek corridor capacity shortens lead times for Korean tier-1 suppliers. |
| Joint Venture for Inverter Integration | Toyota-affiliated suppliers consolidate procurement to secure SiC supply against Chinese vertical integration. |
Research Methodology
Document review covered MIIT automotive semiconductor localization mandates, METI technology roadmaps, and MFDS reliability standards, complemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, foundry capacity planners, and aftermarket distribution specialists. Secondary validation drew from vehicle production databases, customs trade records for semiconductor imports, and AEC-Q100 qualification registries. Bottom-up segment sizing and top-down market triangulation cross-referenced multiple data streams.
Historical shipment trajectories were cross-referenced against panel input from semiconductor supply chain participants across the analysis window. Segmentation dimensions modeled include power device type, voltage architecture tier, functional safety grade, and regional production cluster affiliation. CAGRs were synthesized from unit-volume projections and content-per-vehicle scaling assumptions tied to 800V platform penetration curves and SiC adoption rates in inverter designs.
Several conditions sit outside the modeled scope, including potential relaxation of China's dual carbon timelines, breakthroughs in 8-inch SiC substrate manufacturing, and geopolitical disruption to Taiwan Strait logistics corridors. Forecasts reflect underlying assumptions about continued AEC-Q100 enforcement and ISO 26262 certification stringency. Practitioners should monitor tier-1 supplier inventory drawdown patterns and foundry utilization reports for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
North America Semiconductor Market
Semiconductors
Global Computer Microchip Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Resistive RAM Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Semiconductor Target Market
Semiconductors
Semiconductor Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Semiconductor IP Market