
 Chiplets Market | 2026-2036
Chiplets Market Size, Share, and Industry Trends Forecast 2026-2036
Chiplets Market Analysis
REACH compliance on substrate materials is consolidating the cost-of-entry calculus for European-bound chiplets, forcing foundries to qualify alternative metallurgies ahead of volume ramps. Intel Corporation leverages its IDM model to sustain captive advanced packaging capacity in Arizona and Ireland. AMD anchors its product roadmap to chiplet-based CPU and GPU architectures, competing directly with monolithic alternatives from NVIDIA Corporation, which dominates AI accelerator chiplet stacking through TSMC CoWoS capacity allocations.
Chiplets are discrete, functionally specialized semiconductor dies that interconnect via high-density interfaces such as UCIe to form a complete system-in-package, enabling yield recovery and process-node mixing for complex processors. The primary industrial purpose centers on cost-efficient scaling of transistor counts beyond the reticle limits of monolithic lithography. Compute chiplets currently occupy the largest value pool as CPU and GPU logic disaggregates into tiled architectures, while memory chiplets lead growth velocity through HBM3E and future HBM4 stacks bound for AI training clusters. Interface chiplets sustain margin concentration where proprietary I/O protocols differentiate platform ecosystems.
The U.S. Department of Commerce Bureau of Industry and Administration, the EU Chips Act implementation bodies, and China's MIIT all impose divergent export controls and subsidy conditions on advanced packaging equipment and substrate materials. These frameworks fragment procurement strategies, forcing chiplet designers to maintain parallel qualification tracks for geographically restricted supply chains. Stakeholders must monitor which sovereign semiconductor programs secure priority access to leading-edge interposer capacity before committing architecture roadmaps to specific packaging nodes.
Market Dynamics
Advanced packaging capacity scarcity at TSMC is forcing chiplet architects to redesign floorplans around available CoWoS interposer supply rather than optimal performance targets, compressing product development timelines and locking in suboptimal die configurations.
Growth Catalysts
- HBM3E memory stacks:AI training clusters from hyperscalers consume advanced packaging capacity at unprecedented scale, pulling silicon interposer demand ahead of supply expansion.
- EU Chips Act subsidies:Sovereign semiconductor programs in Europe are redrawing qualification requirements for substrate materials, accelerating alternative metallurgy development.
- UCIe die-to-die interfaces:Standardized high-density interconnect protocols reduce vendor lock-in and enable multi-source chiplet procurement strategies.
Market Restraints
- Organic substrate shortages:Ajinomoto Build-up Film supply concentration in Japan creates single-point-of-failure risk for 2.5D packaging ramps.
- Reticle stitching limitations:Maximum die size constraints prevent certain monolithic-to-chiplet migrations without architectural fragmentation.
- REACH metallurgy compliance:European chemical regulations force foundries to requalify lead-free solder alternatives, extending certification timelines.
Strategic Opportunities
- India semiconductor ecosystem:PLI scheme incentives and Micron's Gujarat assembly presence create emerging demand for packaged memory chiplets.
- Photonics-electronics convergence:Co-packaged optical I/O chiplets enable bandwidth scaling beyond electrical SerDes limitations for data center switches.
- Automotive zonal architectures:Domain controller disaggregation creates demand for automotive-qualified chiplets with extended temperature ranges.
Industry Challenges
- Interposer design expertise scarcity:Foundry-specific design rule mastery requires years of tapeout experience that cannot be rapidly replicated.
- Multi-die thermal management:3D stacking configurations create hotspots that defeat conventional heat spreader approaches.
- Known-good-die testing economics:Wafer-level burn-in costs for chiplets exceed monolithic die testing by factors that erode yield recovery benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chiplets Market |
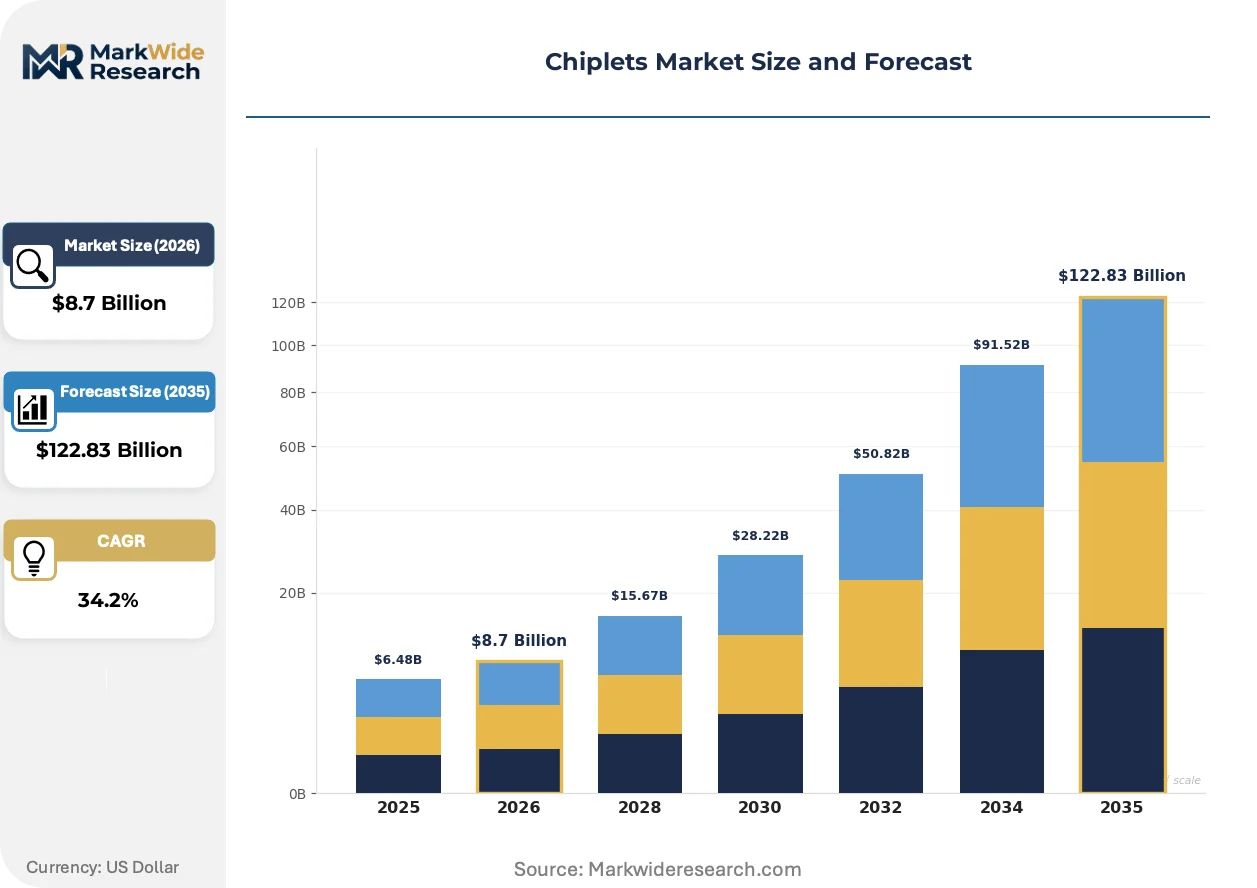
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $122.83 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compute Chiplets, Memory Chiplets, Interface Chiplets, Mixed-Signal Chiplets End User: Consumer Electronics, Data Centers, Automotive, Telecommunications Technology: Silicon Interposer, 3D Packaging, System-on-Chip, Advanced Node Application: Artificial Intelligence, Edge Computing, High-Performance Computing, IoT Solutions |
| Companies Covered | Intel Corporation, Advanced Micro Devices, TSMC, Apple Inc., NVIDIA Corporation, IBM, Marvell Technology, MediaTek Inc., ASE Technology Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chiplets Market Emerging Trajectories
Silicon photonics integration and sovereign manufacturing mandates are restructuring how chiplet ecosystems form, with packaging technology choices now preceding architecture decisions rather than following them.
Hybrid bonding is converging with copper pillar microbumping to enable sub-10 micron pitch die-to-die connections without thermal compression artifacts. Memory vendors are adopting this stack for HBM4 prototypes. The structural consequence is converging with logic-to-memory bandwidth requirements that previously demanded costly silicon interposers.
REACH substance restrictions on substrate core materials are forcing European-bound chiplets through alternative metallurgy qualification tracks. ECHA's candidate list expansion adds brominated flame retardants to scrutiny. Packaging houses serving EU automotive and industrial end-uses are accelerating halogen-free laminate development to preempt supply disruption.
Hyperscalers are consolidating advanced packaging procurement through direct foundry partnerships rather than merchant OSAT channels. This disintermediation concentrates CoWoS allocation decisions within a handful of cloud infrastructure buyers. The shift is most visible in Taiwan, where TSMC's customer engineering teams now embed directly with Microsoft, Amazon, and Google silicon architects.
Chiplets Market Segmentation
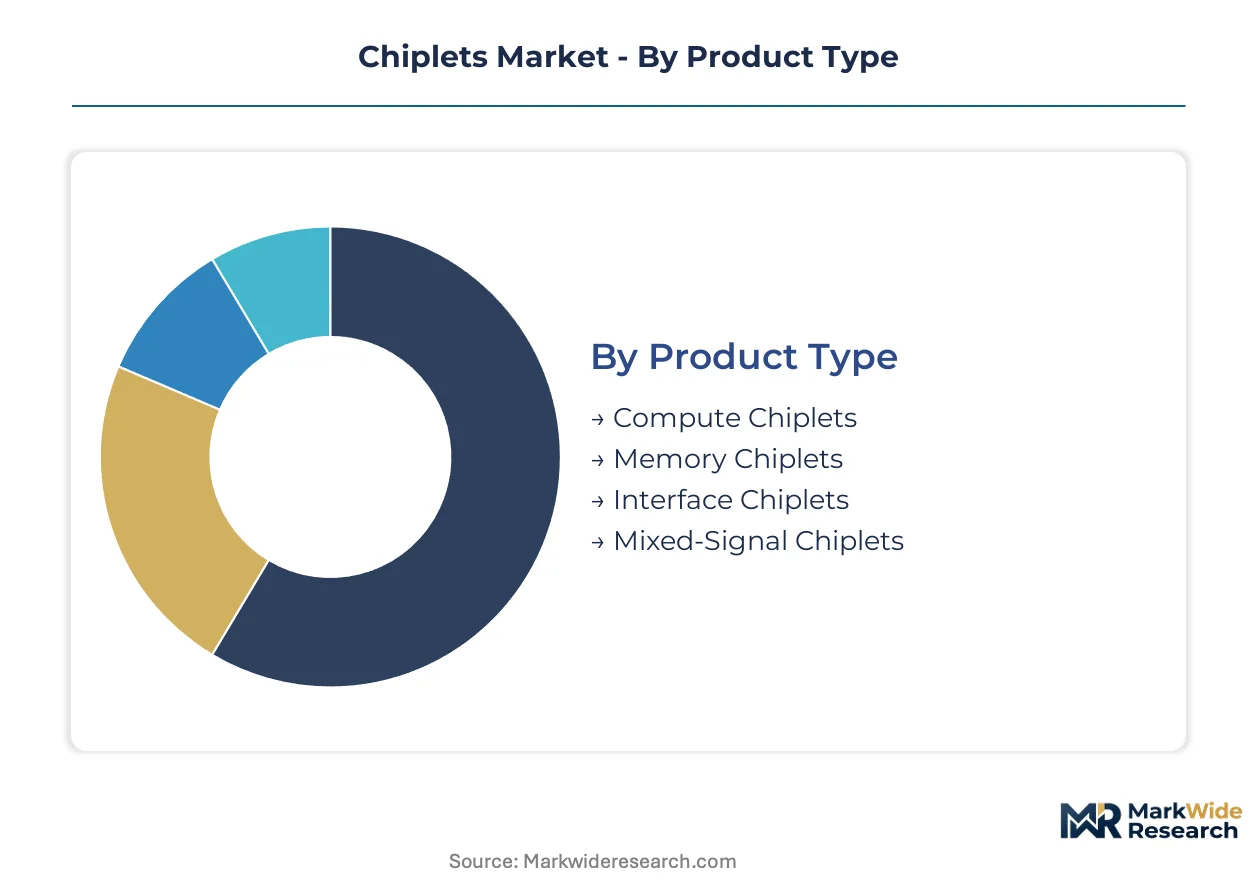
Chiplet architectures fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and qualification requirements. Understanding these segment boundaries helps procurement teams align packaging node selections with end-use reliability specifications.
Product Type:
Upgrade cycles for processor architectures are accelerating as reticle limits force disaggregation, with each chiplet category serving different functional roles within heterogeneous integration.
- Compute Chiplets:CPU and GPU logic tiles fabricated on leading-edge nodes deliver core processing throughput. Hyperscaler AI training clusters in Taiwan and Arizona absorb the majority of advanced CoWoS capacity for these dies.
- Memory Chiplets:HBM3E and emerging HBM4 stacks stack DRAM layers with through-silicon vias. Data center demand for AI accelerators is pulling silicon interposer supply toward memory-logic configurations faster than packaging houses can expand cleanroom footprint.
- Interface Chiplets:SerDes and I/O protocol engines bridge dissimilar process nodes.
- Mixed-Signal Chiplets:Analog and RF functions integrate alongside digital logic.
Compute chiplets sit at the top of the volume ranking, with memory chiplets climbing the fastest.
End User:
Cost tier differentiation separates qualification-intensive automotive deployments from high-volume consumer applications with shorter validation cycles.
- Data Centers:Hyperscaler infrastructure drives CoWoS allocation priority. Microsoft, Amazon, and Google silicon teams embed directly with TSMC customer engineering to secure advanced packaging slots for AI training clusters.
- Automotive:Extended temperature ranges and functional safety requirements demand automotive-qualified chiplets. Zonal E/E architectures are disaggregating domain controllers into specialized tiles.
- Consumer Electronics:Smartphone and PC processors balance performance against thermal constraints.
- Telecommunications:Baseband and radio chiplets serve 5G infrastructure deployments.
Data center deployments command the highest absolute spend, while automotive qualification tracks are expanding most quickly.
Technology:
Application requirements dictate packaging density, with bandwidth-hungry workloads forcing migration toward hybrid bonding and sub-10 micron pitches.
- Silicon Interposer:2.5D integration with embedded traces enables high-bandwidth memory attachment. TSMC CoWoS capacity scarcity is forcing architects to redesign floorplans around available interposer supply rather than optimal targets.
- 3D Packaging:Vertical die stacking with hybrid bonding achieves sub-10 micron pitch without thermal compression artifacts. Memory vendors are prototyping HBM4 configurations using this approach.
- System-on-Chip:Traditional monolithic integration persists at mature nodes.
- Advanced Node:Leading-edge lithography for logic chiplets.
Silicon interposer volumes dominate current procurement, with 3D packaging gaining share fastest as hybrid bonding matures.
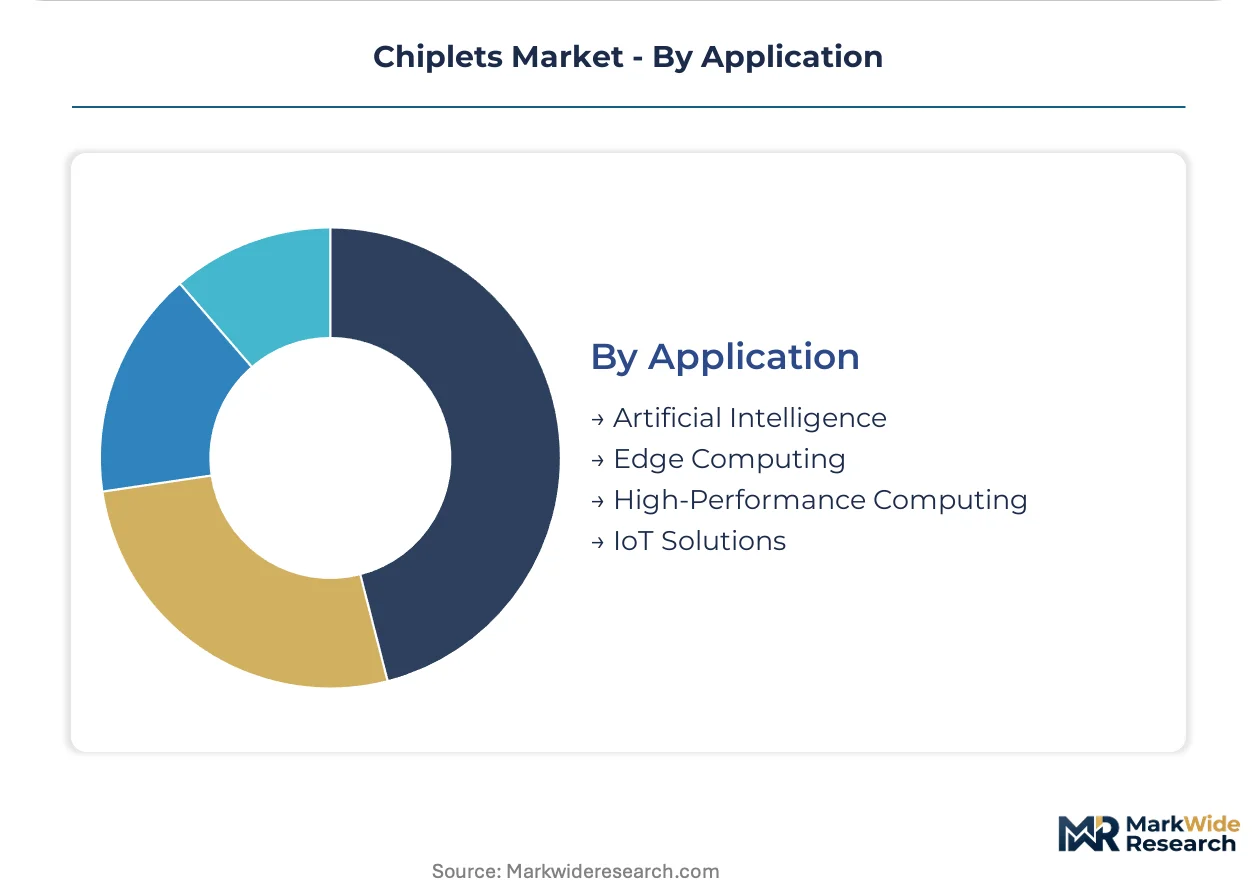
Application:
Customer type concentration creates divergent thermal and latency specifications, separating always-on training infrastructure from intermittent edge inference workloads.
- Artificial Intelligence:Training and inference accelerators disaggregate matrix engines, memory controllers, and I/O into specialized tiles. NVIDIA's dominance in AI chiplet stacking flows through TSMC CoWoS capacity allocations.
- High-Performance Computing:Exascale systems mix process nodes for optimal power-performance. National laboratories in the US and EU sovereign programs are securing dedicated advanced packaging capacity.
- Edge Computing:Distributed inference requires low-latency chiplets with constrained power budgets.
- IoT Solutions:Sensor fusion and connectivity integration at minimal cost points.
Artificial intelligence applications absorb the largest CoWoS allocation, with edge computing expanding most quickly as inference distributes toward data sources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized packaging engineers and interposer design talent concentrate in Taiwan, the United States, and Germany, anchoring the geographic distribution of chiplet innovation. Foundry ecosystems in Hsinchu and Phoenix attract semiconductor architects from global talent pools. Sovereign manufacturing programs in Europe and Asia are redrawing where advanced packaging capacity expands.
United States
Hyperscaler AI training clusters in Arizona and Oregon absorb CoWoS-equivalent packaging capacity as cloud infrastructure scales. The CHIPS and Science Act directs Department of Commerce subsidies toward domestic advanced packaging fabs. Intel's Hillsboro and Santa Clara engineering centers sustain captive interposer design expertise for IDM production.
Taiwan
TSMC's Hsinchu Science Park anchors global silicon interposer supply for NVIDIA and AMD AI accelerators. The National Science and Technology Council coordinates foundry-university partnerships to expand packaging engineering pipelines. Taichung's emerging fab complex is absorbing hybrid bonding equipment for next-generation HBM4 prototyping.
China
Domestic AI chip designers in Shanghai and Beijing are accelerating chiplet roadmaps to circumvent advanced lithography restrictions. MIIT's integrated circuit industry guidance funds local advanced packaging consortiums. Wuxi's OSAT cluster is expanding 2.5D interposer capacity for memory-logic integration serving regional server markets.
Germany
Automotive zonal architecture programs in Stuttgart and Munich are qualifying chiplet-based domain controllers for extended temperature ranges. ECHA's REACH substance restrictions are forcing substrate metallurgy requalification ahead of volume ramps. Dresden's Silicon Saxony cluster is attracting EU Chips Act funding for heterogeneous integration pilot lines.
South Korea
Memory vendors in Icheon and Pyeongtaek are prototyping HBM4 stacks using hybrid bonding for sub-10 micron pitch connections. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative subsidizes advanced packaging equipment imports. Samsung's Giheung complex is converging logic and memory packaging expertise for vertical integration.
Chiplets Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the chiplet ecosystem, creating a tiered competitive structure. Foundries with captive advanced packaging capacity face merchant OSATs expanding interposer offerings. Three archetypes dominate: IDM-integrated device manufacturers controlling full stack production, fabless designers outsourcing to foundry partners, and dedicated packaging houses specializing in multi-die integration. Capacity expansion and strategic partnerships constitute the primary competitive moves, with players securing CoWoS allocation through direct customer engineering relationships.
Within the IDM-integrated tier, Intel Corporation and Advanced Micro Devices exemplify divergent strategic positioning. Intel's manufacturing footprint spans Arizona and Ireland with captive packaging operations. AMD's fabless model anchors to TSMC's CoWoS capacity through dedicated allocation agreements. NVIDIA Corporation occupies a distinctive position as a fabless designer commanding priority interposer access for AI training accelerators.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices |
| TSMC |
| Apple Inc. |
| NVIDIA Corporation |
| IBM |
| Marvell Technology |
| MediaTek Inc. |
| ASE Technology Holding Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed foundry expansions in Arizona and Dresden are consolidating pricing power among captive advanced packaging operators while forcing merchant houses to absorb substrate metallurgy requalification costs. This ownership pattern concentrates supply discipline at the interposer layer and compresses margins for OSATs serving automotive qualification tracks.
Pricing Analysis
Bundled CoWoS capacity-with-design-services commands substantial premiums over unbundled interposer-only procurement. Pricing stratifies across AI accelerator, automotive-qualified, and consumer-grade tiers based on thermal cycling certification and TSMC customer engineering access. Cost compression in standard-tier memory chiplets is intensifying because Ajinomoto Build-up Film supply constraints force packaging houses to absorb material premiums. Hyperscaler direct foundry partnerships exhibit the lowest price sensitivity, while automotive tier-two suppliers face acute margin pressure from REACH compliance-driven substrate switches.
Supply Chain Analysis
Regional distribution centers for advanced packaging equipment cluster in Hsinchu, Phoenix, and Dresden, creating hub-and-spoke patterns that concentrate spare parts logistics around TSMC and Intel captive facilities. Taiwan, South Korea, and the United States anchor silicon interposer fabrication, drawing from ABF substrate laminates, high-purity copper pillar bumping materials, and EUV-grade photoresists. Single-source vulnerability in Japanese ABF supply creates structural risk for 2.5D packaging ramps. Distribution runs through direct foundry partnerships rather than merchant OSAT channels for AI training cluster procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on hybrid bonding yield improvements that reduce CoWoS dependency and enable premium-tier HBM4 stacking economics.
For Market Incumbents: To counter TSMC CoWoS allocation scarcity, Intel and AMD must deepen captive packaging capacity in Arizona and Ireland while securing multi-year ABF substrate offtake agreements with Ajinomoto. Certification investment in automotive extended-temperature chiplets provides channel control against emerging Korean memory vendors. For New Entrants and Emerging Players: The EU Chips Act in Germany opens a window for packaging houses to capture automotive zonal architecture demand through Dresden-based heterogeneous integration pilot lines. White-space targets include India PLI-subsidized memory assembly and photonics-electronics convergence for data center switches. Go-to-market positioning through direct OEM engineering partnerships bypasses established foundry channel congestion. For Investors and Strategic Acquirers: Hyperscaler silicon architecture teams are the most active acquirer in this space, prioritizing advanced packaging design expertise over fabrication assets. Long-term viability favors targets with tapeout experience in hybrid bonding and UCIe protocol implementation. The signal to watch is TSMC customer engineering team embedding patterns with cloud infrastructure buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | Enables sub-10 micron pitch HBM4 prototyping without silicon interposer dependency. |
| Direct Foundry Partnership Formation | Secures CoWoS allocation priority for NVIDIA and AMD AI accelerator roadmaps. |
| Automotive Qualification Track Investment | Captures zonal E/E architecture demand from Stuttgart and Munich OEM programs. |
| ABF Substrate Supply Agreement | Mitigates single-point-of-failure risk from Ajinomoto Build-up Film concentration. |
| UCIe Protocol Standardization | Reduces vendor lock-in and enables multi-source chiplet procurement for hyperscalers. |
Methodological Framework
Bottom-up data center procurement modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with TSMC customer engineering directors, Intel packaging operations leads, AMD silicon architects, and Ajinomoto substrate technical specialists combined with secondary validation from SEC hyperscaler capex disclosures, Department of Commerce CHIPS Act funding announcements, and ECHA REACH substance restriction updates. Triangulation across these sources ensures alignment between reported capacity expansion and actual allocation patterns.
Input-output matrices connect interposer supply constraints to AI accelerator shipment forecasts across the projection horizon. Segmentation dimensions modeled include chiplet functional type, end-use reliability tier, packaging technology node, and regional sovereign program eligibility. CAGRs derive from elasticity-adjusted capacity absorption curves and foundry utilization rate assumptions. Industry-specific forecast inputs encompass HBM3E to HBM4 transition timelines and EU automotive qualification cycle durations.
Revisions become necessary when export control scope expansions, REACH substance list updates, or hybrid bonding yield inflections materialize. Forecasts reflect documented assumptions regarding CoWoS capacity expansion schedules and substrate material qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Smartphone Battery Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Resistive RAM Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Semiconductor IP Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Asia Pacific Flash Memory Market