
 Indium Phosphide Compound Semiconductor Market | 2026-2036
Indium Phosphide Compound Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Indium Phosphide Compound Semiconductor Market Foresight
The EU F-Gas Regulation is consolidating demand for lower-carbon epitaxial growth processes across European photonics supply chains. IQE plc leverages its multi-site epitaxy platform to sustain wafer supply for high-speed optical components. JX Nippon Mining & Metals Corporation anchors upstream indium refining and substrate crystal growth, while Sumitomo Electric Industries Ltd. differentiates through vertical control from raw material to device packaging.
Indium phosphide compound semiconductors are III-V binary semiconductors with a direct bandgap of 1.34 eV and electron mobility exceeding 5,400 cm²/V·s at room temperature, manufactured primarily via liquid-encapsulated Czochralski crystal pulling followed by metalorganic chemical vapor deposition epitaxy for optoelectronic and high-frequency applications. InP-based Lasers dominate current revenue as datacenter optical interconnects scale to 800G and beyond, while Optoelectronics technology captures the fastest growth trajectory as silicon photonics co-packaging architectures multiply InP laser die counts per switch. RF Technology applications in phased-array radar and satellite communications represent mature, high-margin niches where defense qualification cycles protect incumbent positions.
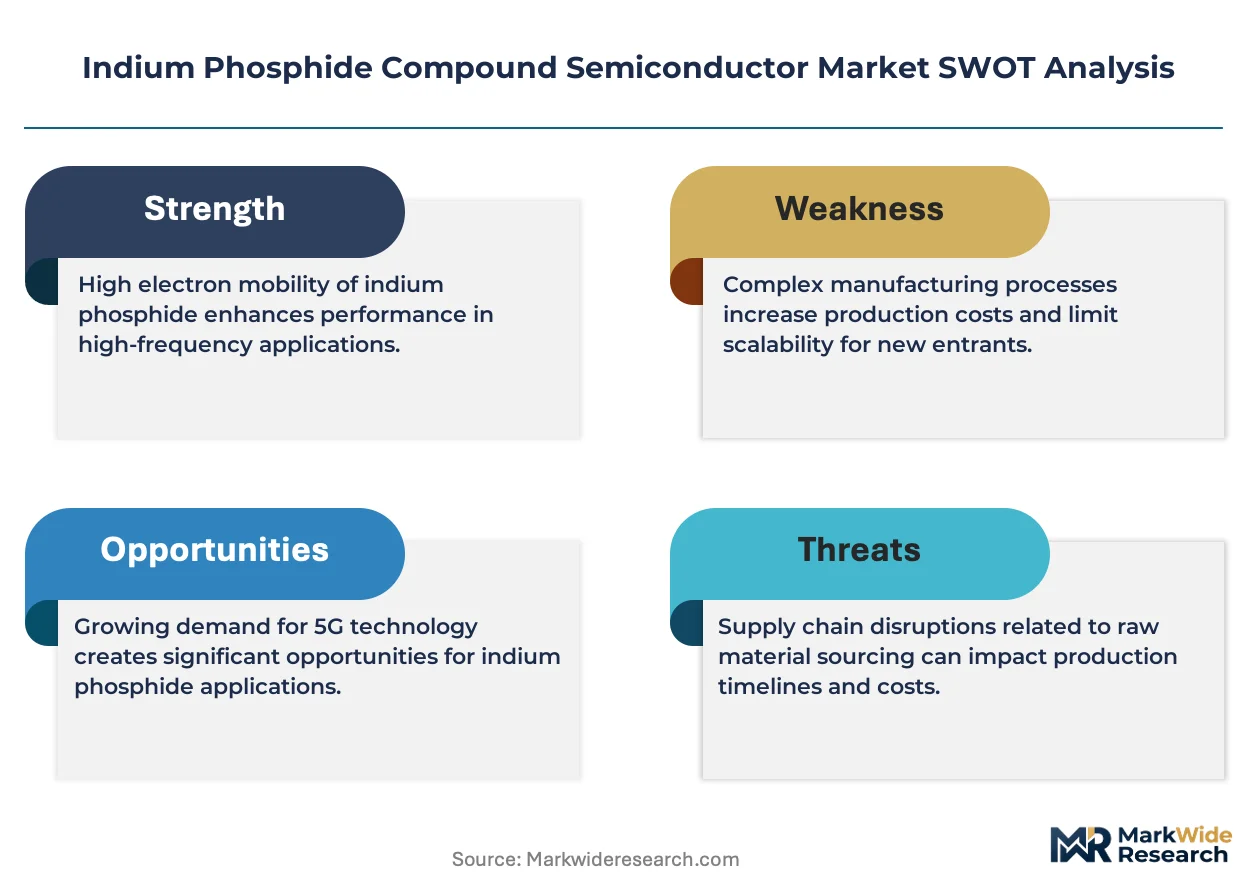
The EPA regulates indium compound handling under TSCA Section 8(a) reporting requirements, while the EU REACH framework governs substance registration across imported InP wafers and process chemicals. Japan's METI enforces JIS standards for compound semiconductor quality certification that constrain non-qualified suppliers from aerospace and medical device supply chains. Stakeholders must monitor evolving restrictions on per- and polyfluoroalkyl substances in wet processing chemistries, as these could force capital-intensive transitions in substrate preparation and epitaxial reactor cleaning protocols.
Market Dynamics
Datacenter transceivers for 800G/1.6T optical interconnects are compressing product lifecycles and forcing epitaxy houses to synchronize capacity expansion with hyperscaler deployment schedules. This demand pulse is restructuring foundry-wafer relationships across the supply chain.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in semiconductor manufacturing are consolidating demand for lower-carbon epitaxial growth processes across European photonics supply chains.
- Silicon photonics co-packaging:Co-packaged optics architectures are multiplying InP laser die counts per switch, accelerating volume requirements for high-speed optical components.
- Arizona and Texas clusters:Major foundry and photonics packaging expansions in these states are concentrating procurement power and pulling substrate supply westward.
Market Restraints
- Indium refining concentration:Upstream indium supply concentrates among a limited set of mining and refining operators, creating vulnerability to geopolitical disruption or export restrictions.
- Defense qualification cycles:RF applications in phased-array radar and satellite communications require extended certification timelines that freeze out new entrants regardless of technical capability.
- Per- and polyfluoroalkyl substance restrictions:Evolving constraints on PFAS in wet processing chemistries threaten to force capital-intensive transitions in substrate preparation and epitaxial reactor cleaning protocols.
Strategic Opportunities
- Co-packaged optics proliferation:The convergence of InP lasers with silicon photonics interposers is opening white space in optical I/O for AI training clusters and high-performance computing fabrics.
- Japan METI quality certification:JIS standards for compound semiconductor quality create defensible positioning for qualified suppliers in aerospace and medical device supply chains.
- Defense RF modernization:Phased-array radar and satellite communications upgrades are sustaining high-margin demand for InP-based millimeter-wave components with multi-year program visibility.
Industry Challenges
- Metalorganic precursor supply security:Trimethylindium and phosphine sourcing requires specialized handling infrastructure and qualified logistics partners, constraining rapid capacity scaling.
- Epitaxy equipment lead times:Metalorganic chemical vapor deposition reactor procurement cycles extend 18-24 months, mismatching capital deployment with demand windows.
- Cross-border chemical compliance:TSCA Section 8(a) reporting requirements in the United States and EU REACH substance registration create documentation burdens that slow wafer shipment velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indium Phosphide Compound Semiconductor Market |
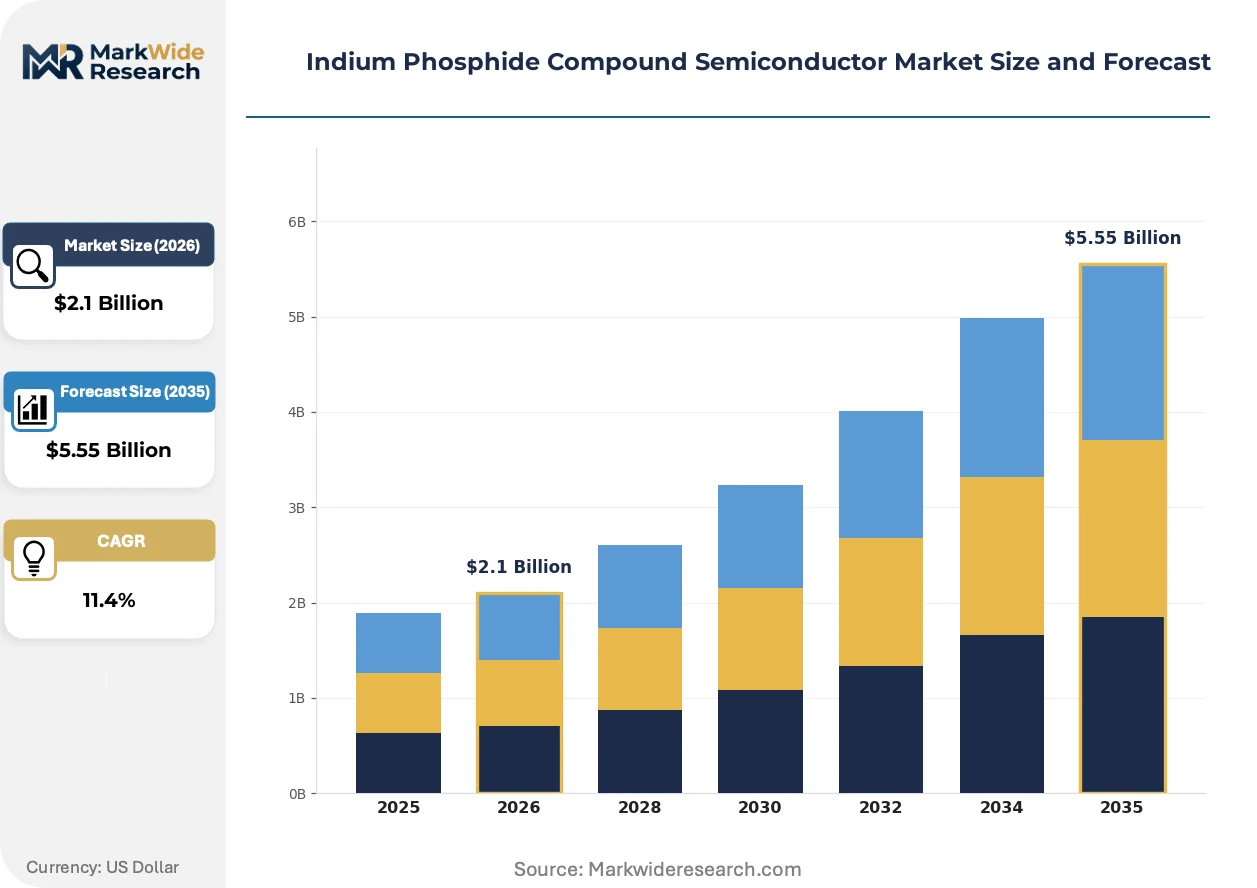
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: InP Substrates, InP-based Lasers, InP Photodetectors, InP-based Detectors Application: Telecommunications, Consumer Electronics, Aerospace, Military End User: Data Centers, Research Institutions, Telecommunication Firms, Medical Devices Technology: MEMS, Optoelectronics, RF Technology, High-Speed Switching |
| Companies Covered | IQE plc, JX Nippon Mining & Metals Corporation, AXT Inc., Infinera Corporation, MACOM Technology Solutions, Sumitomo Electric Industries Ltd., Intelligent Epitaxy Technology Inc., CoorsTek, II-VI Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indium Phosphide Compound Semiconductor Market Shifts & Advancements
Optical interconnect density requirements are forcing simultaneous innovation in laser die efficiency, thermal management, and packaging automation. These pressures are compressing development timelines and rewarding integrated process control.
800G/1.6T pluggable transceivers are rewriting power-per-bit benchmarks for datacenter optical interconnects. Hyperscalers are qualifying these modules for spine-leaf architectures at unprecedented pace. This technology is rewriting foundry capacity allocation as epitaxy houses prioritize high-volume laser arrays over legacy RF device production.
REACH substance registration across imported InP wafers and process chemicals is tightening chemical traceability requirements for European photonics manufacturers. Industrial consequence includes mandatory supply chain documentation and third-party testing protocols. European datacenter transceiver assemblers are responding by consolidating supplier bases to reduce compliance fragmentation.
Hyperscaler direct sourcing of InP epiwafers is displacing traditional tiered distribution through merchant optical component vendors. Datacenter operators are securing multi-year wafer supply agreements that bypass established channel relationships. This pattern is most visible in the United States, where Arizona and Texas facility expansions have concentrated procurement decision-making among a handful of cloud infrastructure architects.
Indium Phosphide Compound Semiconductor Market Segmentation
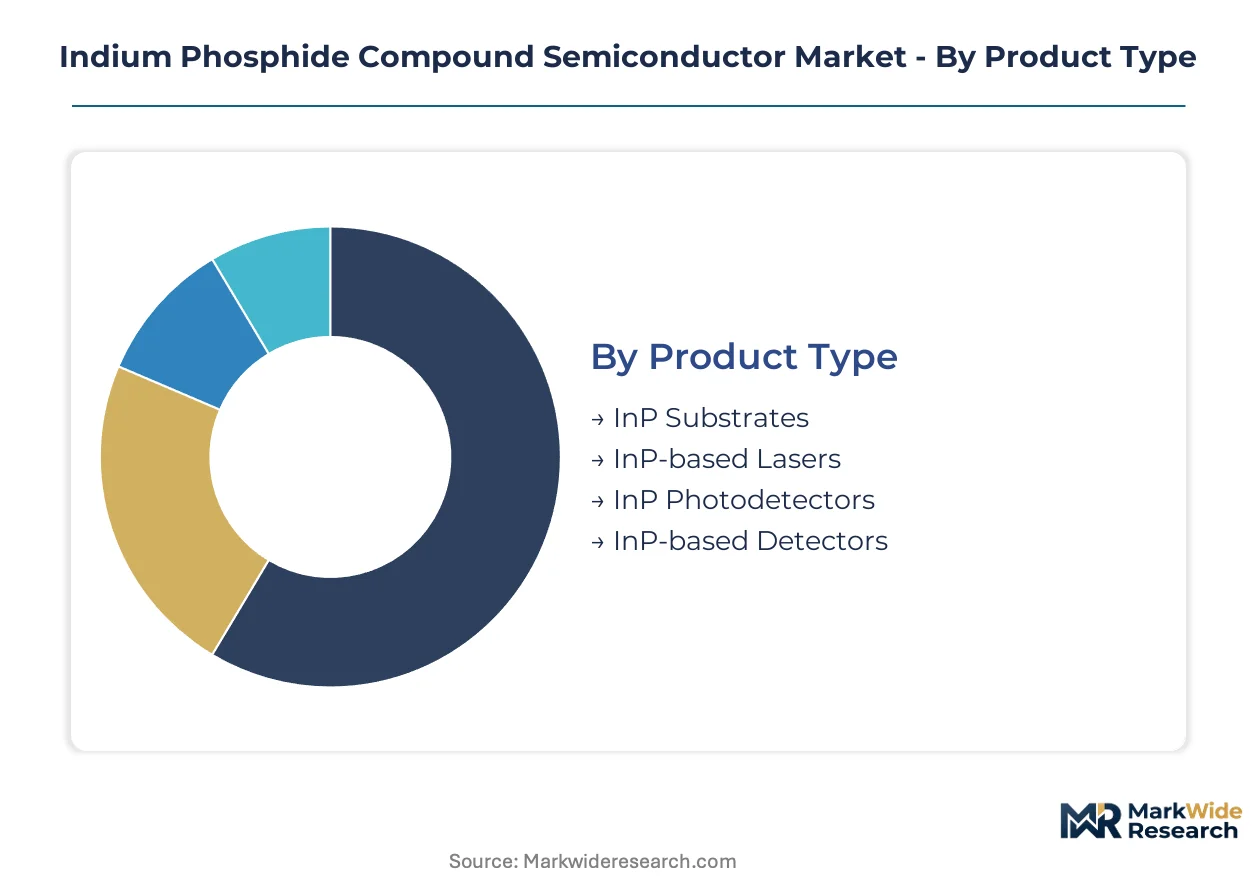
Datacenter transceivers for 800G/1.6T optical interconnects are fragmenting procurement patterns across the InP value chain. Epitaxy houses must now align capacity with hyperscaler deployment schedules rather than traditional telecom cycles. This compression forces granular segmentation to capture where volume concentrates versus where margins hold.
Product Type:
Upgrade cycles in optical interconnects are driving differential demand across InP product categories as datacenter architects specify new performance tiers.
- InP-based Lasers:Direct-bandgap emitters operating at 1310nm and 1550nm wavelengths serve as the primary light source for high-speed optical transceivers. Datacenter spine-leaf architectures in Arizona and Texas are pulling wafer supply toward distributed feedback and electro-absorption modulated laser designs.
- InP Substrates:Single-crystal wafers manufactured via liquid-encapsulated Czochralski pulling provide the lattice-matched foundation for epitaxial growth. JX Nippon Mining & Metals Corporation and Sumitomo Electric Industries Ltd. control upstream crystal growth, constraining rapid capacity scaling for 100mm and 150mm diameters.
- InP Photodetectors:PIN and avalanche photodiode structures convert optical signals to electrical current in receiver assemblies.
- InP-based Detectors:Integrated photodetector arrays support coherent detection schemes for long-haul and metro networks.
InP-based Lasers sits at the top of the volume ranking, with InP Substrates climbing the fastest as foundry expansions strain crystal growth capacity.
Application:
Cost-tier differentiation separates mission-critical deployments from volume-driven consumable optics.
- Telecommunications:Long-haul fiber networks and 5G fronthaul infrastructure consume InP lasers in pluggable and embedded optical modules. Carrier procurement cycles extend 24-36 months, locking in supplier relationships through multi-year frame agreements.
- Aerospace:Satellite optical inter-satellite links and phased-array radar systems demand radiation-hardened InP components with extended qualification timelines. Japan's METI JIS standards constrain non-qualified suppliers from this high-margin niche.
- Consumer Electronics:LiDAR and optical sensing applications in autonomous vehicles and augmented reality headsets.
- Military:Secure communications and electronic warfare systems require ITAR-controlled supply chains with domestic sourcing mandates.
Telecommunications commands the largest revenue pool, though Aerospace delivers the steepest expansion trajectory as constellation deployments multiply.
End User:
Customer-type concentration is restructuring distribution as hyperscalers bypass traditional channel relationships.
- Data Centers:Cloud infrastructure operators are securing direct multi-year wafer supply agreements that displace merchant optical component vendors. Co-packaged optics architectures multiply InP laser die counts per switch, accelerating volume requirements for high-speed optical components.
- Telecommunication Firms:Incumbent carriers maintain tiered supplier bases with qualification requirements that freeze out new entrants regardless of technical capability.
- Research Institutions:National laboratories and university consortia drive early-stage epitaxy process development.
- Medical Devices:Optical coherence tomography and laser surgical equipment require biocompatible packaging and ISO 13485 quality certification.
Data Centers dominate procurement volume, with Medical Devices gaining share fastest as minimally invasive surgical applications expand.
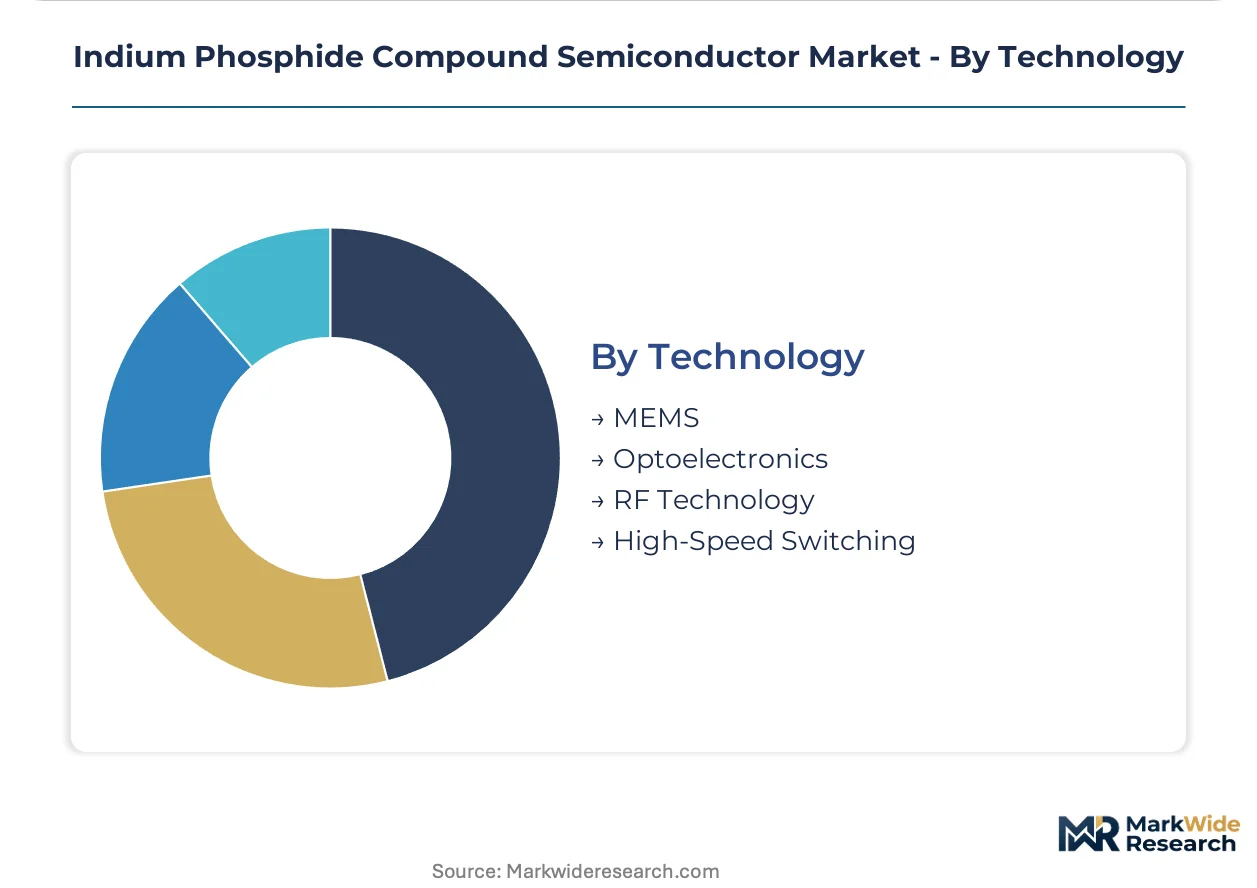
Technology:
Supply concentration in epitaxy equipment creates bottlenecks that favor integrated process control across technology categories.
- Optoelectronics:Integration of InP lasers with silicon photonics interposers enables optical I/O for AI training clusters and high-performance computing fabrics. Metalorganic chemical vapor deposition reactor procurement cycles extend 18-24 months, mismatching capital deployment with demand windows.
- RF Technology:Millimeter-wave monolithic integrated circuits for phased-array radar and satellite communications sustain high-margin demand with multi-year program visibility. Defense qualification cycles protect incumbent positions regardless of technical capability.
- MEMS:Micro-electromechanical systems leverage InP piezoelectric properties for RF filtering and sensing applications.
- High-Speed Switching:Heterojunction bipolar transistors and high-electron-mobility transistors enable terabit-scale data processing.
Optoelectronics leads technology investment, with RF Technology maintaining the most defensible margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide compound semiconductor manufacturing traces its industrial lineage to Japan's post-war electronics expansion, where Sumitomo Electric and Nippon Mining established the foundational crystal growth and refining capabilities that now supply global photonics markets.
United States
Datacenter operators in Arizona and Texas are securing direct multi-year wafer supply agreements that displace traditional merchant optical component vendors. EPA TSCA Section 8(a) reporting requirements govern indium compound handling and constrain rapid shipment velocities. Phoenix and Austin metropolitan clusters concentrate foundry expansions and photonics packaging investments that pull substrate supply westward from historical East Coast distribution channels.
Japan
METI enforces JIS standards for compound semiconductor quality certification that protect incumbent suppliers in aerospace and medical device supply chains from non-qualified competitors. Domestic producers maintain backward integration from raw material refining through device packaging. Osaka and Nagoya industrial corridors anchor substrate crystal growth capacity and epitaxial wafer production for high-speed optical components.
China
MIIT oversees national semiconductor self-sufficiency programs that channel investment into compound materials and photonics manufacturing equipment. Domestic demand for 800G transceivers accelerates local epitaxy capacity buildouts. Yangtze River Delta metropolitan clusters concentrate emerging foundry investments and optical module assembly operations serving hyperscaler infrastructure deployments.
Germany
ECHA REACH substance registration requirements tighten chemical traceability mandates for imported InP wafers and process chemicals used in European photonics manufacturing. EU F-Gas Regulation restrictions on fluorinated greenhouse gases consolidate demand for lower-carbon epitaxial growth processes. Bavarian precision optics and semiconductor equipment clusters coordinate with Dutch lithography suppliers to advance silicon photonics integration.
United Kingdom
IQE plc leverages multi-site epitaxy platforms to sustain wafer supply for high-speed optical components serving European and North American datacenter markets. UK Research and Innovation funding programs support compound semiconductor process development at national laboratory facilities. South Wales semiconductor corridor maintains specialized metalorganic chemical vapor deposition capacity for defense and telecommunications applications.
Indium Phosphide Compound Semiconductor Market Competitive Landscape
Capital-heavy substrate producers compete with asset-light epitaxial design houses across tiered supply relationships. Three to five operators control upstream indium refining and crystal growth, while a broader set of foundries manages downstream wafer processing and device fabrication. Strategic archetypes separate integrated miners-refiners from specialized epitaxy houses and merchant substrate vendors. Dominant competitive moves include multi-year supply agreements with hyperscalers and geographic clustering near datacenter construction sites.
Among Japan-based integrated producers, JX Nippon Mining & Metals Corporation and Sumitomo Electric Industries Ltd. occupy positions spanning raw material refining through packaged device supply. IQE plc represents the specialized epitaxy house archetype with multi-site wafer production capabilities. These three companies exemplify contrasting strategic postures: backward-integrated material control versus focused process technology development.
| Leading Market Players |
|---|
| IQE plc |
| JX Nippon Mining & Metals Corporation |
| AXT Inc. |
| Infinera Corporation |
| MACOM Technology Solutions |
| Sumitomo Electric Industries Ltd. |
| Intelligent Epitaxy Technology Inc. |
| CoorsTek |
| II-VI Incorporated |
| Others |
Supply & Pricing Matrix
Backward integration from indium refining through epitaxial wafer production anchors pricing power for Japanese conglomerates while constraining margin capture for asset-light foundries dependent on merchant substrate supply. JX Nippon Mining & Metals Corporation and Sumitomo Electric Industries Ltd. leverage captive indium sourcing to buffer input cost volatility that compresses margins at IQE plc and other specialized epitaxy houses serving Arizona and Texas datacenter clusters.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between hyperscalers and established epitaxy suppliers, with price differentiation hinging on JIS certification tier and volume scale commitments. Premium pricing attaches to aerospace-qualified wafers meeting METI standards, while datacenter volumes trade at thinner margins due to hyperscaler consolidation of procurement power. Cost compression in standard-grade laser arrays intensifies as silicon photonics co-packaging multiplies die counts per switch. Telecommunication firms exhibit lowest price sensitivity given extended qualification timelines, whereas datacenter operators drive hardest bargain through direct multi-year supply agreements.
Supply Chain Analysis
Regional distribution centers in Osaka, Nagoya, and Phoenix coordinate hub-and-spoke patterns for InP wafers and epitaxial services. Upstream supply concentrates in Japan, China, and the United States, with indium refining and crystal growth tethered to JX Nippon and Sumitomo Electric facilities. Raw material dependencies include high-purity indium metal, trimethylindium precursors, and phosphine gas requiring specialized handling infrastructure. Single-source vulnerability in metalorganic precursor supply constrains rapid capacity scaling. Distribution runs through qualified logistics partners with hazardous materials certification to epitaxy houses and foundry customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as datacenter optical interconnect upgrades sustain demand visibility through multi-year hyperscaler deployment cycles.
For Market Incumbents: Hedge against silicon photonics substitution by deepening backward integration into indium refining and securing long-term phosphine supply agreements. Prioritize JIS certification maintenance to defend aerospace and medical device margins from emerging Chinese competitors. Expand MOCVD capacity in Arizona and Texas clusters to align with hyperscaler procurement concentration.
For New Entrants and Emerging Players: The price-point gap between defense-qualified RF components and commodity datacenter lasers offers white-space entry through specialized thermal management solutions for co-packaged optics architectures. Target medical device applications requiring ISO 13485 certification where incumbent qualification backlogs create procurement bottlenecks. Pursue partnership routes with established substrate vendors rather than capital-intensive crystal growth buildout.
For Investors and Strategic Acquirers: Consolidation pressure builds where defense program visibility and datacenter volume scale diverge in valuation multiples. The InP compound semiconductor sector offers 5-10 year demand visibility through optical interconnect density requirements and RF modernization cycles. Acquisition candidates include specialized epitaxy houses with METI-qualified capacity and established hyperscaler relationships. Watch hyperscaler direct sourcing announcements as inflection indicators for merchant optical component vendor displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Hyperscaler direct wafer procurement in Arizona and Texas clusters displaces traditional distribution channels. |
| Backward Integration | Captive indium refining buffers Japanese producers against metal price volatility and export restriction risks. |
| Capacity Expansion | MOCVD reactor deployment in Phoenix and Austin aligns epitaxy output with datacenter construction schedules. |
| Regulatory Certification | METI JIS qualification creates defensible positioning in aerospace and medical device supply chains. |
| Joint Venture | Silicon photonics partnerships combine InP laser expertise with interposer manufacturing capabilities. |
Research Methodology
Bottom-up datacenter transceiver modeling reconciled against top-down substrate supply tracking forms the analytical core of this study. Primary interviews with epitaxy house operations directors, hyperscaler procurement leads, MOCVD equipment suppliers, and compound semiconductor quality certification officers combined with secondary validation from SEC filings, EPA TSCA Section 8(a) disclosure databases, METI JIS certification registries, and EU REACH substance registration records. Triangulation between demand-side deployment schedules and supply-side capacity expansion announcements ensures consistency across volume estimates.
Input-output matrices connect MOCVD reactor installation rates, indium refining capacity utilization, and hyperscaler optical interconnect procurement across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user archetype, and technology platform. CAGRs derive from fitted growth curves anchored to announced foundry expansions and datacenter buildout timelines. Forecast inputs incorporate EU F-Gas Regulation compliance cost trajectories and PFAS restriction scenarios affecting wet processing chemistry.
Caveats apply where export controls on indium metal, accelerated silicon photonics substitution, or PFAS regulatory bans could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Chiplets Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Semiconductor IP Market