
 Europe Digital Signal Processor Market | 2026-2036
Europe Digital Signal Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Signal Processor Market Insights
Silicon carbide is rebalancing cost structures in high-performance DSP modules for electric vehicle powertrains. Infineon Technologies leverages captive SiC wafer capacity to anchor supply for automotive-grade embedded processors. Texas Instruments sustains broad portfolio coverage across industrial automation and telecommunications endpoints. NXP Semicontronicators specializes in domain-control architectures that integrate DSP blocks with ASIC logic for ADAS applications.
A digital signal processor is a specialized microprocessor optimized for mathematical manipulation of digital signals, typically executing multiply-accumulate operations in single clock cycles with fixed-point or floating-point arithmetic units. These devices filter, compress, and decode real-time data streams in applications from radar processing to audio enhancement. Embedded DSP variants command the largest revenue share across European industrial automation and automotive sectors, while AI-based processing architectures represent the fastest-expanding technology segment as neural network inference migrates to edge devices. Network DSP applications in 5G baseband units remain mature with stable margin pools concentrated among established infrastructure suppliers.
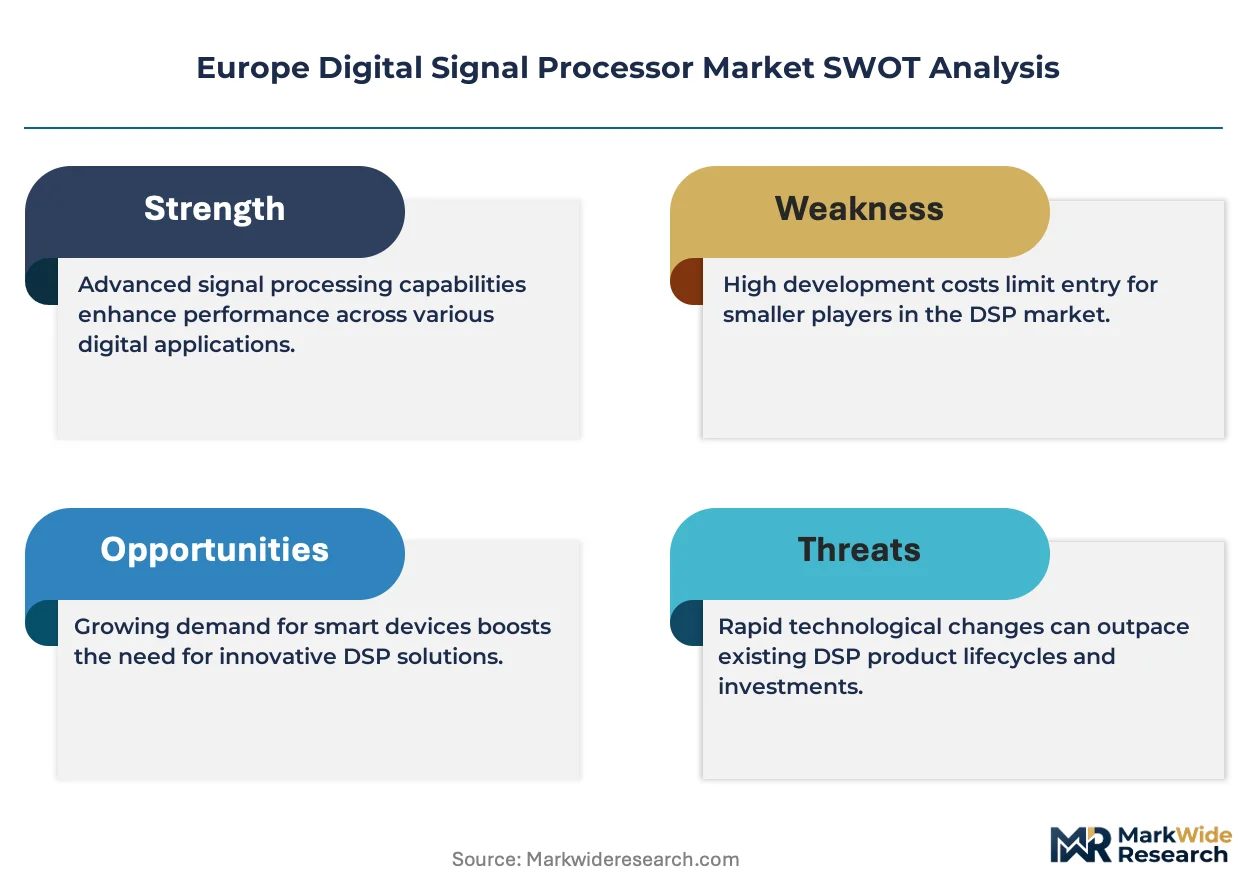
The EU AI Act and CE marking under the Radio Equipment Directive shape product certification requirements for DSP-enabled edge devices deployed in consumer and industrial settings. ECHA REACH compliance governs substance restrictions in semiconductor packaging materials, affecting foundry and assembly choices for European-bound products. Germany's KBA type-approval process for automotive electronics creates additional validation layers that filter non-compliant suppliers from ADAS supply chains. Stakeholders must monitor evolving EU Green Deal sourcing rules for conflict minerals and carbon footprint disclosure as these criteria penetrate procurement specifications for DSP components.
Market Dynamics
Silicon carbide substrate availability is compressing cost curves for automotive-grade embedded processors while EU AI Act compliance deadlines force premature redesign cycles across edge-device portfolios.
Growth Catalysts
- ADAS Platform Expansion:Automotive OEMs across Germany and France are expanding embedded DSP procurement for lane-keeping and sensor-fusion systems. KBA type-approval processes filter non-compliant suppliers, concentrating procurement among validated tier-1s.
- EU AI Act Threshold Tightening:CE marking requirements under the Radio Equipment Directive are elevating compliance thresholds for edge-processing hardware deployed in consumer and industrial settings.
- Silicon Carbide Integration:Captive SiC wafer capacity is anchoring supply for high-performance powertrain modules, rebalancing cost structures in electric vehicle embedded processors.
Market Restraints
- ECHA REACH Substance Restrictions:Compliance governs semiconductor packaging materials, constraining foundry and assembly choices for European-bound DSP products.
- Automotive Validation Layering:Germany's KBA type-approval process creates additional certification timelines that extend product qualification cycles by 12-18 months.
- FPGA Substitution at Edge:Field-programmable gate arrays are capturing inference workloads in low-volume ADAS prototypes where DSP fixed architectures lack flexibility.
Strategic Opportunities
- Industrial Automation Corridor:Embedded DSP variants command revenue concentration across German factory automation, with underpenetrated Polish and Czech manufacturing hubs presenting expansion vectors.
- EU Green Deal Sourcing Rules:Conflict mineral disclosure and carbon footprint reporting are penetrating procurement specifications, creating first-mover advantage for compliant DSP suppliers.
- Neural Network Edge Migration:AI-based processing architectures are expanding fastest as inference workloads shift from cloud to domain-control architectures integrating DSP blocks with ASIC logic.
Industry Challenges
- Multidomain Certification Expertise:Engineers must simultaneously navigate ECHA REACH, CE marking under the Radio Equipment Directive, and KBA automotive validation, creating talent scarcity in regulatory affairs functions.
- Legacy System Integration Friction:5G baseband infrastructure relies on mature network DSP architectures that resist migration to AI-enhanced edge processors without full stack replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Signal Processor Market |
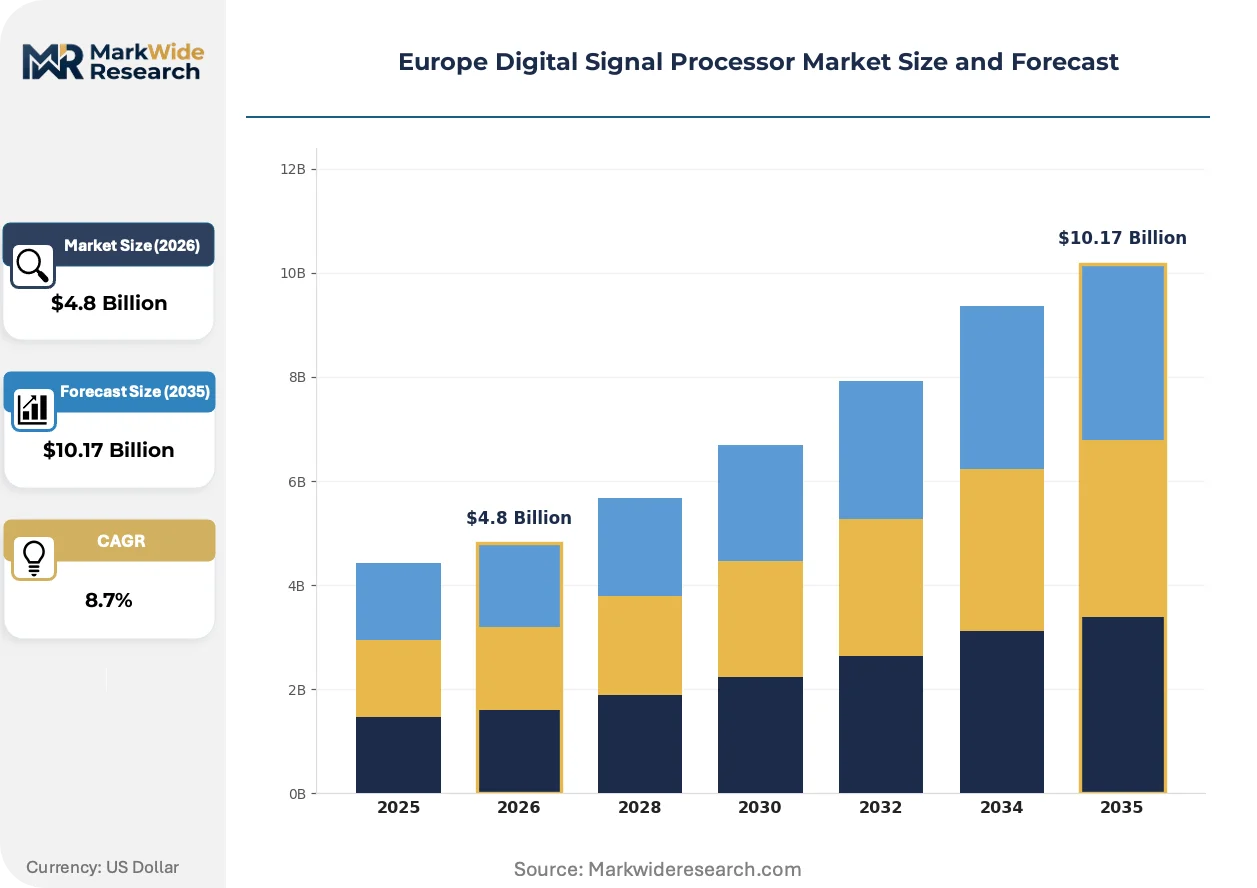
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog DSP, Embedded DSP, Network DSP, Software DSP Application: Consumer Electronics, Telecommunications, Automotive, Industrial Automation End User: Manufacturers, OEMs, System Integrators, Research Institutions Technology: AI-Based Processing, FPGA-Based Processing, Multi-Core Processing, Cloud-Based Processing |
| Companies Covered | Infineon Technologies, Broadcom, Texas Instruments, Renesas Electronics, Intel Corporation, Analog Devices, STMicroelectronics, Xilinx, NXP Semiconductors, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Signal Processor Market Trends and Innovations
Electrification of vehicle platforms is forcing signal-processing architectures toward higher thermal tolerances and real-time deterministic performance. Three developments are compressing design cycles and redrawing competitive boundaries.
Silicon carbide power semiconductors are electrifying thermal management in high-performance DSP modules for electric vehicle powertrains. Automotive tier-1s in Stuttgart and Munich are adopting SiC-integrated embedded processors at accelerated procurement cycles. This substrate transition is compressing cooling system overhead and enabling denser compute packaging in engine-bay environments.
CE marking under the Radio Equipment Directive is tightening electromagnetic compatibility thresholds for DSP-enabled edge devices deployed in consumer settings. Industrial OEMs must redesign shielding and filtering subsystems to meet elevated emission limits. German automotive electronics corridors stretching from Munich to Stuttgart are experiencing the steepest compliance cost inflation as ADAS platforms integrate more radio-frequency processing blocks.
Automotive OEM procurement is consolidating vendor relationships around domain-control suppliers capable of delivering ASIC-DSP integrated architectures. Tier-1 suppliers with captive software stacks are displacing discrete component vendors in ADAS platform awards. This concentration is most visible in France and Germany, where Renault and Volkswagen Group have reduced qualified DSP supplier pools by half since 2023.
Europe Digital Signal Processor Market Segmentation
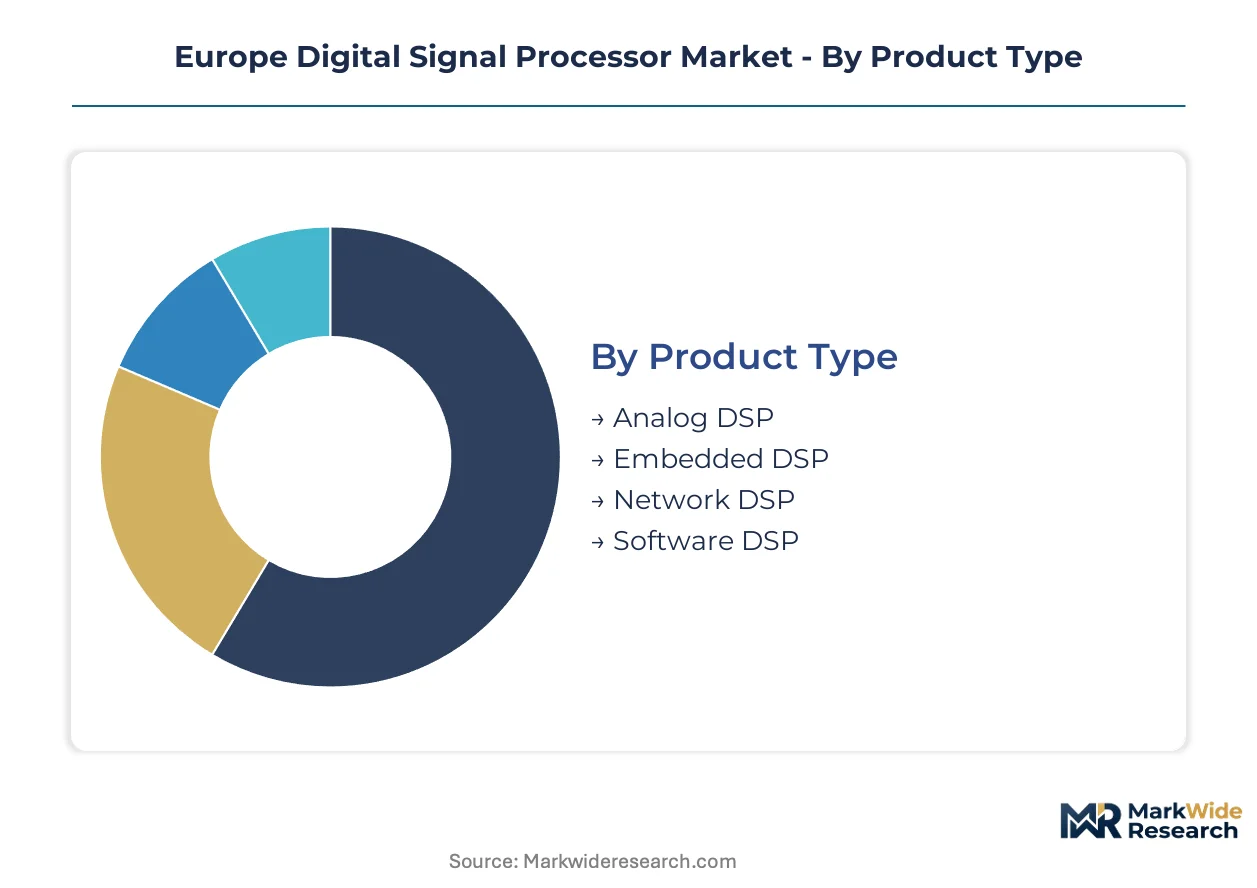
Segmentation in the Europe Digital Signal Processor Market reveals how certification burdens concentrate differently across product architectures and deployment contexts. Understanding these divides helps suppliers allocate engineering resources toward segments with the steepest compliance gradients.
Product Type:
Embedded DSP and Network DSP carry the heaviest CE marking obligations under the Radio Equipment Directive, while Analog DSP faces lighter electromagnetic compatibility thresholds in legacy industrial settings.
- Embedded DSP:These processors integrate fixed-point arithmetic units with real-time operating systems for deterministic signal manipulation. Automotive OEMs in Stuttgart and Munich are expanding procurement for ADAS domain controllers, where KBA type-approval processes filter non-compliant suppliers and extend qualification timelines.
- Network DSP:Specialized architectures handle baseband processing in 5G infrastructure with dedicated multiply-accumulate pipelines. German telecommunications equipment manufacturers concentrate demand here, though ECHA REACH substance restrictions in semiconductor packaging constrain foundry choices for European-bound products.
- Analog DSP:Hybrid devices bridge continuous and discrete signal domains for sensor interface applications.
- Software DSP:Algorithmic implementations running on general-purpose processors enable flexible signal processing without dedicated hardware.
Embedded DSP sits at the top of the volume ranking, with Software DSP climbing the fastest as virtualization penetrates industrial edge deployments.
Application:
Cost tier stratification separates Automotive and Industrial Automation applications, where SiC-integrated modules command premium positioning, from Consumer Electronics with thinner margin pools.
- Automotive:Powertrain electrification and sensor fusion are forcing signal-processing architectures toward higher thermal tolerances. France and Germany anchor procurement concentration, with Renault and Volkswagen Group consolidating vendor relationships around domain-control suppliers capable of ASIC-DSP integrated architectures.
- Industrial Automation:Factory automation corridors across Germany, Poland, and the Czech Republic drive embedded DSP demand for motion control and machine vision. ECHA REACH compliance governs substance restrictions in packaging materials, affecting assembly choices for European-bound components.
- Consumer Electronics:Audio enhancement and image processing applications in smartphones and wearables face tightening CE marking thresholds for electromagnetic compatibility.
- Telecommunications:5G baseband infrastructure relies on mature network DSP architectures with stable margin pools concentrated among established infrastructure suppliers.
Automotive leads absolute revenue contribution, while Industrial Automation gains share fastest as Polish and Czech manufacturing hubs deepen automation adoption.
End User:
Customer type determines validation depth, with OEMs imposing the most stringent certification layering versus Research Institutions with lighter procurement specifications.
- OEMs:Original equipment manufacturers in Germany's automotive electronics corridor demand integrated hardware-software stacks with full regulatory documentation. KBA type-approval processes and EU AI Act compliance deadlines force premature redesign cycles across edge-device portfolios.
- System Integrators:These intermediaries aggregate DSP components into complete automation solutions for industrial end-customers. French and German system integrators are experiencing steepest compliance cost inflation as ADAS platforms integrate more radio-frequency processing blocks.
- Manufacturers:Component producers face ECHA REACH substance restrictions in semiconductor packaging materials.
- Research Institutions:Academic and government laboratories prototype next-generation signal processing algorithms with reduced certification burdens.
OEMs dominate procurement volume, with System Integrators expanding most quickly as domain-control architectures consolidate supplier relationships.
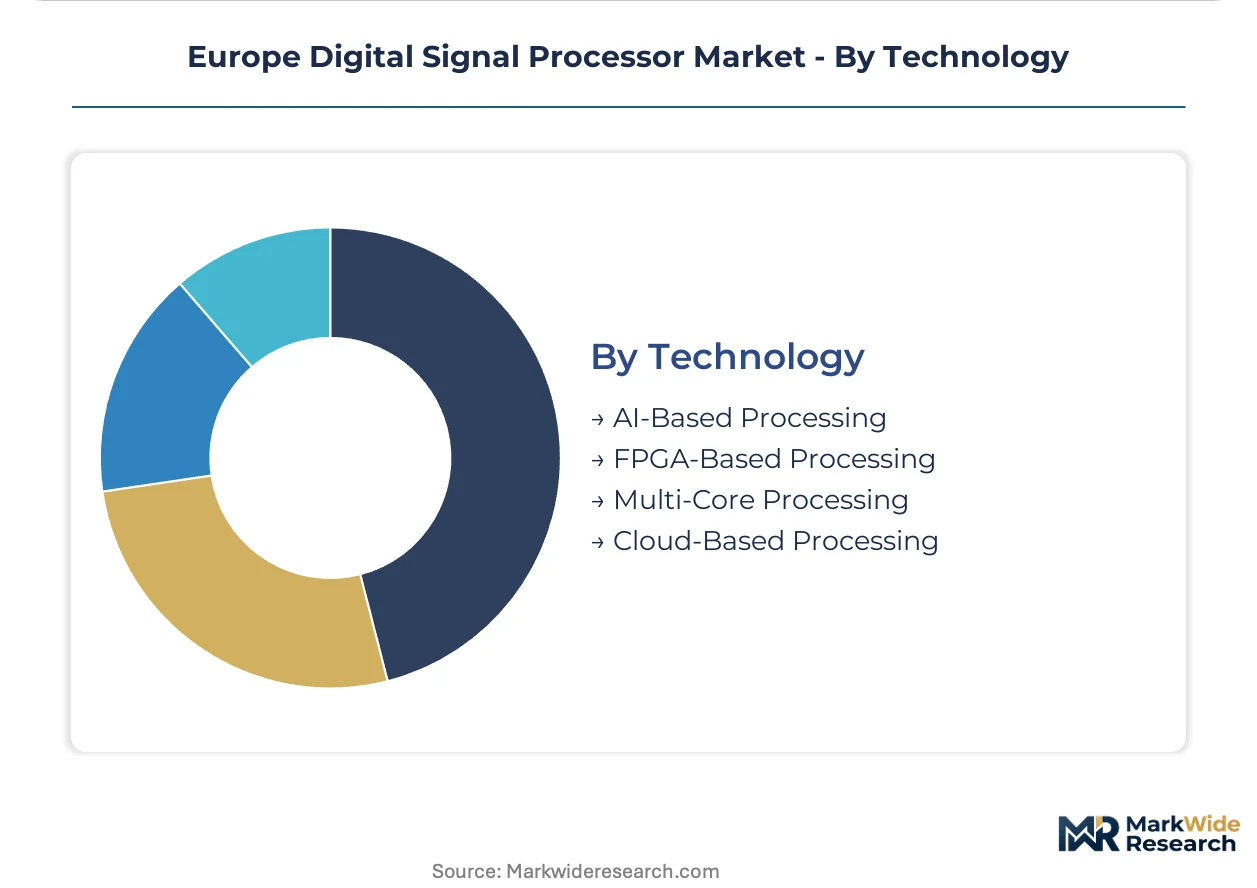
Technology:
Technology maturity separates established Multi-Core Processing from emerging AI-Based architectures, with FPGA-Based alternatives capturing niche flexibility requirements.
- AI-Based Processing:Neural network inference engines integrated with DSP blocks enable edge-based pattern recognition without cloud dependency. Automotive tier-1s across Germany and France are migrating sensor-fusion workloads to these architectures as the EU AI Act tightens compliance thresholds for autonomous systems.
- Multi-Core Processing:Parallel DSP architectures with homogeneous or heterogeneous core configurations deliver deterministic real-time performance. Industrial automation OEMs in Germany's factory automation sector concentrate procurement here for motion control and robotics applications.
- FPGA-Based Processing:Field-programmable gate arrays capture inference workloads in low-volume ADAS prototypes where fixed DSP architectures lack flexibility.
- Cloud-Based Processing:Remote signal processing services shift compute-intensive workloads away from edge devices.
Multi-Core Processing holds the largest installed base, with AI-Based Processing showing the steepest expansion trajectory as inference migrates from cloud to domain-control architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive electronics corridor stretching from Munich to Stuttgart anchors European DSP procurement concentration. France and Italy maintain secondary demand poles through aerospace and industrial automation clusters. Poland and Czech manufacturing hubs are deepening automation adoption and expanding embedded processor requirements.
Germany
Automotive OEM procurement for ADAS domain controllers and powertrain electrification drives embedded DSP volume. KBA type-approval processes filter non-compliant suppliers and extend qualification timelines by 12-18 months. Stuttgart and Munich host tier-1 suppliers consolidating vendor relationships around ASIC-DSP integrated architectures.
France
Renault and aerospace integrators are expanding sensor-fusion processor procurement for autonomous systems. ANSM and CNIL oversight intersects with EU AI Act deadlines for edge-device compliance. Toulouse and Paris-Saclay corridors concentrate aerospace signal-processing development and ADAS platform engineering.
Italy
Industrial automation OEMs in Lombardy and Emilia-Romagna drive multi-core DSP demand for robotics and motion control. CE marking under the Radio Equipment Directive elevates electromagnetic compatibility thresholds for factory-floor deployments. Turin and Milan anchor procurement concentration for machine vision and servo-drive applications.
Poland
Manufacturing automation adoption in Silesian and Greater Poland voivodeships is expanding embedded processor requirements. ECHA REACH substance restrictions govern semiconductor packaging materials for European-bound products. Wrocław and Poznań industrial zones are attracting system integrator investments in smart factory infrastructure.
Czech Republic
Automotive supplier networks in Moravia and Bohemia are integrating DSP blocks for electric vehicle subsystems. EU Green Deal sourcing rules for conflict minerals are penetrating procurement specifications for semiconductor components. Brno and Ostrava host expanding electronics manufacturing services targeting German OEM supply chains.
Europe Digital Signal Processor Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers consolidate domain-control capabilities. The vendor base organizes into three tiers: integrated semiconductor conglomerates with captive foundry access, fabless specialists licensing DSP IP cores, and system-level integrators bundling hardware-software stacks. Two competitive moves define positioning: backward integration into silicon carbide substrate supply and technology licensing agreements for AI-enhanced edge architectures.
Within the integrated semiconductor tier, Infineon Technologies, Texas Instruments, and NXP Semiconductors exemplify divergent geographic anchoring and vertical scope. Infineon Technologies represents European captive-production models with in-house SiC wafer capacity. Texas Instruments occupies a position spanning broad industrial and telecommunications endpoint coverage. NXP Semiconductors exemplifies domain-control specialization through ASIC-DSP integration for automotive validation-heavy procurement channels.
| Leading Market Players |
|---|
| Infineon Technologies |
| Broadcom |
| Texas Instruments |
| Renesas Electronics |
| Intel Corporation |
| Analog Devices |
| STMicroelectronics |
| Xilinx |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer fabrication transitions are compressing thermal management costs for automotive-grade embedded processors while simultaneously concentrating supply around captive-production facilities in Germany and Austria. This substrate migration redistributes pricing power toward integrated semiconductor conglomerates with in-house SiC capacity, forcing fabless specialists into royalty-based licensing arrangements to maintain margin structures.
Pricing Analysis
Input-cost pass-through from silicon carbide substrate premiums flows directly into module pricing for electric vehicle powertrain applications. Automotive OEMs face three-tier pricing differentiation across KBA-validated premium tiers, CE-marked standard tiers, and economy tiers for non-automotive industrial endpoints. Pricing pressure stems from FPGA substitution in low-volume ADAS prototypes where fixed DSP architectures lack reconfiguration flexibility. System integrators in France and Germany exhibit highest price sensitivity due to compliance cost inflation, while validated tier-1 suppliers command premium positioning through KBA type-approval scarcity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced logic wafer fabrication, while silicon carbide substrate supply concentrates in Germany, Austria, and the United States. Raw material dependencies span high-purity silicon, rare earth elements for packaging ceramics, and specialized photoresist chemicals governed by ECHA REACH substance restrictions. Supply chain risk centers on tariff exposure for European-bound components routed through Asian assembly hubs. Distribution runs through authorized tier-1 supplier networks with direct OEM procurement contracts, bypassing traditional semiconductor distribution channels for automotive-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Digital Signal Processor Market functions as a stable compounder anchored by automotive electrification mandates that guarantee embedded processor procurement across multi-year platform cycles.
For Market Incumbents: Deploy captive SiC wafer capacity as a supply security lever to lock in automotive OEM procurement commitments before EU AI Act compliance deadlines force redesign cycles. Consolidate domain-control software stacks with ASIC-DSP integrated architectures to defend against FPGA substitution in sensor-fusion applications. Extend KBA validation coverage to adjacent industrial automation segments in Poland and Czech manufacturing hubs.
For New Entrants and Emerging Players: Polish and Czech system integrators represent an underserved buyer archetype with deepening automation adoption and lighter incumbent relationships than saturated German corridors. Target software DSP virtualization for industrial edge deployments where deterministic performance requirements are relaxing. Pursue ECHA REACH pre-certification as a go-to-market angle to bypass qualification barriers blocking Asian competitors.
For Investors and Strategic Acquirers: Valuations sit cheapest among fabless DSP IP specialists lacking foundry partnerships but holding neural network acceleration patents relevant to EU AI Act edge-device requirements. Long-term viability rests on regulatory compliance capability rather than pure performance metrics. Watch KBA type-approval queue lengths as an inflection signal for supply-constrained premium tier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive wafer capacity anchors automotive-grade processor supply security against foundry allocation constraints. |
| ASIC-DSP Domain Control Architecture Development | Integrated hardware-software stacks displace discrete component vendors in Renault and Volkswagen Group procurement. |
| KBA Type-Approval Pre-Certification Investment | Validation pipeline access filters non-compliant suppliers from ADAS platform awards. |
| AI Inference Engine Licensing Agreements | Neural network acceleration IP enables edge-device compliance with tightening EU AI Act thresholds. |
| Polish-Czech Manufacturing Hub Expansion | Underpenetrated automation corridors present volume growth vectors beyond saturated German electronics clusters. |
Research Methodology
Bottom-up automotive and industrial automation modeling reconciled against top-down semiconductor supply-side tracking forms the analytical core of this study. Primary interviews with automotive platform engineers, tier-1 supplier procurement leads, industrial automation system integrators, and regulatory affairs specialists at ECHA and KBA informed demand-side assumptions. Secondary validation drew from EU AI Act implementation guidance, ECHA REACH substance restriction databases, CE marking directives under the Radio Equipment Directive, and vehicle production registration data from German and French automotive associations. Top-down trade flow analysis for silicon carbide substrates and DSP component customs classifications triangulated against bottom-up OEM procurement estimates.
Historical trendline analysis across embedded processor deployment in electric vehicle powertrains and factory automation installations established baseline growth patterns. Segmentation modeling spanned product architecture, application vertical, end-user type, and technology maturity, with regional regulatory clusters treated as distinct forecast inputs. CAGRs derived from regression analysis of procurement volume against platform electrification timelines and EU AI Act compliance deadlines. Industry-specific forecast inputs included KBA type-approval queue projections and ECHA REACH substance restriction phase-in schedules.
Underlying measurement precision varies by segment; automotive applications with documented OEM procurement contracts carry tighter precision than emerging software DSP virtualization in industrial edge deployments. Forecasts reflect assumptions around EU AI Act enforcement timelines, silicon carbide substrate capacity expansion, and KBA validation throughput. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Edge AI Chipset Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
China Data Center Processor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Latin America Neuromorphic Chip Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
Japan Data Center Processor Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Automotive Image Signal Processor Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
IP Core Chip Market