
 Smartphone Battery Market | 2026-2036
Smartphone Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Battery Market Analysis
Multi-source procurement is shifting from single-cell suppliers toward diversified battery vendor portfolios across tier-one smartphone OEMs. ATL leverages its polymer cell expertise to sustain long-term contracts with Apple and Xiaomi. Samsung SDI anchors premium cylindrical and prismatic supply for the Galaxy S series. LG Energy Solution competes aggressively in mid-range segments through cost-optimized lithium polymer platforms.
A smartphone battery is a rechargeable electrochemical energy storage device, typically lithium-ion or lithium polymer, engineered to deliver nominal voltages between 3.7V and 3.85V with energy densities exceeding 700 Wh per liter in advanced configurations. Its primary commercial purpose is to power mobile computing devices through discharge cycles exceeding 500 full equivalents while maintaining thermal stability under fast-charge currents above 3C. Lithium polymer cells now dominate flagship tier shipments due to form-factor flexibility and thinner z-heights, while fast charging technology commands disproportionate engineering investment as OEMs differentiate on 120W-plus protocols. The 4000 mAh capacity tier has matured into a baseline standard across mid-range devices, compressing margins as manufacturers compete on cycle-life warranties rather than unit economics.
China's SAMR enforces GB 31241 safety certifications that mandate nail-penetration and overcharge tolerance testing for all domestic lithium-ion cell sales. The EU's REACH regulation and impending battery passport requirements under the EU Green Deal are forcing supply-chain traceability for cobalt and lithium sourcing. India's BIS certification and PLI scheme for advanced chemistry cell manufacturing are reshaping regional procurement geography. Stakeholders must monitor how carbon-border adjustment mechanisms and country-of-origin rules for critical minerals will redistribute contract manufacturing away from legacy hubs.
Market Dynamics
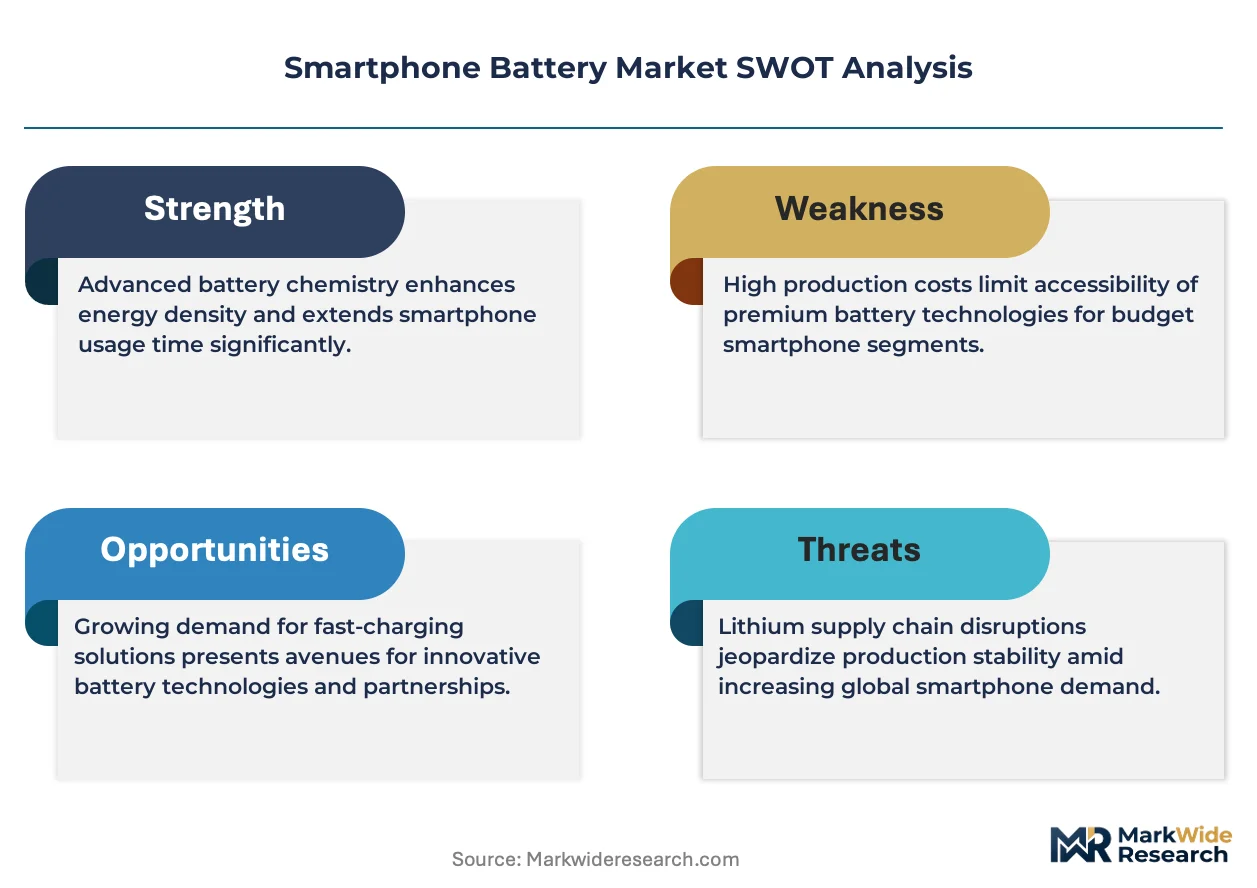
Fast-charge protocol wars among flagship OEMs are compressing cell supplier margins while demanding specialized thermal management architectures that only three East Asian manufacturers can certify at scale.
Growth Catalysts
- 5G Radio Power Draw:Millimeter-wave modems consume 20-40% more energy than LTE equivalents, forcing OEMs to spec larger cells and dual-battery configurations for thermal dissipation.
- India's PLI Scheme for ACC Manufacturing:Production-linked incentives for advanced chemistry cells are attracting Korean and Chinese suppliers to establish local gigafactories serving domestic smartphone assembly.
- Silicon-Anode Chemistry Maturation:Silicon composite anodes are reaching commercial viability in polymer cells, enabling 10-15% energy density gains without sacrificing cycle life under GB 31241 testing protocols.
Market Restraints
- Cobalt Price Volatility:DRC supply concentration and artisanal mining ESG scrutiny create input cost instability that high-nickel cathode formulations cannot fully hedge.
- Prismatic Cell Supply Concentration:Cylindrical and prismatic formats for premium flagships rely on a duopoly of Korean suppliers, creating allocation risk during capacity ramp periods.
- Energy Density Physics Ceiling:Lithium-ion theoretical limits near 300 Wh/kg are constraining form-factor innovation as OEMs demand thinner z-heights for foldable devices.
Strategic Opportunities
- Solid-State Electrolyte Convergence:Sulfide and oxide solid-state platforms promise 400+ Wh/kg densities and intrinsic thermal stability, rewriting safety certification requirements for next-generation flagships.
- Vietnam Manufacturing Cluster Expansion:Samsung and Apple assembly migration to Bac Ninh and Bac Giang provinces is creating localized battery module demand that regional suppliers can capture.
- EU Battery Passport Mandate:Digital traceability requirements under the EU Green Deal create first-mover advantages for suppliers with blockchain-verified cobalt and lithium supply chains.
Industry Challenges
- Electrochemical Modeling Talent Scarcity:Cell OEMs face acute shortages of computational chemists capable of simulating dendrite formation and solid-electrolyte interphase degradation.
- GB 31241 Recertification Timelines:China's SAMR requires 12-18 month retest cycles for any chemistry modification, slowing silicon-anode and high-voltage electrolyte rollout schedules.
- Pack-Level Thermal Integration Complexity:120W+ fast-charge protocols demand vapor chamber and graphite sheet co-design that smartphone OEMs resist outsourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Battery Market |
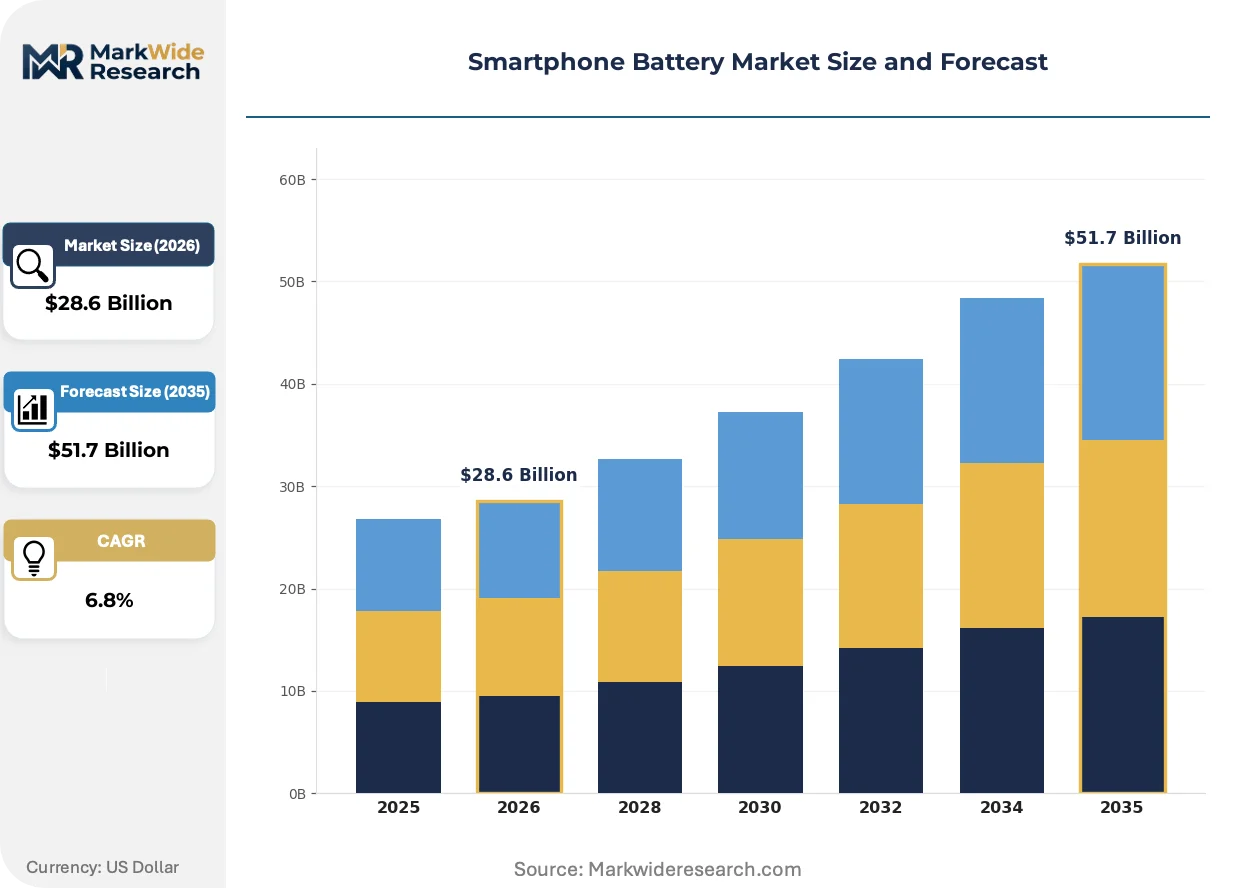
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lithium Polymer, Nickel-Cadmium, Nickel-Metal Hydride Capacity: 1000 mAh, 2000 mAh, 3000 mAh, 4000 mAh End User: Business Professionals, Gamers, Students, Elderly Charging Technology: Fast Charging, Wireless Charging, Solar Charging, Standard Charging |
| Companies Covered | Desay Battery, EVE Energy, ATL, Grepow, BYD Battery, LG Energy Solution, Sunwoda, REPT, Samsung SDI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Battery Market Emerging Trajectories
Electrochemical architecture is fragmenting into three parallel development tracks—high-nickel cylindrical for flagships, cost-optimized lithium polymer for mid-range, and experimental solid-state for next-generation form factors—each with incompatible manufacturing footprints.
Silicon-dominant anode blends are rewriting energy density economics in premium polymer cells. Samsung SDI and ATL have qualified 15% silicon composite formulations that maintain 80% capacity retention past 800 cycles. Flagship OEMs are absorbing 8-12% cell cost premiums to enable sub-8mm device profiles without sacrificing 5000 mAh capacities.
China's GB 31241-2022 revision mandates nail penetration at 150°C ambient and overcharge tolerance to 1.5x nominal voltage, eliminating marginal cell suppliers from domestic procurement. Korean exporters to China must retest entire product lines under SAMR-accredited labs, creating 6-9 month qualification backlogs that favor established players with in-country testing infrastructure.
Smartphone assemblers are consolidating battery procurement through module-level contracts rather than discrete cell purchases. Foxconn and Pegatron now specify complete battery packs with protection circuits and thermal materials, compressing tier-two cell vendors into commodity supply roles while rewarding integrated pack suppliers with design-in influence and longer contract tenors.
Smartphone Battery Market Segmentation
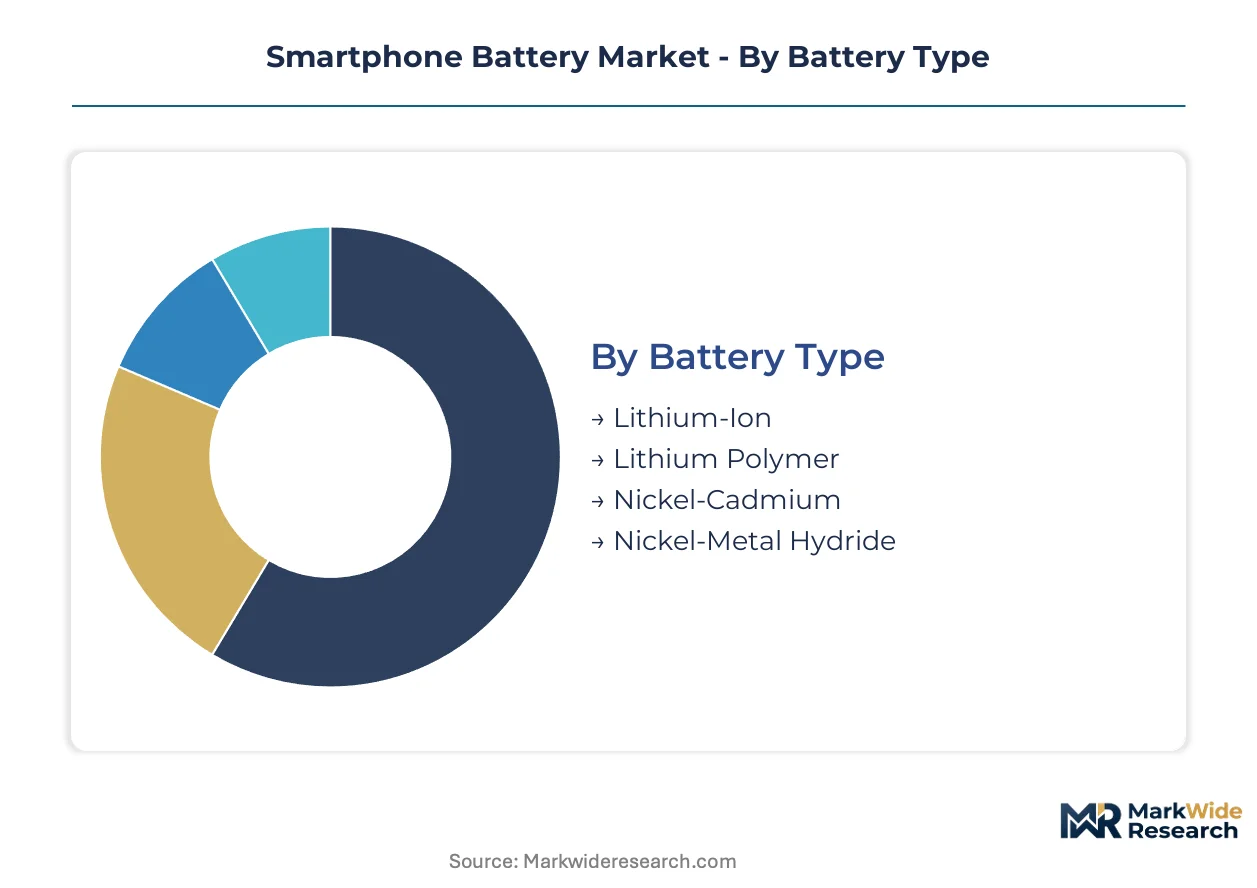
Battery chemistry, capacity tiers, and charging protocols fragment procurement strategies across smartphone OEM portfolios. Segment-specific thermal architectures and certification requirements force suppliers to maintain parallel production lines with incompatible tooling.
Battery Type:
Chemistry selection dictates manufacturing footprint, safety certification pathway, and form-factor flexibility for device integrators.
- Lithium Polymer:Pouch-cell construction enables sub-4mm z-heights and irregular geometries required by foldable flagships. Samsung and Apple procurement concentrates in Korean and Chinese polymer specialists. GB 31241-2022 certification mandates dominate supplier qualification timelines.
- Lithium-Ion:Cylindrical 18650 and 21700 formats anchor premium devices demanding maximum volumetric energy density. Supply concentrates in Samsung SDI and LG Energy Solution production hubs serving Galaxy S-series and iPhone Pro volumes.
- Nickel-Metal Hydride:Legacy chemistry persists in ultra-low-cost feature phones and replacement markets in India and sub-Saharan Africa where BIS certification costs prohibit lithium-ion adoption.
- Nickel-Cadmium:Obsolete for smartphones; residual demand limited to industrial ruggedized devices and military-spec communications equipment exempt from RoHS restrictions.
Mature deployment sits with Lithium-Ion. Newer deployment is concentrated in Lithium Polymer.
Capacity:
Millimeter-wave 5G modems and 120Hz OLED panels are pushing baseline capacity requirements upward across all price tiers.
- 4000 mAh:Standardized baseline for mid-range devices sold in India and Southeast Asia. Foxconn and Pegatron module assembly lines optimize for this capacity tier. PLI scheme incentives compress margins to cycle-life warranty differentiation.
- 3000 mAh:Compact flagship segment serving Japan and Western Europe where device thickness constraints override endurance priorities. Sony and Apple mini-series procurement drives residual demand.
- 2000 mAh:Entry-level smartphones and IoT companion devices in African and Latin American markets. Local assembly operations in Vietnam and Indonesia specify this tier for sub-$100 retail price points.
- 1000 mAh:Feature phones and emergency backup devices. Declining volume as 2G network sunsets accelerate in India and China.
Volume concentrates at 4000 mAh. Premium differentiation is climbing fastest toward 5000 mAh-plus dual-cell architectures.
End User:
Usage intensity patterns reshape thermal management specifications and cycle-life warranty terms in procurement contracts.
- Gamers:Sustained 3C-plus discharge rates and 120W fast-charge protocols demand vapor-chamber cooling and silicon-anode chemistry. Chinese OEMs Xiaomi, iQOO, and RedMagic specify dedicated gaming-optimized cell lines.
- Business Professionals:All-day endurance and wireless charging compatibility prioritize 4000 mAh-plus polymer cells with Qi coil integration. Samsung Galaxy Note and iPhone Pro Max procurement anchors this segment.
- Students:Price-sensitive demand in India and Indonesia drives procurement of 3000-4000 mAh lithium-ion cells with 18-month replacement warranties. Local BIS certification requirements filter supplier options.
- Elderly:Simplified devices with reduced feature sets accommodate 2000-3000 mAh capacities. Japanese and European markets specify enhanced safety circuits and larger physical battery compartments for handling ease.
Gamers command premium cell specifications. Elderly-oriented devices are expanding most quickly in Japan and Western Europe as demographic shifts accelerate.
Charging Technology:
Protocol standardization battles among OEMs are fragmenting cell supplier qualification requirements.
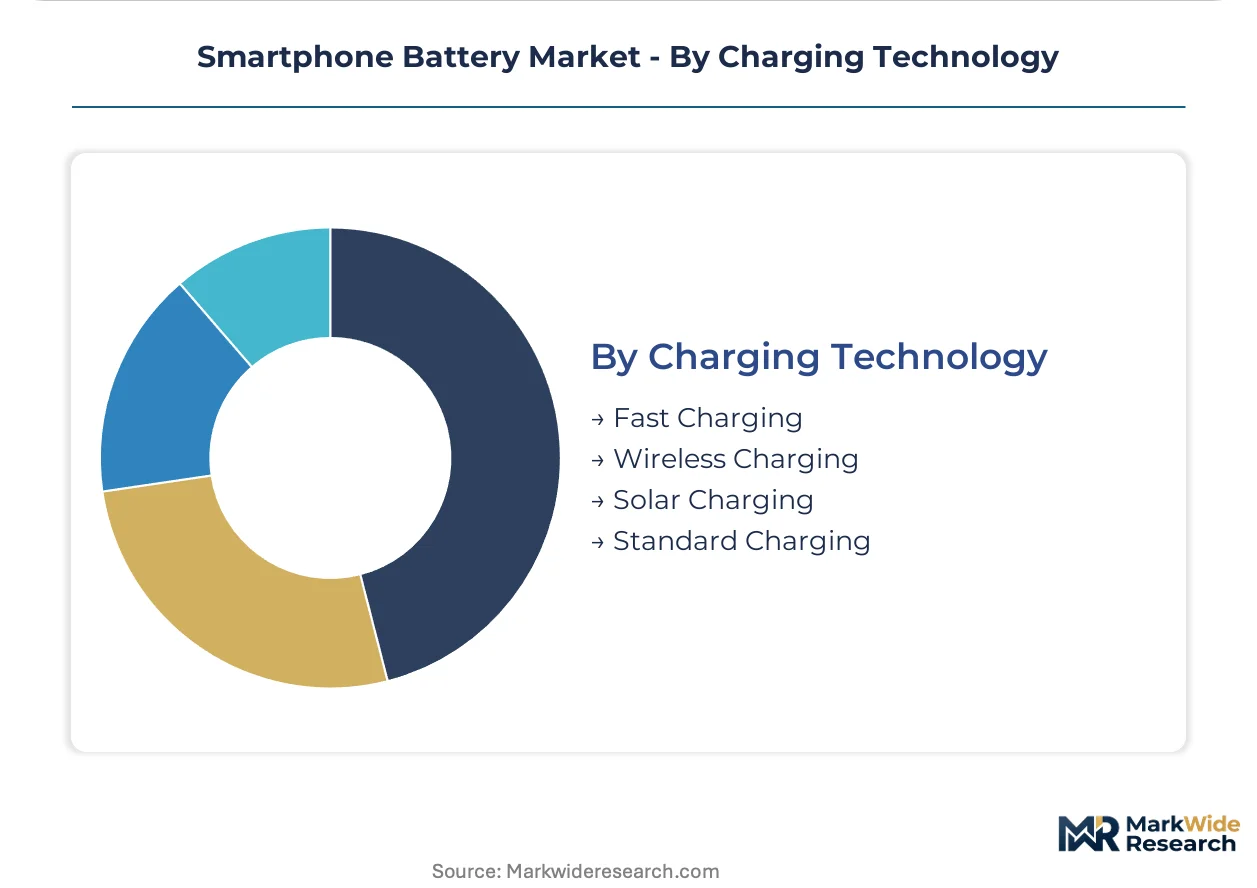
- Fast Charging:65W to 240W protocols from OPPO, Xiaomi, and iQOO require specialized electrolyte formulations and multi-tab cell architectures. Chinese GB standards mandate dedicated thermal runaway testing for each protocol variant.
- Wireless Charging:Qi and proprietary magnetic alignment systems from Apple and Samsung necessitate coil-integrated pack designs. Module-level procurement through Foxconn and Luxshare dominates.
- Standard Charging:10W to 18W legacy protocols persist in government and enterprise fleet devices where battery longevity overrides convenience. Indian public-sector procurement specifies this tier exclusively.
- Solar Charging:Niche outdoor and emergency devices. Low conversion efficiency limits deployment to auxiliary charging in ruggedized smartphones for agricultural and military applications.
Fast Charging anchors flagship R&D investment. Wireless Charging is gaining share fastest as Apple and Samsung expand magnetic ecosystem accessories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium and cobalt supply chains anchor manufacturing geography. Cell production clusters concentrate where OEM assembly plants, cathode material refiners, and export infrastructure converge.
China
Fujian-based ATL and BYD Battery serve domestic OEMs Xiaomi and OPPO with polymer cells. SAMR enforces GB 31241-2022 recertification for silicon-anode chemistries. Shenzhen and Dongguan module assemblers now specify complete packs with integrated protection circuits.
South Korea
Samsung SDI and LG Energy Solution supply cylindrical and prismatic formats for Galaxy S-series and export markets. MFDS coordinates with SAMR on thermal runaway test mutual recognition. Gumi and Ochang production hubs face allocation pressure during flagship launch ramps.
Vietnam
Samsung and Apple assembly migration to Bac Ninh and Bac Giang provinces generates localized battery module demand. Vietnamese government industrial zone incentives attract Korean cell suppliers to establish pack-level operations. Ho Chi Minh City logistics corridors serve re-export to ASEAN markets.
India
Reliance Jio and domestic OEMs Lava, Micromax drive 4000 mAh baseline procurement for sub-$150 smartphones. BIS certification and PLI scheme for advanced chemistry cells reshape supplier qualification. Tamil Nadu and Uttar Pradesh assembly plants source cells from newly established Korean gigafactories.
United States
Apple and Google Pixel procurement concentrates polymer cell imports through Luxshare and Foxconn module partners. FCC equipment authorization and CPSC safety reporting govern pack-level compliance. Texas and California final assembly plants rely on East Asian cell supply with limited domestic electrode production.
Smartphone Battery Market Vendor Landscape
Capacity expansion dominates the current landscape as tier-one suppliers race to match 5G-driven cell volume ramps. The vendor base stratifies into three tiers: integrated chemical-to-pack conglomerates, pure-play polymer specialists, and emerging silicon-anode challengers. Strategic archetypes include captive suppliers serving single OEM ecosystems, independent merchant cell vendors, and module-level integrators capturing design-in influence. M&A activity and geographic diversification through Vietnam and India manufacturing represent the dominant competitive moves.
Among Chinese fabricators, ATL, BYD Battery, and EVE Energy exemplify the integrated conglomerate archetype with captive chemical refining and polymer cell production. Samsung SDI and LG Energy Solution anchor the Korean duopoly controlling premium cylindrical and prismatic supply. These five names represent the core competitive set around which module assemblers and OEM procurement teams structure vendor diversification strategies.
| Leading Market Players |
|---|
| Desay Battery |
| EVE Energy |
| ATL |
| Grepow |
| BYD Battery |
| LG Energy Solution |
| Sunwoda |
| REPT |
| Samsung SDI |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Korean producers and family-owned Chinese specialists anchor cell manufacturing, concentrating procurement leverage among smartphone OEMs while compressing margins through cycle-life warranty competition rather than unit economics. This ownership structure enforces pricing discipline through captive chemical refining and long-term offtake contracts with cobalt suppliers in the DRC and lithium processors in Chile.
Pricing Analysis
Warranty bundling separates procurement tiers: premium flagships include 24-month cycle-life guarantees and thermal-runaway insurance, while mid-range devices carry unbundled 12-month coverage with replacement-cost exposure. Three-tier pricing structure across premium, standard, and economy levels reflects GB 31241 certification grade and silicon-anode content. Cost compression in the 4000 mAh mid-range tier is intensifying because India's PLI scheme attracts new entrants with subsidized capacity. Government fleet buyers in India exhibit highest price sensitivity; gaming-focused Chinese OEMs absorb 8-12% cell cost premiums for silicon-anode chemistry.
Supply Chain Analysis
Workforce availability constraints in Bac Ninh province and Dongguan city limit pack-level assembly expansion despite Samsung and Apple assembly migration. Cell production concentrates in China, South Korea, and Vietnam, drawing from DRC cobalt, Chilean lithium carbonate, and Chinese cathode precursor refineries. Single-source vulnerability sits with Korean cylindrical format supply for Galaxy S-series and iPhone Pro volumes. Distribution runs through Foxconn and Pegatron module integrators that now specify complete packs with protection circuits and thermal materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smartphone battery sector sits in a silicon-anode transition phase, with composite anode chemistry displacing graphite-dominant formulations as OEMs demand sub-8mm profiles without sacrificing 5000 mAh capacities.
For Market Incumbents: Lock in silicon-anode qualification timelines under GB 31241-2022 recertification protocols to preempt challenger entry. Samsung SDI and ATL should expand in-house cathode precursor production in response to cobalt price volatility from DRC supply concentration. Securing module-level contracts through Foxconn and Luxshare preserves design-in influence as OEMs consolidate procurement. For New Entrants and Emerging Players: Direct-to-OEM digital procurement platforms offer white-space entry around BIS-certified 4000 mAh cells for Indian domestic OEMs Lava and Micromax. Vietnam's Bac Giang industrial zone presents localized pack assembly opportunity serving Samsung and Apple re-export demand. Target gaming-optimized cell lines with vapor-chamber integration for Xiaomi and iQOO specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-range polymer specialists with existing SAMR testing infrastructure in Fujian province during Korean capacity allocation crunches. Long-term viability hinges on solid-state electrolyte patent positioning and EU Battery Passport traceability readiness. Watch silicon-anode cycle-life retention past 800 cycles under 3C fast-charge protocols as inflection indicator for chemistry leadership.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Anode Chemistry Scale-Up | Samsung SDI and ATL qualification under GB 31241-2022 enables 10-15% energy density gains for flagship OEMs. |
| Vietnam Pack Assembly Localization | Bac Ninh and Bac Giang province incentives capture module demand from Samsung and Apple assembly migration. |
| EU Battery Passport Compliance | Blockchain-verified cobalt and lithium traceability creates first-mover advantage under EU Green Deal mandates. |
| India ACC Gigafactory Entry | PLI scheme subsidies attract Korean and Chinese suppliers to serve Reliance Jio and domestic OEM procurement. |
| Solid-State Electrolyte R&D Partnership | Sulfide and oxide platform development rewrites safety certification requirements for next-generation foldable devices. |
Methodological Framework
SEC 10-K filings, customs and trade databases, and SAMR certification registries formed the secondary backbone, supplemented by EIA mineral commodity reports and MFDS thermal runaway test documentation. Primary interviews with cell OEM procurement directors, smartphone platform engineers at tier-one OEMs, Foxconn module assembly planners, and BIS certification consultants validated capacity and pricing assumptions. Bottom-up cell shipment estimates by chemistry and capacity tier were cross-referenced against top-down smartphone production forecasts from assembly partner disclosures.
Bottom-up modeling of lithium polymer, lithium-ion cylindrical, and emerging silicon-anode volumes across the projection horizon was reconciled with top-down OEM procurement budget analysis. Segmentation dimensions included battery chemistry, capacity tier, charging protocol, and end-user intensity profile. CAGRs were derived from fitted growth curves accounting for 5G radio power draw, foldable device form-factor constraints, and regional certification timelines. Forecast inputs incorporated cathode material cost trajectories and GB 31241 recertification lag effects.
The model holds under stable cobalt and lithium carbonate supply conditions; deviation in DRC export restrictions or Chilean lithium brine policy would shift capacity expansion timelines. Forecasts reflect documented assumptions regarding silicon-anode commercialization rates and SAMR testing backlog resolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
North America Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Discrete Semiconductor Market