
 Resistive RAM Market | 2026-2036
Resistive RAM Market Size, Share, and Industry Trends Forecast 2026-2036
Resistive RAM Market Outlook
Hafnium oxide is consolidating as the dominant transition-metal-oxide switching material in filamentary ReRAM, displacing earlier nickel-oxide and titanium-oxide formulations that suffered higher cycle-to-cycle variability. Samsung Electronics leverages its captive foundry and memory divisions to co-develop embedded ReRAM with logic nodes at scale. Intel Corporation sustains process integration research through its advanced packaging roadmaps, anchoring ReRAM as a candidate for in-memory compute architectures. TSMC differentiates by offering ReRAM macros as standard intellectual-property blocks at mature nodes, competing for IoT and microcontroller socket wins.
Resistive RAM stores data through resistance modulation in metal-oxide thin films, typically achieving switching speeds below 10 nanoseconds and endurance exceeding 10^12 cycles in filamentary architectures. Its primary purpose is to bridge the latency gap between DRAM and flash while eliminating the refresh power penalty of volatile memory. Embedded RAM dominates current wafer starts because microcontroller and system-on-chip designers value non-volatile storage without added packaging cost. Standalone RAM occupies a narrower but higher-margin niche where density scaling justifies dedicated die allocation. Automotive Systems application demand is accelerating fastest as edge inference and over-the-air update requirements multiply across vehicle platforms.
REACH restrictions on hazardous substances in electronics and the EU AI Act's emerging hardware transparency requirements are shaping European qualification protocols for memory components in safety-critical systems. The US CHIPS Act and NSF semiconductor research programs are channeling federal funding toward novel memory technologies that strengthen domestic supply chain resilience. China's GB standards and MIIT industry guidelines establish domestic certification pathways that favor locally developed ReRAM intellectual property. Stakeholders must monitor which regulatory jurisdictions first mandate non-volatile memory for functional safety, as this will determine the geographic sequencing of high-volume design wins.
Market Dynamics
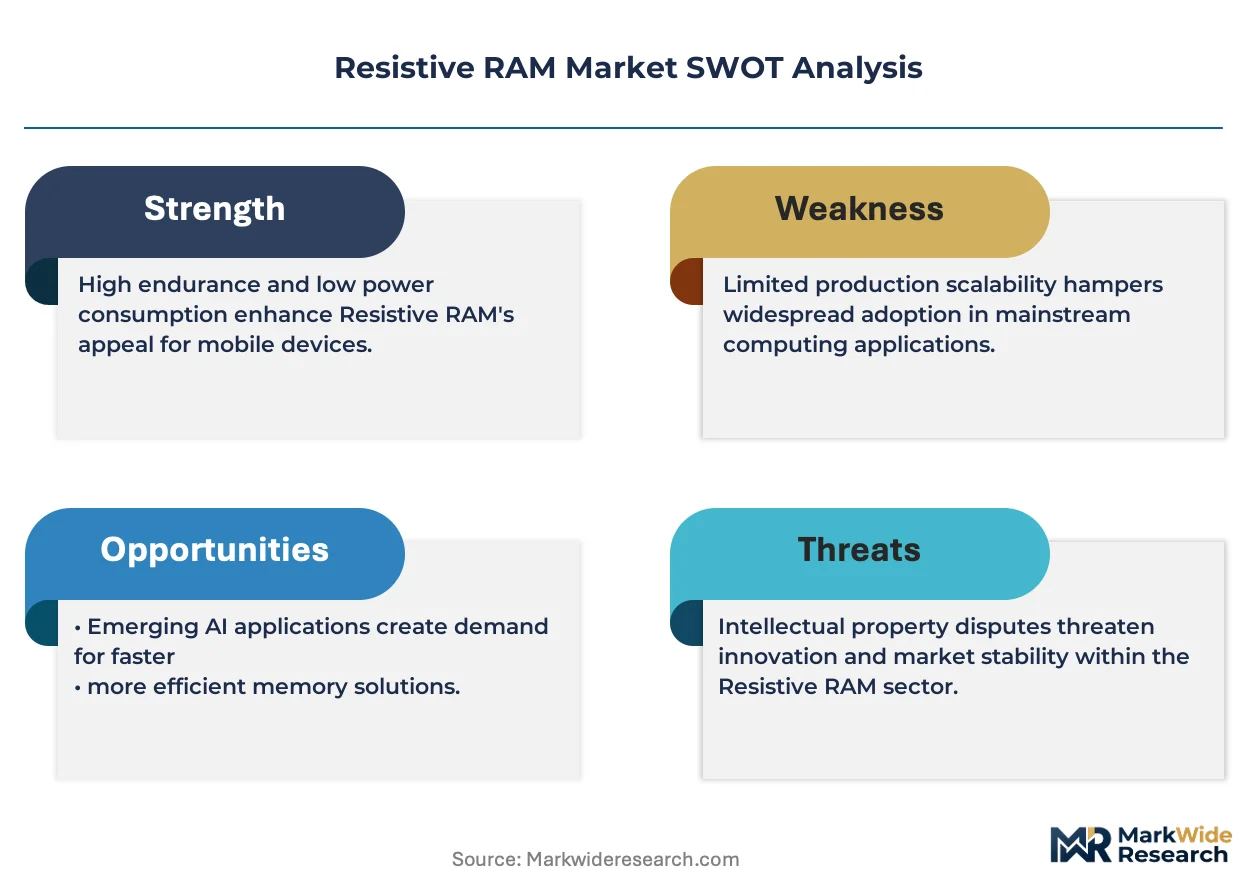
Hafnium oxide filamentary architectures are consolidating design wins as automotive functional safety requirements harden, compressing qualification timelines and concentrating procurement around proven switching materials.
Growth Catalysts
- ISO 26262 functional safety mandates:Automotive ECU designers require non-volatile memory for fault-tolerant state retention, pulling ReRAM into advanced driver-assistance system roadmaps across German and Japanese supply chains.
- China MIIT localization directives:Domestic foundry capacity in Shanghai and Wuxi is pivoting toward captive ReRAM production to satisfy semiconductor self-sufficiency targets under dual carbon policy frameworks.
- Edge inference workloads:Microcontroller architects in Taiwan and South Korea are embedding ReRAM macros to eliminate external flash latency in battery-constrained sensor nodes.
Market Restraints
- Equipment depreciation cycles:Sputtering and atomic layer deposition tools for hafnium oxide switching layers carry capital recovery timelines exceeding standard CMOS node transitions.
- Hsinchu-Seoul supply concentration:Specialty gas and precursor chemical supply for metal-oxide ReRAM filaments routes through a narrow East Asian vendor base exposed to maritime chokepoint risk.
- DRAM-NAND price compression:Aggressive bit-cost scaling in established volatile and non-volatile memory technologies narrows the latency-power value window for standalone ReRAM products.
Strategic Opportunities
- India PLI scheme electronics manufacturing:Greenfield fab investments in Gujarat and Karnataka create openings for embedded ReRAM IP licensing at mature logic nodes.
- EU AI Act hardware transparency requirements:Emerging certification pathways for explainable edge compute favor non-volatile memory architectures with deterministic state retention.
- In-memory compute convergence:ReRAM crossbar arrays paired with analog vector-matrix multiplication engines enable new architectural paradigms for neural network inference acceleration.
Industry Challenges
- Process integration engineering scarcity:Deep expertise in metal-oxide defect engineering and filament formation physics resides within a limited pool of specialists concentrated at legacy memory manufacturers.
- AEC-Q100 qualification timelines:Extended temperature cycling and data retention testing for automotive-grade ReRAM macros stretches product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistive RAM Market |
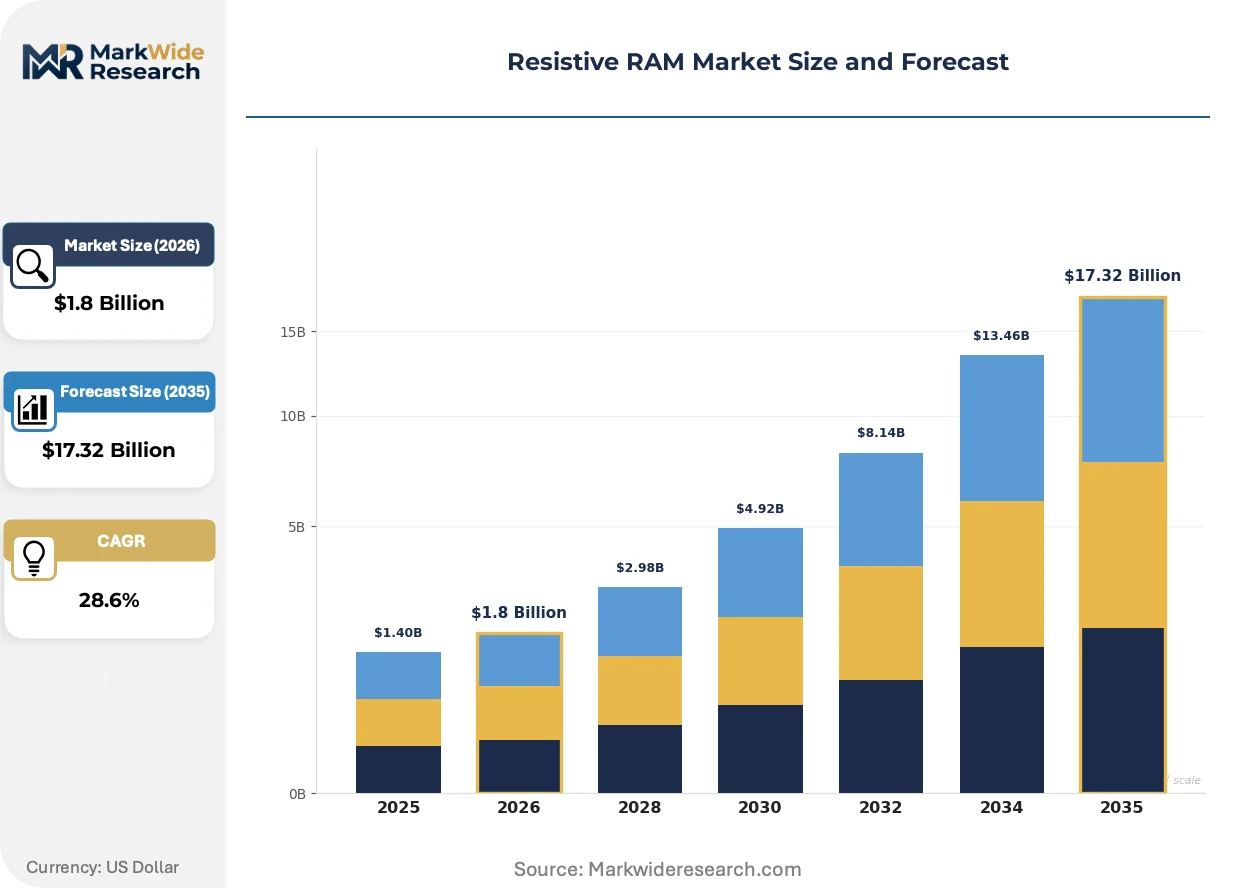
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded RAM, Standalone RAM, Specialty RAM, High-Power RAM Technology: Selector Device Technology, Switch Technology, Low-Power Technology, High-Speed Technology Application: Consumer Electronics, Automotive Systems, Industrial Automation, Telecommunications End User: Electronics Manufacturers, Automotive OEMs, Telecommunication Providers, Industrial Sector |
| Companies Covered | Samsung Electronics, Intel Corporation, Micron Technology, Panasonic Corporation, Fujitsu Ltd, SK Hynix, Crossbar Inc., TSMC, Weebit Nano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistive RAM Market Strategic Shifts
Three forces are restructuring how ReRAM technology penetrates semiconductor value chains: material platform consolidation, regulatory-driven safety certification, and procurement model evolution toward embedded IP sourcing.
Conductive-bridge RAM variants utilizing silver or copper filament electrochemistry are overtaking oxide-based alternatives in low-power microcontroller sockets. Nordic and Japanese MCU architects are adopting these chemistries for sub-microamp standby consumption. This material shift is overtaking earlier titanium-oxide formulations in designs where write endurance exceeds ten billion cycles.
REACH substance restrictions under ECHA jurisdiction are tightening precursor chemical approval pathways for hafnium and zirconium organometallics used in atomic layer deposition. European equipment suppliers are reformulating precursor delivery systems to preempt authorization bottlenecks. Automotive module manufacturers in Germany and France are prioritizing ReRAM suppliers with pre-qualified green chemistry dossiers.
Procurement of ReRAM functionality is fragmenting from standalone die purchases toward embedded macro licensing. System-on-chip design teams in Taiwan and Israel are negotiating hard IP integration rather than external memory procurement. This behavioral pivot is most pronounced in industrial automation and medical device verticals where board-space constraints dominate bill-of-material decisions.
Resistive RAM Market Segmentation
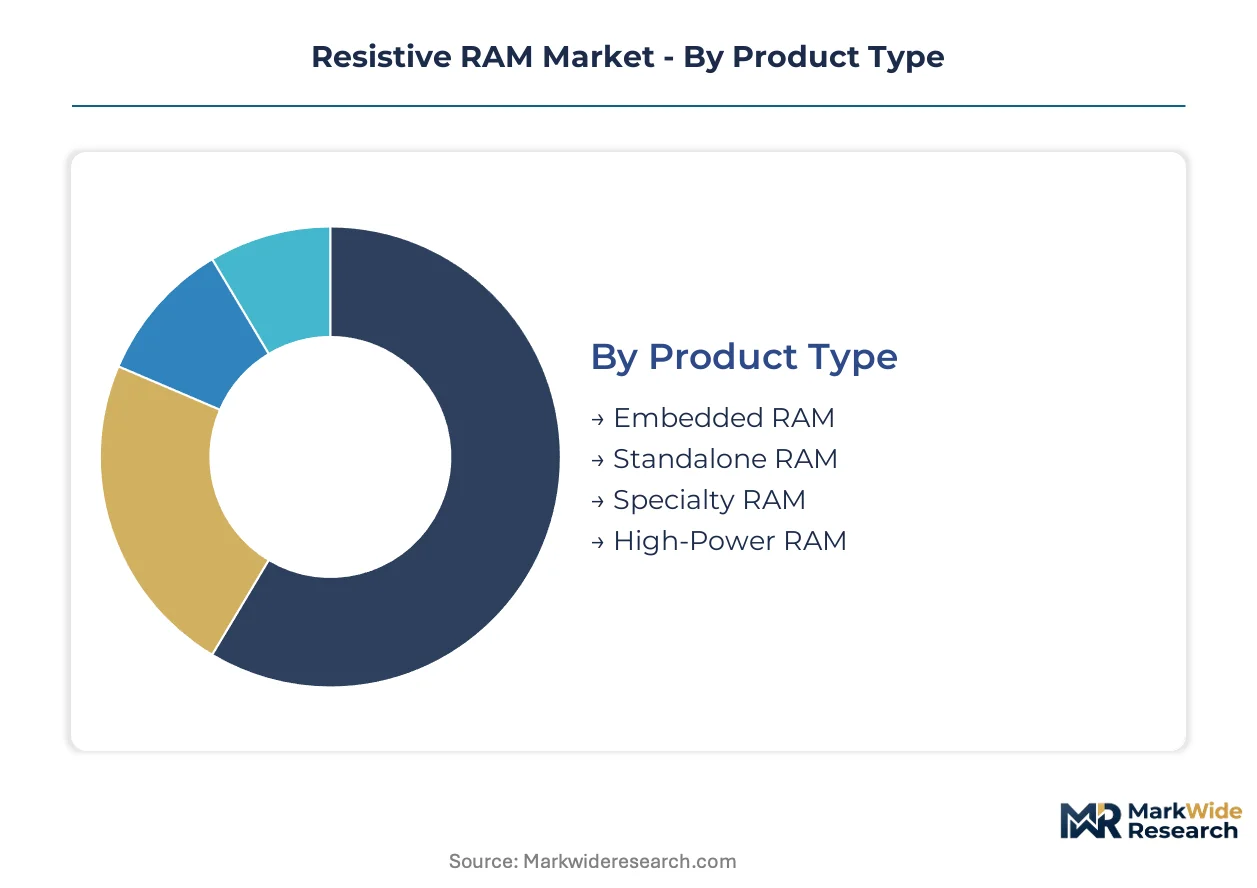
ReRAM product configurations diverge sharply between embedded integration and standalone deployment, with each trajectory demanding distinct process integration expertise and qualification protocols. Technology selection dictates filament chemistry, selector architecture, and power-performance trade-offs that ripple through end-use suitability. Application verticals impose divergent reliability standards, from consumer temperature cycling to automotive ISO 26262 functional safety mandates.
Product Type:
Integration depth determines packaging economics and design win accessibility across microcontroller, system-on-chip, and dedicated memory socket opportunities.
- Embedded RAM:Non-volatile macros co-fabricated with logic transistors at mature nodes eliminate external memory packaging cost. Microcontroller architects in Taiwan and Israel prioritize embedded ReRAM for industrial sensor nodes where board space constraints dominate bill-of-material decisions. Embedded RAM leads on scale; Specialty RAM leads on momentum.
- Standalone RAM:Dedicated die allocation targets density-scaled storage applications requiring higher margins to justify custom wafer processing. Standalone configurations concentrate procurement among cloud-edge gateway manufacturers seeking deterministic latency below NAND flash thresholds.
- Specialty RAM:Radiation-hardened and extreme-temperature variants serve aerospace and downhole instrumentation with customized filament engineering.
- High-Power RAM:Elevated current drive capabilities support in-memory compute crossbar arrays where analog vector-matrix multiplication demands enhanced conductance programming range.
Embedded RAM dominates wafer starts; Specialty RAM climbs the fastest as mission-critical verticals harden qualification requirements.
Technology:
Filament formation physics and selector device engineering separate commercial viability from laboratory demonstration across power, speed, and endurance specifications.
- Selector Device Technology:One-selector-one-resistor architectures utilizing ovonic threshold switches or transistor selectors suppress sneak path currents in dense crossbar arrays. Hsinchu foundries integrate proprietary selector devices with hafnium oxide switching layers for embedded IoT macros. Selector Device Technology leads on maturity; High-Speed Technology leads on design win velocity.
- Switch Technology:Filamentary metal-oxide switching mechanisms modulate resistance through oxygen vacancy migration in hafnium oxide thin films, achieving endurance exceeding ten billion cycles in qualified automotive designs.
- Low-Power Technology:Sub-microamp programming currents enable energy-harvesting sensor applications where battery replacement is economically prohibitive.
- High-Speed Technology:Sub-ten-nanosecond switching latencies bridge the performance gap between DRAM and flash in cache hierarchy reconfigurations.
Switch Technology anchors volume production; High-Speed Technology gains share fastest as edge inference workloads multiply.
Application:
End-use reliability requirements and temperature exposure profiles segment ReRAM qualification pathways from consumer-grade to automotive-extended temperature ranges.
- Automotive Systems:Advanced driver-assistance system ECUs require non-volatile state retention for fault-tolerant operation under ISO 26262 functional safety mandates. German and Japanese automotive module manufacturers prioritize AEC-Q100 qualified ReRAM macros for over-the-air update persistence and edge inference acceleration. Automotive Systems leads on revenue expansion; Consumer Electronics leads on unit volume.
- Consumer Electronics:Wearable and hearable devices integrate embedded ReRAM to eliminate external flash latency while minimizing standby power consumption.
- Industrial Automation:Programmable logic controllers and robotic motion controllers demand deterministic write endurance for real-time parameter logging.
- Telecommunications:Baseband processing and network timing modules utilize ReRAM for configuration storage across power cycling events.
Consumer Electronics dominates socket count; Automotive Systems shows the steepest expansion trajectory as electrification multiplies ECU content per vehicle.
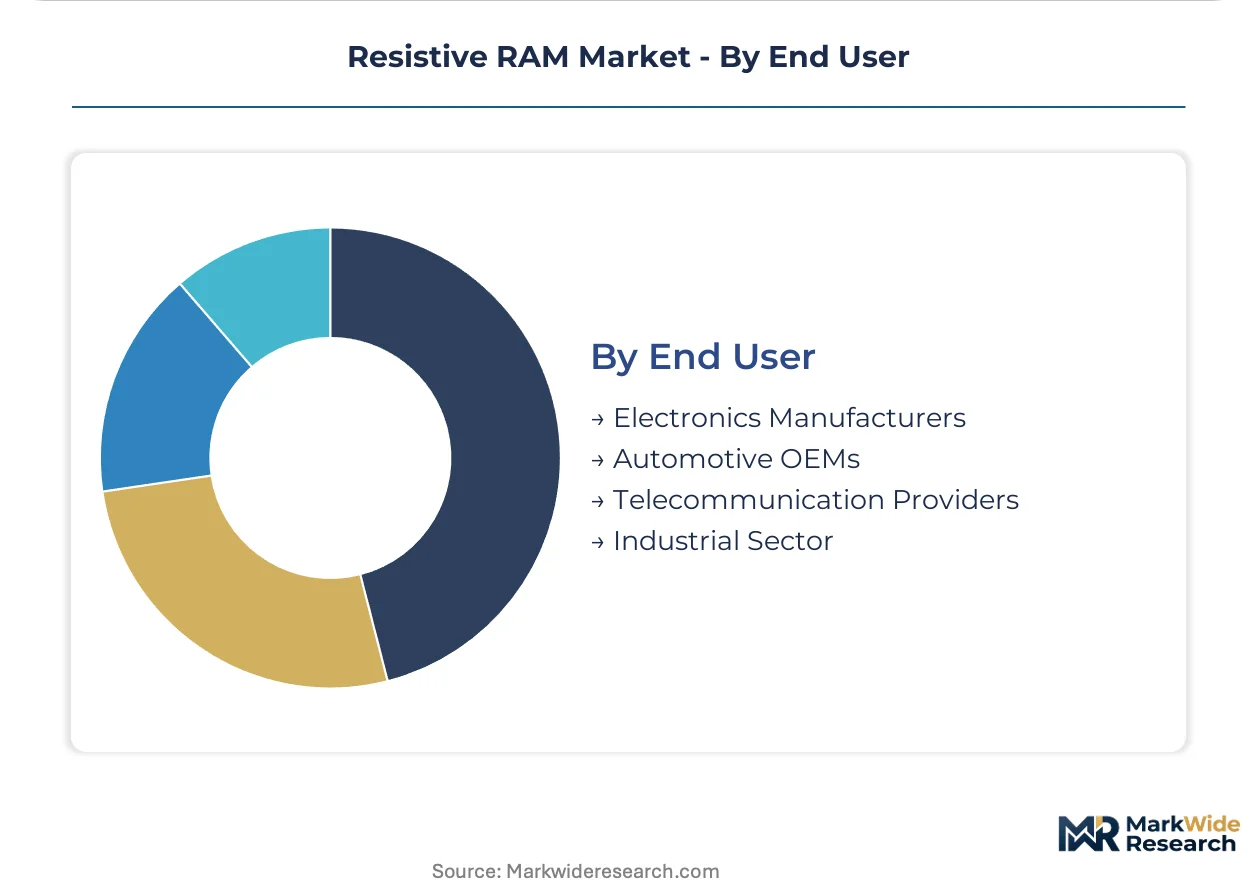
End User:
Procurement sophistication and captive integration depth separate vertically integrated OEMs from merchant memory purchasers across the value chain.
- Electronics Manufacturers:Fabless system-on-chip designers license hardened ReRAM intellectual property from foundry partners rather than sourcing standalone memory die. Israeli and Taiwanese design houses negotiate macro integration terms that embed non-volatile functionality without process development burden. Electronics Manufacturers leads on design activity; Automotive OEMs leads on qualification rigor.
- Automotive OEMs:Tier-one suppliers and vehicle manufacturers impose extended temperature cycling and data retention testing that stretches product development schedules.
- Telecommunication Providers:Network equipment manufacturers specify ReRAM for timing and synchronization modules requiring deterministic state persistence.
- Industrial Sector:Factory automation OEMs prioritize write endurance and radiation tolerance in programmable controller applications.
Electronics Manufacturers drive licensing volume; Automotive OEMs command premium pricing through safety-critical certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu anchors fabrication concentration for resistive RAM technology, with foundry clusters in Taiwan, South Korea, and China commanding wafer start volumes for embedded non-volatile memory production.
United States
Advanced packaging research and CHIPS Act funding drive domestic ReRAM development for in-memory compute architectures. NSF semiconductor programs channel federal investment toward novel memory supply chain resilience. Intel Corporation maintains process integration research through its Arizona and Oregon fabrication facilities.
Germany
Automotive module manufacturers demand AEC-Q100 qualified ReRAM macros for advanced driver-assistance systems under ISO 26262 mandates. ECHA REACH restrictions shape precursor chemical approval pathways for hafnium organometallics. Bavarian equipment suppliers reformulate atomic layer deposition delivery systems to preempt authorization bottlenecks.
China
Domestic foundry capacity in Shanghai and Wuxi pivots toward captive ReRAM production to satisfy MIIT semiconductor self-sufficiency targets. Dual carbon policy frameworks redirect localization mandates toward non-volatile memory alternatives. Yangtze River Delta fabrication clusters scale embedded macro output for industrial automation sockets.
South Korea
Memory division integration with captive foundry operations accelerates embedded ReRAM co-development at mature logic nodes. Edge inference workloads pull microcontroller architects toward sub-ten-nanosecond switching specifications. Seoul metropolitan area R&D concentration advances filamentary hafnium oxide qualification timelines.
Japan
MCU architects adopt conductive-bridge RAM variants utilizing silver filament electrochemistry for sub-microamp standby consumption. METI industrial guidelines support domestic intellectual property development for automotive functional safety applications. Nagoya and Osaka design houses concentrate on industrial automation and medical device verticals.
Resistive RAM Market Competitive Environment
Strategic partnerships dominate the current landscape as foundries and fabless designers negotiate embedded IP licensing terms rather than standalone die procurement. The vendor base separates into three tiers: integrated memory-foundry conglomerates, pure-play foundry service providers, and specialty non-volatile memory developers. Two strategic archetypes define competitive positioning: captive vertical integration spanning memory and logic divisions, and merchant IP licensing models targeting microcontroller socket wins. Technology licensing agreements and portfolio diversification into automotive-qualified macros represent the dominant competitive moves.
Within the integrated conglomerate tier, Samsung Electronics and Intel Corporation exemplify captive vertical integration strategies that span memory production, logic fabrication, and advanced packaging research. TSMC occupies a merchant foundry position, offering ReRAM macros as standard intellectual-property blocks that compete for IoT and microcontroller design wins without captive memory division overhead.
| Leading Market Players |
|---|
| Samsung Electronics |
| Intel Corporation |
| Micron Technology |
| Panasonic Corporation |
| Fujitsu Ltd |
| SK Hynix |
| Crossbar Inc. |
| TSMC |
| Weebit Nano |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions under ECHA jurisdiction gate qualified supply of hafnium organometallic precursors and premium-tier pricing access for automotive-grade ReRAM macros, as German module manufacturers prioritize suppliers with pre-certified green chemistry dossiers.
Pricing Analysis
Input-cost pass-through from hafnium precursor and specialty gas pricing shapes contract negotiations between foundries and fabless designers. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-tier levels reflects certification burden and temperature range specifications. Pricing pressure stems from DRAM-NAND bit-cost compression narrowing the latency-power value window for standalone products. Automotive OEMs exhibit lowest price sensitivity due to ISO 26262 functional safety mandates, while consumer electronics manufacturers drive hard volume negotiations.
Supply Chain Analysis
Freight costs for precursor chemicals and specialty gases amplify margin pressure on European equipment suppliers serving hafnium oxide deposition tool installations. Manufacturing concentrates in Taiwan, South Korea, and China, with Hsinchu foundry clusters commanding wafer start volumes for embedded macros. Production draws from hafnium oxide switching layers, silver/copper filament chemistries, and ovonic threshold switch selectors. Single-source vulnerability concentrates in East Asian maritime chokepoints for precursor delivery. Distribution runs through foundry-direct IP licensing rather than merchant memory distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Resistive RAM Market functions as a stable compounder, with automotive electrification multiplying ECU content per vehicle and embedding non-volatile memory into long-term vehicle platforms.
For Market Incumbents: Deepen captive foundry-memory division integration to accelerate AEC-Q100 qualification timelines and defend against conductive-bridge RAM substitutes overtaking oxide-based alternatives in low-power sockets. Expand hafnium oxide process development in Seoul and Hsinchu clusters to preempt emerging Chinese domestic foundry capacity. Prioritize ECHA green chemistry dossier completion to maintain European automotive module supplier status.
For New Entrants and Emerging Players: The premium-economy price-point gap in industrial automation and medical device verticals creates white-space opportunity for embedded ReRAM IP licensing at mature nodes. Target India's Gujarat and Karnataka greenfield fab investments under PLI scheme electronics manufacturing incentives. Pursue design house partnerships in Israel and Taiwan where board-space constraints dominate bill-of-material decisions.
For Investors and Strategic Acquirers: Roll-up economics work for specialty non-volatile memory developers because process integration engineering scarcity concentrates within legacy memory manufacturers and acquisition multiples reflect IP portfolio depth rather than standalone revenue scale. Five-to-ten-year viability hinges on automotive functional safety mandate expansion. Watch for which regulatory jurisdictions first mandate non-volatile memory for functional safety as the inflection indicator for geographic sequencing of high-volume design wins.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Investment | AEC-Q100 certification opens ISO 26262-compliant supply to German and Japanese tier-one module manufacturers. |
| Embedded IP Licensing Expansion | Standard macro offerings at mature nodes capture IoT and microcontroller socket wins without captive memory overhead. |
| Green Chemistry Dossier Completion | ECHA REACH pre-qualification secures precursor chemical approval pathways for European automotive supply chains. |
| In-Memory Compute Architecture Development | Crossbar array integration with analog vector-matrix multiplication enables neural network inference acceleration paradigms. |
| Regional Foundry Partnership | India PLI scheme alignment creates licensing foothold in Gujarat and Karnataka greenfield fabrication investments. |
Study Parameters
Coverage spans East Asian fabrication clusters, European automotive supply chains, and North American advanced packaging research, with primary inputs from each region combining interviews with foundry process integration engineers, fabless SoC design architects, automotive tier-one procurement managers, and semiconductor equipment specialists. Secondary validation draws from MIIT industry guidelines, ECHA REACH substance databases, SEC semiconductor equipment filings, and ISO 26262 functional safety documentation. Bottom-up wafer start estimates and top-down memory market sizing undergo triangulation against foundry capacity announcements.
Rate-of-change decomposition separates volume expansion from value capture across the analysis window through segmentation modeling by integration depth, filament chemistry, application vertical, and end-user procurement sophistication. CAGRs derive from node transition timelines, automotive ECU content trajectories, and edge inference workload penetration curves. Forecast inputs include MIIT localization directive implementation pace, AEC-Q100 qualification completion rates, and in-memory compute architecture commercialization milestones.
Caveats apply where DRAM-NAND price compression acceleration, maritime chokepoint disruption, or regulatory jurisdiction sequencing for functional safety mandates could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Semiconductor Target Market
Semiconductors
China Semiconductor Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
North America Semiconductor Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
China Discrete Semiconductors Market