
 Japan Discrete Semiconductors Market | 2026-2036
Japan Discrete Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Discrete Semiconductors Market Insights
The capital-intensity divergence between integrated device manufacturers and fabless competitors is unwinding competitive dynamics across Japan's discrete semiconductor base. Renesas Electronics Corporation leverages its in-house fabrication network to sustain pricing power in automotive-grade MOSFETs. ROHM Co Ltd anchors its position through captive silicon carbide substrate production, while Toshiba Electronic Devices & Storage Corporation competes aggressively in industrial rectifier segments.
Discrete semiconductors are individual circuit elements—diodes, transistors, thyristors, and rectifiers—fabricated on silicon or compound semiconductor wafers using epitaxial growth, ion implantation, and photolithographic patterning to achieve breakdown voltages from tens to thousands of volts and switching speeds from kilohertz to megahertz, serving primarily as power conversion, signal conditioning, and protection components in electronic systems. Transistors and diodes together command the dominant share of product type revenue, with silicon carbide-based devices in the transistor category outpacing legacy silicon growth rates as automotive electrification intensifies. Among applications, automotive and industrial automation absorb the highest-margin production lots, while consumer electronics remains a high-volume, price-sensitive outlet.
METI's semiconductor subsidies, JIS standards for electronic component reliability, and PMDA-adjacent quality protocols for medical-grade devices collectively shape Japan's discrete semiconductor demand profile and qualification requirements. Manufacturers must navigate tightening energy-efficiency benchmarks under Japan's green transformation framework while maintaining backward compatibility with existing industrial installed bases. Stakeholders should monitor how METI's next funding round allocates resources between legacy node preservation and wide-bandgap material transitions.
Market Dynamics
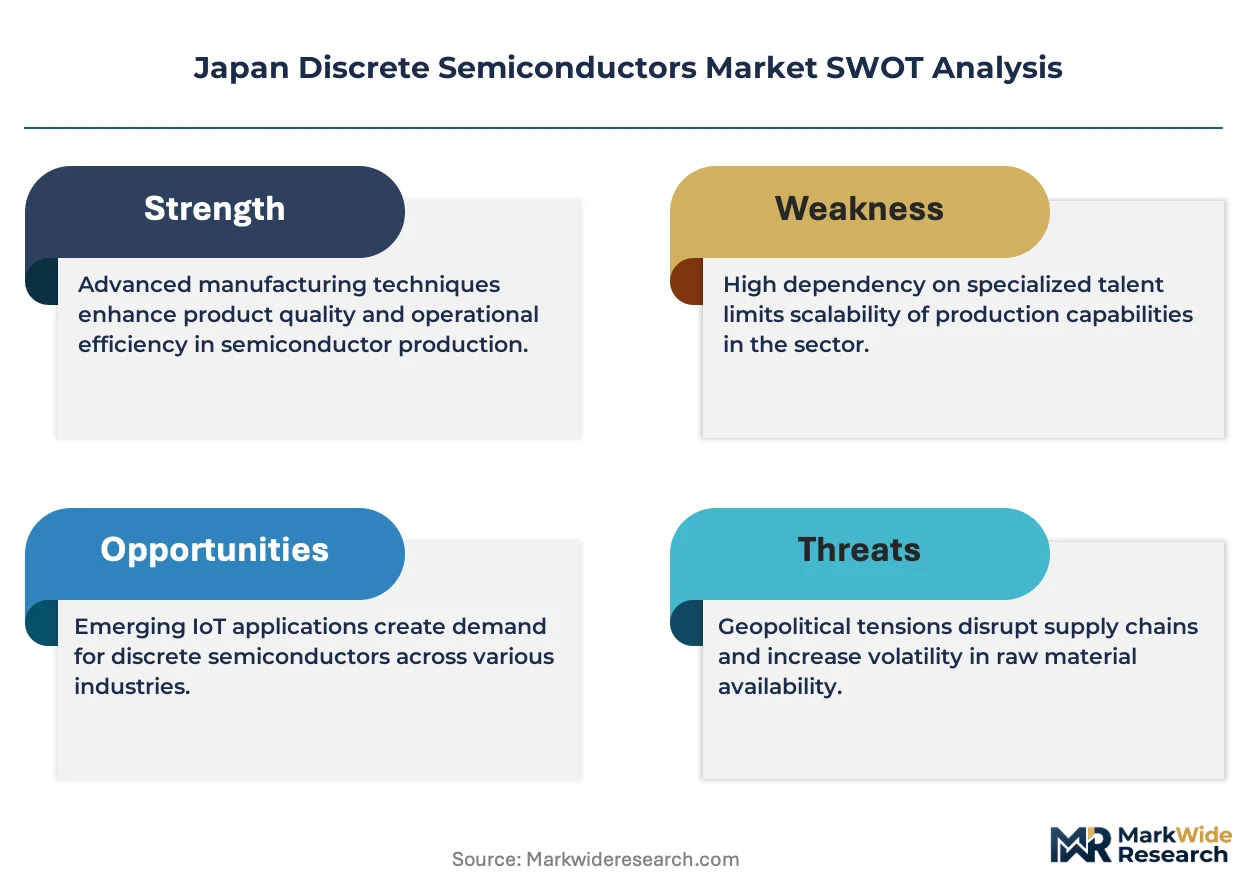
Silicon carbide substrate shortages are compressing lead times for automotive-grade power devices, forcing Japanese OEMs to renegotiate long-term supply agreements with domestic wafer producers while METI subsidies accelerate domestic SiC epitaxy capacity buildout.
Growth Catalysts
- Automotive electrification mandates:Japan's green transformation framework imposes stringent efficiency benchmarks on EV traction systems, pulling silicon carbide MOSFET demand from Tier-1 inverter suppliers.
- METI semiconductor revitalization subsidies:Direct capital grants for 200mm and 300mm wafer fabs are lowering entry barriers for wide-bandgap material transitions in discrete power devices.
- Kanto industrial corridor concentration:Dense clustering of automotive electronics assembly in Tokyo, Kanagawa, and Chiba prefectures creates localized demand pull for just-in-time component delivery.
Market Restraints
- Silicon carbide substrate cost volatility:Limited global supply of high-purity SiC boules constrains margin expansion for Japanese power device manufacturers dependent on imported raw material.
- Legacy node preservation requirements:Industrial automation customers demand multi-decade supply continuity for planar MOSFETs and IGBTs, locking capacity at mature process nodes.
- Import dependency for gallium nitride epitaxy:Domestic Japanese foundries lack production-scale GaN-on-Si capabilities, forcing reliance on Taiwanese and Korean epitaxial service providers.
Strategic Opportunities
- Hokkaido renewable energy zones:Offshore wind and geothermal expansion projects in northern Japan create demand for high-voltage rectifiers and protection devices in grid-tied power conversion systems.
- Medical-grade device certification:PMDA-adjacent quality protocols for implantable and diagnostic equipment open premium pricing tiers for hermetically packaged discrete components.
- Direct OEM contracting models:Automotive manufacturers are bypassing traditional distribution channels to negotiate volume commitments directly with Renesas, ROHM, and Toshiba device divisions.
Industry Challenges
- Compound semiconductor process engineering talent scarcity:Japanese universities produce insufficient SiC and GaN device physicists to staff expanding domestic epitaxy and fabrication facilities.
- Dual qualification burden:Suppliers must simultaneously maintain JIS C 1010 reliability certifications for industrial markets and AEC-Q101 automotive stress test compliance, extending product development cycles.
- Legacy system integration complexity:Industrial automation customers operate 20-30 year installed bases of silicon-based power electronics, creating friction for SiC retrofit adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Discrete Semiconductors Market |
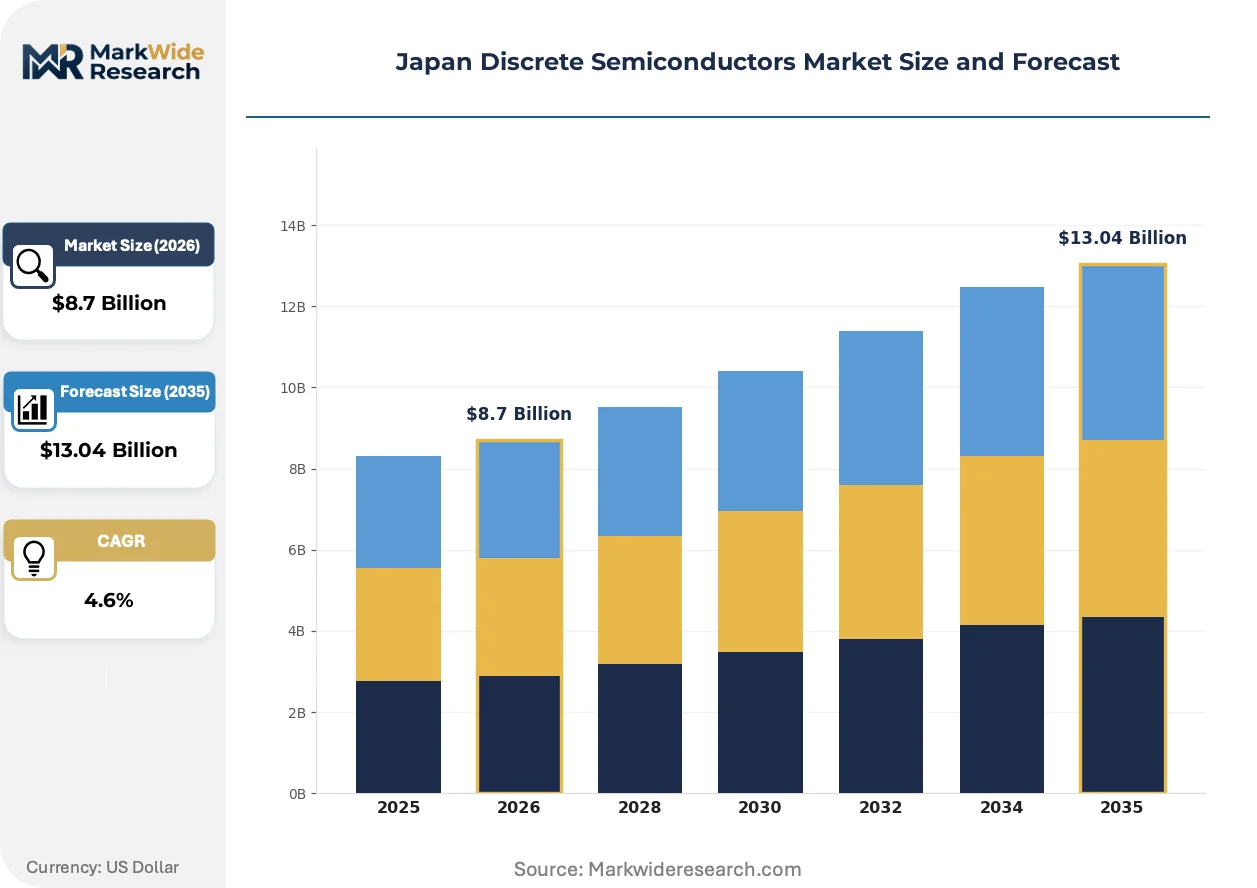
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, Transistors, Thyristors, Rectifiers Technology: Lithography, Additive, Substrates, Packaging Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications End User: OEMs, Aftermarket, Contract Manufacturers, Distributors |
| Companies Covered | Renesas Electronics Corporation, ROHM Co Ltd, Toshiba Electronic Devices & Storage Corporation, Infineon Technologies AG, STMicroelectronics NV, On Semiconductor Corporation, NXP Semiconductors NV, Diodes Incorporated, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Discrete Semiconductors Market Trends and Innovations
Wide-bandgap material transitions are fragmenting established competitive hierarchies in Japan's discrete semiconductor base, while regulatory pressure on energy efficiency and supply chain localization reshape investment priorities across the value chain.
Silicon carbide power MOSFET technology enables higher switching frequencies and reduced thermal losses in EV traction inverters compared to silicon IGBTs. Automotive OEMs in Japan are adopting SiC devices at accelerating rates for 800V platform architectures. This adoption is fragmenting the traditional silicon-dominant supply base, compressing market share for legacy planar MOSFET suppliers while elevating vertically integrated SiC substrate producers.
METI's green transformation framework mandates progressive efficiency improvements in industrial motor drives and power conversion equipment. The regulation forces discrete semiconductor suppliers to prioritize wide-bandgap device development over silicon legacy product extensions. Power module manufacturers serving Japan's industrial automation sector are responding by accelerating SiC and GaN qualification timelines to maintain eligibility for public procurement contracts.
Automotive Tier-1 suppliers are consolidating vendor lists and demanding direct technical collaboration with discrete semiconductor manufacturers on custom device specifications. This disintermediation bypasses traditional Japanese electronics distributors like Macnica and Chip One Stop for high-volume power device procurement. The shift is most visible in Kanagawa and Aichi prefectures, where inverter assembly plants for Toyota, Honda, and Nissan are co-locating engineering teams with device supplier R&D facilities.
Japan Discrete Semiconductors Market Segmentation
Discrete semiconductor procurement in Japan channels through distinct pathways depending on application criticality and volume scale. Automotive OEMs negotiate direct contracts for silicon carbide power devices, while industrial buyers rely on authorized distributors for legacy component continuity.
Product Type:
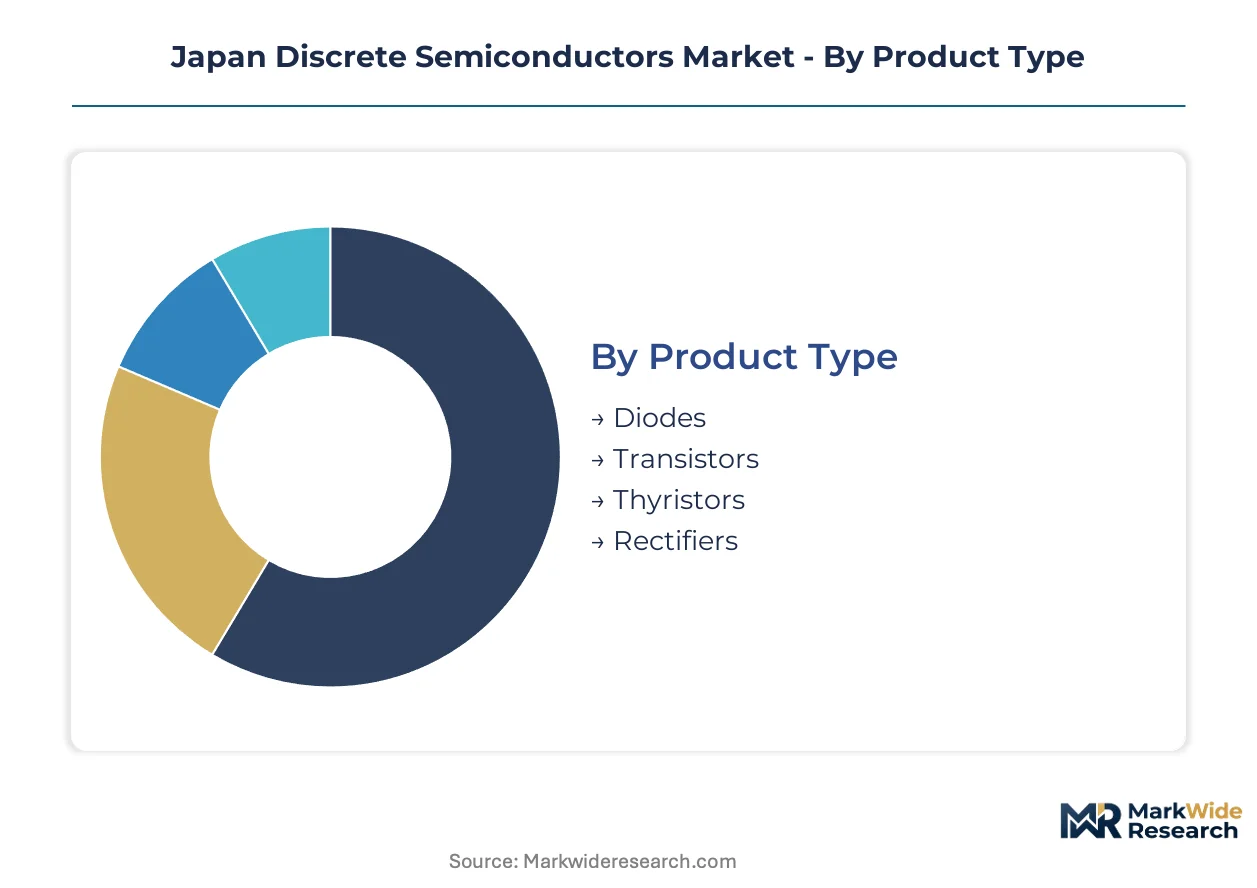
Channel mix varies sharply by product category. Transistors and diodes flow primarily through direct OEM agreements in automotive and high-volume industrial segments. Thyristors and rectifiers move predominantly through distributor networks serving maintenance and replacement demand.
- Diodes:These two-terminal devices enable unidirectional current flow for rectification, voltage clamping, and signal isolation. Demand clusters in Kanagawa Prefecture inverter assembly plants where Toyota and Honda procurement teams specify silicon carbide Schottky variants for 800V EV platforms.
- Transistors:Three-terminal switching and amplification devices fabricated on silicon and silicon carbide substrates. Automotive traction inverter manufacturers in Aichi Prefecture are pulling MOSFET and IGBT volumes through direct technical partnerships with domestic device suppliers.
- Thyristors:Four-layer semiconductor switches for high-power AC control in industrial motor drives and grid-connected equipment.
- Rectifiers:Power conversion components converting AC to DC for power supplies and battery charging systems across industrial automation installed bases.
Transistors dominate installed base in revenue terms. Diodes are where expansion concentrates as wide-bandgap material transitions accelerate.
Technology:
Cost tier separation distinguishes technology segments. Lithography and substrate production command premium capital investment and captive in-house capacity. Additive processes and packaging operate at lower margin tiers with greater outsourcing flexibility.
- Lithography:Photopatterning processes defining device geometries through photoresist exposure and etch sequences. METI subsidy eligibility for 200mm and 300mm wafer fabs is concentrating investment in Tokyo and Chiba fabrication facilities serving automotive qualification pipelines.
- Substrates:Silicon and silicon carbide wafer production including epitaxial layer growth for power device active regions. ROHM's captive SiC boule production in Kyoto anchors domestic supply as imported material costs fluctuate.
- Additive:Ion implantation and metallization processes modifying wafer electrical properties and forming interconnect structures.
- Packaging:Die attach, wire bonding, and encapsulation processes determining thermal performance and reliability in end-use environments.
Substrates dominate capital deployment. Lithography is where technology transition friction concentrates.
Application:
Customer type segmentation separates application demand. Automotive and industrial automation buyers specify custom devices through engineering collaboration. Consumer electronics and telecommunications procurement favors standard catalog components through distribution.
- Automotive:EV traction inverters, onboard chargers, and DC-DC converters requiring AEC-Q101 qualified devices. Tier-1 suppliers in Kanagawa and Aichi prefectures are consolidating vendor lists and demanding direct technical collaboration on custom MOSFET specifications.
- Industrial Automation:Motor drives, power supplies, and robotics systems requiring multi-decade supply continuity for planar MOSFETs and IGBTs. JIS C 1010 reliability certifications dominate procurement criteria in this segment.
- Consumer Electronics:Power adapters, white goods, and personal electronics representing high-volume, price-sensitive demand through standard distribution channels.
- Telecommunications:Base station power amplifiers and network infrastructure equipment requiring RF-optimized discrete components.
Industrial automation dominates installed base longevity requirements. Automotive is where technology substitution concentrates.
End User:
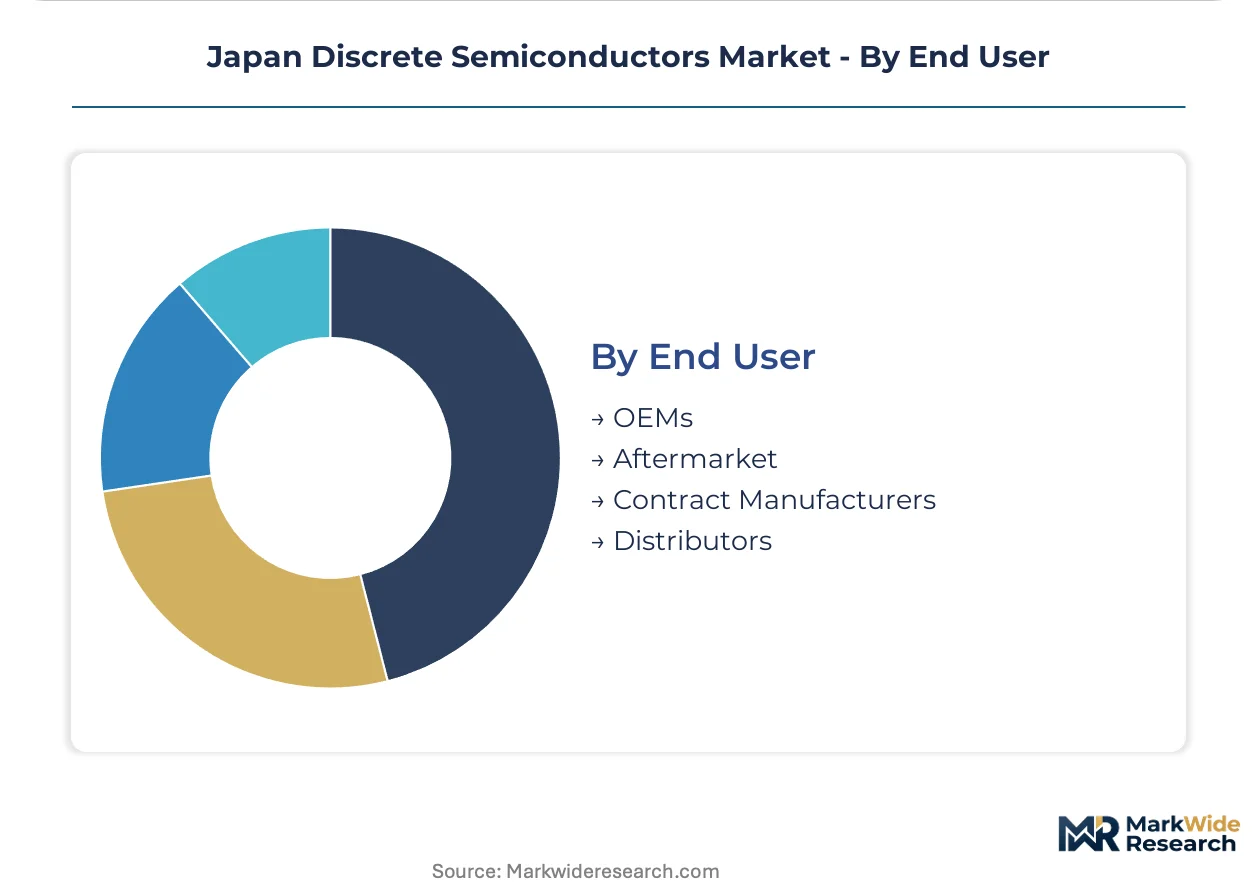
Volume scale determines end user channel structure. OEMs and contract manufacturers at sufficient scale bypass distribution for direct manufacturer contracts. Aftermarket and smaller distributors remain dependent on authorized channel inventory.
- OEMs:Original equipment manufacturers in automotive and industrial sectors negotiating volume commitments directly with Renesas, ROHM, and Toshiba device divisions. This disintermediation bypasses traditional Japanese electronics distributors for high-volume power device procurement.
- Contract Manufacturers:Electronics manufacturing services providers assembling systems for brand owners, procuring through hybrid direct-and-distributor models depending on customer-specified component approvals.
- Distributors:Authorized resellers including Macnica and Chip One Stop maintaining inventory for mid-volume industrial and commercial customers requiring just-in-time delivery.
- Aftermarket:Replacement part suppliers and maintenance service providers sourcing legacy node devices for 20-30 year industrial installed base support.
OEMs dominate high-value transaction flow. Contract manufacturers are where channel complexity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan's Kanto industrial corridor demonstrate the lowest price sensitivity for automotive-grade silicon carbide devices, while consumer electronics procurement across western prefectures operates on thin margins where cost dominates supplier selection. This elasticity divergence shapes regional investment patterns and subsidy allocation under METI's semiconductor strategy.
Kanto
Tokyo, Kanagawa, and Chiba prefectures concentrate Japan's highest-value discrete semiconductor demand from EV traction inverter assembly plants. METI's green transformation framework channels capital grants toward 200mm and 300mm wafer fabrication facilities in this corridor. Toyota and Honda procurement teams in Kanagawa specify silicon carbide MOSFETs through direct technical partnerships with domestic device suppliers.
Kansai
Osaka and Kyoto anchor captive silicon carbide substrate production and legacy power device manufacturing for industrial automation. ROHM's in-house SiC boule growth in Kyoto reduces import dependency as global raw material costs fluctuate. JIS C 1010 reliability certifications dominate procurement criteria for planar MOSFETs serving multi-decade industrial installed bases.
Chubu
Aichi Prefecture's automotive electronics cluster generates concentrated demand for AEC-Q101 qualified transistors and diodes. Tier-1 inverter suppliers are consolidating vendor lists and co-locating engineering teams with device manufacturer R&D facilities. METI subsidies for wide-bandgap material transitions accelerate qualification timelines for 800V platform architectures.
Kyushu
Fukuoka and neighboring prefectures host packaging and testing operations for power modules serving industrial motor drives. The region captures overflow capacity from Kanto fabrication facilities as lead times compress for automotive-grade devices. Local suppliers navigate dual qualification burdens for industrial and automotive markets.
Hokkaido
Offshore wind and geothermal expansion projects in northern Japan create emerging demand for high-voltage rectifiers and protection devices. Grid-tied power conversion systems require hermetically packaged components qualified for harsh environmental conditions. METI's renewable energy subsidies indirectly stimulate discrete semiconductor procurement for infrastructure buildout.
Japan Discrete Semiconductors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's discrete semiconductor base. Vertically integrated manufacturers with captive substrate production command premium positioning in silicon carbide power devices, while fabless competitors and foreign suppliers compete on price in standard silicon segments. Three archetypes dominate: integrated device manufacturers with in-house fabrication networks, compound semiconductor specialists with upstream material control, and global diversified suppliers leveraging scale. Competitive dynamics center on capacity expansion for wide-bandgap epitaxy and strategic partnerships for gallium nitride process development.
Among Japan-based integrated device manufacturers, Renesas Electronics Corporation, ROHM Co Ltd, and Toshiba Electronic Devices & Storage Corporation occupy positions defined by fabrication asset ownership and substrate supply strategies. Renesas exemplifies the IDM archetype through its automotive-grade MOSFET pricing power sustained by in-house wafer networks. ROHM anchors the compound semiconductor specialist tier through captive silicon carbide boule production in Kyoto. Toshiba represents the diversified industrial supplier competing aggressively in rectifier segments while managing legacy node preservation requirements. Foreign competitors including Infineon Technologies AG and STMicroelectronics NV compete through direct OEM contracting models that bypass traditional Japanese distribution channels.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| ROHM Co Ltd |
| Toshiba Electronic Devices & Storage Corporation |
| Infineon Technologies AG |
| STMicroelectronics NV |
| On Semiconductor Corporation |
| NXP Semiconductors NV |
| Diodes Incorporated |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Toyota and Honda procurement teams and domestic SiC substrate producers lock in supply access while anchoring price visibility across volatile raw material cycles. METI capital grants for 200mm and 300mm wafer fabs further stabilize input cost forecasting for Japanese power device manufacturers negotiating with Kanto-based inverter assembly plants.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value capture for Japanese discrete semiconductor suppliers serving automotive OEMs. Pricing stratifies across AEC-Q101 qualified premium tiers, JIS C 1010 industrial certification mid-tiers, and unqualified economy tiers for consumer electronics. Cost compression in standard silicon MOSFETs is intensifying because fabless competitors from Taiwan and Korea flood spot markets. Industrial automation buyers in Kansai demonstrate lowest price sensitivity due to multi-decade installed base support requirements, while consumer electronics procurement in western prefectures operates on thin margins where cost dominates supplier selection.
Supply Chain Analysis
Port congestion on transpacific lanes and container availability constraints from Taiwanese and Korean epitaxial service providers elevate inbound logistics costs for Japanese GaN device manufacturers. Domestic supply draws from captive SiC boule production in Kyoto, silicon wafer fabrication in Tokyo and Chiba, and outsourced GaN-on-Si epitaxy from Taiwan and Korea. High-purity SiC substrate supply rests on limited global boule growers, creating single-source vulnerability for automotive-grade power device qualification pipelines. Distribution runs through direct OEM contracting for high-volume automotive tiers, with authorized distributors like Macnica serving mid-volume industrial maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan Discrete Semiconductors Market functions as a defensive-moat story anchored in regulatory entrenchment. METI qualification requirements and JIS reliability certifications create switching costs that protect incumbent positions against foreign competitors.
For Market Incumbents: Shield automotive-grade MOSFET pricing power by deepening captive SiC substrate production in Kyoto and Kansai, countering cost volatility from imported boule suppliers. Accelerate AEC-Q101 certification pipelines for 800V platform architectures to lock out emerging GaN specialists before they achieve automotive qualification. Channel METI subsidy access toward 300mm wafer fab capacity in Kanto, preserving technical collaboration advantages with co-located Tier-1 inverter engineering teams. For New Entrants and Emerging Players: Anchor in Hokkaido renewable energy zones where offshore wind and geothermal expansion creates uncontracted demand for high-voltage rectifiers and protection devices. Target medical-grade device segments requiring PMDA-adjacent quality protocols, where hermetic packaging premiums offset volume disadvantages against industrial suppliers. Pursue direct contracting with grid-tied power conversion system integrators bypassing established automotive vendor lists. For Investors and Strategic Acquirers: Compound semiconductor specialists with upstream material control represent the most defensible acquisition archetype as wide-bandgap transitions accelerate. Evaluate targets through the lens of 5-10 year substrate supply security rather than near-term fabrication capacity. Monitor METI funding round allocations between legacy node preservation and SiC epitaxy expansion as the critical inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Expansion | ROHM's in-house boule growth in Kyoto reduces import dependency as global raw material costs fluctuate. |
| Direct OEM Contracting Models | Toyota and Honda procurement teams bypass traditional distributors for volume commitments with device suppliers. |
| AEC-Q101 Certification Acceleration | Tier-1 inverter suppliers consolidate vendor lists around automotive-qualified MOSFET and IGBT specifications. |
| Hokkaido Renewable Energy Supply | Offshore wind projects create demand for hermetically packaged rectifiers in grid-tied power conversion systems. |
| GaN Epitaxy Partnership Development | Domestic foundries lack production-scale GaN-on-Si capabilities, forcing reliance on Taiwanese service providers. |
Research Methodology
Initial hypotheses were tested against primary input from power device procurement managers at automotive Tier-1 suppliers, semiconductor fabrication engineers, METI policy officials, and industrial automation maintenance directors, then refined through secondary validation. Primary fieldwork combined structured interviews with channel partners including Macnica and Chip One Stop, alongside technical discussions with ROHM and Renesas device division executives. Secondary sources encompassed METI subsidy disclosure filings, JIS C 1010 certification databases, AEC-Q101 test standard documentation, and customs records for SiC substrate imports. Bottom-up demand modeling from end-use application clusters was triangulated against top-down wafer fab capacity announcements.
Variance decomposition across product type, technology tier, application segment, and regional demand cluster shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled included transistor versus diode product categories, silicon versus wide-bandgap technology transitions, automotive versus industrial automation application splits, and OEM versus distributor channel structures. CAGRs were derived from installed base replacement cycles, EV platform adoption curves, and METI green transformation compliance timelines. Forecast inputs incorporated SiC substrate supply elasticity, GaN epitaxy qualification delays, and Kanto industrial corridor concentration effects.
Decision-makers should treat outputs as directional under assumptions of continued METI subsidy continuity, stable transpacific logistics lanes, and incremental rather than disruptive wide-bandgap material transitions; material deviation would warrant model refresh. Specific risk factors include tariff escalation on Taiwanese GaN epitaxy services, abrupt JIS standard revisions, and foreign competitor bypass of traditional Japanese distribution channels. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
North America Semiconductor Market
Semiconductors
Semiconductor Clock Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
China Discrete Semiconductors Market