
 Europe Semiconductor Market | 2026-2036
Europe Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Semiconductor Market Insights
Automotive OEMs are unwinding their historical dependence on consumer electronics suppliers for chip procurement. Infineon Technologies AG anchors European automotive semiconductor production through its Dresden and Villach manufacturing footprint. STMicroelectronics N.V. competes aggressively in silicon carbide power devices for traction inverters. NXP Semiconductors N.V. dominates secure connectivity and vehicle networking architectures across German and French automotive programs.
Semiconductors are crystalline solid-state materials, typically silicon or compound substrates like gallium nitride and silicon carbide, engineered with precise doping profiles to control electrical conductivity for signal processing and power switching. CMOS technology sustains cost-efficient digital logic production for European consumer and industrial applications, while GaN and SiC segments capture expanding margin pools in automotive electrification and renewable energy inverters. Analog and sensor categories lead revenue contribution from industrial automation and automotive safety systems, whereas artificial intelligence and data center applications represent the fastest-growing demand vectors for advanced digital and memory-intensive architectures.
The EU Chips Act, REACH chemical compliance, and CE marking requirements collectively reshape capital allocation toward sovereign manufacturing capacity and restricted substance substitution. ECHA substance evaluations and RoHS directives force material transitions in packaging and wafer processing chemistries. Stakeholders must monitor subsidy disbursement timelines under the EU Chips Act while calibrating R&D bets across compound semiconductor platforms and legacy node continuity for automotive supply security.
Market Dynamics
Automotive electrification and the EU Chips Act are jointly restructuring European semiconductor demand patterns, pulling investment away from legacy consumer nodes toward sovereign capacity for power electronics and secure automotive architectures.
Growth Catalysts
- EU Chips Act subsidy disbursements:National governments in Germany, France, and Italy are channeling state aid toward 300mm wafer fabrication, accelerating domestic capacity buildouts for automotive-grade silicon.
- Silicon carbide traction inverter demand:Battery-electric vehicle platforms from Stuttgart to Wolfsburg are specifying SiC power modules, creating dedicated procurement lanes separate from silicon IGBT supply chains.
- REACH-compliant material substitution:ECHA substance restrictions on lead-based solders and halogenated flame retardants are forcing packaging chemistry transitions that favor European substrate and interconnect suppliers.
Market Restraints
- Neon gas supply concentration:Ukrainian neon purification infrastructure remains vulnerable to supply disruption, constraining lithography laser operations across Dutch and German fabs.
- Lithography equipment import dependency:Extreme ultraviolet scanner procurement depends on single-source Dutch equipment vendors, creating capex bottlenecks for advanced node expansion.
- RoHS exemption expiration timelines:Pending restrictions on cadmium and lead in high-reliability automotive applications threaten qualification continuity for legacy component families.
Strategic Opportunities
- Polish and Romanian packaging corridors:Lower-cost substrate and test operations in Eastern European member states offer margin expansion for automotive module assembly.
- GaN-on-Si power integration:Gallium nitride devices for onboard chargers and DC-DC converters represent underexploited white space between silicon MOSFETs and SiC modules.
- CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements are creating competitive differentiation for European fabs with verified low-carbon wafer processing.
Industry Challenges
- Compound semiconductor process engineering scarcity:European universities produce insufficient GaN and SiC epitaxy specialists, forcing fabs to recruit from aerospace and defense programs.
- Automotive qualification timeline compression:AEC-Q100 and AEC-Q101 certification cycles conflict with vehicle platform launch schedules, compressing design-in windows.
- Legacy node equipment obsolescence:Depreciation of 200mm toolsets threatens supply security for mature automotive microcontrollers as foundries prioritize advanced node returns.
Report Scope
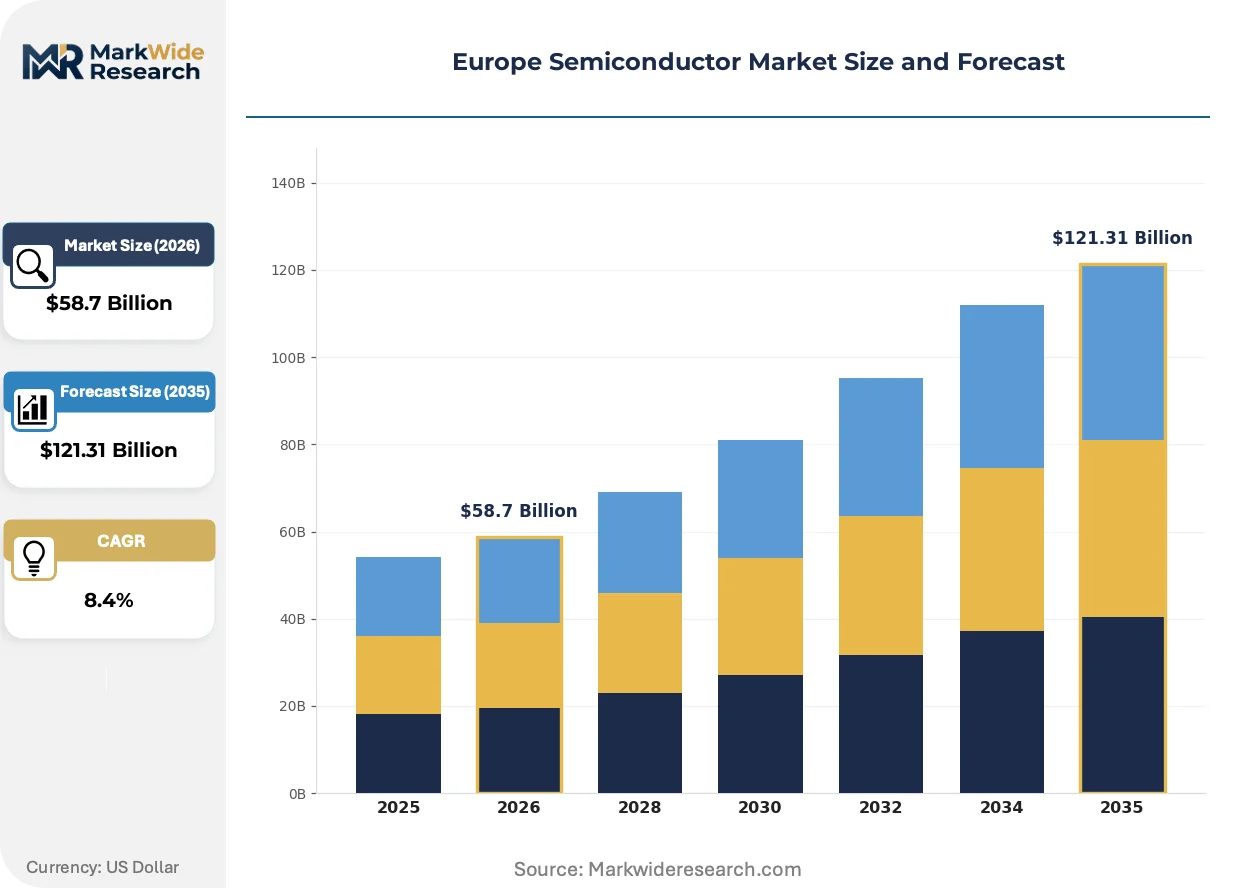
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Semiconductor Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Microcontrollers, Sensors End User: Consumer Electronics, Automotive, Industrial, Telecommunications Technology: CMOS, BiCMOS, GaN, SiC Application: Artificial Intelligence, IoT, Cloud Computing, Data Centers |
| Companies Covered | ASML Holding N.V., Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., ams OSRAM AG, Robert Bosch GmbH, ASM International NV, Melexis NV, Elmos Semiconductor SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Semiconductor Market Trends and Innovations
European semiconductor manufacturing is pivoting from cost-optimized global sourcing toward sovereignty-driven capacity localization, with process technology and supply architecture evolving in parallel.
Silicon carbide MOSFETs are supplanting silicon IGBTs in 800-volt electric vehicle architectures. BMW Group and Volkswagen Group procurement teams are specifying SiC for traction inverters above 150 kW. This transition is compressing silicon foundry utilization rates for automotive power while expanding margin pools for European substrate and epitaxy specialists.
REACH authorization procedures are forcing substitution of hexavalent chromium in leadframe plating and underfill chemistries. ECHA sunset dates for specific substances are accelerating material qualification programs at OSAT providers. German automotive tier-one suppliers are responding by consolidating qualified material lists and pushing packaging partners toward green chemistry certifications.
Direct OEM-semiconductor contracting is fragmenting traditional tiered distribution. Bosch, Continental, and ZF Friedrichshafen are establishing direct engineering relationships with European power semiconductor vendors, bypassing established component distributors for strategic silicon categories. This pattern is most visible in Munich and Stuttgart engineering centers, where vehicle platform teams co-develop thermal and electrical specifications with fab process engineers.
Europe Semiconductor Market Segmentation
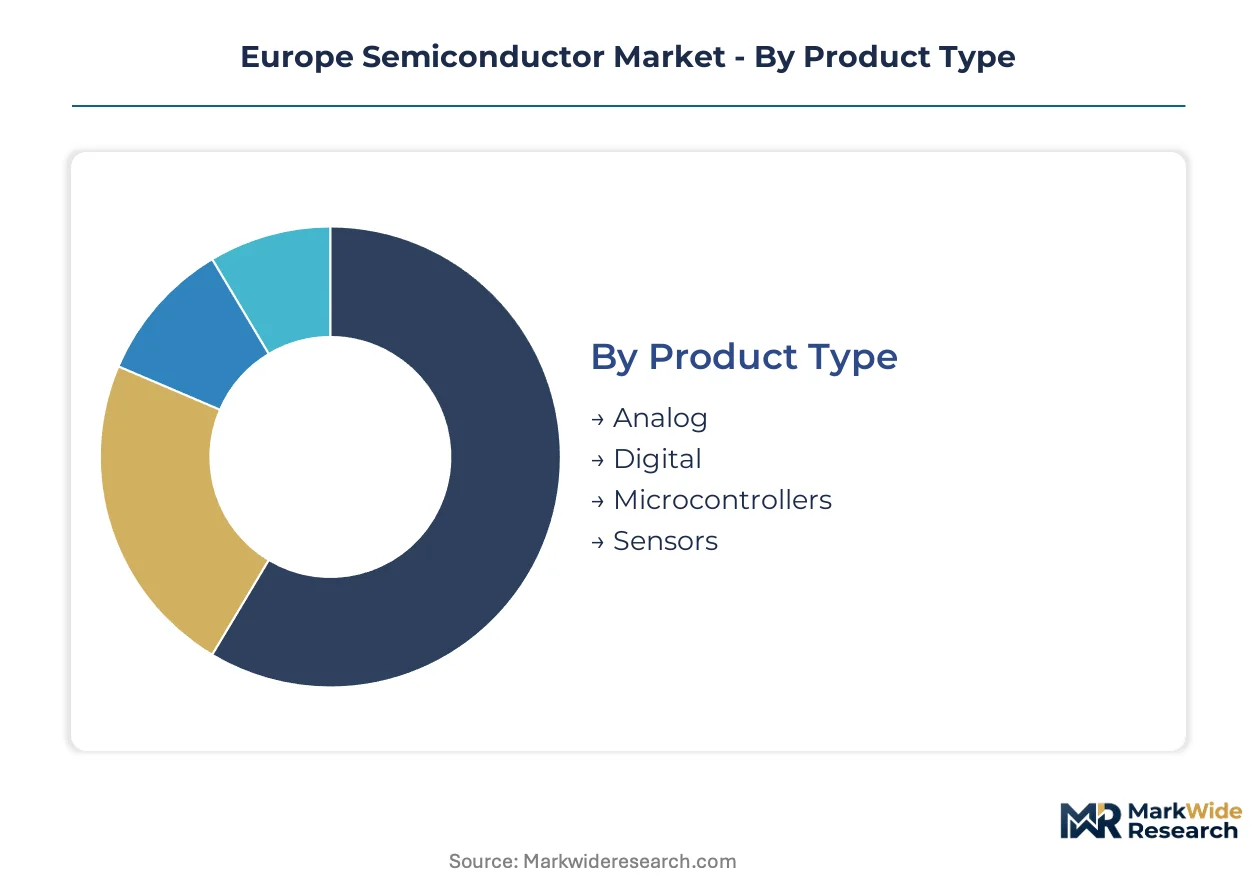
European semiconductor procurement patterns diverge sharply across product architectures and end-use verticals. REACH substance restrictions and AEC-Q automotive qualification tiers create regulatory fault lines that reshape supplier selection and margin capture.
Product Type:
REACH authorization timelines and RoHS exemption expirations force material transitions that favor certain wafer processing chemistries over others.
- Analog:Precision signal conditioning circuits for industrial automation and automotive sensor interfaces. German automotive tier-one suppliers concentrate procurement for battery management systems in Stuttgart and Wolfsburg programs. ECHA restrictions on halogenated compounds accelerate green chemistry transitions in packaging.
- Digital:Logic devices fabricated on CMOS nodes for consumer and enterprise compute. Dutch lithography ecosystems anchor advanced node production, though neon supply vulnerability from Ukrainian purification infrastructure constrains capacity expansion timelines.
- Microcontrollers:Embedded control units for automotive body electronics and industrial motor drives.
- Sensors:MEMS and environmental detection elements for ADAS and factory automation.
Analog handles the majority of throughput; Sensors is the fastest mover on share.
End User:
Customer procurement authority concentrates in engineering centers with direct OEM-semiconductor contracting authority.
- Automotive:Power electronics and secure networking architectures for electrified platforms. BMW Group and Volkswagen Group procurement teams in Munich and Stuttgart specify SiC traction inverters above 150 kW, bypassing traditional distribution tiers for strategic silicon categories.
- Industrial:Motor drives, PLCs, and renewable energy inverters. French automation clusters around Lyon and German industrial corridors anchor demand for ruggedized components with extended temperature ratings.
- Consumer Electronics:Mobile and compute devices with compressed lifecycle requirements.
- Telecommunications:Baseband and RF infrastructure for 5G deployment.
Automotive commands the dominant procurement volume; Industrial is climbing the fastest on share expansion.
Technology:
Process platform selection determines capex intensity and subsidy eligibility under EU Chips Act disbursement criteria.
- CMOS:Cost-optimized digital logic production sustaining European consumer and industrial applications. German and French fabs prioritize 300mm wafer capacity for automotive-grade silicon with sovereign supply security mandates.
- SiC:Wide-bandgap power devices for 800-volt traction inverters and onboard chargers. Battery-electric vehicle platforms from Stuttgart to Wolfsburg specify SiC modules, compressing silicon IGBT utilization while expanding margin pools for European substrate specialists.
- BiCMOS:Mixed-signal integration for RF and precision analog applications.
- GaN:High-frequency power switching for DC-DC converters and telecom infrastructure.
CMOS maintains the installed capacity base; SiC is gaining share fastest on electrification pull-through.
Application:
Compute intensity and data sovereignty requirements reshape demand concentration across European hosting clusters.
- Data Centers:Server processors and memory architectures for cloud and enterprise workloads. Frankfurt and Amsterdam hosting corridors drive advanced digital and memory-intensive procurement with CSRD disclosure mandates favoring low-carbon wafer verification.
- Artificial Intelligence:Accelerators and edge inference engines for automotive and industrial vision systems. German OEMs co-develop thermal specifications with fab engineers for autonomous driving compute platforms.
- IoT:Connected sensor networks for smart factory and building automation.
- Cloud Computing:Hyperscale infrastructure with sovereign data localization requirements.
Data Centers absorbs the dominant silicon volume; Artificial Intelligence shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch lithography equipment flows predominantly to German fabs and Taiwanese foundries, anchoring Europe's position in the global semiconductor capital goods trade. This equipment corridor shapes regional investment patterns and subsidy allocation across the continent.
Germany
Automotive electrification and industrial automation anchor semiconductor demand in Baden-Württemberg and Bavaria. The EU Chips Act channels state aid toward 300mm wafer fabrication in Dresden, where Infineon Technologies AG operates sovereign capacity for power electronics. Munich engineering centers co-develop thermal specifications with fab process engineers for 800-volt traction inverters.
Netherlands
Extreme ultraviolet lithography equipment production concentrates around Veldhoven, supplying global advanced node capacity. REACH authorization procedures force substitution of hexavalent chromium in equipment manufacturing chemistries. Eindhoven's high-tech ecosystem anchors photonics and sensor packaging operations for automotive tier-one suppliers.
France
Secure connectivity architectures and GaN power devices drive procurement from Crolles and Rousset manufacturing sites. The EU Green Deal carbon border adjustments favor domestic wafer processing with verified low-carbon credentials. Lyon automation clusters anchor industrial semiconductor demand for motor drives and renewable energy inverters.
Italy
Mixed-signal and power discrete production concentrates in Agrate Brianza and Catania, serving automotive body electronics. National recovery fund disbursements under the EU Chips Act accelerate 200mm capacity modernization for legacy automotive microcontrollers. Emilia-Romagna's machine tool corridor generates sustained demand for ruggedized industrial components.
Poland
Lower-cost packaging and test operations in Wrocław and Warsaw corridors offer margin expansion for automotive module assembly. CSRD supply chain disclosure mandates create competitive differentiation for Eastern European assembly sites with verified carbon accounting. The country's industrial zones attract OSAT investment for power module integration serving German OEMs.
Europe Semiconductor Market Competitive Landscape
Listed leaders compete with private specialists across sovereign capacity development, creating a tiered structure where scale-driven fabricators face agile technology licensors. The vendor base separates into three strategic archetypes: integrated device manufacturers with captive fabs, fabless specialists licensing process technology, and equipment vendors controlling lithography bottlenecks. Dominant competitive moves include backward integration into substrate and epitaxy supply, alongside geographic expansion into Eastern European packaging corridors.
Within the integrated device manufacturer tier, Infineon Technologies AG and STMicroelectronics N.V. exemplify European sovereign production strategies, while ASML Holding N.V. occupies a position as the dominant lithography equipment vendor. These three anchors represent distinct competitive vectors: power electronics fabrication, mixed-signal integration, and capital goods supply chain control.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| ams OSRAM AG |
| Robert Bosch GmbH |
| ASM International NV |
| Melexis NV |
| Elmos Semiconductor SE |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German automotive OEMs and Dresden-based power semiconductor fabs lock in wafer capacity allocation and provide price visibility across volatile raw material cycles. These agreements tether procurement costs to neon gas and silicon carbide substrate indices while insulating buyers from spot market spikes in lithography consumables.
Pricing Analysis
Silicon carbide MOSFETs command substantial premiums over silicon IGBTs and legacy planar MOSFETs in automotive traction inverter applications. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels reflects AEC-Q101 qualification burden and thermal performance thresholds. Cost compression in silicon power devices is intensifying because foundries prioritize advanced node returns over legacy automotive microcontroller production. Tier-one automotive suppliers exhibit lowest price sensitivity due to platform qualification lock-in, whereas industrial motor drive OEMs negotiate aggressively on volume commitments.
Supply Chain Analysis
Ukrainian neon purification infrastructure underwrites lithography laser gas supply for Dutch and German fabs, creating a single-source vulnerability amplified by geopolitical disruption. European semiconductor manufacturing draws from Taiwanese foundry capacity for advanced digital logic, German substrate specialists for silicon carbide epitaxy, and Dutch equipment vendors for extreme ultraviolet scanners. Raw material dependencies span high-purity neon from Ukrainian cryogenic plants, fluorinated gases from Belgian chemical processors, and silicon carbide boules from Norwegian crystal growers. Tariff exposure on Chinese rare earth processing constrains magnet material flows for automotive sensor modules. Distribution runs through direct OEM-fab contracting that fragments traditional component distribution tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification fragments procurement authority across vehicle platform teams, creating specialization opportunities for power semiconductor specialists and packaging innovators. Sovereignty mandates under the EU Chips Act accelerate niche formation for domestic substrate and epitaxy capabilities.
For Market Incumbents: Secure captive silicon carbide substrate supply through backward integration into boule growth and epitaxy operations, insulating margin pools from raw material volatility. Expand 300mm wafer capacity in Dresden and Villach corridors to capture EU Chips Act subsidy disbursements before qualification timelines compress. Defend against emerging GaN-on-Si specialists by accelerating AEC-Q101 certification cycles for next-generation power modules. For New Entrants and Emerging Players: Lead with GaN power integration for onboard chargers and DC-DC converters in the 400-volt to 800-volt transition window, exploiting white space between silicon MOSFETs and SiC modules. Target Polish and Romanian packaging corridors for automotive module assembly, leveraging lower-cost substrate operations and CSRD-aligned carbon accounting. Pursue direct engineering relationships with Munich and Stuttgart OEM platform teams, bypassing established distribution tiers through co-development partnerships. For Investors and Strategic Acquirers: The market sits at a sovereign capacity buildout phase that favors compound semiconductor substrate specialists and automotive-qualified packaging innovators. Long-term viability hinges on securing positions in silicon carbide epitaxy and gallium nitride-on-silicon process platforms before qualification timelines compress further. Acquisition target archetype: mid-cap European OSAT providers with verified green chemistry certifications and established German automotive tier-one relationships. Watch EU Chips Act subsidy disbursement velocity as the inflection indicator for domestic capacity expansion momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captures margin pools in Norwegian boule growth and German epitaxy operations. |
| GaN-on-Si Process Platform Investment | Exploits white space in 400-volt onboard charger applications between silicon and SiC. |
| Eastern European Packaging Corridor Expansion | Leverages Polish and Romanian cost structures for automotive module assembly. |
| Direct OEM-Fab Contracting Relationships | Bypasses distribution tiers through co-development with Munich and Stuttgart engineering centers. |
| REACH-Compliant Green Chemistry Certification | Differentiates packaging operations under ECHA substance restriction timelines. |
Research Methodology
The analysis maps power semiconductor fabrication, analog and sensor production, lithography equipment supply, and automotive packaging sub-sectors, each validated through semiconductor process engineers, Tier 1 supplier procurement leads, OEM platform engineering directors, and ECHA regulatory affairs specialists. Primary fieldwork combined structured interviews with secondary validation against SEMI trade statistics, EU Chips Act disbursement filings, ECHA substance restriction databases, and automotive production registration data. Bottom-up wafer capacity modeling triangulated against top-down OEM semiconductor content forecasts.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework segmented by product architecture, end-use vertical, process technology, and application intensity, modeling vehicle electrification penetration and data center compute demand as industry-specific forecast inputs. CAGRs were derived from fitted growth curves anchored to disclosed fab capacity expansion timelines and OEM platform launch schedules.
Forecasts assume regulatory continuity in EU Chips Act disbursement criteria and REACH authorization timelines; material policy shifts would require re-modeling of subsidy eligibility and substance substitution pathways. Practitioners should keep alternative scenarios live as ECHA sunset date revisions and Ukrainian neon supply stabilization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
China Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Analog Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Chiplets Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Germanium Semiconductor Market