
 Gaas Wafer Market | 2026-2036
Gaas Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Gaas Wafer Market Analysis
China is narrowing its technological gap against Japanese and German substrate leaders through state-backed capital deployment in 6-inch and 8-inch GaAs foundries. Sumitomo Electric Industries leverages vertical integration from crystal growth through epitaxial services to sustain premium positioning in RF and photonics grades. Freiberger Compound Materials GmbH anchors European supply security for defense and space-qualified wafers, while AXT Inc competes on cost-engineered substrates for LED and consumer laser applications.
Gallium arsenide wafers are compound semiconductor substrates fabricated from single-crystal ingots grown via vertical gradient freeze or liquid encapsulated Czochralski methods, typically achieving electron mobilities exceeding silicon by a factor of six and serving as the foundational material for high-frequency and optoelectronic devices. The epitaxial wafer segment dominates value capture due to the technical complexity of depositing lattice-matched layers for RF power amplifiers and laser diodes, while the RF Devices application category leads volume absorption from 5G base station rollouts and satellite communications terminals. Substrate wafer production remains concentrated among established crystal growers, with thickness standardization shifting toward thinner specifications to reduce material consumption per die.
Japan's METI coordinates national semiconductor strategy including GaAs supply chain resilience, while China's SAMR enforces revised GB standards for electronic-grade compound semiconductors and REACH compliance in Europe restricts hazardous precursor chemicals in wafer processing. The US FCC and Department of Defense procurement rules increasingly prioritize domestic or allied-nation substrate sourcing for critical communications infrastructure. Stakeholders must monitor export control expansions and substrate qualification timelines as determinants of competitive positioning in defense-aerospace and telecommunications verticals.
Market Dynamics
Substrate thickness standardization toward thinner specifications is compressing material economics while simultaneously amplifying quality control burdens across crystal growth and epitaxial processing stages.
Growth Catalysts
- 5G Infrastructure Deployment:RF power amplifier demand from base station rollouts in China, Japan, and South Korea is pulling 6-inch semi-insulating substrate volumes. MIIT substrate quality mandates through updated GB standards enforce tighter specifications.
- Satellite Communications Expansion:Low-earth orbit terminal manufacturers are qualifying GaAs for phased array antennas. Defense procurement rules in the US prioritize allied-nation substrate sourcing for critical communications infrastructure.
- Vertical Gradient Freeze Advances:Crystal growth method improvements are reducing defect densities in large-diameter ingots. Liquid encapsulated Czochralski alternatives are expanding capacity for LED-grade material.
Market Restraints
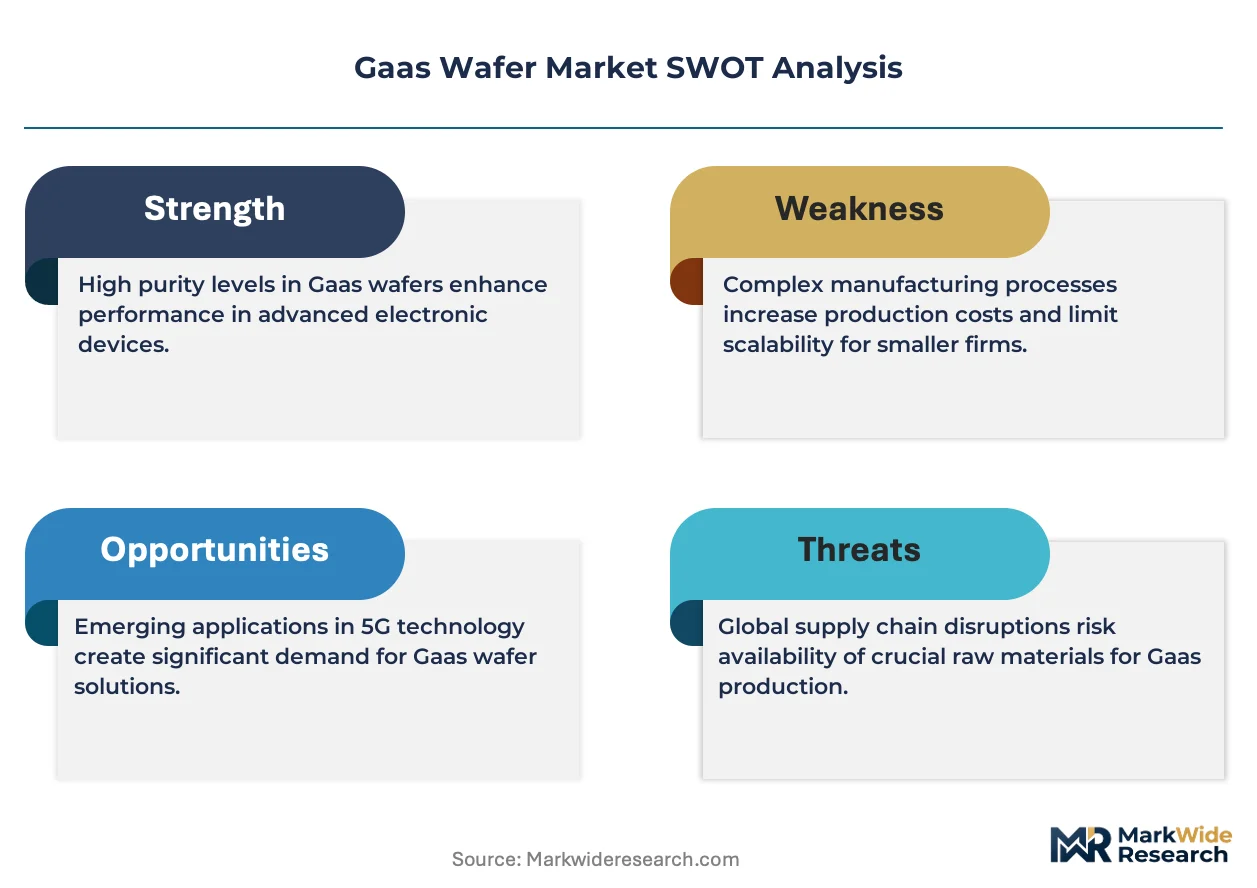
- Gallium Feedstock Concentration:Primary gallium refining capacity clusters in Chinese smelters, exposing non-Chinese wafer manufacturers to export control volatility and precursor chemical restrictions under REACH.
- Epitaxial Equipment Lead Times:Metal-organic chemical vapor deposition reactor availability from limited equipment vendors stretches qualification timelines for new substrate suppliers by 18-24 months.
- Silicon-Germanium Substitution:SiGe BiCMOS processes are capturing sub-6 GHz RF applications where GaAs once dominated, compressing addressable market in consumer wireless segments.
Strategic Opportunities
- India Compound Semiconductor Mission:PLI scheme incentives for domestic GaAs foundry construction are attracting substrate qualification programs from established crystal growers seeking tariff-advantaged supply positions.
- Automotive Radar Integration:77 GHz radar module adoption in advanced driver-assistance systems is opening new frequency bands where GaAs noise performance exceeds silicon alternatives.
- Photonics-Electronics Convergence:Silicon photonics packaging requirements are creating hybrid substrate demand combining GaAs optoelectronic layers with silicon interposers for data center transceivers.
Industry Challenges
- Crystal Growth Specialist Scarcity:Vertical gradient freeze furnace operation and seed crystal preparation require decade-long apprenticeship pipelines that semiconductor engineering programs have neglected.
- Defense-Aerospace Certification Cycles:Space-qualified wafer documentation under MIL-PRF-38534 requires 36-48 month traceability records that new market entrants cannot immediately satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaas Wafer Market |
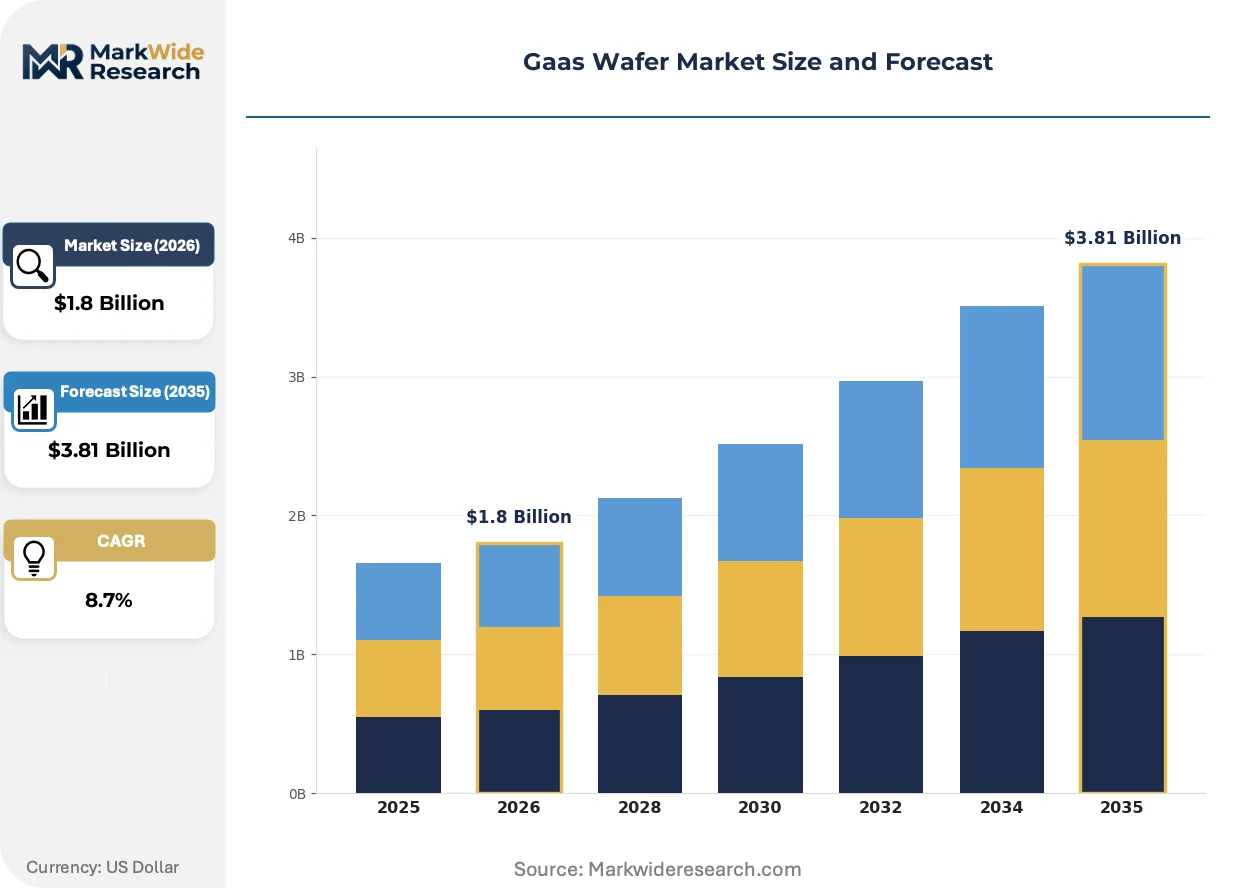
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wafer, Epitaxial Wafer, Substrate Wafer, Sapphire Wafer Thickness: Thin Film, Standard Thickness, Thick Film, Ultra-Thin Application: LEDs, Solar Cells, RF Devices, Laser Diodes End User: Telecommunications, Consumer Electronics, Automotive, Aerospace |
| Companies Covered | Sumitomo Electric Industries, Freiberger Compound Materials GmbH, AXT Inc, Xiamen Powerway Advanced Material, IQE plc, Wafer Technology, DOWA Electronics Materials, China Crystal Technologies, Yunnan Germanium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaas Wafer Market Emerging Trajectories
Wafer processing economics are being restructured by simultaneous pressures from device miniaturization, regulatory chemical restrictions, and buyer consolidation in telecommunications infrastructure.
Thin-wafer handling technology is collapsing the traditional thickness-cost relationship that favored thicker substrates for mechanical durability. 100-micron and 75-micron specifications are now standard for RF power amplifiers, enabling 40% more die per ingot but requiring temporary bonding and de-bonding process investments that smaller substrate vendors cannot finance. Equipment suppliers are consolidating around integrated grinding-polishing systems that automate thickness uniformity control.
REACH restrictions on arsenic precursor handling are forcing European wafer processors to adopt closed-loop effluent recovery systems. ECHA authorization requirements for gallium arsenide manufacturing waste streams are extending facility permitting timelines in Germany and France. Freiberger Compound Materials GmbH and other European suppliers are investing in precursor recycling partnerships to maintain production continuity under tightening hazardous substance frameworks.
Telecommunications equipment manufacturers are consolidating substrate procurement under direct long-term supply agreements with crystal growers, bypassing traditional distributor channels. Ericsson, Nokia, and Samsung network divisions now negotiate multi-year epitaxial wafer contracts specifying defect density thresholds and delivery flexibility terms. This disintermediation is compressing margins for substrate traders while rewarding vertically integrated manufacturers with captive crystal growth and epitaxial deposition capabilities.
Gaas Wafer Market Segmentation
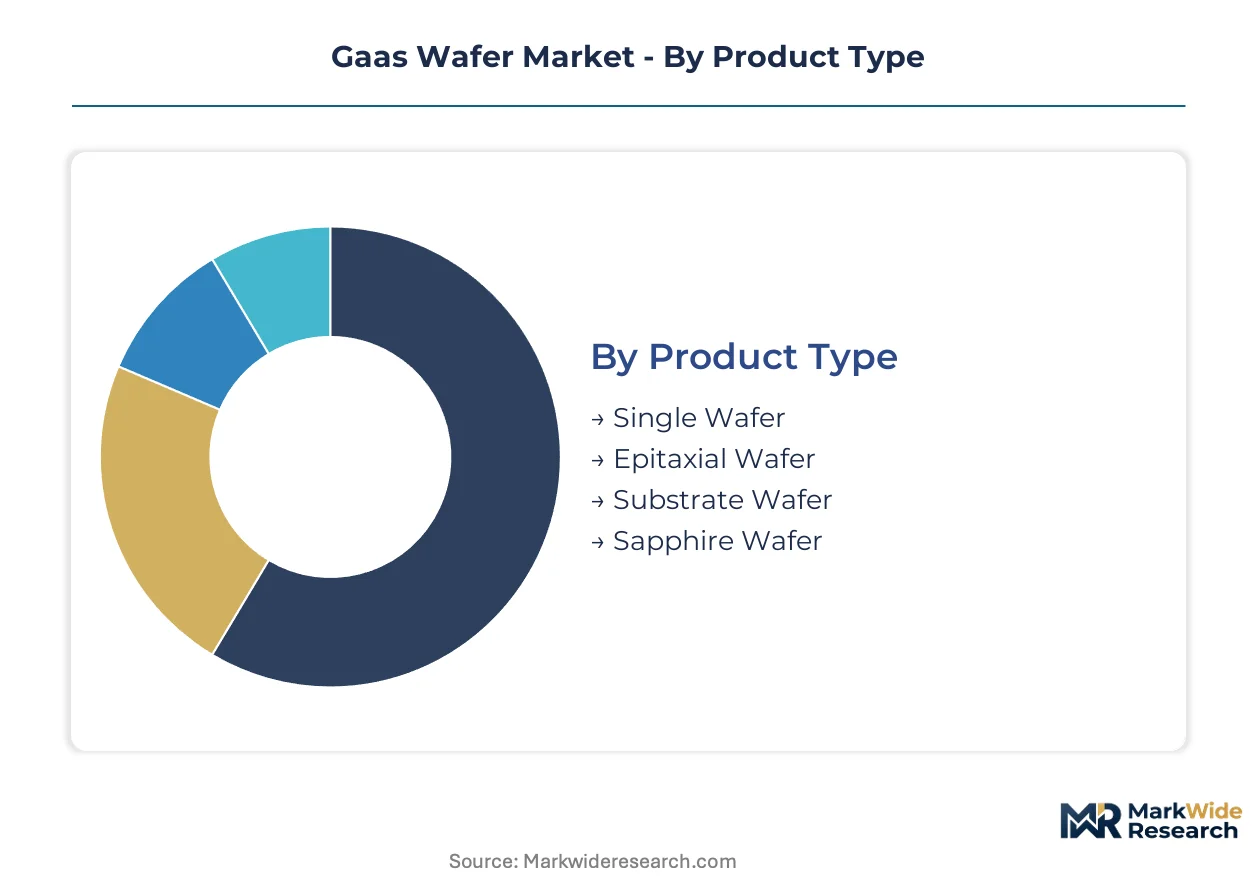
GaAs wafer segmentation reflects divergent technical requirements across RF power amplification, optoelectronic emission, and photovoltaic conversion. Substrate specifications vary dramatically by carrier concentration, crystal orientation, and surface preparation standards demanded by downstream device fabrication.
Product Type:
Mature crystal growth methods anchor substrate wafer supply while epitaxial deposition commands premium value through technical complexity barriers.
- Epitaxial Wafer:Lattice-matched layer deposition via metal-organic chemical vapor deposition creates the functional active layers for RF power amplifiers and laser diodes. RF device manufacturers in 5G telecommunications infrastructure specify these wafers for base station rollouts across China, Japan, and South Korea.
- Substrate Wafer:Single-crystal ingots grown through vertical gradient freeze or liquid encapsulated Czochralski methods provide the mechanical foundation for subsequent epitaxial processing. LED manufacturers absorb significant volumes of semi-insulating and doped substrates for solid-state lighting applications.
- Single Wafer:Discrete substrates without epitaxial layers serve research institutions and specialized device prototyping.
- Sapphire Wafer:Alternative substrate material for GaN-on-sapphire LED architectures competes for optoelectronic applications.
Substrate Wafer retains volume leadership; Epitaxial Wafer holds the steepest expansion curve.
Thickness:
Cost engineering through material reduction is compressing thickness specifications while amplifying handling complexity.
- Ultra-Thin:75-micron and 100-micron specifications now standard for RF power amplifiers enable 40% more die per ingot. Telecommunications equipment manufacturers driving 5G infrastructure procurement specify these thicknesses to reduce gallium consumption per device.
- Thin Film:Sub-150-micron wafers require temporary bonding and de-bonding process investments that smaller substrate vendors cannot finance. Automotive radar module suppliers at 77 GHz are qualifying thin-film specifications for advanced driver-assistance systems.
- Standard Thickness:Legacy 350-micron to 625-micron specifications persist in defense-aerospace applications requiring mechanical durability.
- Thick Film:Greater than 625-micron wafers serve specialized thermal management applications and research-scale crystal growth.
Standard Thickness maintains installed base dominance; Ultra-Thin is climbing the fastest as telecommunications procurement consolidates.
Application:
Frequency performance requirements and optical emission characteristics partition demand across distinct device categories.
- RF Devices:Power amplifiers and low-noise amplifiers for 5G base stations, satellite communications terminals, and radar systems exploit electron mobility six times silicon levels. China's MIIT substrate quality mandates through updated GB standards enforce tighter specifications for telecommunications infrastructure deployment.
- Laser Diodes:Edge-emitting and vertical-cavity surface-emitting lasers for optical communications and sensing applications demand precise wavelength control through aluminum gallium arsenide composition grading. Data center transceiver manufacturers are driving hybrid substrate demand combining GaAs optoelectronic layers with silicon interposers.
- LEDs:Solid-state lighting and display backlighting absorb significant volumes of doped substrates.
- Solar Cells:Multi-junction photovoltaic devices for space applications require specialized substrate orientations.
RF Devices command the dominant revenue share; Laser Diodes show the most rapid qualification activity for photonics-electronics convergence.
End User:
Procurement consolidation patterns and certification requirements differentiate customer segments sharply.
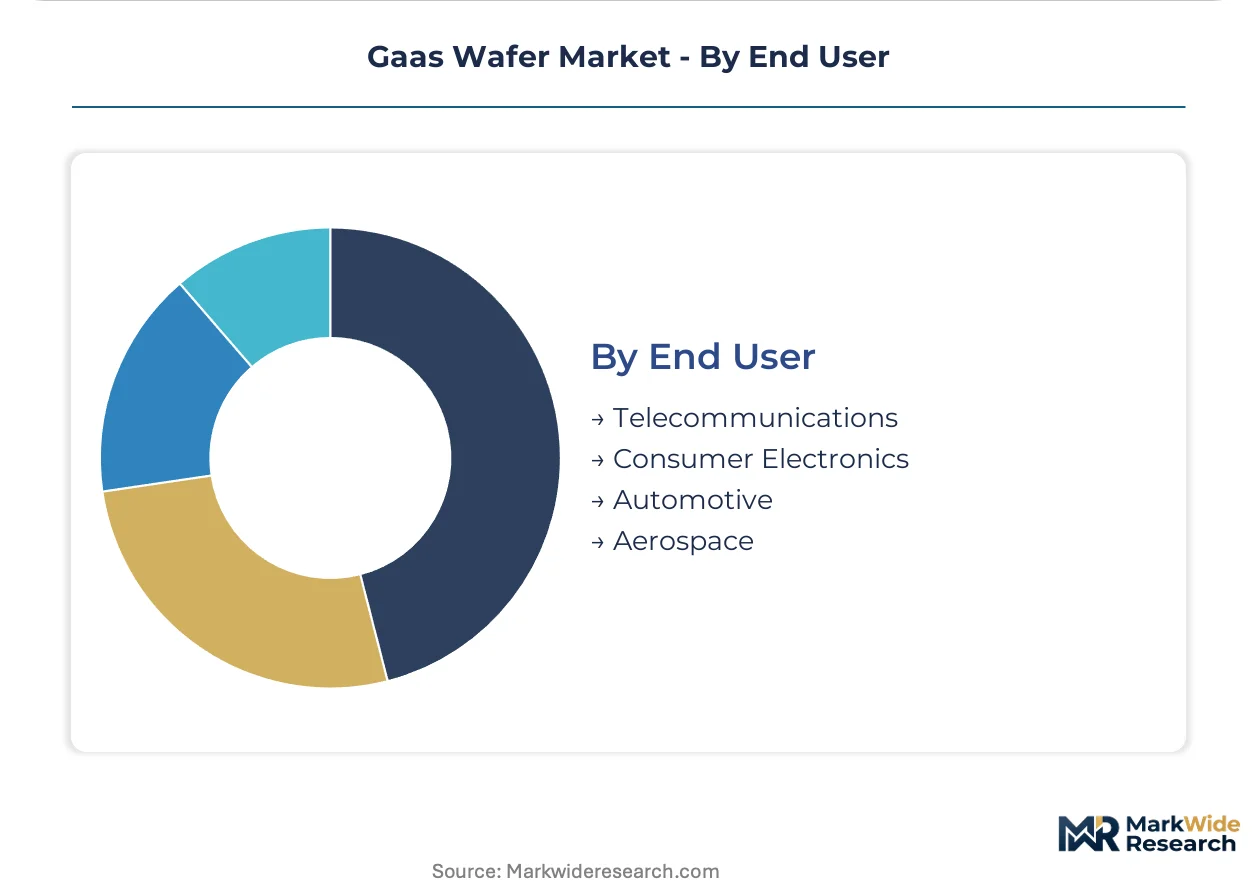
- Telecommunications:Ericsson, Nokia, and Samsung network divisions negotiate multi-year epitaxial wafer contracts specifying defect density thresholds and delivery flexibility terms. Direct long-term supply agreements with crystal growers are bypassing traditional distributor channels.
- Aerospace:Space-qualified wafer documentation under MIL-PRF-38534 requires 36-48 month traceability records that new market entrants cannot immediately satisfy. Defense procurement rules in the US prioritize allied-nation substrate sourcing for critical communications infrastructure.
- Consumer Electronics:High-volume laser diode and LED applications compete on cost-engineered substrates.
- Automotive:77 GHz radar module adoption in advanced driver-assistance systems is opening new frequency bands where GaAs noise performance exceeds silicon alternatives.
Telecommunications concentrates procurement volume; Automotive is gaining share fastest as radar integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystal growth capacity clusters heavily in East Asian manufacturing corridors, with substrate qualification programs and defense procurement rules reshaping competitive access across national boundaries.
China
MIIT substrate quality mandates through updated GB standards enforce tighter specifications for 5G telecommunications infrastructure deployment. SAMR coordinates revised standards for electronic-grade compound semiconductors. Yangtze River Delta foundries absorb significant semi-insulating substrate volumes for RF power amplifier production.
Japan
METI coordinates national semiconductor strategy including GaAs supply chain resilience initiatives. JIS standards govern crystal orientation specifications for optoelectronic device fabrication. Kanto and Kansai industrial corridors concentrate vertical gradient freeze furnace operations and epitaxial service providers.
South Korea
MFDS regulates precursor chemical handling in wafer processing facilities. Samsung network divisions negotiate multi-year epitaxial wafer contracts specifying defect density thresholds. Seoul Capital Area hosts RF device manufacturers pulling 6-inch substrate volumes for base station rollouts.
United States
FCC spectrum allocation rules and Department of Defense procurement prioritize allied-nation substrate sourcing for critical communications infrastructure. MIL-PRF-38534 documentation requirements extend space-qualified wafer certification timelines. Greater Boston and Pacific Northwest corridors concentrate defense-aerospace device prototyping activity.
Germany
ECHA REACH restrictions on arsenic precursor handling force closed-loop effluent recovery system adoption. Freiberger Compound Materials anchors European supply security for defense and space-qualified wafers. Bavaria and Saxony host crystal growth specialists serving satellite communications terminal manufacturers.
Gaas Wafer Market Vendor Landscape
Vertically integrated crystal growers and specialized epitaxial service providers split the market between captive supply security and technical differentiation. The vendor base concentrates around established furnace operators with decade-long apprenticeship pipelines in crystal growth. Three archetypes dominate: integrated manufacturers controlling ingot-to-epi value chains, substrate specialists competing on cost-engineered specifications, and foundry-linked service providers. Competitive moves center on capacity expansion in 6-inch and 8-inch formats and strategic partnerships with telecommunications equipment manufacturers.
Among Japanese and German integrated manufacturers, Sumitomo Electric Industries and Freiberger Compound Materials exemplify vertical control from crystal growth through epitaxial services. AXT Inc occupies a position within the cost-engineered substrate tier competing for LED and consumer laser applications. These three anchors represent divergent strategic postures: premium RF and photonics positioning, European defense-aerospace supply security, and high-volume cost optimization respectively.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Freiberger Compound Materials GmbH |
| AXT Inc |
| Xiamen Powerway Advanced Material |
| IQE plc |
| Wafer Technology |
| DOWA Electronics Materials |
| China Crystal Technologies |
| Yunnan Germanium |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion feeds directly into substrate landed costs, amplifying the pricing power of Japanese and German crystal growers while compressing margins for distributors serving RF device manufacturers in China. This logistics friction reinforces a three-tier pricing structure across premium, standard, and economy levels that stratifies by certification grade and captive epitaxial capability.
Pricing Analysis
MIIT substrate quality mandates dictate the pricing tier structure through defect density thresholds and traceability documentation requirements. Pricing stratifies across premium, standard, and economy tiers based on MIL-PRF-38534 certification status and volume commitment scale. Cost compression in LED-grade material is intensifying because liquid encapsulated Czochralski capacity expansion in China feeds oversupply into consumer laser segments. Telecommunications equipment manufacturers show least price sensitivity due to long-term supply security priorities, while LED backlighting procurement teams drive hardest bargain.
Supply Chain Analysis
Extended payment terms from telecommunications OEMs stretch working capital requirements for substrate specialists without captive crystal growth. Primary supply concentrates in Japan, China, and Germany, with gallium feedstock refining anchored in Chinese smelters. Raw material dependencies center on high-purity gallium metal, arsenic precursors, and pyrolytic boron nitride crucibles. Single-source vulnerability runs through metal-organic chemical vapor deposition reactor vendors. Distribution runs through direct long-term supply agreements with crystal growers, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through space qualification documentation creates switching costs that lock in incumbent positions.
For Market Incumbents: Entrench through backward integration into 8-inch vertical gradient freeze furnace operations and captive epitaxial service capacity. Accelerate certification investment for MIL-PRF-38534 space qualification to extend documentation lead over emerging Chinese crystal growers. Deepen channel control by negotiating multi-year direct supply agreements with Ericsson, Nokia, and Samsung network divisions before India's PLI scheme matures domestic foundry capacity.
For New Entrants and Emerging Players: Pursue qualification programs for automotive radar substrate specifications at 77 GHz, where GaAs noise performance exceeds silicon alternatives and incumbent certification burdens are lighter. Target India's Compound Semiconductor Mission PLI incentives for tariff-advantaged supply positioning. Establish go-to-market through foundry-linked epitaxial service partnerships rather than direct crystal growth investment.
For Investors and Strategic Acquirers: Crystal growth specialists with decade-long apprenticeship pipelines and established seed crystal preparation capabilities represent the most defensible acquisition archetype. Long-term viability rests on regulatory moat duration and defense procurement rule persistence favoring allied-nation sourcing. Monitor ECHA REACH authorization timelines for arsenic precursor handling as inflection indicator for European supply security premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in 6-inch and 8-inch Formats | Sumitomo Electric Industries and Freiberger Compound Materials scale furnace operations to capture RF power amplifier demand from 5G base station rollouts. |
| Backward Integration into Crystal Growth | IQE plc and DOWA Electronics Materials secure ingot supply through vertical control over seed crystal preparation and vertical gradient freeze furnace operations. |
| Long-term Supply Agreement with Telecommunications OEMs | Samsung network divisions negotiate multi-year epitaxial wafer contracts specifying defect density thresholds and delivery flexibility terms. |
| Joint Venture for Precursor Recycling Partnerships | Freiberger Compound Materials invests in closed-loop effluent recovery systems to maintain production continuity under tightening ECHA REACH frameworks. |
| Geographic Expansion through India's PLI Scheme | Established crystal growers establish qualification programs in India Compound Semiconductor Mission to secure tariff-advantaged supply positions. |
Methodological Framework
A standing panel of RF device procurement managers, crystal growth furnace operators, epitaxial service technical directors, and telecommunications infrastructure planners provided ongoing calibration across primary fieldwork. Secondary validation drew from MIIT GB standard filings, METI semiconductor strategy documents, ECHA REACH authorization records, and SEC 10-K disclosures from listed substrate manufacturers. Bottom-up wafer shipment estimates triangulated against top-down RF power amplifier production forecasts from telecommunications equipment OEMs.
Scenario-bracketing framed analytical framework across the analysis window, modeling volume and value outputs through product type, thickness specification, application segment, and end-use industry dimensions. CAGRs derived from regression against historical substrate shipment patterns and telecommunications capex cycles. Forecast inputs incorporated metal-organic chemical vapor deposition reactor delivery schedules and gallium metal price volatility indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed 6-inch and 8-inch foundries would shift outcomes through accelerated price competition in LED-grade material. Macroeconomic contraction in telecommunications infrastructure deployment, regulatory restriction tightening on arsenic precursor handling, or breakthrough silicon-germanium performance at millimeter-wave frequencies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Smartphone Battery Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
China Semiconductor Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
North America Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Semiconductor IP Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Discrete Semiconductor Market