
 Global Semiconductor Silicon Intellectual Property Market | 2026-2036
Global Semiconductor Silicon Intellectual Property Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Silicon Intellectual Property Market Intelligence
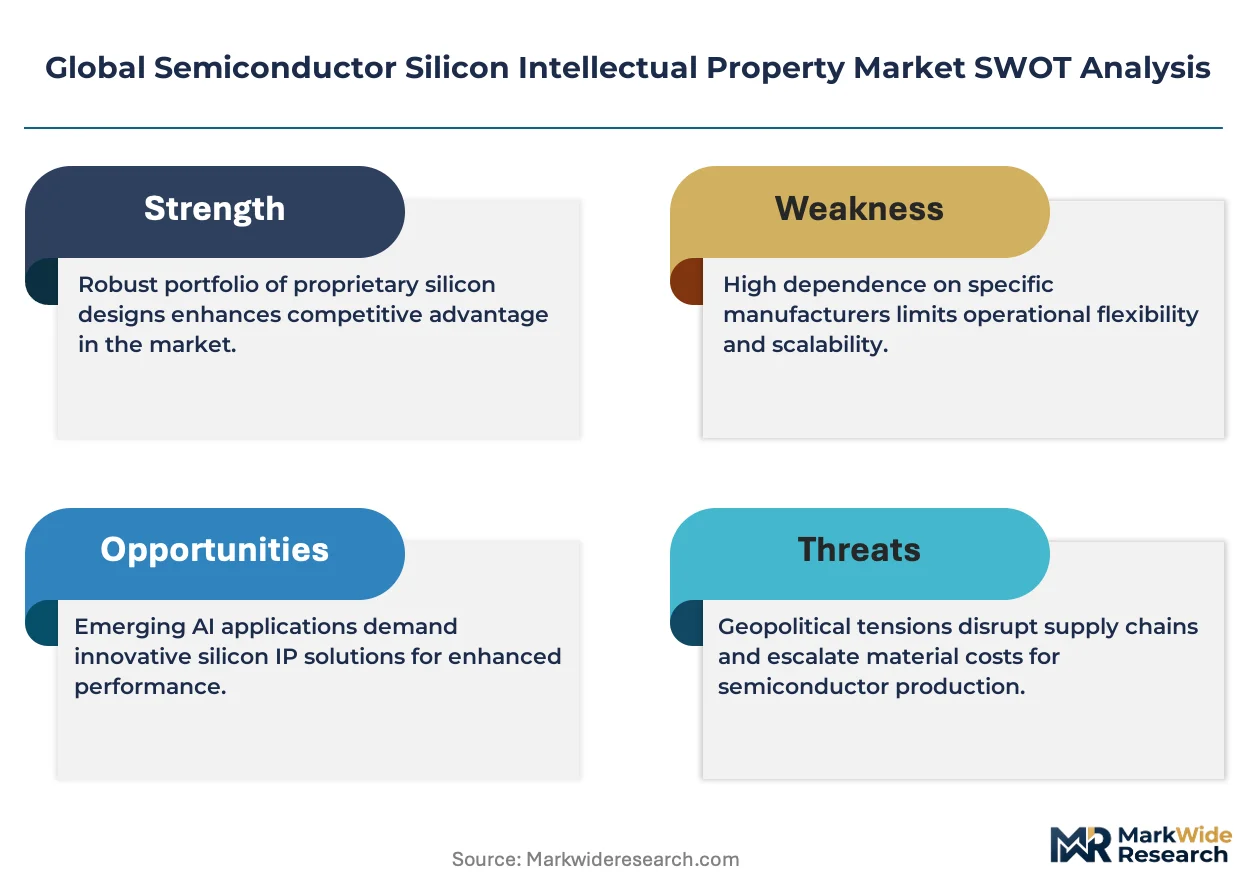
Modular IP bundling is decoupling processor cores from mandatory interface IP packages, letting fabless buyers license functional blocks à la carte. ARM Holdings leverages its instruction-set architecture dominance to sustain recurring royalty streams across mobile and automotive SoCs. Synopsys anchors the electronic design automation layer with integrated IP verification tools that reduce tape-out risk. SiFive competes in the open-standard RISC-V ecosystem, offering customizable core configurations that challenge incumbent proprietary architectures.
Semiconductor silicon intellectual property comprises pre-verified, reusable design blocks—logic gates, memory compilers, physical layout cells, and analog macros—delivered as synthesizable RTL or hard macros for integration at 7nm, 5nm, and emerging 3nm process nodes. These blocks eliminate redundant design cycles, compressing time-to-market for complex system-on-chip devices by 30-50% compared to full-custom development. Processor cores and interface IP command the deepest margin pools due to their ubiquity across computing platforms, while security IP represents the fastest-expanding category as hardware-rooted trust becomes mandatory for connected devices and payment systems. Memory IP maintains steady demand from data-center and networking hardware segments where high-bandwidth interfaces dominate bill-of-materials.
FDA oversight of medical device chips, FCC certification requirements for wireless-integrated SoCs, and EU AI Act hardware transparency mandates collectively tighten compliance burdens for IP vendors serving regulated end markets. REACH and RoHS substance restrictions further constrain material choices in analog and mixed-signal IP fabrication. Stakeholders must monitor how fragmented export-control regimes between the United States, China, and the European Union reroute licensing flows and foundry partnerships.
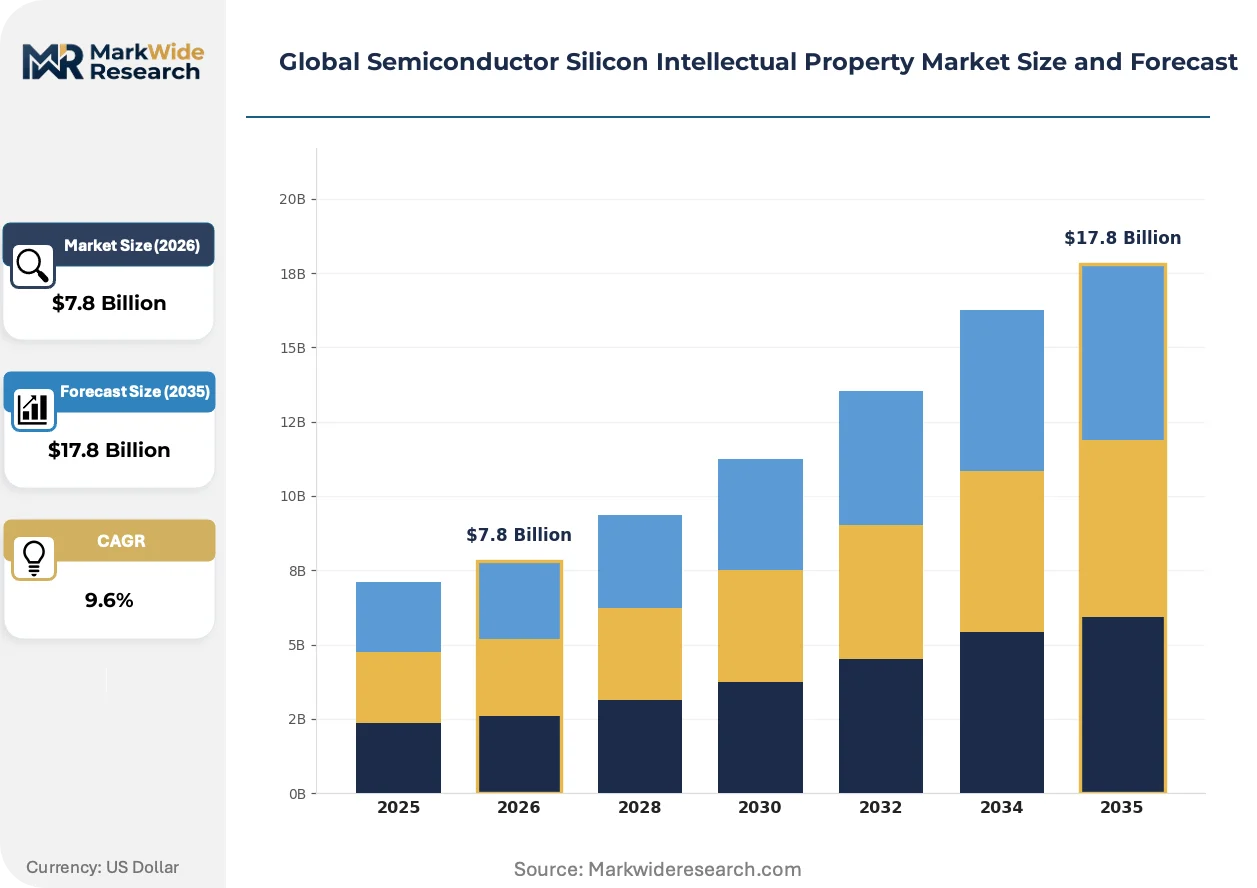
Market Dynamics
Modular licensing architectures are fragmenting the traditional bundled-IP model, forcing incumbents to unbundle processor cores from interface packages while open-standard ecosystems erode proprietary instruction-set dominance.
Growth Catalysts
- ADAS platform proliferation:Automotive SoC designers are licensing high-performance processor cores and safety-certified interface IP for autonomous driving stacks, with demand concentrating in Germany, Japan, and the United States where OEMs are vertically integrating silicon design.
- EU Chips Act implementation:Subsidy frameworks and local-content mandates are redirecting foundry partnerships toward European Union member states, creating captive demand for EU-developed security and analog IP blocks.
- RISC-V ecosystem maturation:Open-standard instruction-set architectures are displacing proprietary cores in edge AI and industrial control applications, lowering barriers to entry for fabless entrants in Taiwan and South Korea.
Market Restraints
- Export control fragmentation:Divergent technology transfer rules between the United States Bureau of Industry and Security and China's Ministry of Commerce are bifurcating licensing flows, forcing IP vendors to maintain duplicate compliance architectures.
- Advanced node concentration:Taiwan Semiconductor Manufacturing Company and Samsung Foundry control 90%+ of 3nm-5nm capacity, creating single-source risk for hard-macro IP validation and physical design kits.
- Verification cost escalation:Pre-silicon validation for automotive-grade IP now consumes 40-50% of development budgets, squeezing margin pools for mid-tier vendors without EDA-integrated toolchains.
Strategic Opportunities
- India semiconductor manufacturing incentives:The country's Production Linked Incentive scheme for fabs and ATMP facilities is creating greenfield demand for physical IP, memory compilers, and analog macros from domestic and foreign licensors.
- Hardware-rooted security mandates:Payment Card Industry PIN Transaction Security requirements and EU Cybersecurity Act certification frameworks are accelerating demand for secure enclave IP, true random number generators, and cryptographic accelerators.
- Chiplets and die-to-die interconnects:Universal Chiplet Interconnect Express standardization is converging with 2.5D/3D packaging advances, opening white space for specialized PHY IP and interposer routing solutions.
Industry Challenges
- Physical design talent scarcity:Deep-submicron layout expertise for 3nm finFET and gate-all-around processes is concentrated among senior engineers at Synopsys, Cadence, and a handful of foundry-affiliated teams, constraining vendor scaling.
- Multi-jurisdictional certification timelines:Simultaneous FDA 510(k) clearance for medical device SoCs, FCC Part 15 certification for wireless-integrated designs, and EU MDR conformity assessment is extending time-to-revenue by 12-18 months.
- Legacy node obsolescence management:Industrial and automotive customers require 10-15 year supply guarantees for 28nm and larger nodes, forcing IP vendors to maintain duplicate physical design kits across deprecated and active process generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Silicon Intellectual Property Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Processor Cores, Interface IP, Memory IP, Analog & Mixed-Signal IP, Security IP Technology: System on Chip, Embedded Technology, Digital Signal Processing, Low Power Design, IP Reuse Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Industrial Automation, Networking Hardware End User: Fabless Companies, Foundries, IDMs, Original Design Manufacturers, Electronic Manufacturing Services |
| Companies Covered | Imagination Technologies, eMemory Technology, ARM Holdings, SiFive, Rambus, Synopsys, Faraday Technology Corporation, Fujitsu, Cadence Design Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Silicon Intellectual Property Market Strategic Shifts & Innovations
Three convergent forces are restructuring how semiconductor IP is developed, licensed, and integrated: open-standard hardware architectures are commoditizing processor cores; regulatory mandates are embedding compliance into silicon design; and procurement models are unbundling long-term support from upfront licensing.
Chiplets are expanding into high-performance computing and AI training accelerators as AMD, Intel, and emerging Chinese designers adopt disaggregated die strategies to improve yield and mix-and-match process nodes. Hyperscalers are now specifying chiplet-based custom silicon in their procurement RFPs, compressing the market for monolithic SoC IP portfolios and forcing vendors to rearchitect offerings around die-to-die interconnect and packaging-aware design kits.
REACH substance restrictions and RoHS hazardous material limits are constraining material choices in analog and mixed-signal IP fabrication, particularly for high-voltage drivers and power management units. The European Chemicals Agency's candidate list expansion is forcing IP vendors to redesign legacy macros or qualify alternative metallization schemes, with automotive and industrial segments absorbing the bulk of requalification costs through extended certification cycles.
Subscription-based IP access models are displacing perpetual licenses in the mid-market fabless segment, with vendors like Arm and SiFive offering royalty-offset SaaS tiers for startups and university spinouts. This shift is most visible in Israel and the United Kingdom, where venture-backed chip designers prioritize cash-flow flexibility over long-term cost optimization, and where cloud-based EDA integration enables just-in-time IP procurement without on-premise tool investments.
Global Semiconductor Silicon Intellectual Property Market Segmentation
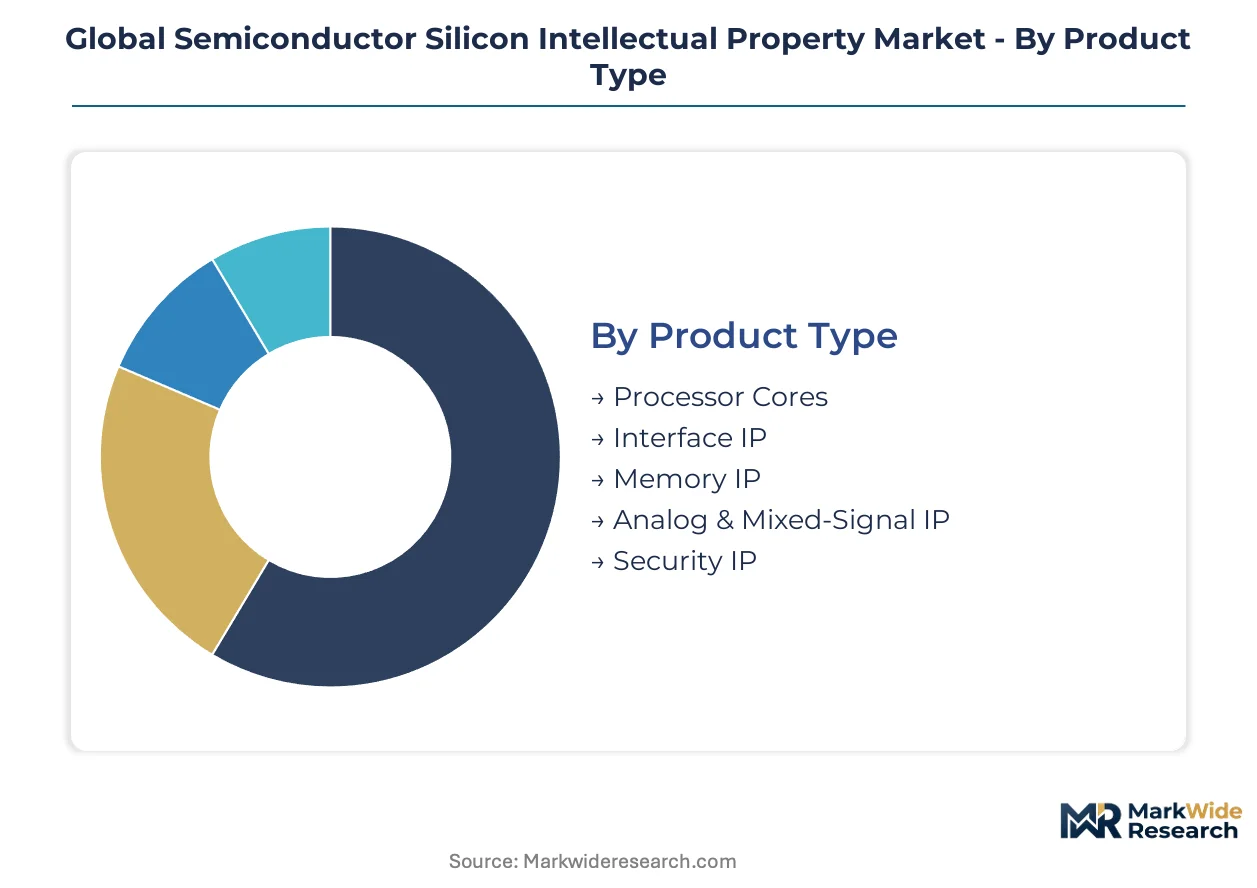
Semiconductor IP segmentation reflects how design blocks embed into finished silicon—some function as standalone licensable units, others integrate tightly into complete subsystem stacks. Understanding these integration patterns clarifies where margin pools concentrate and which vendor capabilities command premium positioning.
Product Type:
Processor cores and interface IP dominate standalone licensing flows, while security and analog blocks increasingly ship as embedded subsystems within broader platform bundles.
- Processor Cores:Central processing units and application processors delivered as synthesizable RTL or optimized hard macros for 5nm and 3nm nodes. Automotive SoC designers in Germany and the United States license ARM and RISC-V cores for ADAS compute stacks, with safety certification requirements extending development cycles.
- Interface IP:High-speed SerDes, PCIe, and memory controllers connecting dies to external systems. Data-center networking hardware in Taiwan and South Korea drives demand for 112G/224G PHY solutions as hyperscalers scale AI training clusters.
- Memory IP:SRAM compilers, register files, and high-bandwidth memory controllers integrated into SoC subsystems. Fabless designers license these for AI accelerators and edge computing devices.
- Analog & Mixed-Signal IP:Data converters, PLLs, and power management units bridging digital logic with physical sensors. Industrial automation systems require extended temperature-range variants.
- Security IP:Hardware roots of trust, cryptographic accelerators, and secure enclaves embedded into payment and connected devices. EU Cybersecurity Act certification is accelerating procurement in European banking terminals.
Processor cores lead volumes today; security IP is gaining share fastest.
Technology:
Technology segments stratify by design abstraction level—higher integration approaches command premium pricing, while reuse methodologies compress unit economics for volume applications.
- System on Chip:Complete die-level integration of processors, memory, and I/O on single silicon. Consumer electronics OEMs in South Korea and Taiwan license SoC platforms for smartphone and tablet applications, with time-to-market pressures favoring pre-verified subsystems.
- Embedded Technology:Microcontroller cores and real-time operating system integration for constrained devices. Industrial automation controllers in Germany and Japan specify embedded IP for deterministic response requirements.
- Digital Signal Processing:Specialized arithmetic units for audio, video, and sensor data processing. Telecommunications equipment vendors license these for baseband modems.
- Low Power Design:Clock gating, power gating, and voltage island techniques extending battery life. Wearable device manufacturers prioritize these methodologies.
- IP Reuse:Standardized design blocks ported across process nodes to amortize verification costs. Foundries promote reuse libraries to accelerate customer tape-outs.
SoC integration commands the highest royalty rates; embedded technology shows the steepest expansion trajectory in automotive and industrial endpoints.
Application:
Application segments distribute across consumer volume markets and regulated industrial systems, with certification burdens creating divergent vendor margin structures.
- Consumer Electronics:Smartphones, tablets, wearables, and home entertainment systems requiring annual design refreshes. Fabless companies in Taiwan and China dominate procurement, with seasonal volume spikes compressing pricing cycles.
- Telecommunications Equipment:Base stations, optical transport, and satellite communication systems demanding 99.999% reliability. Ericsson and Nokia suppliers in Sweden and Finland specify extended-temperature IP variants.
- Aerospace Systems:Rad-hard and fault-tolerant designs for satellites and avionics. FAA certification requirements and ESA qualification standards extend development timelines.
- Industrial Automation:Programmable logic controllers, motor drives, and robotic systems. German and Japanese machinery OEMs source safety-certified IP blocks.
- Networking Hardware:Routers, switches, and data-center interconnects scaling to 800G and beyond. Hyperscalers in the United States specify custom silicon with proprietary extensions.
Consumer electronics generates the highest unit volumes; aerospace systems deliver the strongest pricing premiums despite constrained shipment scale.
End User:
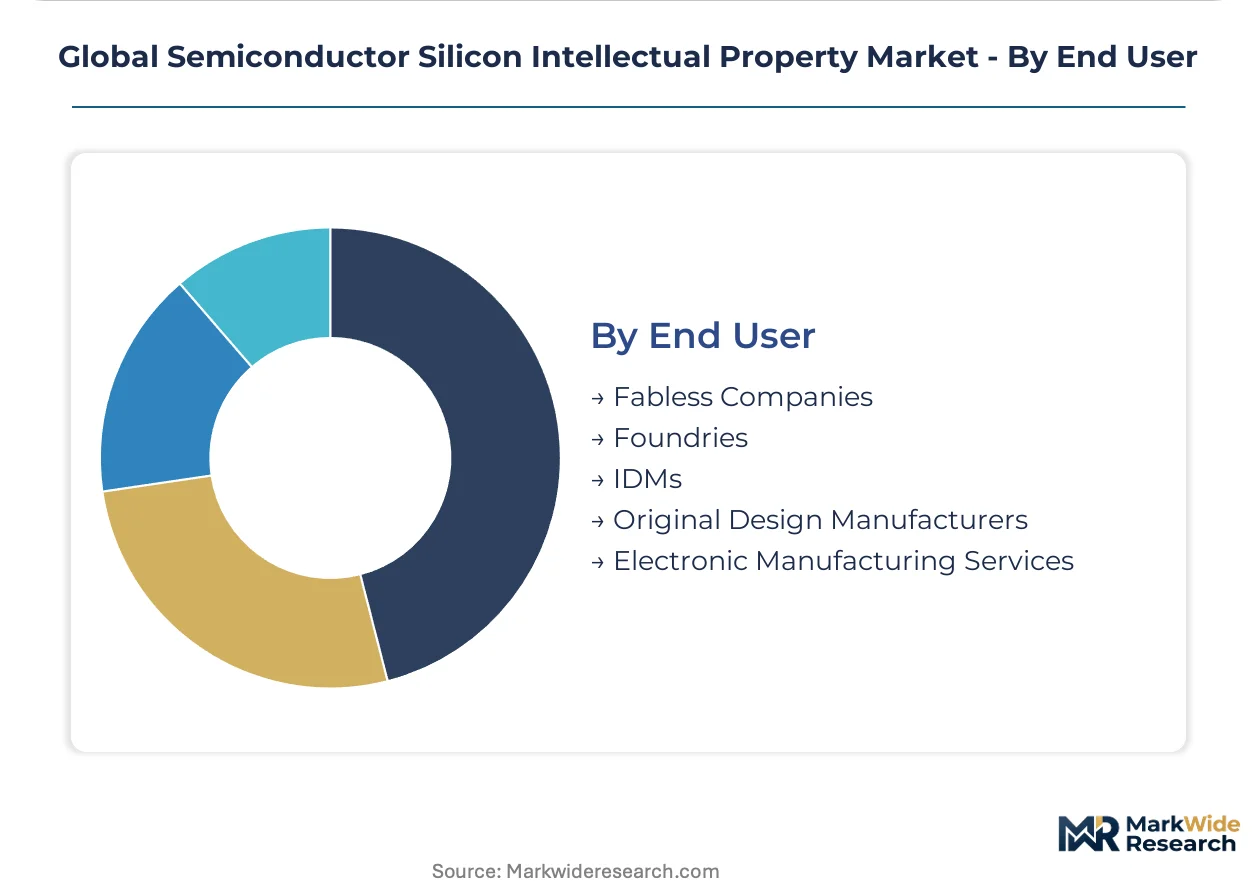
End-user categories reflect vertical integration depth—pure-play fabless designers outsource entirely, while IDMs and foundries maintain captive IP development capabilities.
- Fabless Companies:Design-only semiconductor firms licensing complete IP portfolios for outsourced manufacturing. Qualcomm, NVIDIA, and AMD suppliers concentrate procurement decisions in California and Taiwan.
- Foundries:TSMC, Samsung Foundry, and GlobalFoundries developing process-specific design kits and foundation IP for customer use. These entities license third-party cores while promoting in-house physical IP libraries.
- IDMs:Intel and Texas Instruments maintaining captive design teams with selective external licensing for specialized functions. Memory and analog specialists source digital controller IP externally.
- Original Design Manufacturers:Foxconn and Quanta designing reference platforms for brand-label customers. These firms license interface and power management IP for tablet and notebook subsystems.
- Electronic Manufacturing Services:Jabil and Flex providing assembly and test services with limited IP involvement, occasionally licensing basic connectivity blocks for module-level integration.
Fabless companies drive the broadest licensing diversity; foundries are consolidating influence through captive physical IP development and preferred vendor programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon IP licensing originated in the United States and United Kingdom during the 1990s, when ARM Holdings and early EDA vendors pioneered reusable design block commercialization. Foundry scaling in Taiwan and South Korea subsequently concentrated advanced-node validation demand in East Asia.
United States
Fabless designers in California and Texas license processor cores for AI accelerators and data-center networking hardware. The Bureau of Industry and Security administers export controls that bifurcate technology transfer rules for advanced node IP. Austin and Silicon Valley host the densest concentrations of automotive SoC design teams integrating safety-certified interface blocks.
Taiwan
TSMC's foundry dominance drives captive demand for physical design kits and hard-macro IP validation at 3nm and 5nm nodes. The National Science and Technology Council coordinates semiconductor R&D subsidies under the Chip Implementation Center program. Hsinchu Science Park anchors the world's densest cluster of IP-fab-design integration teams.
South Korea
Samsung Foundry and domestic fabless firms license memory controllers and high-bandwidth interface PHY for AI training clusters. The Ministry of Trade, Industry and Energy allocates K-Chips Act funding toward local IP ecosystem development. Seoul and Yongin concentrate RISC-V customization teams serving industrial automation markets.
Germany
Automotive OEMs in Munich and Stuttgart source safety-certified processor cores and interface IP for ADAS compute platforms. The Kraftfahrt-Bundesamt enforces ISO 26262 functional safety mandates for silicon components in autonomous systems. Dresden's Silicon Saxony cluster hosts foundry-adjacent IP validation labs serving European chip designers.
China
Domestic fabless designers license interface and security IP for server and telecommunications equipment under import substitution programs. The Ministry of Commerce implements technology transfer regulations that diverge from U.S. export control frameworks. Shanghai and Beijing host the largest concentrations of RISC-V core customization teams.
Global Semiconductor Silicon Intellectual Property Market Key Industry Players
Premium-margin players sit above commodity-margin players across architecture licensing and EDA integration depth. The market structures around instruction-set architecture dominance, electronic design automation bundling, and foundry-adjacent physical IP validation. Three archetypes prevail: proprietary ISA licensors with recurring royalty streams, EDA-integrated IP verification platforms, and open-standard core customization specialists. Competitive moves concentrate on unbundling traditional processor-interface packages and securing automotive safety certification partnerships.
Within the proprietary architecture tier, ARM Holdings exemplifies the royalty-recurring model across mobile and automotive SoCs. Synopsys anchors the EDA-integrated verification segment with pre-silicon validation toolchains that reduce tape-out risk. SiFive occupies the open-standard customization vector, offering configurable RISC-V cores that challenge incumbent lock-in. Cadence Design Systems and Imagination Technologies represent alternative positioning across synthesis tools and graphics-focused IP licensing respectively.
| Leading Market Players |
|---|
| Imagination Technologies |
| eMemory Technology |
| ARM Holdings |
| SiFive |
| Rambus |
| Synopsys |
| Faraday Technology Corporation |
| Fujitsu |
| Cadence Design Systems |
| Others |
Cost & Logistics Intelligence
Pre-silicon verification labor costs cascade through licensing tiers as ARM Holdings and Synopsys translate specialized engineering scarcity into differentiated royalty structures for automotive-grade IP blocks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates safety-certified automotive cores from general-purpose mobile processors from basic connectivity blocks. Price differentiation rests on ISO 26262 certification grade and customization depth for specific foundry nodes. Cost compression in mid-tier interface IP is intensifying because RISC-V open-standard alternatives erode proprietary architecture premiums. Fabless startups and university spinouts exhibit highest price sensitivity, while automotive OEMs absorbing extended certification cycles show lowest.
Supply Chain Analysis
Domestic-content mandates embedded in the EU Chips Act and India's PLI scheme are reshaping sourcing patterns for physical design kits and hard-macro validation services. Supply concentrates in Taiwan, South Korea, and the United States for advanced-node IP development. Raw material dependencies span silicon wafers, specialized EDA software licenses, and photomask fabrication capacity. Single-source vulnerability runs through TSMC's 3nm-5nm foundry monopoly for hard-macro validation. Distribution runs through direct enterprise licensing agreements with foundry-fabless design partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive functional-safety certification and hardware-rooted security specifications command sustainable premiums over commoditized mobile processor cores.
For Market Incumbents: Cement royalty-recurring streams by locking automotive OEMs into long-term safety-certified core agreements before RISC-V maturation accelerates. Deepen backward integration into EDA toolchains to capture verification spend that now consumes half of development budgets. Defend against open-standard displacement by embedding proprietary extensions into cloud-native design platforms.
For New Entrants and Emerging Players: Capture white space in secure enclave IP for EU Cybersecurity Act compliance and die-to-die interconnect PHY for chiplet-based AI accelerators. India's PLI-driven fab buildout represents the most penetrable geography for greenfield physical IP licensing. Lead with royalty-offset SaaS tiers targeting venture-backed Israeli and UK chip designers prioritizing cash-flow flexibility.
For Investors and Strategic Acquirers: Consolidation pressure builds where verification cost escalation squeezes mid-tier vendors lacking EDA-integrated toolchains. Long-term viability favors IP vendors with captive foundry relationships and automotive safety certification partnerships. Target acquisition profiles center on specialized security IP developers and chiplet interconnect specialists. Monitor RISC-V ecosystem maturation in industrial automation as the signal for open-standard inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Safety Certification Partnership | ISO 26262 qualification opens ADAS procurement channels at BMW, Volkswagen, and Ford. |
| Chiplet Interconnect IP Development | UCIe standardization enables AMD and Intel disaggregated die strategies for AI training. |
| Cloud-Native EDA Integration | SaaS delivery models reduce startup procurement friction and accelerate time-to-tape-out. |
| RISC-V Customization Platform Launch | Open-standard core configurations challenge ARM royalty structures in edge AI endpoints. |
| Hardware Security IP Acquisition | EU Cybersecurity Act mandates drive banking terminal and payment device demand. |
Research Approach
Direct dialogue with semiconductor IP licensing executives, automotive SoC design leads, foundry physical design kit managers, and EDA platform engineers grounded this analysis in operational reality. Secondary validation drew from SEC filings of fabless semiconductor firms, TSMC technology symposium disclosures, EU Chips Act implementation documents, and RISC-V International membership directories. Bottom-up segment sizing triangulated against top-down foundry capacity and royalty revenue estimates.
Output projections across processor core, interface, memory, analog, and security IP categories reflect segment-specific adoption curves and foundry node migration patterns. CAGRs derive from regression analysis of historical licensing volumes against semiconductor capital expenditure cycles and automotive electronics content growth. Key inputs include ADAS platform deployment timelines, chiplet standardization progress, and export control regime divergence between US BIS and China's Ministry of Commerce.
Export control escalation, foundry node transition delays, and open-standard ecosystem acceleration beyond baseline assumptions are the dominant revision risks. Forecasts embed assumptions about sustained automotive electronics demand and stable Taiwan Strait logistics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Compound Semiconductor Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Resistive RAM Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Gaas Wafer Market
Semiconductors
Semiconductor Target Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market