
 North America Semiconductor Market | 2026-2036
North America Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Semiconductor Market Insights
Software-defined silicon licensing is broadening what semiconductor vendors monetize beyond physical die sales. NVIDIA Corporation leverages its CUDA ecosystem to sustain recurring revenue from AI acceleration workloads. Intel Corporation anchors its foundry strategy on advanced packaging services for external fabless customers. Broadcom Inc. competes through custom AI chip co-development agreements with hyperscalers.
North America semiconductors encompass integrated circuits fabricated on silicon wafers using photolithography processes at nodes ranging from legacy 28nm to leading-edge 2nm, serving functions from computation and memory storage to signal conditioning and power conversion. Analog ICs and mixed-signal devices command durable margin pools in automotive and industrial applications where precision and reliability requirements resist commoditization. Memory chips face cyclical pricing pressure though AI training workloads are expanding high-bandwidth DRAM demand. Microprocessors dominate value capture in data center and client computing segments.
The CHIPS and Science Act directs Department of Commerce funding toward domestic wafer fabrication, reshaping capital allocation across the supply chain. EPA emissions standards and OSHA workplace chemical exposure limits govern fab construction and operation in the United States. Industry Canada and PMRA coordinate cross-border environmental review for facilities near the Great Lakes watershed. Stakeholders must monitor how export control classifications evolve for advanced AI accelerators and memory technologies.
Market Dynamics
AI training clusters are compressing semiconductor procurement cycles from annual to quarterly rhythms, forcing foundries and fabless designers into co-development partnerships that reshape traditional supplier-buyer boundaries.
Growth Catalysts
- CHIPS Act fab subsidies:Department of Commerce funding accelerates domestic wafer fabrication construction in Arizona and Texas, pulling equipment and materials procurement forward.
- Hyperscale AI buildouts:Cloud providers are expanding high-bandwidth memory and accelerator orders for generative inference and training workloads.
- Advanced packaging services:3D stacking and chiplet integration enable performance gains without sole reliance on leading-edge lithography nodes.
Market Restraints
- Extreme ultraviolet lithography concentration:ASML's monopoly on EUV scanners creates single-source vulnerability for sub-7nm production.
- Fluorinated gas emissions controls:EPA regulations on perfluorinated compounds raise compliance costs for etching and chamber cleaning operations.
- Neon and palladium supply chokepoints:Ukrainian neon purification and Russian palladium refining concentrate input risk for mature-node manufacturing.
Strategic Opportunities
- Mexico nearshoring corridors:Baja California and Chihuahua offer assembly and test capacity with preferential USMCA tariff treatment.
- Automotive silicon carbide:Electric vehicle traction inverters are expanding demand for wide-bandgap power semiconductors in Detroit and Tennessee supplier networks.
- Defense trusted foundry expansion:Department of Defense DMEA accreditation programs create captive demand for radiation-hardened and secure microelectronics.
Industry Challenges
- Process engineer scarcity:Leading-edge fab operations require PhD-level expertise in plasma physics and materials science that outpaces university pipeline output.
- Legacy node equipment obsolescence:200mm wafer tool refurbishment delays are extending lead times for automotive and industrial microcontroller production.
- Export classification complexity:Bureau of Industry and Security Entity List restrictions create compliance overhead for AI accelerator shipments to data center operators with foreign ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Semiconductor Market |
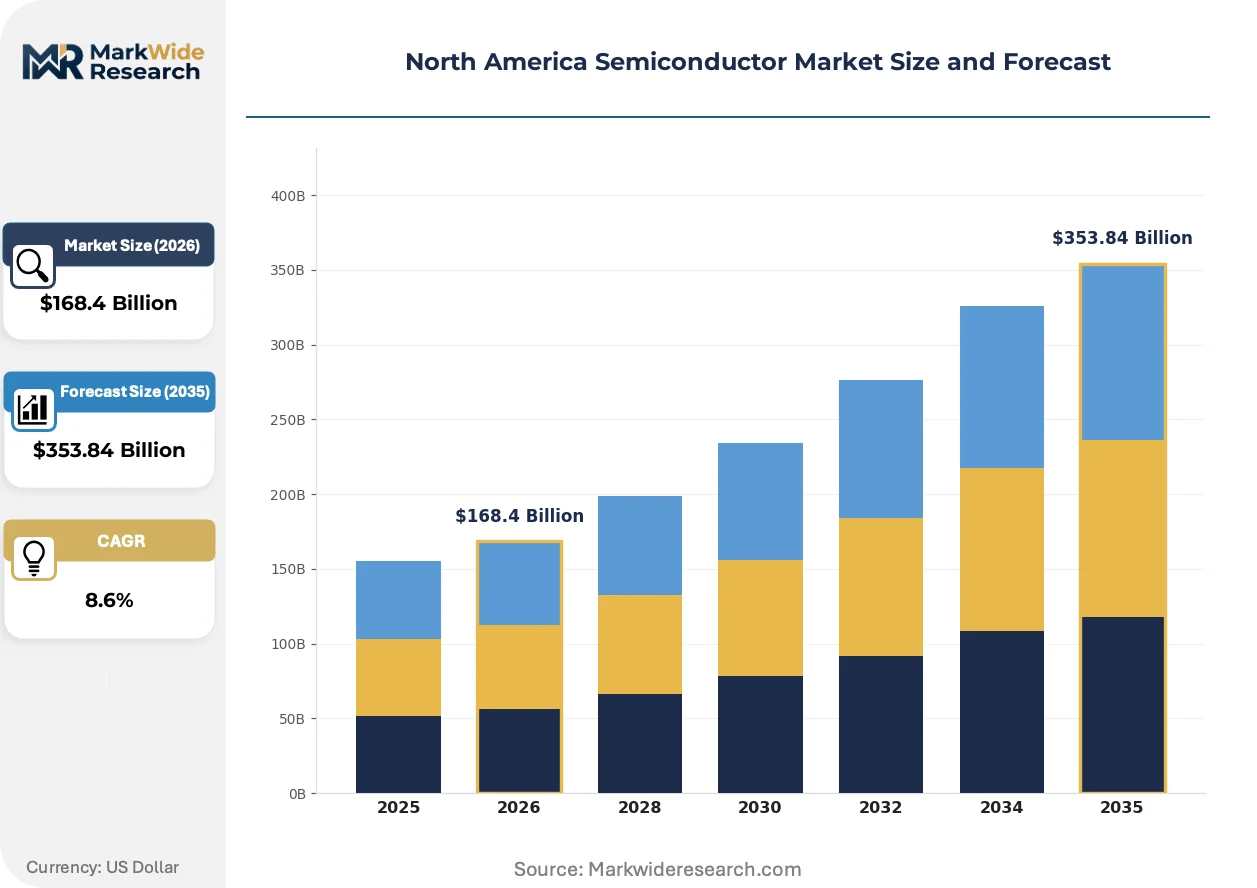
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $353.84 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Microcontrollers, Memory Chips, Analog ICs Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Automation Technology: Digital, Analog, Mixed-Signal, Power Management End User: Telecom Operators, OEMs, Tier-1 Suppliers, Aftermarket Providers |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Broadcom Inc., QUALCOMM Incorporated, Texas Instruments, Analog Devices, GlobalFoundries, NXP Semiconductors, II-VI Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Semiconductor Market Trends and Innovations
Chiplet-based disaggregation is fragmenting monolithic die architectures into modular subsystems, enabling mixed-node integration and decoupling memory from logic scaling constraints.
Gate-all-around transistors are overtaking finFET structures as the dominant CMOS architecture for sub-3nm nodes. Samsung Foundry and TSMC Arizona are qualifying nanosheet geometries for 2025 production ramps. This transition is overtaking planar density limitations while introducing new variability challenges in threshold voltage control.
OSHA's updated permissible exposure limits for semiconductor process chemicals are tightening fab workplace safety protocols. The revised standards affect photoresist handling and chemical mechanical planarization slurry management. Arizona and Texas facilities are retrofitting ventilation and monitoring systems to maintain operating licenses.
Hyperscalers are internalizing custom silicon design teams, bypassing traditional merchant semiconductor vendors for AI accelerators. Google, Amazon, and Microsoft now specify their own tensor processing unit architectures. This pattern concentrates most visibly in Seattle and Silicon Valley engineering centers where cloud hardware divisions have scaled past thousand-engineer thresholds.
North America Semiconductor Market Segmentation
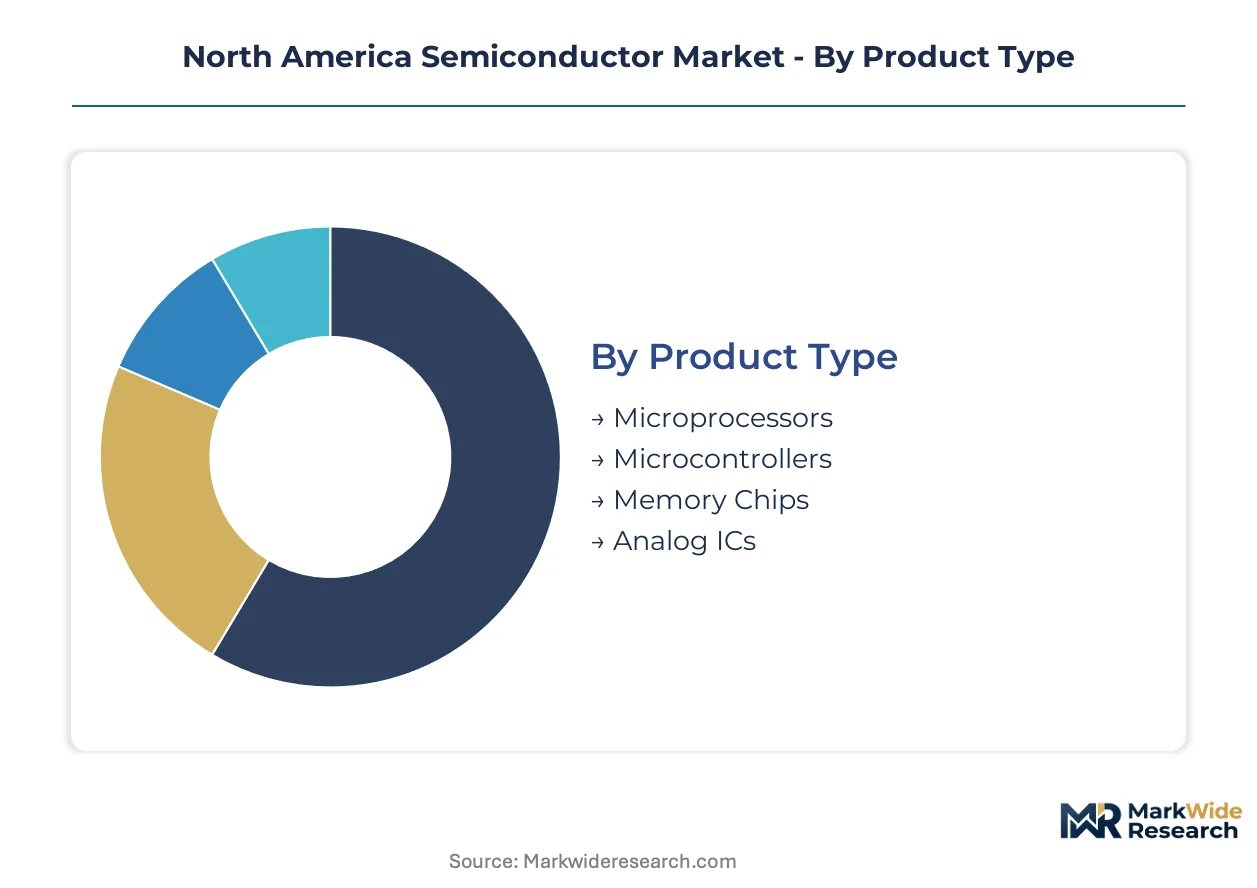
Semiconductor demand fragments across functional categories with divergent margin profiles and capital intensity requirements. Procurement patterns in North America reveal how AI infrastructure buildouts, automotive electrification, and industrial automation reshape volume allocation across die types and end-use specifications.
Product Type:
Standardization dominates microprocessors and memory chips where scale economics favor merchant vendors, while microcontrollers and analog ICs retain customization latitude through process-tuned variants and application-specific architectures.
- Microprocessors:Complex instruction-set and reduced instruction-set architectures fabricated at leading-edge nodes for computation-intensive workloads. Data center operators in Texas and Arizona clusters drive procurement volumes for AI training and inference acceleration, with cloud providers specifying custom tensor-core configurations.
- Memory Chips:High-bandwidth DRAM and NAND flash arrays enabling data storage and retrieval at speed. AI training clusters in hyperscale facilities concentrate demand for HBM3E and DDR5 modules, though cyclical pricing pressure constrains foundry margin expansion.
- Microcontrollers:Embedded processing units integrating CPU cores with peripherals for deterministic control. Detroit and Tennessee automotive supplier networks source 32-bit and 64-bit variants for powertrain and chassis management systems.
- Analog ICs:Continuous-signal processing devices for voltage regulation, data conversion, and sensor interfacing. Industrial automation OEMs in the Midwest specify precision amplifiers and data converters for process control environments.
Most installed capacity flows through Microprocessors. Expansion is steepest in Memory Chips.
Application:
Volume concentration tracks capital deployment cycles, with automotive and industrial segments commanding longer qualification timelines and stickier supplier relationships than consumer-facing categories.
- Automotive Electronics:Powertrain control, advanced driver-assistance systems, and infotainment modules subject to AEC-Q100 reliability standards. Electric vehicle traction inverters in Michigan and California assembly plants expand silicon carbide and IGBT procurement.
- Consumer Electronics:Smartphones, personal computers, and wearable devices with compressed product lifecycles driving annual die shrinks. Design wins concentrate with Cupertino and Seattle headquarters engineering teams.
- Industrial Automation:Programmable logic controllers, motor drives, and robotic motion controllers requiring extended temperature ranges. Factory floor deployments in Ohio and Illinois manufacturing corridors specify ruggedized packaging.
- Telecommunications:Baseband processors, RF front-end modules, and optical transceivers for 5G infrastructure buildouts. Tower equipment deployments across the Great Plains and Southeast prioritize energy efficiency in power amplifier design.
Automotive Electronics commands the highest average selling prices per wafer. Consumer Electronics delivers the largest unit volumes.
Technology:
Process node differentiation separates commodity production from value-capture opportunities, with digital logic scaling fastest while analog and power technologies exploit mature-node cost structures.
- Digital:CMOS logic gates implementing Boolean operations at nodes from 28nm to 2nm. Leading-edge fabs in Arizona and Texas qualify gate-all-around transistors for sub-3nm production ramps serving cloud AI accelerators.
- Analog:Bipolar and BiCMOS processes optimized for signal fidelity rather than switching speed. Precision instrumentation suppliers in Massachusetts and Colorado specify low-noise operational amplifiers for scientific equipment.
- Mixed-Signal:Integration of analog front-ends with digital signal processing on single die. Automotive radar module manufacturers in Texas combine RF transceivers with baseband processors for adaptive cruise control systems.
- Power Management:Voltage regulators, battery management ICs, and motor drivers fabricated on specialized BCD processes. Data center operators in Virginia and Oregon deploy multi-phase buck converters for server rack power delivery.
Digital technology absorbs the majority of capital expenditure. Power Management is gaining share fastest in revenue terms.
End User:
Procurement authority concentrates with entities controlling system-level architecture decisions, creating tiered supplier access patterns based on design ownership and volume commitment.
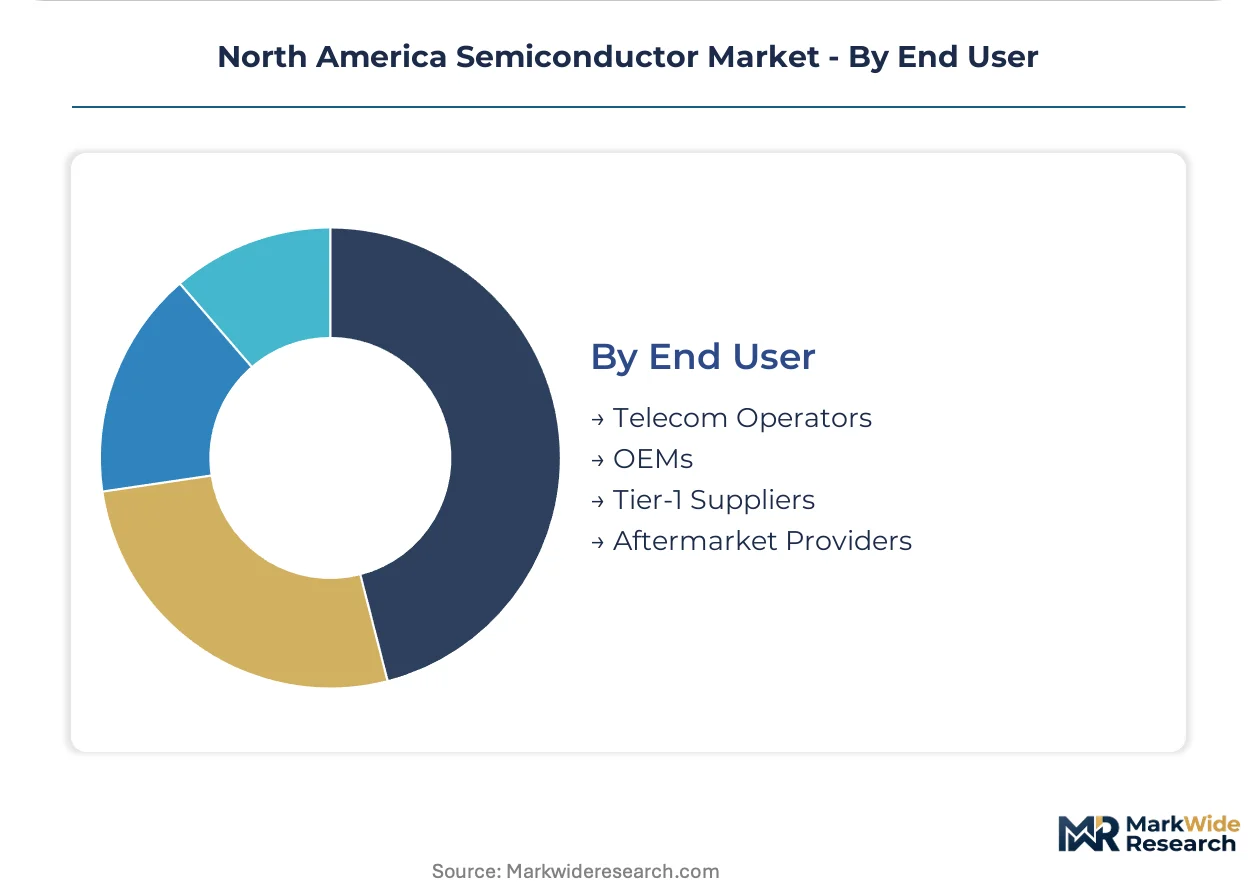
- OEMs:Original equipment manufacturers specifying semiconductor content for finished products. Apple, Tesla, and General Motors maintain direct foundry relationships for custom silicon development.
- Telecom Operators:AT&T, Verizon, and T-Mobile procuring network infrastructure semiconductors for 5G and fiber deployments. Equipment sourcing decisions prioritize supply chain security and domestic fabrication.
- Tier-1 Suppliers:Delphi, Bosch USA, and Magna integrating chips into subsystems for automotive OEMs. Module assembly in Mexico border zones leverages USMCA tariff preferences.
- Aftermarket Providers:Independent distributors and repair networks sourcing replacement components for legacy equipment. Obsolescence management challenges dominate procurement for industrial machinery maintenance.
OEMs command the deepest foundry access for custom development. Tier-1 Suppliers represent the most fragmented procurement base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's semiconductor ecosystem trails the United States in fabrication scale yet exceeds Mexico in design services concentration. Mexico's assembly and test corridor captures tariff-advantaged flows under USMCA that neither northern neighbor can replicate.
United States
Hyperscale cloud operators in Virginia and Oregon data center clusters drive procurement of AI accelerators and high-bandwidth memory modules. The CHIPS and Science Act directs Department of Commerce funding toward domestic wafer fabrication construction. Arizona and Texas host leading-edge fab clusters where TSMC and Intel qualify gate-all-around transistors for sub-3nm production ramps.
Canada
Photonics and compound semiconductor design houses in Ottawa and Toronto serve telecommunications and sensing applications. Industry Canada coordinates with PMRA on environmental review for facilities near the Great Lakes watershed. Waterloo Region anchors quantum computing research programs that pull federal innovation grants and university partnership funding.
Mexico
Automotive electronics assemblers in Baja California and Chihuahua source packaged dies for Detroit and Tennessee OEM supply chains. USMCA rules of origin provisions grant preferential tariff treatment for semiconductor packaging and test operations. Tijuana and Ciudad Juárez concentrate backend capacity that feeds just-in-time delivery schedules for North American vehicle production.
North America Semiconductor Market Competitive Landscape
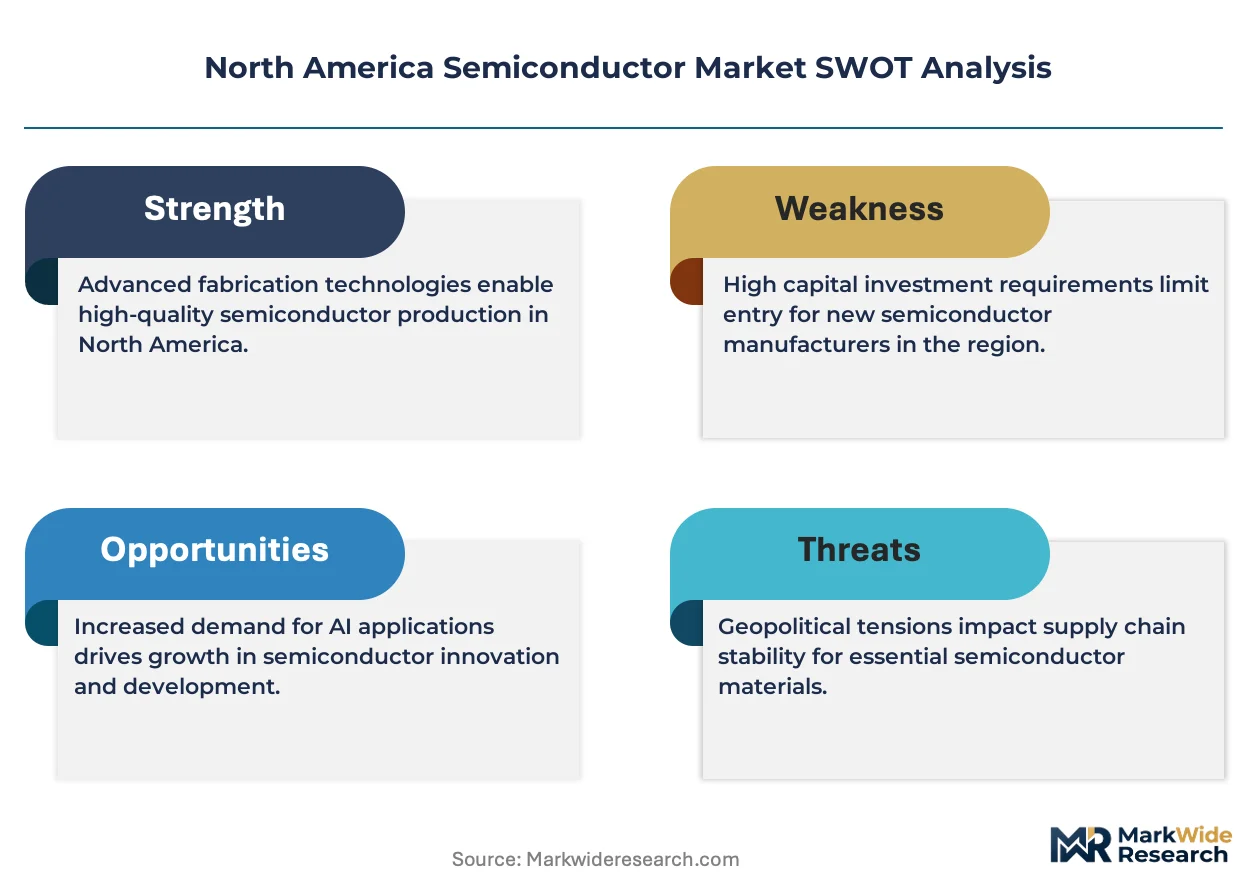
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers controlling captive fabrication while pure-play foundries serve fabless design houses. The vendor base concentrates around three strategic archetypes: IDMs with in-house process technology, fabless designers reliant on external foundry access, and specialty analog houses exploiting mature-node cost structures. Dominant competitive moves include strategic partnerships for advanced packaging co-development and geographic expansion into tariff-advantaged nearshoring corridors.
Within the integrated device manufacturer tier, Intel Corporation anchors domestic foundry ambitions through advanced packaging services for external customers. NVIDIA Corporation exemplifies the fabless AI accelerator archetype, leveraging software-defined silicon licensing to sustain recurring revenue beyond physical die sales. Broadcom Inc. occupies a position in custom silicon co-development, engaging hyperscalers on proprietary chip architectures that bypass merchant semiconductor procurement.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Broadcom Inc. |
| QUALCOMM Incorporated |
| Texas Instruments |
| Analog Devices |
| GlobalFoundries |
| NXP Semiconductors |
| II-VI Incorporated |
| Others |
Pricing and Supply Chain Analysis
EPA fluorinated gas emissions mandates gate qualified supply for etching and chamber cleaning operations, restricting premium-tier pricing access to fabs with certified abatement systems and documented carbon footprint reductions.
Pricing Analysis
Capacity additions in Arizona and Texas are reshaping price floors for leading-edge wafers as TSMC and Intel ramp gate-all-around transistor production. Contract-based long-term offtake agreements dominate, with price differentiation driven by AEC-Q100 automotive certification and volume scale commitments. Cost compression in mature-node microcontrollers is intensifying because legacy 200mm equipment refurbishment delays constrain supply elasticity. Automotive OEMs exhibit the least price sensitivity due to qualification lock-in, while consumer electronics buyers drive the hardest volume negotiations.
Supply Chain Analysis
AEC-Q100 and MIL-STD-883 qualification requirements gate supplier access for automotive and defense applications, concentrating certified capacity with established IDMs. Raw material flows draw from Ukrainian neon purification, Russian palladium refining, and Malaysian packaging substrates. Single-source vulnerability pervades extreme ultraviolet lithography equipment where ASML holds effective monopoly. Distribution runs through authorized distributors for qualified components and spot markets for commodity memory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story as advanced packaging services command premium pricing and software-defined silicon licensing decouples revenue from wafer cost curves.
For Market Incumbents: Anchor domestic foundry capacity through CHIPS Act subsidy capture in Arizona and Texas clusters. Defend against hyperscaler custom silicon teams by deepening advanced packaging co-development partnerships. Prioritize AEC-Q100 certification investment to lock in automotive microcontroller sockets against emerging wide-bandgap competitors. For New Entrants and Emerging Players: Cloud-native EDA platforms enable fabless entry without legacy tool licensing burdens. Target radiation-hardened microelectronics for defense trusted foundry accreditation, the most penetrable segment given DMEA program expansion. Pursue Mexico nearshoring corridors for assembly and test capacity with USMCA tariff advantages. For Investors and Strategic Acquirers: Roll-up economics work for specialty analog houses because process-tuned variants resist commoditization and generate sticky industrial relationships. Five-to-ten year viability hinges on backward integration into silicon carbide substrate supply. Watch hyperscaler capex disclosure inflections as demand signal for AI accelerator foundry loadings.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Co-Development | TSMC Arizona and Intel Foundry Services enable 3D stacking revenue without sole reliance on EUV nodes. |
| CHIPS Act Funding Capture | Department of Commerce subsidies accelerate domestic fab construction and equipment procurement cycles. |
| Defense Trusted Foundry Accreditation | DMEA programs create captive demand for radiation-hardened microelectronics with multi-year contract visibility. |
| Silicon Carbide Vertical Integration | In-house substrate production secures margin capture for electric vehicle traction inverter suppliers. |
| Software-Defined Silicon Licensing | CUDA-like ecosystems sustain recurring revenue streams beyond physical die sales for AI acceleration. |
Research Methodology
Direct dialogue with foundry operations executives, fabless design house CTOs, automotive Tier 1 procurement leads, and defense microelectronics program managers grounded qualitative insights. Secondary validation drew from SEC 10-K filings, Department of Commerce CHIPS Act award announcements, EPA emissions compliance databases, and hyperscaler capex disclosures. Bottom-up wafer demand modeling and top-down semiconductor consumption estimates were triangulated to cross-check volume outputs.
Bottom-up segmentation by product type, application, technology node, and end user category anchored the analytical framework across the projection horizon. CAGRs were derived from installed capacity ramps, die shrink cadences, and content-per-vehicle trends for automotive electrification. Forecast inputs incorporated gate-all-around transistor yield learning curves and high-bandwidth memory attach rates for AI training clusters.
The model assumes a particular technology adoption path; alternative pathways for gate-all-around transistors or chiplet disaggregation would alter the outlook. Forecasts reflect assumptions about CHIPS Act disbursement timing and hyperscaler infrastructure deployment cadence. A model refresh is warranted upon material change in export control classifications for advanced AI accelerators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Semiconductor Target Market
Semiconductors
Semiconductor Market
Semiconductors
Chiplets Market