
 Europe Semiconductor Diode Market | 2026-2036
Europe Semiconductor Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Semiconductor Diode Market Insights
The gap between silicon carbide premium tiers and standard silicon commodity offerings is realigning procurement patterns across European supply chains. Infineon Technologies AG leverages its Dresden manufacturing complex to dominate wide-bandgap substrate production. STMicroelectronics N.V. anchors its position through integrated SiC wafer facilities in Catania, Italy. Nexperia B.V. competes aggressively in automotive-qualified discrete packaging for Manchester and Hamburg production lines.
A semiconductor diode is a two-terminal electronic component permitting unidirectional current flow, typically fabricated from doped silicon, gallium nitride, or silicon carbide with junction temperatures rated between 125°C and 175°C for industrial-grade devices. Its primary purpose lies in rectification, voltage clamping, and switching protection across power electronics and signal conditioning circuits. Schottky diodes and silicon carbide variants command the fastest expansion as electric vehicle onboard chargers and solar inverters displace legacy silicon rectifiers across European industrial automation and energy conversion installations. Rectifier diodes retain volume dominance in consumer electronics power supplies though margin compression intensifies amid Asian import competition.
REACH chemical registration, RoHS substance restrictions, and CE marking under the EU's Radio Equipment Directive collectively dictate material compositions, supplier documentation burdens, and market access preconditions for diode manufacturers selling into Europe. ECHA's evolving candidate list for Substances of Very High Concern directly impacts solder alloys, molding compounds, and passivation layers used in discrete packaging. Stakeholders must monitor the EU Critical Raw Materials Act's silicon carbide supply security provisions as geopolitical sourcing risks intersect with automotive electrification timelines.
Market Dynamics
Automotive electrification timelines are compressing qualification cycles for wide-bandgap discrete components across German and French OEM supply chains, forcing diode manufacturers to accelerate SiC substrate ramp rates while maintaining REACH material purity standards.
Growth Catalysts
- Automotive Electrification:Electric vehicle onboard chargers and DC-DC converters are pulling silicon carbide Schottky diodes into high-volume production across Stuttgart and Munich automotive corridors.
- REACH Compliance:ECHA's Substances of Very High Concern candidate list is driving substitution of legacy solder alloys and molding compounds, creating upgrade demand for compliant discrete packaging.
- Solar Inverter Replacement:Utility-scale photovoltaic installations in Spain and Italy are displacing silicon rectifiers with SiC diodes to achieve higher switching frequencies and reduced thermal losses.
Market Restraints
- Substrate Supply Concentration:Silicon carbide wafer production concentrates among a handful of European and US suppliers, exposing automotive diode manufacturers to allocation risk during capacity ramps.
- Raw Material Cost Volatility:High-purity silicon metal and gallium prices fluctuate with energy costs, compressing margins on standard silicon rectifiers facing Asian import competition.
- Technical Limitation:Silicon carbide gate oxide reliability issues constrain maximum voltage ratings for certain automotive traction inverter applications, delaying full silicon displacement.
Strategic Opportunities
- Underpenetrated Geographies:Poland and Czech Republic industrial automation sectors show low SiC diode penetration relative to Germany, offering first-mover expansion potential for automotive-qualified suppliers.
- EU Critical Raw Materials Act:Silicon carbide supply security provisions create incentives for captive European wafer production, favoring manufacturers with in-house substrate capabilities.
- Technology Convergence:Integration of SiC diodes with GaN power transistors in multi-chip modules enables next-generation onboard charger architectures with higher power density targets.
Industry Challenges
- Power Electronics Talent Gap:Shortages of wide-bandgap device physicists and thermal packaging engineers in Dresden and Catania clusters delay product qualification timelines.
- Capex Intensity:SiC crystal growth furnaces and cleanroom expansion require capital commitments that strain mid-tier discrete manufacturers competing against integrated substrate producers.
- Certification Timeline Compression:Automotive AEC-Q101 qualification cycles must compress from 18 months to 12 months to match EV platform launch schedules without compromising reliability testing rigor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Semiconductor Diode Market |
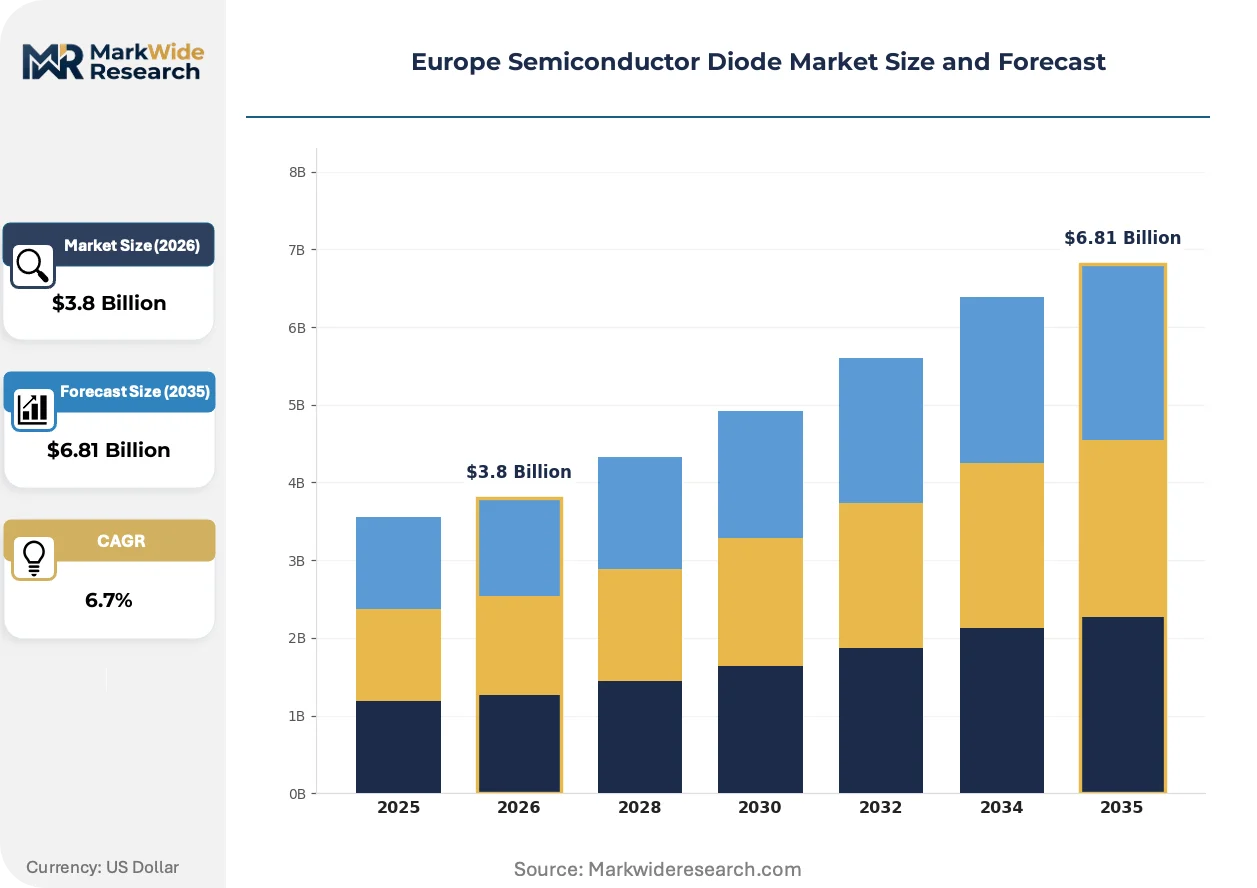
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectifier Diodes, Zener Diodes, Schottky Diodes, Signal Diodes End User: Consumer Electronics, Automotive, Telecommunications, Industrial Automation Technology: Silicon, Gallium Nitride, Silicon Carbide, Organic Application: Power Supply, Signal Processing, Voltage Regulation, Energy Conversion |
| Companies Covered | Infineon Technologies AG, STMicroelectronics N.V., Nexperia B.V., Vishay Intertechnology, Inc., onsemi Corporation, NXP Semiconductors NV, ROHM Co., Ltd., Renesas Electronics Corp., Hitachi Power Semiconductor Device Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Semiconductor Diode Market Trends and Innovations
Wide-bandgap materials are reconfiguring competitive boundaries between discrete component tiers, while regulatory chemical restrictions and procurement centralization reshape how European manufacturers source and specify diode technologies.
Silicon carbide Schottky diodes perform rectification at higher temperatures and switching frequencies than silicon alternatives, enabling automotive OEMs in Germany and France to shrink onboard charger volumes by 30-40 percent. Tier-1 suppliers are consolidating procurement around qualified SiC sources with captive substrate supply, squeezing second-tier discrete vendors into standard silicon commodity segments where margin compression intensifies.
ECHA's evolving REACH candidate list for Substances of Very High Concern now targets specific phthalates and heavy metals used in diode passivation layers and leadframe plating. Manufacturers must reformulate molding compounds and solder alloys to maintain market access, with compliance documentation burdens falling heaviest on small-to-mid tier suppliers serving industrial automation in Northern Italy and Benelux.
Automotive OEMs are consolidating discrete component procurement through direct supplier relationships rather than distributor channels, compressing qualification timelines and demanding application-specific diode co-development. This disintermediation concentrates volume with manufacturers offering integrated SiC wafer-to-package capabilities, particularly visible in German automotive semiconductor corridor sourcing patterns.
Europe Semiconductor Diode Market Segmentation
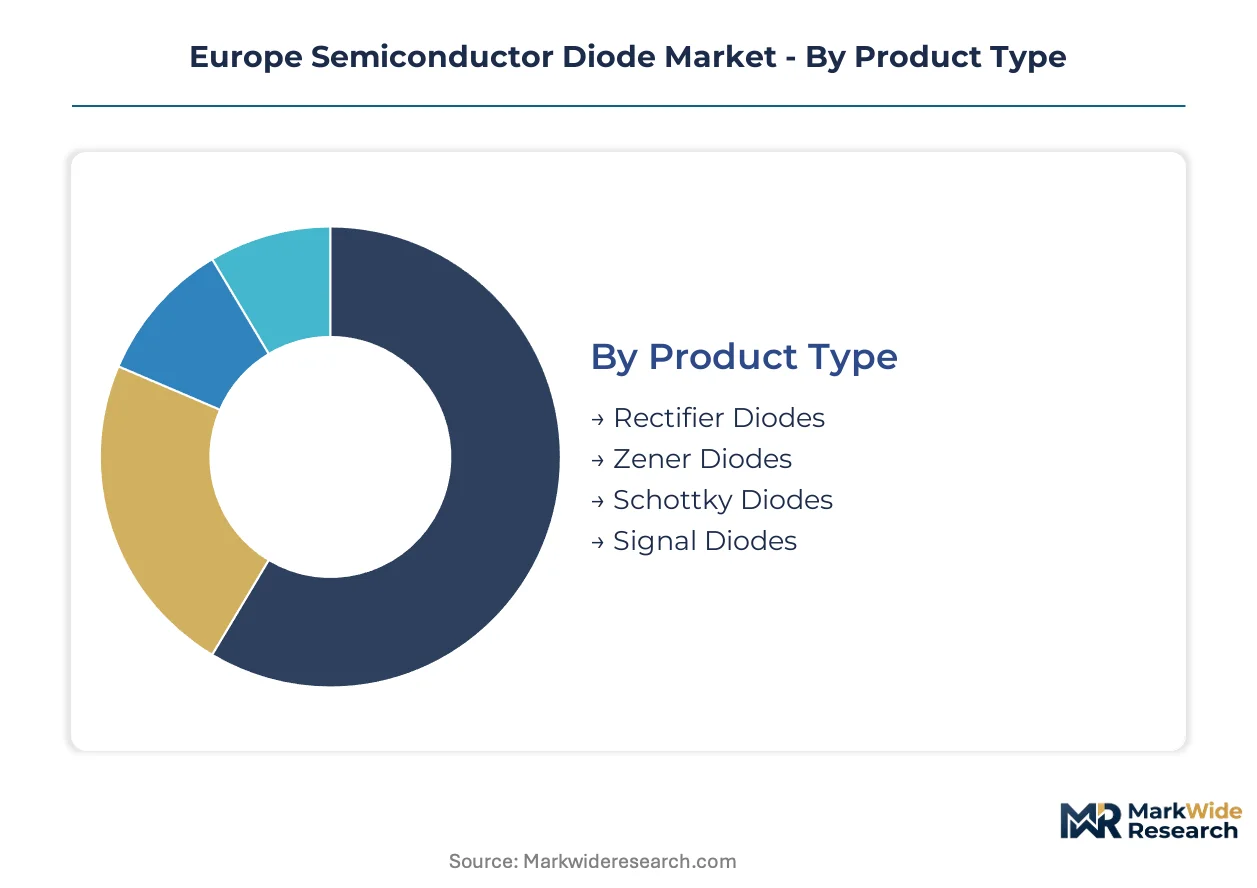
Segmentation reveals how upgrade cycles and replacement demand concentrate across discrete component tiers. Procurement patterns diverge sharply between legacy silicon rectifiers and wide-bandgap alternatives as automotive electrification compresses qualification timelines.
Product Type:
Replacement cycles vary dramatically across diode architectures, with silicon carbide variants displacing legacy rectifiers in thermally constrained applications.
- Rectifier Diodes:Standard silicon p-n junction devices dominate legacy power supply installations across consumer electronics manufacturing in Poland and Czech Republic. Volume demand persists in cost-sensitive industrial motor drives where switching frequency requirements remain modest.
- Schottky Diodes:Metal-semiconductor junction construction delivers lower forward voltage drop and faster switching than p-n alternatives. Demand concentrates in Stuttgart automotive corridor onboard chargers where thermal efficiency targets are tightening.
- Zener Diodes:Reverse breakdown voltage regulation serves reference voltage applications and surge protection circuits.
- Signal Diodes:Small-switching devices handle logic-level rectification and clamping in telecommunications infrastructure.
Volume placements concentrate in Rectifier Diodes; the faster expansion belongs to Schottky Diodes.
End User:
Customer procurement maturity separates specification-driven automotive buyers from price-sensitive consumer electronics assemblers.
- Automotive:AEC-Q101 qualification requirements and traceability mandates dominate sourcing decisions across German and French OEM supply chains. Tier-1 suppliers consolidate procurement around captive-substrate diode manufacturers to secure allocation during silicon carbide capacity ramps.
- Industrial Automation:Factory automation in Northern Italy and Benelux drives demand for high-reliability rectifiers in motor drives and power conversion modules. Extended operational temperature requirements favor industrial-grade packaging over consumer specifications.
- Consumer Electronics:Power adapter and charger manufacturing in Eastern Europe prioritizes cost-optimized standard silicon rectifiers.
- Telecommunications:Base station power supplies and optical networking equipment require signal diodes with tight parameter distribution.
Automotive commands the steepest expansion trajectory; Consumer Electronics retains the largest unit volumes.
Technology:
Material substrate choices determine thermal performance ceilings and switching frequency capabilities across application tiers.
- Silicon Carbide:Wide-bandgap crystal structure enables junction temperatures exceeding 175°C and switching frequencies above 100 kHz. Spanish and Italian solar inverter manufacturers are displacing silicon rectifiers to reduce thermal management system mass.
- Silicon:Mature wafer supply chains and established packaging infrastructure support cost-optimized rectification in high-volume consumer applications.
- Gallium Nitride:Heterostructure devices enable megahertz-range switching in next-generation power conversion architectures.
- Organic:Emerging polymer-based junctions target flexible electronics and biodegradable device applications.
Silicon retains dominant volume share; Silicon Carbide is climbing the fastest.
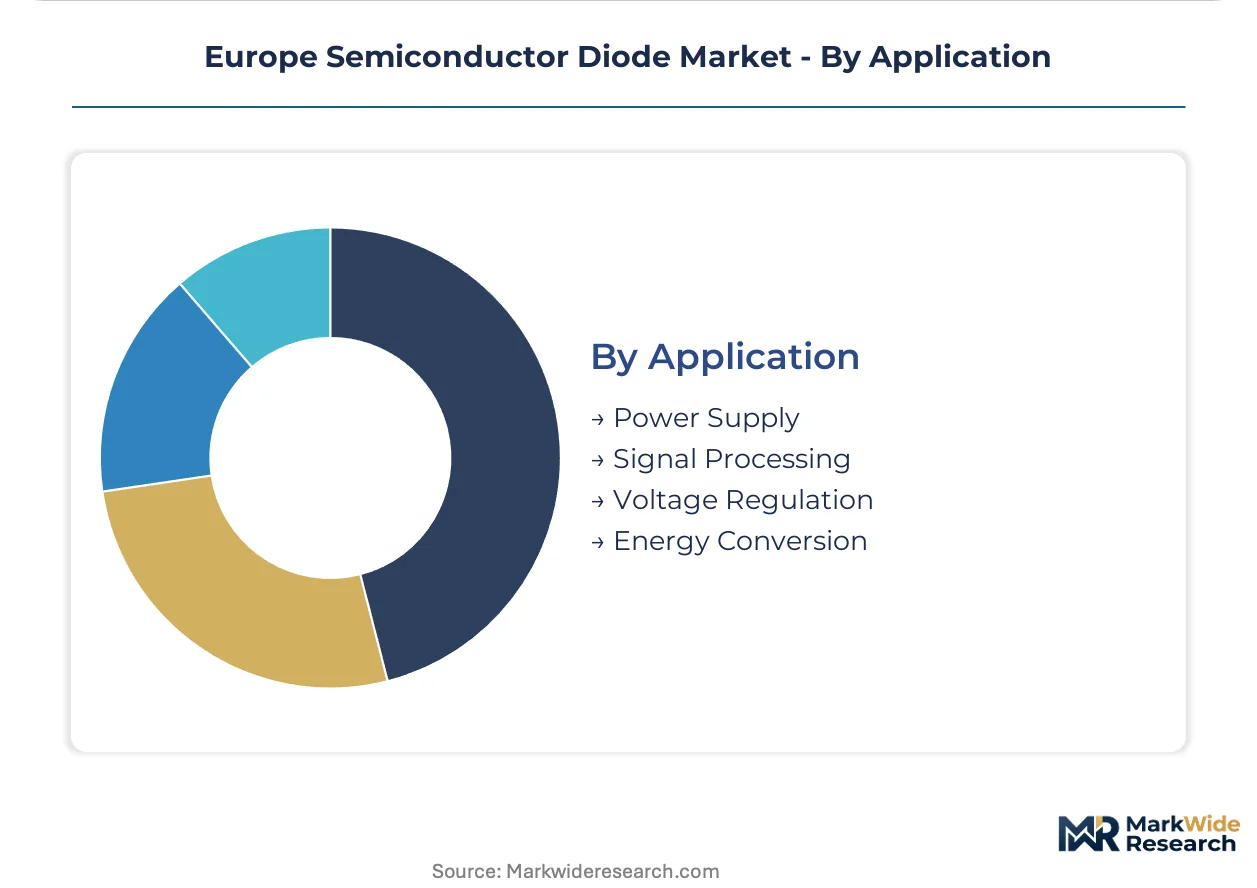
Application:
Functional requirements separate high-frequency switching applications from steady-state rectification duties.
- Power Supply:AC-DC conversion in adapters, chargers, and industrial drives demands rectifier diodes with low forward voltage drop and adequate reverse recovery characteristics. German automotive corridor suppliers are integrating SiC devices to shrink onboard charger volumes.
- Energy Conversion:Solar inverters and wind turbine power electronics require high-voltage rectification with minimal switching losses.
- Voltage Regulation:Zener and avalanche diodes maintain stable reference voltages across automotive and industrial control systems.
- Signal Processing:RF detection, mixing, and switching applications in telecommunications infrastructure demand low-capacitance signal diodes.
Power Supply absorbs the largest component volumes; Energy Conversion shows the steepest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dresden anchors European wide-bandgap substrate production, with Infineon's manufacturing complex driving silicon carbide wafer output for automotive electrification timelines across the continent.
Germany
Stuttgart and Munich automotive corridors pull silicon carbide Schottky diodes into high-volume production for electric vehicle onboard chargers. KBA vehicle type approval requirements enforce AEC-Q101 qualification standards across Tier-1 supplier networks. Baden-Württemberg's industrial automation sector concentrates demand for high-reliability rectifiers in motor drive applications.
France
Paris-Saclay semiconductor research clusters accelerate GaN-SiC integration for next-generation power conversion architectures. ANSM chemical safety oversight intersects with REACH compliance for medical device diode applications. Auvergne-Rhône-Alpes hosts specialty packaging operations serving aerospace-qualified discrete component demand.
Italy
Catania's integrated SiC wafer facilities anchor STMicroelectronics' substrate-to-package capabilities for solar inverter manufacturers displacing silicon rectifiers. ECHA substance restrictions drive reformulation of molding compounds in Northern Italy's industrial automation supply base. Lombardy's factory automation sector demands extended temperature-range rectifiers for motor control systems.
Spain
Andalusian utility-scale photovoltaic installations deploy SiC diodes to achieve higher switching frequencies and reduced thermal losses in string inverter designs. CE marking under the Radio Equipment Directive governs telecommunications infrastructure signal diode specifications. Madrid's renewable energy project pipelines sustain replacement demand for legacy silicon rectification components.
Netherlands
Eindhoven's automotive electronics ecosystem sources automotive-qualified discrete packaging from Nexperia's Hamburg and Manchester production lines. REACH registration requirements concentrate documentation burdens on molding compound suppliers serving Benelux industrial markets. Randstad port logistics facilitate silicon carbide substrate import flows for distribution across German supply chains.
Europe Semiconductor Diode Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in European diode supply. Integrated substrate manufacturers capture premium-tier automotive qualification volumes while discrete packaging specialists defend position in cost-sensitive industrial segments. Three archetypes dominate: captive wafer producers, automotive-qualified packaging houses, and commodity rectifier importers. Capacity expansion and REACH-compliant material reformulation represent the dominant competitive moves as electrification timelines compress.
Among Germany-based integrated producers, Infineon Technologies AG occupies the captive substrate tier, leveraging Dresden manufacturing depth. STMicroelectronics N.V. anchors the Mediterranean wafer-to-package vector through Italian facilities. Nexperia B.V. exemplifies the automotive-qualified discrete packaging archetype with production lines spanning Hamburg and Manchester. These three represent divergent strategic positions within a market splitting between wide-bandgap premium tiers and silicon commodity compression.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| Nexperia B.V. |
| Vishay Intertechnology, Inc. |
| onsemi Corporation |
| NXP Semiconductors NV |
| ROHM Co., Ltd. |
| Renesas Electronics Corp. |
| Hitachi Power Semiconductor Device Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive substrate production at Infineon's Dresden complex anchors both supply security and pricing power for automotive-qualified silicon carbide diodes across German OEM networks. This backward integration into SiC crystal growth insulates qualified suppliers from raw material allocation shocks while commanding premium positioning against second-tier discrete packagers.
Pricing Analysis
Automotive uptime guarantees anchor value-based pricing for AEC-Q101 qualified diodes, with Tier-1 suppliers contracting directly for yield-assured volumes rather than spot-market transactions. Price differentiation separates captive-substrate manufacturers from packaging specialists, with REACH compliance documentation adding cost layers that commodity importers cannot absorb. Cost compression in standard silicon rectifiers intensifies because Asian import competition floods Eastern European consumer electronics assembly lines. Consumer electronics power adapter manufacturers in Poland and Czech Republic exhibit acute price sensitivity, while Stuttgart corridor OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
High-purity silicon carbide wafer supply rests on concentrated European and US crystal growth facilities, with Dresden and Catania clusters feeding downstream packaging operations in Hamburg and Manchester. Raw material dependencies span high-purity silicon metal, gallium feedstock for GaN heterostructures, and specialty molding compounds subject to ECHA substance restrictions. Single-source vulnerability concentrates in SiC substrate allocation during automotive electrification capacity ramps, exposing second-tier diode manufacturers to forced silicon substitution. Distribution runs through direct OEM procurement channels rather than distributor networks, compressing margin capture for non-qualified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive qualification timeline compression is forcing consolidation as mid-tier discrete manufacturers lack capital for simultaneous SiC substrate investment and REACH-compliant material reformulation.
For Market Incumbents: Deepen captive wafer production through Dresden-equivalent facility expansion to secure allocation priority during silicon carbide capacity ramps. Accelerate AEC-Q101 qualification cycle compression from 18-month baselines to match 12-month EV platform launch schedules without compromising thermal reliability testing rigor. For New Entrants and Emerging Players: Industrial automation buyers in Poland and Czech Republic represent underserved white-space targets with low SiC diode penetration relative to German automotive corridors. Enter through application-specific co-development partnerships with Northern Italian motor drive manufacturers seeking extended temperature-range rectifiers, bypassing direct competition with integrated substrate producers for automotive qualification slots. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-qualified discrete packaging specialists with Hamburg or Manchester production footprints and established AEC-Q101 certification records. Long-term viability hinges on substrate-to-package integration depth; watch for silicon carbide wafer allocation inflections at German Tier-1 supplier networks as demand-pull indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Production | Dresden and Catania facilities capture allocation priority during automotive capacity ramps. |
| REACH-Compliant Material Reformulation | ECHA candidate list compliance maintains market access for European molding compound suppliers. |
| AEC-Q101 Qualification Cycle Compression | 12-month automotive timelines match EV platform launches without reliability compromise. |
| Direct OEM Procurement Channel Development | Stuttgart corridor disintermediation concentrates volume with qualified substrate-to-package suppliers. |
| Multi-Chip Module Integration Partnerships | GaN-SiC convergence enables next-generation onboard charger architectures with higher power density. |
Research Methodology
Document review covered ECHA substance restriction filings, EU Critical Raw Materials Act provisions, and automotive OEM supplier qualification requirements, complemented by interviews with power electronics procurement leads at German Tier-1 suppliers, thermal packaging engineers in Dresden and Catania clusters, and REACH compliance officers at discrete component manufacturers. Secondary validation drew from KBA vehicle type approval databases, customs records for silicon carbide substrate import flows, and SEC filings of integrated substrate producers. Bottom-up volume estimates triangulated against top-down automotive electrification penetration assumptions.
Cross-referencing historical qualification timeline data against expert panel input on EV platform launch schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include diode architecture, end-user procurement maturity, substrate material technology, and functional application requirements. CAGRs derived from automotive content-per-vehicle trajectories and solar inverter replacement cycle intensity, with silicon carbide penetration rates and REACH compliance cost pass-through as industry-specific forecast inputs.
Revisions become necessary when ECHA expands Substances of Very High Concern designations, automotive OEMs accelerate platform launch schedules, or silicon carbide wafer allocation constraints tighten beyond modeled baselines. Forecasts reflect documented assumptions about electrification penetration and regulatory compliance timelines. A small set of named triggers—substrate supply disruption, qualification timeline compression failure, and REACH substance list expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Europe Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Gaas Wafer Market
Semiconductors
China Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Smartphone Battery Market