
 Analog Semiconductor Market | 2026-2036
Analog Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Analog Semiconductor Market Analysis
Asset-light foundry partnerships and equipment leasing arrangements is reconfiguring capital barriers for new entrants in analog semiconductor fabrication. Texas Instruments leverages captive 300mm analog wafer capacity to sustain cost leadership across power management portfolios. Infineon Technologies anchors its position through in-house silicon carbide substrate production, while STMicroelectronics competes via diversified exposure to automotive and industrial end markets.
An analog semiconductor processes continuous electrical signals through transistors, resistors, capacitors, and inductors fabricated on silicon or compound semiconductor substrates, typically operating at voltages below 100V for signal chain functions and above 100V for power applications, with bandwidth specifications ranging from DC to multiple gigahertz depending on the circuit architecture. Its primary commercial purpose is to interface between physical sensors or power sources and digital processing systems, enabling real-world signal conditioning, power conversion, and motor control. Voltage regulators and data converters occupy the deepest margin pools within product type categories, reflecting their irreplaceable role in precision power delivery and sensor digitization. CMOS technology dominates unit volume across consumer and computing applications, while GaN and silicon carbide processes are capturing the fastest expansion in automotive traction inverters and telecommunications base station power amplifiers.
The EPA regulates hazardous substance reporting for semiconductor manufacturing facilities in the United States, while REACH and RoHS frameworks in Europe constrain material composition across imported analog components. China's MIIT enforces domestic content ratios through GB standards certification, reshaping supply qualification requirements for foreign suppliers. Japan's METI coordinates national semiconductor strategy through subsidies and joint development consortia, directly influencing regional capacity allocation decisions. Stakeholders must monitor how carbon border adjustment mechanisms and export control expansions alter foundry location economics and customer qualification timelines.
Market Dynamics
Silicon carbide substrate advances and gallium nitride epitaxy improvements are compressing switching losses in high-voltage applications, fundamentally altering competitive economics for power management integrated circuits across automotive and industrial end uses.
Growth Catalysts
- Automotive electrification mandates:Germany, Japan, and the United States are pulling demand for traction inverters and onboard chargers through fleet electrification timelines and emissions standards enforcement.
- REACH and RoHS frameworks:European material composition constraints are accelerating qualification of lead-free and halogen-free analog packages for industrial automation and medical device exports.
- Domestic wafer fab expansion:China's eastern manufacturing corridor is concentrating analog capacity additions to serve local automotive tier-1 suppliers and industrial equipment builders.
Market Restraints
- Silicon carbide substrate cost volatility:Limited qualified substrate suppliers concentrate pricing power and create input cost instability for high-voltage power device manufacturers.
- Equipment leasing dependency:Asset-light foundry partnerships expose new entrants to capacity allocation risk when leading-edge analog demand surges.
- GaN thermal management limitations:Power density advantages in telecommunications base stations face reliability constraints under sustained junction temperatures above 150°C.
Strategic Opportunities
- India industrial automation:BIS certification requirements and PLI scheme incentives for domestic electronics manufacturing are creating qualification pathways for analog suppliers establishing local test and packaging operations.
- Energy storage system integration:Battery management analog front-ends represent underpenetrated demand as grid-scale lithium-ion deployments accelerate in North America and Europe.
- EU Green Deal carbon border adjustments:Embedded emissions tracking requirements favor analog suppliers with transparent foundry energy sourcing and process water recycling credentials.
Industry Challenges
- Compound semiconductor process engineering scarcity:GaN epitaxy and SiC defect control expertise concentrates among experienced foundry operators, constraining talent pools for capacity expansion programs.
- Multi-jurisdiction certification timelines:Simultaneous EPA hazardous substance reporting, REACH substance registration, and MIIT GB standards compliance extend product qualification cycles by 12-18 months for new analog power devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog Semiconductor Market |
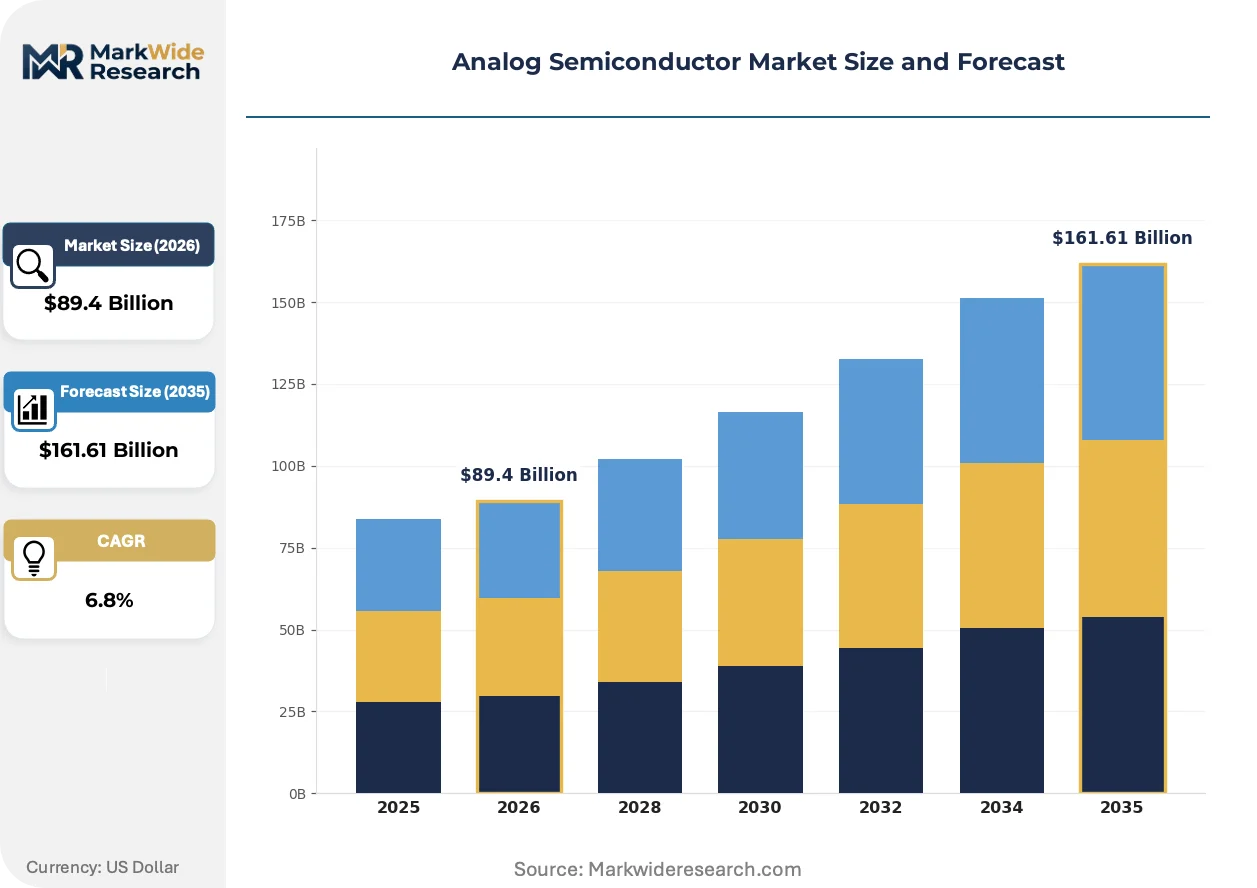
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $161.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Operational Amplifiers, Voltage Regulators, Comparators, Data Converters Technology: CMOS, BiCMOS, Bipolar, GaN Application: Consumer Electronics, Automotive Systems, Industrial Automation, Telecommunications End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | Infineon Technologies, Skyworks Solutions, Analog Devices, Wolfspeed, Qorvo, Texas Instruments, NXP Semiconductors, Maxim Integrated, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog Semiconductor Market Emerging Trajectories
Process technology migration and regulatory compliance architectures are redefining how analog semiconductor suppliers structure R&D allocation and foundry partnerships across voltage classes and end-use verticals.
Silicon carbide MOSFET technology handles power switching in electric vehicle traction inverters and renewable energy converters. Automotive OEMs in Germany and the United States are qualifying 800V architectures at accelerated pace. The technology is migrating from niche performance applications to cost-competitive mainstream replacement of silicon IGBTs in 400V-800V systems.
EPA hazardous substance reporting requirements for semiconductor manufacturing facilities are tightening disclosure thresholds for fluorinated greenhouse gases and heavy metal process chemicals. Fabrication sites in the United States face expanded monitoring obligations and third-party verification mandates. High-voltage power analog suppliers with captive 300mm capacity are consolidating production in EPA-registered facilities to streamline compliance documentation.
Direct procurement relationships between automotive OEMs and analog semiconductor suppliers are displacing traditional tier-1 distributor intermediation for battery management and motor drive components. German and Japanese vehicle manufacturers are establishing technical qualification teams with direct foundry access. This pattern concentrates most visibly in power management categories where silicon carbide device customization determines inverter efficiency benchmarks.
Analog Semiconductor Market Segmentation
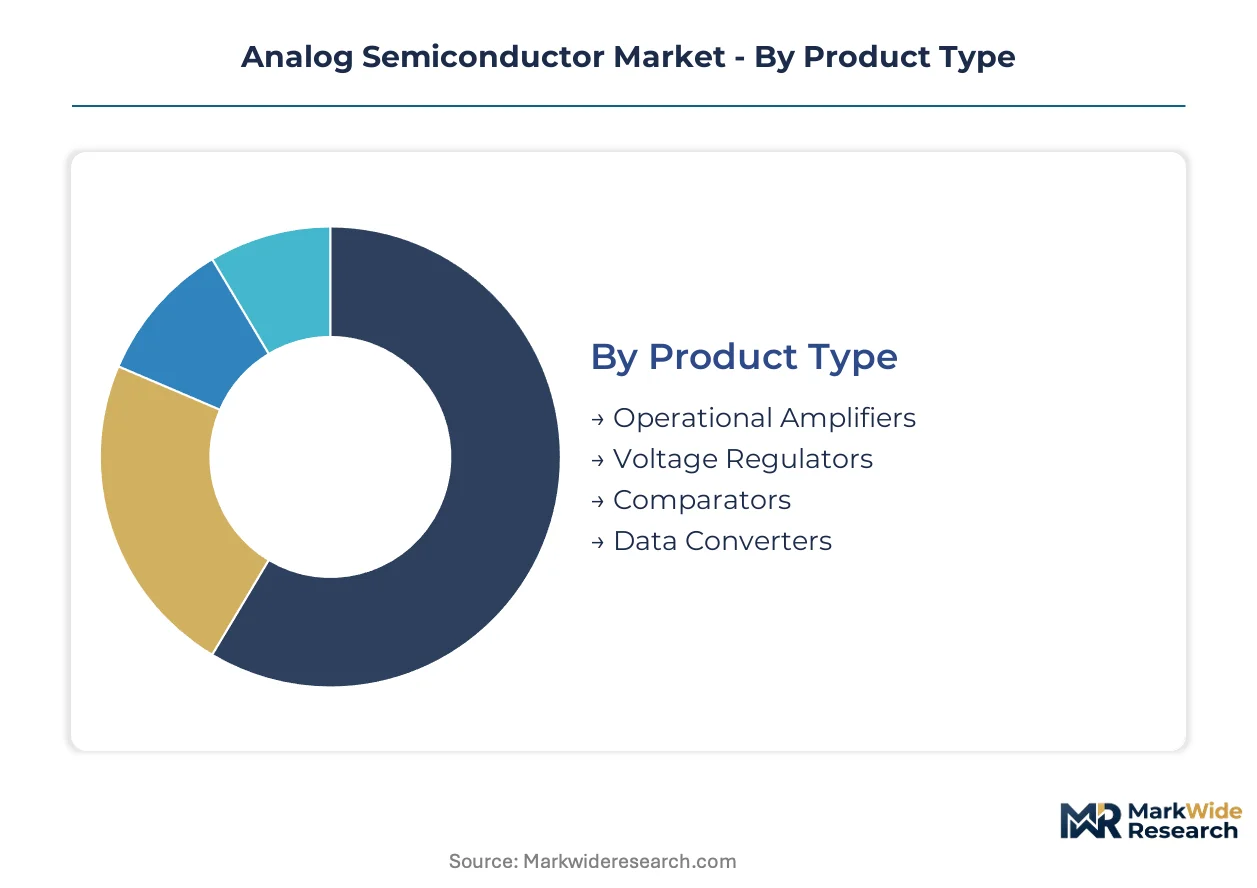
Analog semiconductor segmentation reveals how voltage specifications, process architectures, and customer procurement patterns create distinct competitive arenas. Each dimension carries different margin profiles, qualification timelines, and captive capacity requirements.
Product Type:
Voltage regulators and data converters command premium positioning through precision specifications, while operational amplifiers and comparators serve broader signal conditioning needs across price-sensitive applications.
- Voltage Regulators:These devices maintain stable output voltage across varying input conditions and load currents through linear or switching topologies. Automotive electrification programs in Germany, Japan, and the United States are pulling demand for multi-phase buck controllers in battery management systems. Silicon carbide substrate integration is compressing switching losses in high-voltage automotive applications.
- Data Converters:Analog-to-digital and digital-to-analog circuits translate physical sensor signals into digital processing formats with resolution specifications from 8-bit to 24-bit. Industrial automation deployments in China's eastern manufacturing corridor are concentrating demand for high-speed precision converters in motion control systems. REACH and RoHS frameworks in Europe are accelerating qualification of halogen-free packages for medical device exports.
- Operational Amplifiers:Differential amplification circuits with high input impedance serve sensor interface and signal conditioning functions across consumer and industrial equipment.
- Comparators:High-speed voltage level detection devices trigger digital responses in power management and safety monitoring subsystems.
The dominant share belongs to voltage regulators, while data converters are closing the gap fastest.
Technology:
Process selection traces power density requirements against frequency specifications, with mature silicon geometries competing against compound semiconductor insertion in high-voltage and high-frequency niches.
- CMOS:Complementary metal-oxide-semiconductor fabrication dominates unit volume through scalable lithography and low static power consumption. Consumer electronics manufacturers in South Korea and Taiwan are concentrating orders for sub-100nm CMOS analog in smartphone camera modules and display driver ICs.
- GaN:Gallium nitride epitaxy enables power switching above 1MHz with superior efficiency in compact form factors. Telecommunications base station deployments in North America and Europe are pulling demand for GaN power amplifiers in massive MIMO transmitters. Thermal management limitations above 150°C junction temperatures constrain sustained reliability in enclosed outdoor installations.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with dense CMOS logic for mixed-signal processing in precision instrumentation.
- Bipolar:Traditional junction transistor processes retain cost advantages in linear regulation and audio amplification where frequency requirements remain modest.
CMOS maintains volume leadership, though GaN is expanding most quickly in power conversion applications.
Application:
End-use verticals separate commodity consumer volumes from automotive qualification rigor and industrial longevity requirements.
- Automotive Systems:Traction inverters, onboard chargers, and battery management electronics operate across 400V-800V architectures with AEC-Q100 qualification mandates. German and Japanese OEMs are establishing direct procurement relationships with analog suppliers for silicon carbide device customization. EPA hazardous substance reporting requirements are consolidating production in registered fabrication facilities.
- Industrial Automation:Motor drives, programmable logic controllers, and sensor interfaces demand 10-20 year supply continuity with extended temperature specifications. China's domestic wafer fab expansion is serving local tier-1 industrial equipment builders with qualified analog capacity.
- Consumer Electronics:Smartphones, wearables, and computing peripherals drive CMOS analog volume through annual product refresh cycles.
- Telecommunications:Base station power amplifiers and optical transceivers require high-frequency performance with energy efficiency specifications.
Automotive systems capture the steepest expansion trajectory, while industrial automation provides the most stable long-term contracting environment.
End User:
Procurement authority is shifting from traditional distribution channels toward direct technical engagement between analog suppliers and terminal equipment manufacturers.
- OEMs:Original equipment manufacturers in automotive and telecommunications are bypassing tier-1 intermediaries for power management component qualification. Direct foundry access allows German vehicle manufacturers to specify silicon carbide device geometries for inverter efficiency optimization.
- Tier-1 Suppliers:Subsystem integrators retain procurement influence in industrial automation and medical equipment where multi-source qualification remains standard practice.
- Aftermarket Providers:Replacement component distributors serve repair and refurbishment channels with less stringent qualification requirements.
- System Integrators:Turnkey solution providers bundle analog components with software and mechanical subsystems in custom industrial deployments.
OEMs command the dominant procurement share, while direct supplier engagement is displacing traditional tier-1 intermediation fastest in automotive power management categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and industrial equipment builders concentrate procurement authority across manufacturing corridors in Germany, China, Japan, the United States, and South Korea. Direct supplier engagement is displacing traditional distribution channels in power management categories.
United States
Electric vehicle manufacturers in Michigan and California are qualifying 800V traction inverter architectures at accelerated pace. EPA hazardous substance reporting requirements tighten disclosure thresholds for fluorinated greenhouse gases at fabrication facilities. Austin and Phoenix anchor expanding analog wafer capacity serving domestic automotive tier-1 suppliers.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are establishing direct technical qualification teams with foundry access for silicon carbide device customization. REACH substance registration and RoHS compliance frameworks constrain material composition for industrial automation exports. Dresden and Regensburg concentrate power semiconductor fabrication serving European electrification programs.
China
Domestic wafer fabs in the Yangtze River Delta are expanding analog capacity to serve local battery management and motor drive demand. MIIT enforces domestic content ratios through GB standards certification reshaping supply qualification for foreign suppliers. Shanghai and Wuxi anchor the eastern manufacturing corridor where state-backed capacity additions target automotive and industrial customers.
Japan
Vehicle manufacturers in Aichi and Kanagawa prefectures are pulling demand for onboard chargers and DC-DC converters through fleet electrification timelines. METI coordinates national semiconductor strategy through subsidies and joint development consortia directly influencing regional capacity allocation. Kyoto and Nagoya retain concentration in precision analog design for industrial automation and telecommunications equipment.
South Korea
Consumer electronics manufacturers in Gyeonggi Province are concentrating orders for sub-100nm CMOS analog in smartphone camera modules and display driver ICs. The country's national semiconductor regulator enforces process environmental standards through facility certification requirements. Seoul and Suwon anchor design centers where fabless analog specialists engage foundry partners for advanced node production.
Analog Semiconductor Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where captive wafer capacity and compound semiconductor expertise create distinct competitive arenas. Consolidation characterizes high-voltage power management while signal chain categories retain fragmentation. Three archetypes dominate: integrated device manufacturers with captive fabrication, fabless specialists leveraging foundry partnerships, and diversified conglomerates spanning multiple semiconductor categories. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified substrate supply and foundry allocation.
Among diversified European-based fabricators, Infineon Technologies and STMicroelectronics exemplify integrated production archetypes with in-house silicon carbide substrate capabilities and broad automotive exposure. Texas Instruments represents the scale-driven captive capacity model with 300mm analog wafer fabrication sustaining cost leadership across power management portfolios. These three anchors demonstrate how upstream control over substrate supply and wafer fabrication creates defensive positioning against foundry allocation volatility.
| Leading Market Players |
|---|
| Infineon Technologies |
| Skyworks Solutions |
| Analog Devices |
| Wolfspeed |
| Qorvo |
| Texas Instruments |
| NXP Semiconductors |
| Maxim Integrated |
| STMicroelectronics |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor channels silicon carbide substrates and gallium nitride wafers from Shanghai port to inland fabrication clusters, with logistics cost spikes during peak automotive qualification cycles compressing margins for fabless analog specialists while amplifying price differentiation between captive-capacity incumbents and equipment-leasing dependent entrants.
Pricing Analysis
Cost-plus contracts with silicon carbide substrate indexation dominate high-voltage power device procurement, tying analog supplier margins to volatile raw material benchmarks. Pricing stratifies across AEC-Q100 automotive qualification tiers, ISO 13485 medical certification grades, and standard industrial specifications. Cost compression in sub-100V CMOS signal chain components stems from China's domestic wafer fab capacity additions. Tier-1 automotive OEMs exhibit lowest price sensitivity due to inverter efficiency customization requirements, while consumer electronics manufacturers drive aggressive unit-cost negotiations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Japanese trading houses anchor working capital structures for Taiwan and South Korea foundry customers. Substrate supply concentrates in Japan, the United States, and Germany for silicon carbide boule production, while gallium nitride epitaxy draws from Taiwan and South Korea. Raw material dependencies span high-purity silicon carbide powder, rare-earth dopants for GaN heterostructures, and fluorinated process chemicals. Single-source vulnerability in qualified 150mm SiC substrate supply creates allocation risk during automotive ramp cycles. Distribution runs through direct OEM technical qualification teams displacing traditional tier-1 distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN epitaxy and SiC defect control expertise concentrates among a handful of experienced foundry operators, constraining capacity expansion timelines and amplifying returns for asset owners with proven process yields.
For Market Incumbents: Build captive substrate supply moats through in-house silicon carbide boule production or long-term offtake agreements with Japanese and German qualified suppliers. Add 300mm analog wafer capacity in EPA-registered US facilities to streamline hazardous substance reporting compliance. Defend against fabless entrants exploiting equipment leasing partnerships by securing priority allocation clauses during demand surge periods. For New Entrants and Emerging Players: Establish a beachhead in India's industrial automation segment by securing BIS certification and local test and packaging partnerships under PLI scheme incentives. Target battery management analog front-ends for grid-scale energy storage deployments in North America where incumbent qualification backlogs create procurement gaps. Pursue direct technical engagement with German automotive OEMs seeking silicon carbide device customization for 800V traction inverter architectures. For Investors and Strategic Acquirers: Fabless analog specialists with proven GaN power amplifier designs and established foundry relationships represent priority acquisition targets given compound semiconductor process engineering scarcity. Long-term viability hinges on securing qualified substrate supply and navigating multi-jurisdiction certification timelines. Watch for carbon border adjustment mechanism implementation in Europe as an inflection indicator favoring suppliers with transparent foundry energy sourcing credentials.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | In-house SiC boule production secures supply allocation for automotive traction inverter qualification programs. |
| 300mm Analog Wafer Capacity Expansion | Captive fabrication in EPA-registered facilities streamlines hazardous substance reporting for US automotive customers. |
| Direct OEM Technical Qualification | Bypassing tier-1 distributors enables silicon carbide device geometry customization for German vehicle manufacturers. |
| GaN Thermal Management R&D Investment | Reliability solutions above 150°C junction temperatures unlock telecommunications base station deployment scale. |
| India Local Test and Packaging Operations | BIS certification and PLI scheme alignment opens qualification pathways for industrial automation demand. |
Methodological Framework
A standing panel of analog semiconductor design engineers, foundry operations directors, automotive Tier-1 procurement managers, and industrial equipment OEM technical qualification leads provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA hazardous substance reporting databases, MIIT GB standards certification records, METI subsidy disclosure filings, and REACH substance registration repositories. Bottom-up unit demand modeling triangulated against top-down wafer capacity and substrate supply assessments.
Scenario-bracketing around silicon carbide substrate cost trajectories and gallium nitride thermal reliability thresholds bounded the projection horizon. Segmentation dimensions spanned voltage class architecture, process technology node, end-use vertical qualification tier, and regional regulatory cluster. CAGRs derived from wafer start forecasts, content-per-vehicle trends in automotive electrification programs, and industrial automation capital expenditure patterns across the analysis window.
Sensitivities concentrate around silicon carbide substrate supplier qualification delays, EPA disclosure threshold tightening for fluorinated greenhouse gases, and MIIT domestic content ratio enforcement intensity. Forecasts embed assumptions regarding automotive electrification timeline adherence and foundry equipment delivery schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Chiplets Market
Semiconductors
North America Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
Semiconductor Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Compound Semiconductor Market
Semiconductors
Semiconductor IP Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Semiconductor Intellectual Property Market