
 Global Computer Microchip Market | 2026-2036
Global Computer Microchip Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer Microchip Market Intelligence
Chiplet-based modularization of processor designs is shifting buyer choice toward specialized, high-performance computing solutions. Advanced Micro Devices (AMD) leverages this approach to compete effectively in the server market. Intel Corporation positions its own advanced packaging technologies to defend its historical market share. Taiwan Semiconductor Manufacturing Company (TSMC) sustains this ecosystem for numerous fabless companies through its leading-edge foundry services and advanced packaging capabilities.
A computer microchip is a monolithic integrated circuit fabricated on a silicon wafer, containing billions of transistors organized to perform logic or memory functions. These devices are manufactured using photolithography processes, with leading-edge chips built on nodes smaller than 7 nanometers. Microprocessors designed for data centers represent a high-margin application driven by artificial intelligence workloads. In contrast, memory chips, particularly for consumer electronics, exhibit more cyclical pricing and volume dynamics.
Governmental policies like the US CHIPS and Science Act and the European Chips Act are directing significant public investment into domestic semiconductor manufacturing. Concurrently, regulations such as China's dual carbon goals influence energy consumption standards for fabrication facilities. Navigating these divergent industrial policies and securing access to critical manufacturing equipment from suppliers like ASML Holding will define strategic success for all market participants.
Market Dynamics
Governmental industrial policy is the central force shaping the computer microchip market. National security imperatives, embodied in the US CHIPS Act and European Chips Act, are compelling a geographic re-shuffling of advanced semiconductor manufacturing capacity and altering global supply chain strategies.
Growth Catalysts
- Extreme Ultraviolet Lithography:This advanced manufacturing process enables the production of sub-7nm nodes, unlocking higher performance and efficiency for processors used in data centers and for artificial intelligence workloads.
- Data Center Expansion:The proliferation of cloud computing and AI requires massive deployments of high-performance microprocessors and memory, creating sustained, high-margin demand for leading-edge silicon.
- US CHIPS and Science Act:This legislation provides significant financial incentives for building new semiconductor fabrication plants on US soil, aiming to increase domestic production capacity and secure supply chains.
Market Restraints
- Foundry Concentration in Taiwan:The overwhelming majority of advanced logic chip manufacturing is located in Taiwan, creating a significant geopolitical and logistical vulnerability for the global supply chain.
- Photolithography Equipment Scarcity:Access to critical EUV lithography machines, supplied almost exclusively by a single European company, limits the pace at which new fabrication capacity can be built by all market participants.
- High Capital Expenditure:The cost to build and equip a leading-edge semiconductor fabrication plant exceeds tens of billions of dollars, creating a formidable barrier to entry for new market participants.
Strategic Opportunities
- Chiplet-Based Architectures:Modular chiplet designs allow for the integration of diverse process nodes on a single package, creating opportunities for specialized, cost-effective high-performance computing solutions.
- Automotive Silicon Content:The transition to electric and autonomous vehicles is driving a rapid increase in the number and complexity of microchips required per vehicle, opening a high-volume, long-lifecycle market.
- European Chips Act:This initiative aims to increase the EU's share of semiconductor production, offering public funding and streamlined permitting for new foundries and R&D centers within the bloc.
Industry Challenges
- Specialized Workforce Scarcity:A global shortage of engineers and technicians with expertise in semiconductor design and process engineering threatens to delay new fab construction and ramp-up schedules.
- Navigating Divergent Regulations:Market participants must manage conflicting industrial policies and environmental standards, such as China's dual carbon goals versus different frameworks in the US and EU, complicating global operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer Microchip Market |
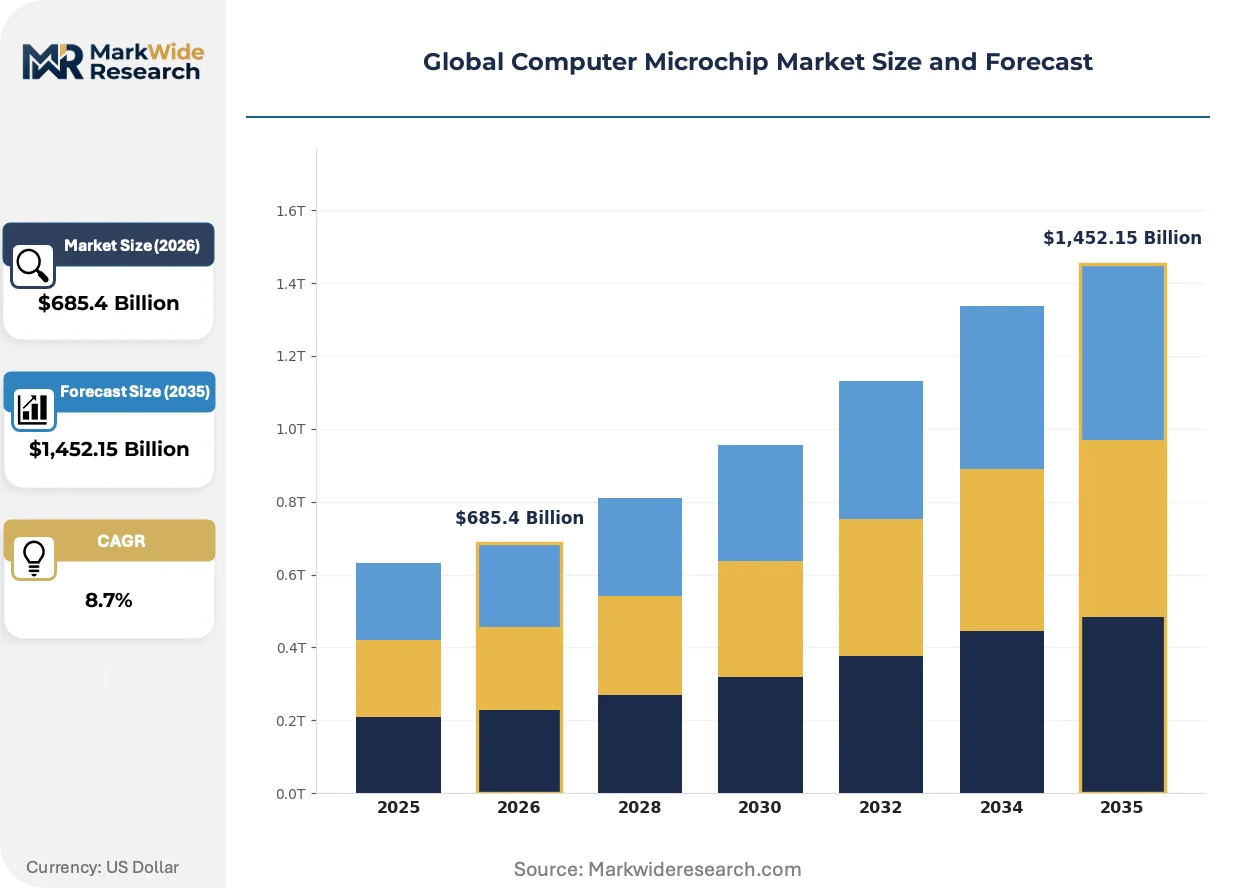
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,452.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Memory Chips, Logic ICs, Analog ICs, Mixed-Signal ICs Technology: CMOS, Bipolar, BiCMOS, GaAs, SOI Application: Consumer Electronics, Data Centers, Telecommunications Equipment, Aerospace Systems, Industrial Automation End User: OEMs, Semiconductor Foundries, Electronic Manufacturing Services, Research Institutions, Defense Contractors |
| Companies Covered | Samsung Electronics, Qualcomm Incorporated, NVIDIA Corporation, Micron Technology, Intel Corporation, Taiwan Semiconductor Manufacturing Company (TSMC), Advanced Micro Devices (AMD), ASML Holding, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer Microchip Market Strategic Shifts & Innovations
A fundamental shift from monolithic chip design toward heterogeneous integration is underway, driven by the physical limits of silicon scaling. Advanced packaging is becoming as critical as front-end lithography in delivering performance gains for next-generation computing.
Advanced packaging, such as 2.5D and 3D stacking, assembles multiple smaller chips, or chiplets, into a single powerful component. Hyperscale data center operators and high-performance computing clients are rapidly adopting these solutions for better performance-per-watt. This trend is consolidating the value proposition away from raw transistor density toward system-level integration.
Heightened export controls on advanced semiconductor manufacturing equipment and chip designs are being implemented by governments, notably the United States. These restrictions aim to limit the technological advancement of strategic rivals and reconfigure global trade flows. Chinese technology firms are most affected, accelerating their efforts to develop a self-sufficient domestic semiconductor ecosystem.
Large-scale cloud providers and automotive OEMs are increasingly designing custom silicon to optimize for specific workloads and differentiate their products. This disintermediates traditional chip vendors, shifting procurement towards co-design partnerships with foundries. This move toward in-house development is most visible in the North American data center market.
Global Computer Microchip Market Segmentation
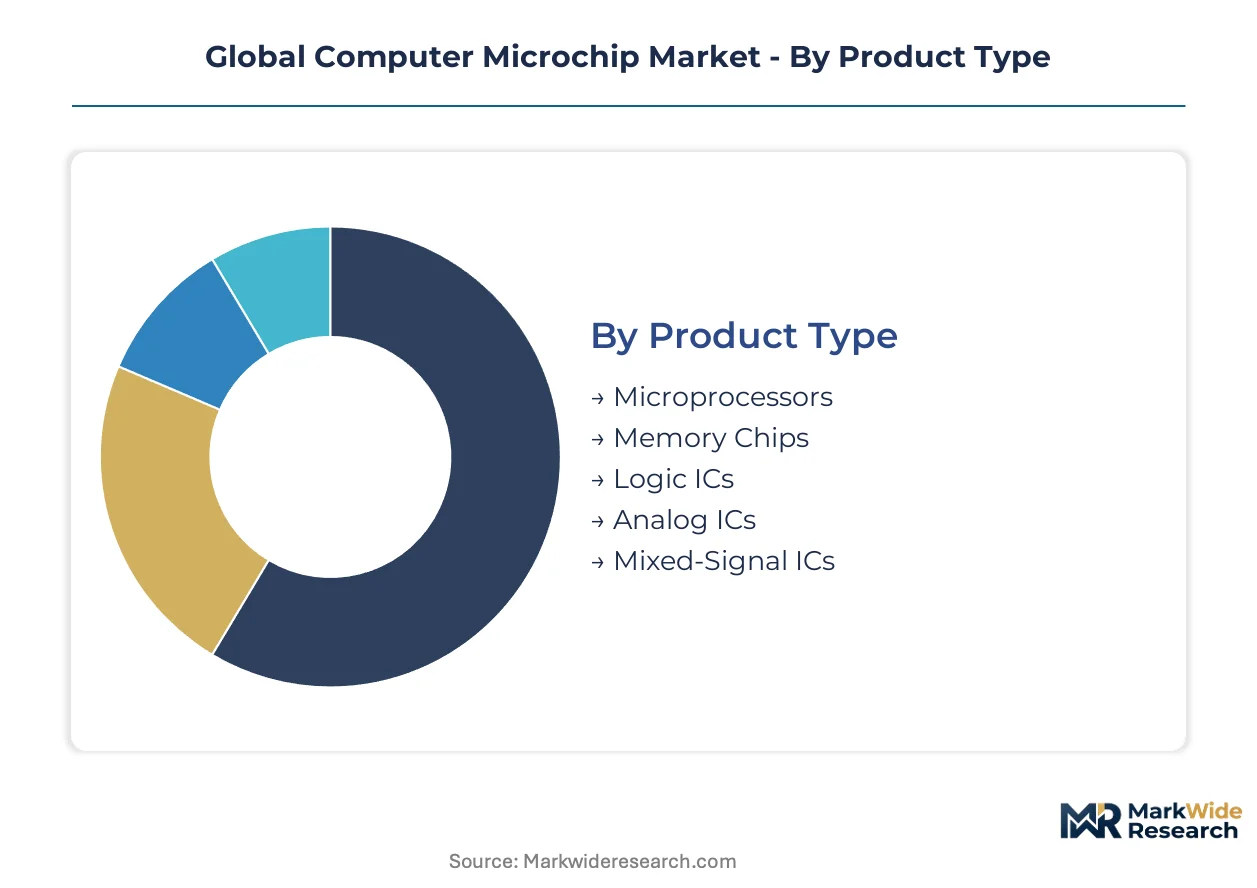
The global computer microchip market segments across diverse parameters, reflecting the specialized requirements of various industries and technological advancements. Understanding these distinctions is critical for market participants to tailor product development, optimize supply chains, and address specific customer needs across the vast microchip ecosystem.
Product Type:
Buyers in the computer microchip market differentiate their choices based on the fundamental function a chip performs within a system.
- Microprocessors:These complex integrated circuits execute instructions, performing arithmetic, logical, and control functions. Demand for high-performance microprocessors concentrates in data centers for artificial intelligence workloads and cloud computing infrastructure.
- Memory Chips:Devices designed to store data and program instructions, including DRAM and NAND flash. Consumer electronics, particularly smartphones and personal computers, drive significant volume demand for memory chips, though pricing remains cyclical.
- Logic ICs:Integrated circuits that implement digital logic functions, forming the building blocks of digital systems. These components are foundational across telecommunications equipment and industrial control systems.
- Analog ICs:Chips processing continuous signals, converting real-world inputs like temperature or sound into digital data. Automotive systems and power management solutions heavily rely on analog ICs.
- Mixed-Signal ICs:Integrated circuits combining both analog and digital functionalities on a single chip. These are essential for modern communication devices and advanced sensor applications.
Microprocessors lead volumes today; Logic ICs are gaining share fastest.
Technology:
Maturity and specialized performance needs dictate the technology choices for microchip fabrication.
- CMOS:Complementary Metal-Oxide-Semiconductor technology is the dominant process for fabricating integrated circuits due to its low power consumption and high integration density. Modern microprocessors and memory chips extensively utilize CMOS technology.
- GaAs:Gallium Arsenide technology offers superior high-frequency performance and optical properties compared to silicon, making it suitable for specialized applications. Telecommunications equipment, particularly 5G infrastructure and radar systems, leverage GaAs components.
- Bipolar:Bipolar junction transistor technology provides high current gain and faster switching speeds in certain applications. Power management circuits and radio frequency components still incorporate bipolar designs.
- BiCMOS:This technology combines the advantages of both bipolar and CMOS transistors on a single chip. BiCMOS is often used in analog-to-digital converters and high-speed communication interfaces.
- SOI:Silicon-on-Insulator technology reduces parasitic capacitance, leading to faster, lower-power chips. High-performance computing and automotive electronics benefit from SOI advancements.
The dominance of CMOS technology remains unchallenged, while specialized applications drive growth in GaAs and SOI.
Application:
The end-use application significantly influences both the volume and performance specifications required from computer microchips.
- Data Centers:These facilities require high-performance microprocessors, memory, and specialized logic chips to manage vast amounts of data and artificial intelligence workloads. Hyperscale cloud providers in North America are significant consumers of these advanced solutions.
- Consumer Electronics:This segment includes smartphones, laptops, and smart home devices, demanding high volumes of cost-effective and energy-efficient microchips. Memory chips and microcontrollers are critical components in this application area.
- Telecommunications Equipment:Microchips are vital for network infrastructure, including base stations, routers, and optical fiber systems. 5G deployment in China and Europe is accelerating demand for high-frequency and high-bandwidth chips.
- Aerospace Systems:High-reliability and radiation-hardened microchips are essential for avionics, satellite communications, and defense applications. Defense contractors in the United States and European Union procure specialized components for these systems.
- Industrial Automation:This application covers programmable logic controllers, robotics, and factory control systems, requiring robust and durable microchips. German and Japanese manufacturing sectors utilize these chips for advanced industrial processes.
High-performance computing in Data Centers drives significant revenue, while Consumer Electronics provides stable, high-volume demand.
End User:
The position of an entity within the semiconductor value chain directly shapes their procurement patterns for microchip products.
- OEMs:Original Equipment Manufacturers integrate microchips into their final products, such as computers, automobiles, and industrial machinery. These companies often engage in co-design partnerships with foundries to optimize custom silicon.
- Semiconductor Foundries:These facilities manufacture integrated circuits for fabless companies and other clients, requiring specialized process control and testing chips. Taiwan Semiconductor Manufacturing Company (TSMC) exemplifies a leading foundry player.
- Electronic Manufacturing Services:EMS providers assemble and test electronic components and systems for other companies. They procure microchips in bulk to fulfill contract manufacturing orders for various industries.
- Research Institutions:Universities and dedicated research centers conduct fundamental and applied research in microchip design and fabrication. They acquire specialized chips for experimental platforms and advanced material science studies.
- Defense Contractors:Companies supplying military and aerospace systems require highly reliable and often customized microchips. These contractors adhere to stringent security and performance specifications for critical national security applications.
OEMs represent the largest purchasing segment, with Research Institutions driving innovation in new chip architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global computer microchip market traces its foundational development and initial scaling to the United States, particularly through early innovations in semiconductor technology. This historical precedence continues to shape current manufacturing and research priorities across key regions. Geopolitical strategies now significantly influence the geographic distribution of advanced fabrication capabilities.
United States
High-performance computing for data centers and AI workloads drives significant demand for advanced microprocessors in the United States. The US CHIPS and Science Act provides substantial financial incentives for constructing new domestic semiconductor fabrication facilities. Silicon Valley and Austin, Texas, continue as critical hubs for chip design and advanced research.
Taiwan
Taiwan anchors the global supply of advanced logic chips, primarily due to its unparalleled foundry capabilities supporting numerous fabless companies. The country's industrial policy prioritizes maintaining its technological lead in leading-edge semiconductor manufacturing processes. Hsinchu Science Park remains the epicenter for advanced chip production and packaging innovation.
China
Telecommunications equipment and a growing domestic electronics sector fuel substantial microchip demand across China. China's dual carbon goals influence energy consumption standards for fabrication facilities, pushing for sustainable operations. Shanghai and Shenzhen serve as major centers for semiconductor design houses and emerging domestic foundries.
Germany
Industrial automation and the expanding automotive sector represent significant end-use applications for microchips within Germany. The European Chips Act aims to increase the EU's share of global semiconductor production, offering public funding for new facilities. Dresden has emerged as a prominent microelectronics cluster, attracting investment in advanced manufacturing.
South Korea
Memory chips for consumer electronics and advanced logic for mobile devices constitute core demand drivers in South Korea. The government actively supports domestic semiconductor research and development through various national initiatives. The Gyeonggi Province is a major hub for large-scale memory and foundry operations, including key industry players.
Global Computer Microchip Market Key Industry Players
Premium-margin players sit above commodity-margin players across the computer microchip market, primarily differentiated by their technological advancement and specialization. The market structure features a tiered landscape, encompassing integrated device manufacturers, pure-play foundries, and specialized fabless design companies. Key strategic archetypes include leading-edge logic producers, high-volume memory manufacturers, and critical equipment suppliers. Capacity expansion in advanced nodes and strategic partnerships for co-development represent dominant competitive moves.
Within the specialized foundry and integrated device manufacturer (IDM) segments, Taiwan Semiconductor Manufacturing Company (TSMC) exemplifies a pure-play foundry model, enabling numerous fabless companies with leading-edge process technology. Intel Corporation, a US-based IDM, defends its historical market share through advanced packaging and processor innovation, investing heavily in its own manufacturing capabilities. ASML Holding, a Netherlands-based equipment supplier, occupies a critical position by providing the essential Extreme Ultraviolet (EUV) lithography machines required for advanced chip manufacturing globally. These players collectively anchor the high-value end of the microchip ecosystem, influencing the pace of technological progress.
| Leading Market Players |
|---|
| Samsung Electronics |
| Qualcomm Incorporated |
| NVIDIA Corporation |
| Micron Technology |
| Intel Corporation |
| Taiwan Semiconductor Manufacturing Company (TSMC) |
| Advanced Micro Devices (AMD) |
| ASML Holding |
| Broadcom Inc. |
| Others |
Cost & Logistics Intelligence
Procurement is shifting towards co-design partnerships for custom silicon, forcing foundries to offer more integrated solutions. This influences pricing models to reflect specialized research and development and intellectual property contributions.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model for advanced microchips. Price differentiation stems from technological node advancement and the level of customization required for specific applications. Pricing softness reflects increased competition in mature nodes, particularly for memory chips in consumer electronics. Data center microprocessors exhibit lower price sensitivity due to their high-performance requirements.
Supply Chain Analysis
Access to critical Extreme Ultraviolet (EUV) lithography equipment rests on a single European company, creating a significant point of vulnerability. Geographic supply concentration centers in Taiwan, South Korea, and the United States for advanced logic and memory production. Silicon wafers and specialized photolithography chemicals represent key raw material dependencies. Direct sales from foundries to Original Equipment Manufacturers (OEMs) and fabless companies represent the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The computer microchip market presents geographic arbitrage opportunities due to divergent industrial policies, such as US CHIPS Act incentives versus European Chips Act funding for domestic manufacturing. This creates distinct cost structures and strategic advantages across regions.
For Market Incumbents: Deepen strategic partnerships with critical equipment suppliers like ASML Holding to secure access to advanced lithography. Invest in next-generation packaging technologies to defend market share against emerging chiplet designs. A global shortage of specialized workforce threatens new fab construction, requiring significant investment in talent development initiatives.
For New Entrants and Emerging Players: Electronic Manufacturing Services (EMS) providers offer a route for new entrants to access diverse end-use applications. Target specialized niches within automotive silicon content, leveraging modular chiplet designs for cost-effective high-performance computing. Focus on co-design partnerships with hyperscale data center operators to optimize custom silicon for specific workloads.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play foundries and advanced packaging specialists over the long term. These entities are critical enablers for the entire ecosystem, benefiting from sustained demand for leading-edge process technology. The signal to watch is the successful ramp-up of new fabrication facilities outside of established hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Nodes | Securing future supply for high-performance computing and artificial intelligence workloads is critical. |
| Strategic Partnership with Equipment Suppliers | Ensuring preferential access to scarce Extreme Ultraviolet (EUV) lithography machines maintains technological leadership. |
| Investment in Advanced Packaging | Enables heterogeneous integration, delivering performance gains beyond traditional silicon scaling for hyperscale data centers. |
| Workforce Development Programs | Addressing the specialized workforce scarcity is essential for timely construction and operation of new fabrication facilities. |
| Custom Silicon Co-design Agreements | Aligning with major Original Equipment Manufacturers (OEMs) and cloud providers captures high-margin, application-specific demand. |
Research Approach
Coverage spans the United States, Taiwan, China, Germany, and South Korea, with primary inputs from each region. Interviews included semiconductor design engineers, foundry operations managers, OEM procurement specialists, and government policy advisors. Secondary validation drew from national trade association reports, corporate financial disclosures, and technology-specific patent databases. Bottom-up and top-down triangulation ensured data consistency.
Rate-of-change decomposition isolated individual growth contributors across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and geographic region. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included data center expansion plans and EUV lithography adoption rates.
Revisions become necessary when significant shifts in governmental industrial policy or critical equipment supply occur. Forecasts reflect assumptions regarding technological progression and geopolitical stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Chiplets Market
Semiconductors
India Semiconductor Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Semiconductor Intellectual Property Market
Semiconductors
Semiconductor IP Market
Semiconductors
Compound Semiconductor Market