
 IV-IV Compound Semiconductor Market | 2026-2036
IV-IV Compound Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
IV-IV Compound Semiconductor Market Analysis
A capital-intensity divergence between established substrate manufacturers and fabless design houses is unwinding competitive stability in the IV-IV compound semiconductor space. Wolfspeed sustains the industry's deepest vertical integration from crystal growth through device fabrication, anchoring its position in silicon carbide substrates. Infineon Technologies AG leverages European automotive qualification standards to dominate module supply contracts with German OEMs. Coherent Corp. specializes in materials science breadth across compound semiconductor platforms, extending its reach beyond pure-play silicon carbide competitors.
IV-IV compound semiconductors encompass group-IV and IV-IV alloy materials—principally silicon carbide and germanium—engineered with bandgaps exceeding 2 eV for silicon carbide polytypes, enabling operation above 200°C junction temperatures where silicon devices fail. These materials serve critical functions in power conversion, radio-frequency transmission, and photonic detection across harsh environments. Silicon carbide power devices command the largest revenue pool within the product type taxonomy, while RF components built on gallium arsenide hybrid platforms represent the fastest-expanding application segment as 5G base station deployment intensifies. Crystal growth technology remains the most margin-concentrated manufacturing step, with chemical vapor deposition processes gaining share in epitaxial layer production for next-generation device architectures.
The U.S. Environmental Protection Agency tailpipe rules and the EU F-Gas Regulation jointly constrain legacy silicon powertrain designs, redirecting automotive procurement toward silicon carbide inverters. China's MIIT dual carbon goals and GB standards for new energy vehicle efficiency are compressing qualification timelines for domestic substrate suppliers. Japan's METI semiconductor revitalization framework and JIS standards for wide-bandgap materials are reinforcing quality benchmarks that shape export market access. Stakeholders must monitor how divergent subsidy structures across Washington, Brussels, and Beijing reshape the geographic distribution of captive wafer capacity versus merchant supply.
Market Dynamics
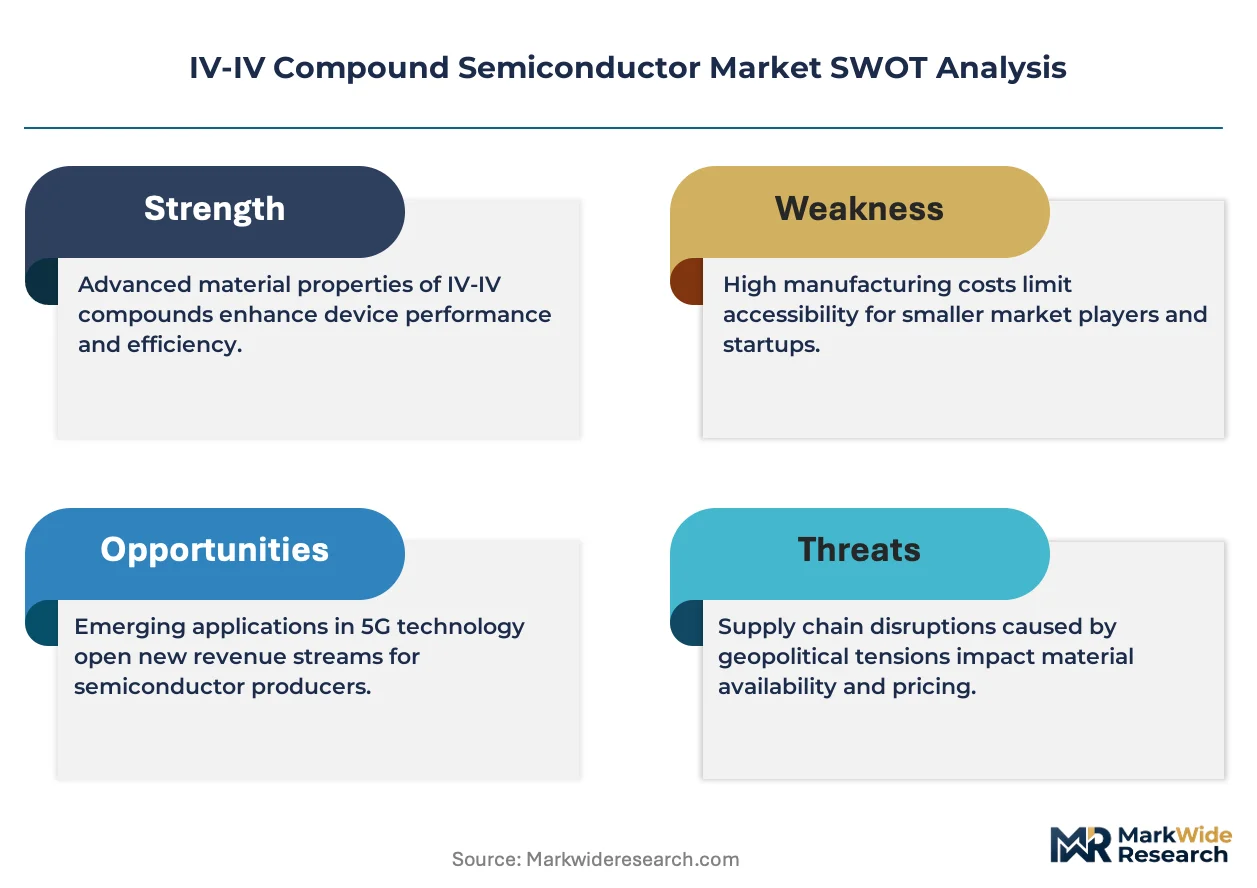
The migration of automotive powertrains to 800V architectures is compressing silicon carbide qualification timelines and redrawing supplier-buyer power balances across the IV-IV compound semiconductor value chain.
Growth Catalysts
- EPA Vehicle Emissions Standards:Tightened tailpipe rules in the United States are forcing automakers to abandon silicon inverters for silicon carbide alternatives that cut switching losses.
- China Electric Vehicle Output:Domestic new energy vehicle production scaling under MIIT dual carbon goals is absorbing record volumes of 6-inch silicon carbide substrates.
- Crystal Growth Automation:Advanced chemical vapor deposition processes are reducing defect density in epitaxial layers, expanding usable wafer yield for power module manufacturers.
Market Restraints
- Substrate Supply Concentration:Six-inch silicon carbide wafer production clusters heavily in China and the United States, exposing module makers to geographic disruption risk.
- High-Purity Graphite Input Costs:Crucible and susceptor materials for physical vapor transport growth face volatile pricing tied to petroleum coke markets.
- Silicon IGBT Persistence:Mature 650V silicon devices retain cost advantages in 400V battery systems, slowing penetration in economy vehicle segments.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor manufacturing are attracting substrate fabrication investments previously concentrated in East Asia.
- RF-GaN Convergence:Hybrid gallium nitride-on-silicon carbide platforms for 5G base stations are opening new revenue pools beyond pure-play power electronics.
- EU Green Deal Procurement Mandates:Public tender rules favoring wide-bandgap materials in rail and grid infrastructure are creating captive demand for European-qualified suppliers.
Industry Challenges
- Epitaxial Engineering Talent Scarcity:The specialized skill set for defect engineering in 4H-SiC crystal growth remains concentrated among a handful of experienced technologists.
- Automotive AEC-Q101 Certification Timelines:Extended qualification cycles for power discretes under JEDEC standards delay revenue recognition for new substrate entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV-IV Compound Semiconductor Market |
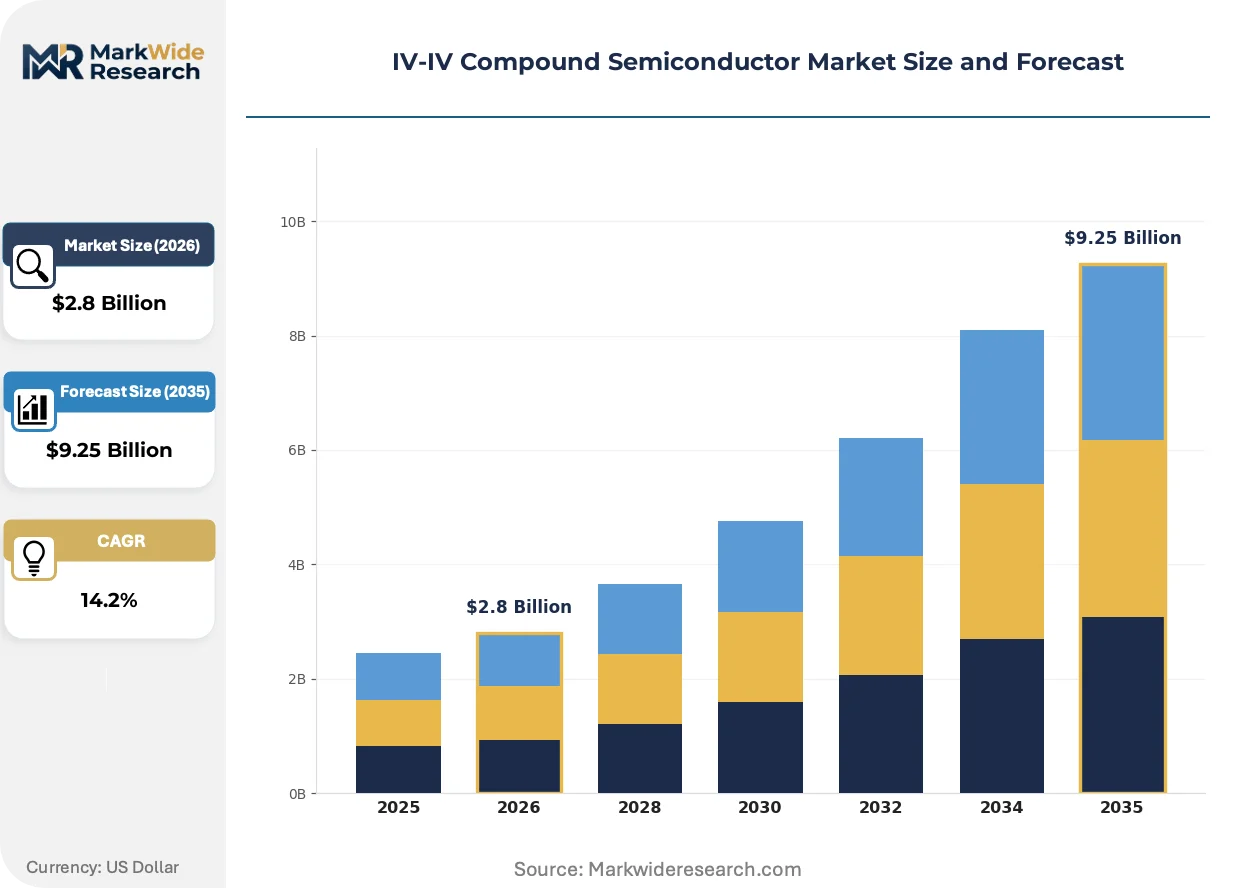
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Carbide, Germanium, Gallium Arsenide, Gallium Phosphide Technology: Crystal Growth, Molecular Beam Epitaxy, Chemical Vapor Deposition, Hybrid Technology End User: Telecommunications, Automotive, Aerospace, Consumer Electronics Application: LEDs, Power Devices, RF Components, Photodetectors |
| Companies Covered | Wolfspeed, Inc., Infineon Technologies AG, Skyworks Solutions, Inc., Qorvo, Inc., STMicroelectronics N.V., Texas Instruments Incorporated, Coherent Corp., Navitas Semiconductor, onsemi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV-IV Compound Semiconductor Market Emerging Trajectories
Device architectures are compressing thermal management requirements while regulatory mandates accelerate material substitution timelines across transportation and energy infrastructure.
Silicon carbide MOSFETs with trench gate designs are cutting specific on-resistance below 2 mΩ·cm². Electric vehicle inverter manufacturers in Germany and South Korea are qualifying these devices for 800V platforms launching in 2025-2026 model years. The technology is miniaturizing thermal management systems, reducing heat sink mass by 40% versus planar silicon IGBT modules.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in power electronics cooling systems. This constraint is redirecting thermal design toward direct liquid cooling and phase-change materials compatible with wide-bandgap junction temperatures. Automotive module suppliers serving European OEMs are redesigning packaging to eliminate refrigerant-dependent heat pumps.
Long-term supply agreements are displacing spot market purchasing for 6-inch substrates. Tier-1 automotive suppliers in Japan and Germany are securing 3-5 year offtake contracts directly with crystal growers, bypassing traditional distributor channels. This pattern concentrates procurement leverage among vehicle manufacturers with volume visibility above 500,000 units annually.
IV-IV Compound Semiconductor Market Segmentation
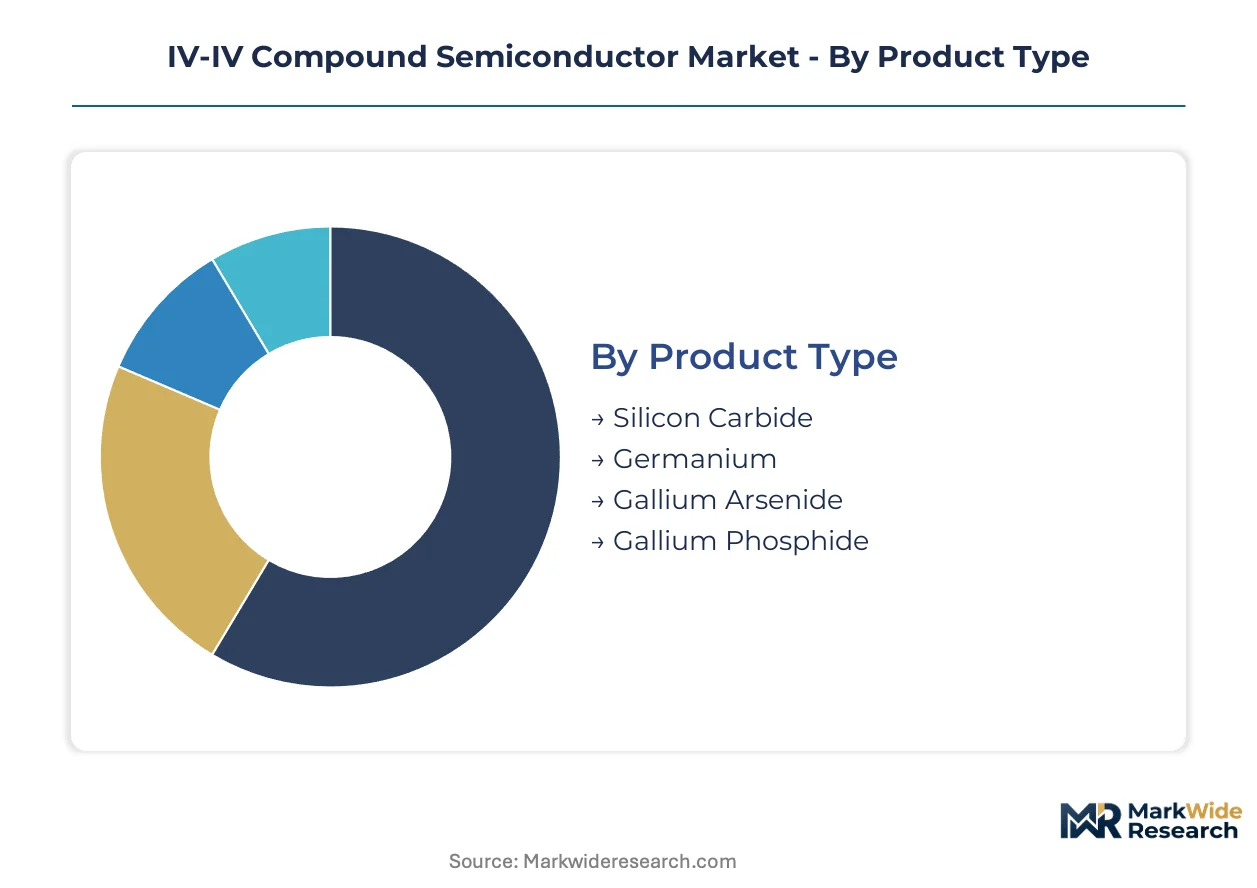
Segmentation in IV-IV compound semiconductors reveals how material properties, fabrication methods, and end-use requirements partition value creation across the value chain. Each dimension carries distinct geographic footprints and margin structures that shape supplier strategy.
Product Type:
Silicon carbide substrates flow predominantly to domestic electric vehicle supply chains in China and export-oriented automotive module manufacturers in Germany. Germanium and gallium arsenide segments serve more dispersed telecommunications and defense applications across multiple continents.
- Silicon Carbide:Polytype 4H-SiC dominates power electronics with bandgaps exceeding 3 eV, enabling junction temperatures above 175°C. Chinese wafer fabs under MIIT dual carbon goals are absorbing six-inch substrates for domestic inverter production, while Wolfspeed's North Carolina crystal growth supplies German and South Korean automotive qualification pipelines.
- Germanium:Narrow 0.67 eV direct bandgap suits infrared photodetection and high-mobility transistor channels. Defense procurement in the United States and satellite manufacturers in Japan sustain demand despite limited commercial scaling, constrained by germanium tetrachloride precursor availability.
- Gallium Arsenide:Direct bandgap of 1.42 eV powers high-frequency RF amplification and optoelectronic conversion. 5G base station deployment in South Korea and millimeter-wave radar in German automotive platforms concentrate uptake.
- Gallium Phosphide:Indirect 2.26 eV bandgap limits applications to visible LEDs and optical isolators. Niche demand from industrial lighting manufacturers in Japan and medical equipment producers in Switzerland defines its commercial footprint.
Silicon carbide commands the established base. The steepest expansion runs through gallium arsenide hybrid platforms.
Technology:
Cost tiers separate mature physical vapor transport methods from capital-intensive epitaxial deposition systems. Volume scale distinguishes automotive substrate qualification from aerospace lot production.
- Crystal Growth:Physical vapor transport at 2,200°C produces boules sliced into substrates, with defect engineering determining usable yield. Chinese manufacturers scaling six-inch production and Wolfspeed's eight-inch development pipeline in New York represent competing volume trajectories.
- Chemical Vapor Deposition:Epitaxial layer deposition at 1,600°C builds device-quality films on substrates, with in-situ doping control enabling trench MOSFET architectures. Infineon's Dresden facility and Showa Denko's Chiba plant anchor European and Japanese supply for automotive qualification.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition achieves atomic-layer precision for RF heterostructures, limiting throughput to research and defense volumes. U.S. Department of Defense trusted foundry requirements constrain commercial scaling.
- Hybrid Technology:GaN-on-SiC epitaxy combines wide-bandgap benefits with established gallium nitride device processing. 5G infrastructure tenders in South Korea and radar module contracts in the United States concentrate demand for this convergence platform.
Crystal growth absorbs the majority of capital deployment. Chemical vapor deposition is climbing the fastest as device architectures demand thicker, lower-defect epitaxial stacks.
End User:
Customer type stratification separates price-sensitive consumer volumes from qualification-intensive automotive and aerospace procurement.
- Automotive:800V inverter platforms require AEC-Q101 certified discretes with decade-long reliability data. German OEM qualification timelines and Chinese domestic supplier substitution under MIIT guidelines reshape sourcing patterns.
- Telecommunications:5G base station deployment and fiber optic infrastructure sustain gallium arsenide and indium phosphide demand. South Korean network equipment manufacturers and Chinese state-owned carriers concentrate procurement leverage.
- Aerospace:Radiation-hardened requirements and extreme temperature cycling specifications limit qualified suppliers. NASA Artemis program specifications and European Space Agency component qualification define addressable market boundaries.
- Consumer Electronics:Fast-charging adapters and premium audio amplifiers absorb silicon carbide diodes and germanium transistors. Cost pressure from Chinese original design manufacturers constrains margin expansion.
Automotive procurement commands qualification premiums and long-term contract structures. Telecommunications is gaining share fastest as base station deployment accelerates.
Application:
Margin concentration varies sharply between commodity LED volumes and specialized power device qualification.
- Power Devices:MOSFETs and Schottky diodes convert battery DC to motor AC with switching losses below silicon IGBT benchmarks. German electric vehicle platforms and Chinese bus electrification programs concentrate demand for 1,200V-rated components.
- RF Components:Power amplifiers and low-noise amplifiers enable millimeter-wave transmission and radar sensing. 5G macro base stations in South Korea and automotive radar in German premium vehicles drive frequency specification evolution.
- LEDs:Solid-state lighting and display backlighting consume gallium phosphide and gallium arsenide substrates. Chinese packaging houses dominate downstream assembly, compressing upstream margin capture.
- Photodetectors:Infrared sensors and optical receivers serve defense, medical imaging, and telecommunications test equipment. Japanese industrial automation and U.S. night vision programs sustain specialized demand.
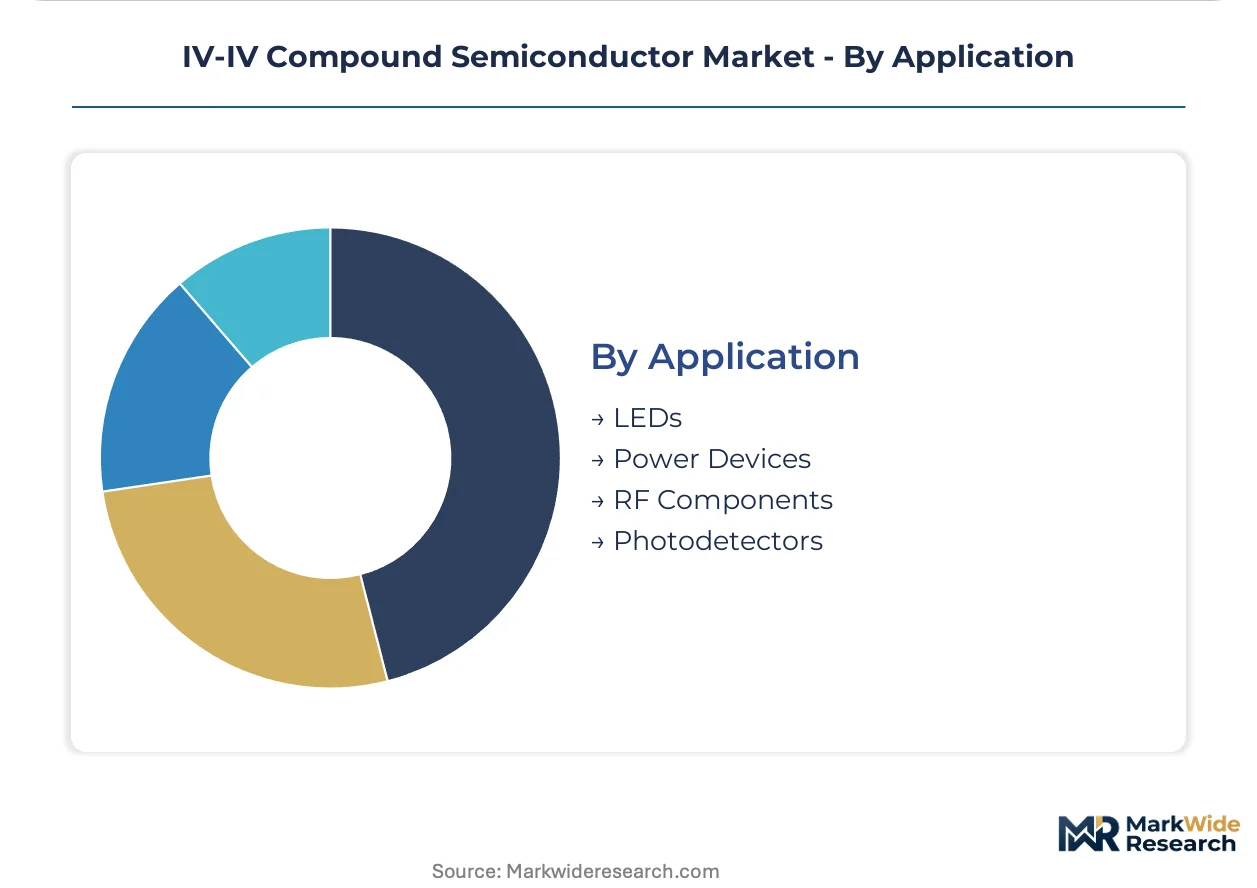
Power devices anchor revenue concentration through automotive electrification. RF components are expanding most quickly as 5G and radar applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany absorb silicon carbide substrates at qualification premiums, while Indian and Brazilian procurement remains price-elastic due to nascent electric vehicle penetration and import dependency. This demand-elasticity contrast is compressing margin capture for merchant suppliers serving cost-sensitive emerging markets.
United States
The EPA tailpipe rules and IRA clean vehicle credits are accelerating silicon carbide inverter adoption across Detroit Three electrification programs. Wolfspeed's Mohawk Valley fab in New York anchors domestic 200mm substrate production for automotive qualification pipelines serving German and South Korean OEMs.
China
Domestic new energy vehicle output under MIIT dual carbon goals is absorbing record six-inch silicon carbide volumes from Shanxi and Hunan crystal growth clusters. BYD and NIO are qualifying local substrate suppliers under compressed GB standards timelines, reducing import dependency for 800V platform components.
Germany
The EU Green Deal procurement mandates and KBA type-approval requirements are concentrating silicon carbide module demand among Bavarian and Baden-Württemberg automotive suppliers. Infineon's Dresden epitaxial facility supplies AEC-Q101 certified stacks for domestic OEM 800V inverter platforms launching through 2026.
Japan
METI semiconductor revitalization frameworks and JIS wide-bandgap material standards are reinforcing quality benchmarks for export market access. Showa Denko's Chiba chemical vapor deposition plant anchors epitaxial supply for Toyota and Honda electrification programs targeting North American markets.
South Korea
5G base station deployment under MSIT spectrum allocation and automotive radar qualification for Hyundai-Kia platforms are driving gallium arsenide and silicon carbide uptake. Samsung's Pyeongtaek compound semiconductor cluster is expanding epitaxial capacity for domestic RF and power device fabrication.
IV-IV Compound Semiconductor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the IV-IV compound semiconductor space. Crystal growth capabilities and automotive qualification credentials separate the upper tier from fabless design houses and merchant epitaxial suppliers. Three archetypes dominate: vertically integrated substrate-to-device manufacturers, European automotive-qualified module specialists, and materials science platforms spanning multiple compound semiconductor chemistries. Capacity expansion and strategic partnerships represent the dominant competitive moves, with long-term offtake agreements displacing spot market purchasing.
Within the integrated leader tier, Wolfspeed, Inc. exemplifies backward integration from crystal growth through device fabrication, while Infineon Technologies AG occupies a position as the European automotive qualification anchor. Coherent Corp. sits within the materials science platform archetype, extending reach across compound semiconductor substrates beyond pure-play silicon carbide competitors.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Infineon Technologies AG |
| Skyworks Solutions, Inc. |
| Qorvo, Inc. |
| STMicroelectronics N.V. |
| Texas Instruments Incorporated |
| Coherent Corp. |
| Navitas Semiconductor |
| onsemi |
| Others |
Supply Flow & Price Mechanics
Eight-inch wafer scale economies at Wolfspeed's Mohawk Valley fab are compressing unit costs for silicon carbide substrates while simultaneously concentrating pricing power among crystal growth specialists with captive automotive qualification pipelines. This scale-driven consolidation is elevating price floors for six-inch merchant supply as Chinese domestic absorption tightens spot availability.
Pricing Analysis
After-sales service bundling and long-term reliability warranties drive lifetime value capture for AEC-Q101 certified substrate suppliers serving German and Japanese automotive OEMs. Contract-based long-term offtake agreements dominate pricing structures, with volume scale and certification tier as primary price differentiation drivers. Cost compression in six-inch merchant substrates is intensifying as Chinese wafer fabs expand captive capacity under MIIT dual carbon goals. Economy vehicle segments exhibit highest price sensitivity, while 800V platform suppliers accept qualification premiums.
Supply Chain Analysis
High-purity graphite crucible supply from petroleum coke refineries in the United States and China underwrites physical vapor transport crystal growth capacity for silicon carbide substrate production. Raw material dependencies include graphite susceptors, silicon carbide source powder, and ultra-high purity argon gas. Single-source vulnerability concentrates in six-inch wafer finishing equipment anchored in Japanese and German precision manufacturing. Distribution runs through direct OEM contracts bypassing traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as 800V architecture migration splinters procurement requirements across multiple qualification tiers and geographic supply clusters. Divergent EPA, EU Green Deal, and MIIT regulatory timelines are creating distinct demand niches for substrate suppliers with regional certification expertise.
For Market Incumbents: Compound defensive positioning by securing decade-long reliability data packages for AEC-Q101 certification and adding captive epitaxial capacity in Dresden or Chiba to defend against emerging Chinese substrate entrants. Wolfspeed's backward integration into eight-inch crystal growth and Infineon's module qualification leverage with German OEMs represent referenceable consolidation templates. For New Entrants and Emerging Players: Anchor in India's PLI scheme substrate fabrication incentives and RF-GaN convergence opportunities for 5G base station hybrid platforms, the most penetrable white-space segment outside automotive qualification barriers. A design-house-plus-foundry partnership model with established epitaxial suppliers accelerates time-to-revenue without crystal growth capital burden. For Investors and Strategic Acquirers: Merchant epitaxial specialists with automotive qualification credentials and established chemical vapor deposition capacity represent the highest-conviction acquisition target archetype for long-term viability across the electrification transition. Monitor JEDEC standard revision timelines and EPA rule implementation pace as inflection indicators for substrate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Secures volume visibility above 500,000 units annually for German OEM 800V platforms. |
| Backward Integration into Crystal Growth | Wolfspeed's Mohawk Valley fab anchors domestic 200mm substrate supply for automotive qualification. |
| Automotive Certification Investment | AEC-Q101 qualification under JEDEC standards unlocks decade-long reliability premiums from Japanese OEMs. |
| Geographic Manufacturing Footprint | Dresden and Chiba epitaxial facilities supply European and Asian automotive module pipelines. |
| Technology Licensing | GaN-on-SiC hybrid platform licensing opens 5G infrastructure revenue beyond pure-play power electronics. |
Methodological Framework
Operator-level perspectives from substrate crystal growth engineers, automotive power module procurement leads, epitaxial process technologists, and wide-bandgap materials R&D directors anchored the qualitative base for this analysis. Primary interview insights triangulated against secondary validation from SEC 10-K filings, MIIT dual carbon policy documents, EPA tailpipe rule regulatory filings, and JEDEC standard development records. Bottom-up wafer capacity modeling and top-down automotive electrification demand forecasting converged on segment-level projections.
Sensitivity analysis across automotive adoption scenarios, Chinese domestic supply substitution rates, and eight-inch wafer yield trajectories shaped the forecast framework. Segmentation dimensions modeled include polytype specification, crystal growth technology, epitaxial deposition method, end-user qualification tier, and regional regulatory cluster. CAGRs derived from volume-price elasticity functions calibrated to historical silicon carbide penetration patterns in rail and renewable energy applications.
Material uncertainties — EPA rule litigation outcomes, EU F-Gas Regulation phase-down pace, and MIIT subsidy renewal decisions — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as automotive platform voltage architectures and graphite supply cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Semiconductor Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Compound Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Semiconductor Target Market