
 Global Organic Semiconductor Market | 2026-2036
Global Organic Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Semiconductor Market Intelligence
Expertise in polymer chemistry and materials science is bifurcating the competitive landscape. Chemical giants like BASF SE leverage deep R&D in novel organic materials. Technology firms such as Universal Display Corporation specialize in phosphorescent OLED intellectual property, licensing key patents to display manufacturers. LG Chem Ltd. operates across the value chain from material synthesis to panel production.
Organic semiconductors are carbon-based compounds that exhibit semiconductor properties, often featuring pi-conjugated systems allowing charge transport. Their primary commercial purpose is enabling the fabrication of flexible, lightweight, and transparent electronic devices. OLED displays for consumer electronics constitute the largest device application segment. In terms of material type, small molecules are critical for high-performance displays, while polymers are gaining traction in emerging organic photovoltaics.
Compliance with chemical regulations like the EU's REACH and the US EPA's Toxic Substances Control Act (TSCA) governs material synthesis and market entry. ISO standards for electronic component reliability are also critical for adoption in demanding applications. Stakeholder success will hinge on navigating complex material intellectual property landscapes while scaling up cost-effective manufacturing processes.
Market Dynamics
The central dynamic in the organic semiconductor market is the performance-cost tension between specialized small molecules for high-end displays and scalable polymers for emerging flexible electronics. This bifurcation is driven by intense demand from consumer electronics for better, thinner screens.
Growth Catalysts
- OLED Display Proliferation:The integration of OLED technology into premium smartphones, televisions, and wearables, particularly by manufacturers in South Korea and China, serves as the primary demand engine for high-purity organic materials.
- Roll-to-Roll Manufacturing:Advances in solution-based and vapor-deposition roll-to-roll processing are enabling cost-effective, high-throughput production of large-area flexible devices like organic photovoltaics and lighting panels.
- Government Electronics Initiatives:National strategies, such as India's PLI scheme for electronics manufacturing, stimulate domestic production of components, creating new geographic demand pockets for semiconductor materials.
Market Restraints
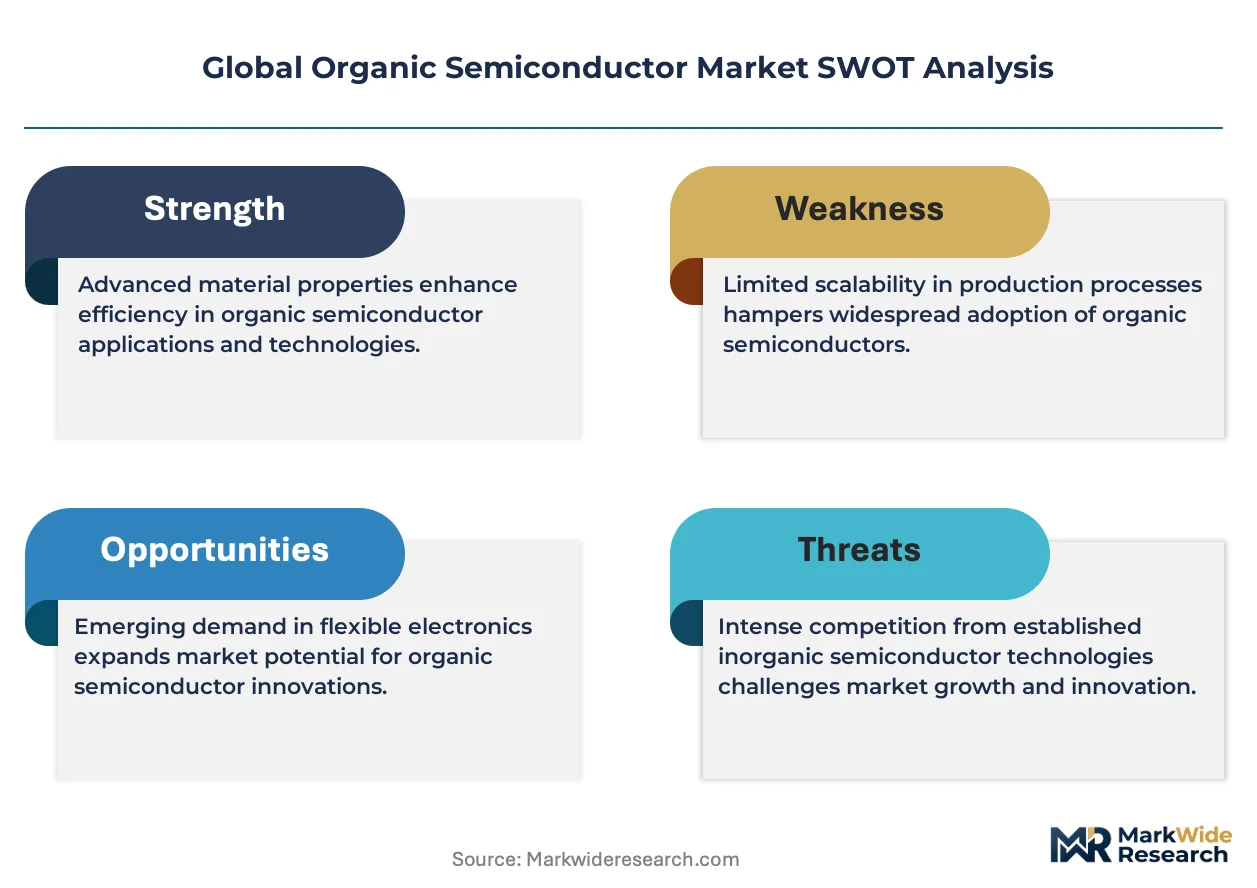
- Performance and Stability Limits:Compared to silicon, organic materials exhibit lower charge carrier mobility and are more susceptible to degradation from oxygen and moisture, limiting their operational lifetime and use in high-frequency logic circuits.
- High Material Purification Costs:Achieving the ultra-high purity required for efficient and stable OLED devices involves complex, multi-step synthesis and sublimation processes, which elevates the cost of key emissive and transport layer materials.
- Substitution by Inorganic Alternatives:The development of competing technologies like MicroLEDs and quantum dot films presents a long-term substitution threat, particularly in the high-end display segment where performance is paramount.
Strategic Opportunities
- Organic Photovoltaics (OPV):The push for renewable energy sources creates an opportunity for lightweight, flexible, and semi-transparent solar cells integrated into buildings (BIPV), automotive surfaces, and portable power generation applications.
- Flexible and Wearable Sensors:Underpenetrated applications in healthcare and the Internet of Things (IoT) offer significant growth potential for organic-based biosensors, pressure sensors, and photodetectors in wearable health monitors and smart textiles.
- Printable Electronics:The convergence of functional inks and high-resolution printing technologies enables the fabrication of low-cost electronic circuits, RFID tags, and smart packaging on flexible substrates like plastic and paper.
Industry Challenges
- Intellectual Property Complexity:A dense and overlapping patent landscape, especially concerning phosphorescent emitter materials and device architectures, creates significant licensing hurdles and litigation risks for new market entrants.
- Manufacturing Process Scalability:Transitioning novel materials from laboratory-scale synthesis to consistent, high-volume industrial production with tight quality control remains a significant engineering and capital investment challenge.
- Lack of Material Standardization:The absence of universally accepted standards for measuring and reporting material purity, device efficiency, and operational lifetime complicates material selection and comparability for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Semiconductor Market |
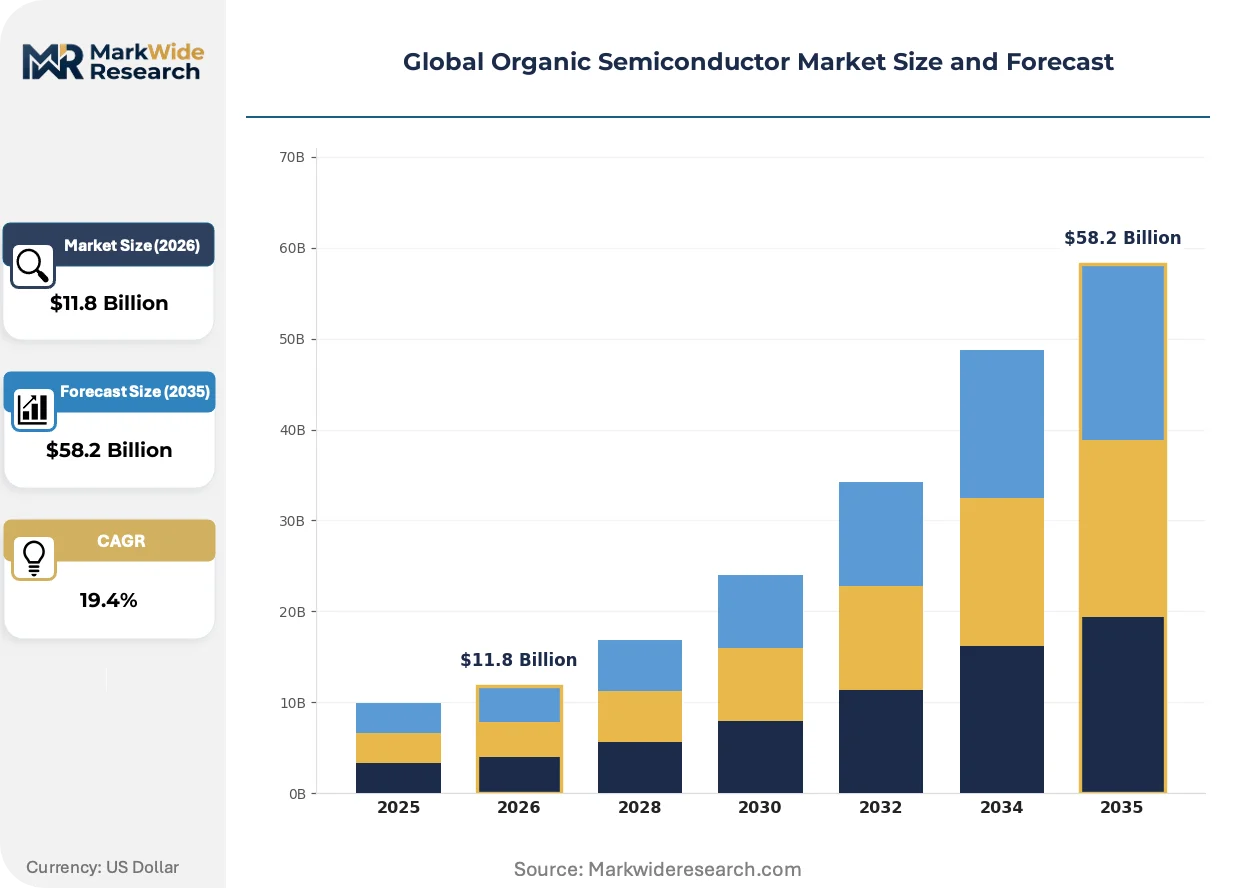
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $58.2 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polymer, Small Molecule, Dendrimer, Oligomer, Biopolymer Device Application: OLED Displays, Organic Photovoltaics, Organic Field Effect Transistors, Organic Sensors, Organic Light Emitting Transistors Manufacturing Technology: Vacuum Thermal Evaporation, Spin Coating, Inkjet Printing, Roll-to-Roll Processing, Spray Coating End User Industry: Consumer Electronics, Renewable Energy, Biotechnology, Telecommunications, Lighting |
| Companies Covered | BASF SE, Merck KGaA, DuPont de Nemours, Inc., Heliatek GmbH, Cambridge Display Technology Ltd., LG Chem Ltd., Universal Display Corporation, Samsung Electronics, AU Optronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Semiconductor Market Strategic Shifts & Innovations
Material development is cleaving into two distinct pathways. One path pursues incremental performance gains in complex small molecules for premium displays, while the other focuses on cost-effective, solution-processable polymers to unlock new applications in flexible electronics and sensors.
Thermally activated delayed fluorescence (TADF) materials are emerging as next-generation emitters for OLEDs. Display manufacturers are adopting these metal-free compounds to create highly efficient blue and green pixels without relying on expensive and supply-constrained iridium-based phosphors. This material innovation is miniaturizing the emissive layer stack within OLED devices, enabling thinner and more power-efficient panel designs.
The European Union's REACH regulation imposes stringent requirements on the chemical industry. It mandates comprehensive safety data and registration for all chemical substances manufactured or imported into the EU, including novel organic semiconductor compounds. This directly affects material developers, who must invest in extensive toxicological testing and documentation to gain or maintain market access in a critical geography.
A shift from transactional component sales to collaborative co-development is altering supply chain relationships. This model is most visible in the display sector, where panel producers in South Korea partner directly with chemical firms to design bespoke organic materials optimized for specific product roadmaps, such as foldable or transparent screens. This displaces the traditional arm's-length procurement of off-the-shelf materials.
Global Organic Semiconductor Market Segmentation
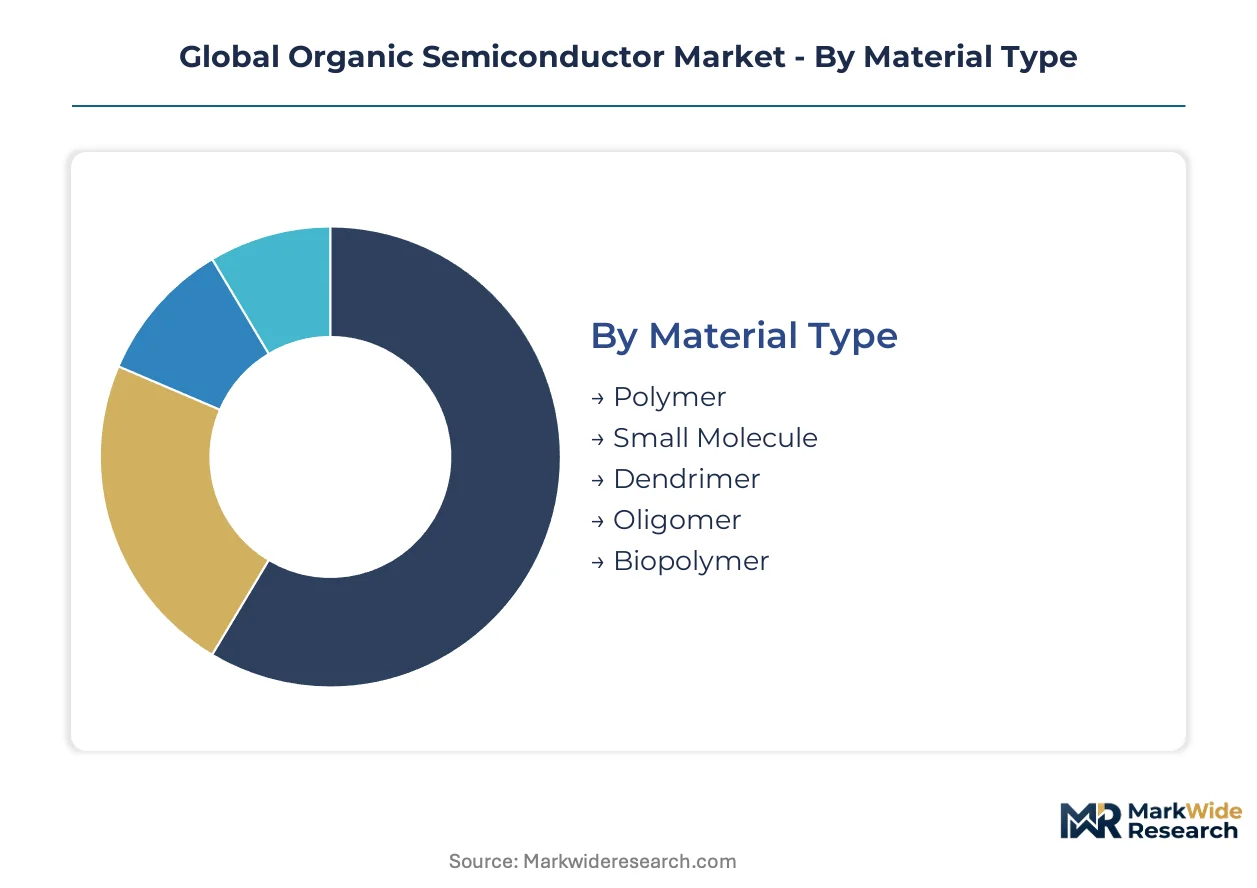
The Global Organic Semiconductor Market segmentation reveals the diverse material foundations and application landscapes driving innovation. Understanding these distinct market segments is essential for stakeholders to identify areas of concentrated value and strategic investment. This granular view clarifies the performance-cost trade-offs inherent in various organic semiconductor technologies.
Material Type:
Margin pools within organic semiconductor materials often concentrate in specialized, high-purity compounds critical for premium display performance.
- Small Molecule:These carbon-based compounds possess precise molecular structures, offering high charge carrier mobility and luminous efficiency. Demand concentrates heavily in OLED displays for consumer electronics, driven by the need for vibrant colors and energy efficiency.
- Polymer:Long-chain macromolecules provide mechanical flexibility and solution processability, enabling cost-effective, large-area fabrication. Demand gains traction in flexible electronics, such as organic photovoltaics and wearable sensors, due to their ease of integration.
- Dendrimer:Highly branched, tree-like macromolecules offer tunable electronic properties, explored for advanced light-emitting and sensing applications.
- Oligomer:Intermediate-sized molecules balance processability and performance for various organic electronic devices.
- Biopolymer:Naturally derived polymers like cellulose are investigated for sustainable and biocompatible electronic components, targeting medical and environmental sensors.
The dominant share belongs to Small Molecule compounds, while Polymer materials are expanding most quickly.
Device Application:
Device applications define the functional output of organic semiconductors, ranging from consumer-facing screens to specialized sensing platforms.
- OLED Displays:These self-emissive devices utilize organic materials to produce light, offering superior contrast, wide viewing angles, and flexibility. Demand concentrates in premium smartphones, televisions, and wearables, driven by consumer preference for high-quality visual experiences.
- Organic Photovoltaics:Flexible, lightweight solar cells convert light into electricity using organic semiconductor materials, enabling integration into non-traditional surfaces. The push for renewable energy sources creates demand for building-integrated and portable power generation.
- Organic Field Effect Transistors:These fundamental switching components are crucial for flexible circuits, smart cards, and large-area electronics due to low-cost fabrication potential.
- Organic Sensors:Organic materials enable highly sensitive and flexible sensors for healthcare monitoring, environmental detection, and IoT applications.
- Organic Light Emitting Transistors:These devices combine light emission and transistor functionality, offering potential for simplified display architectures and novel optoelectronic circuits.
OLED Displays command the largest volume, while Organic Photovoltaics attract substantial R&D for future energy solutions.
Manufacturing Technology:
Manufacturing technologies dictate the scalability, cost-efficiency, and device architecture capabilities for organic semiconductor production.
- Vacuum Thermal Evaporation:This high-precision method deposits ultra-thin organic layers in a vacuum, ensuring high purity and uniform films. It is critical for manufacturing high-performance OLED displays, where material integrity impacts device lifespan.
- Roll-to-Roll Processing:A continuous, high-throughput method processes flexible substrates from a roll, significantly reducing manufacturing costs for large-area devices. This technology is vital for cost-effective production of organic photovoltaics and flexible lighting.
- Spin Coating:A solution-based technique applies thin films by rotating a substrate, commonly used for laboratory-scale development and small-batch production.
- Inkjet Printing:A digital, additive manufacturing technique deposits precise patterns of organic inks, enabling flexible circuits and customized device designs.
- Spray Coating:This method applies organic solutions over large or complex surfaces, offering a scalable and versatile approach for fabricating various organic electronic layers.
Vacuum Thermal Evaporation remains the benchmark for high-end displays, while Roll-to-Roll Processing unlocks new frontiers in flexible electronics.
End User Industry:
End-user industries define the ultimate demand for organic semiconductor products, dictating performance requirements and market volume.
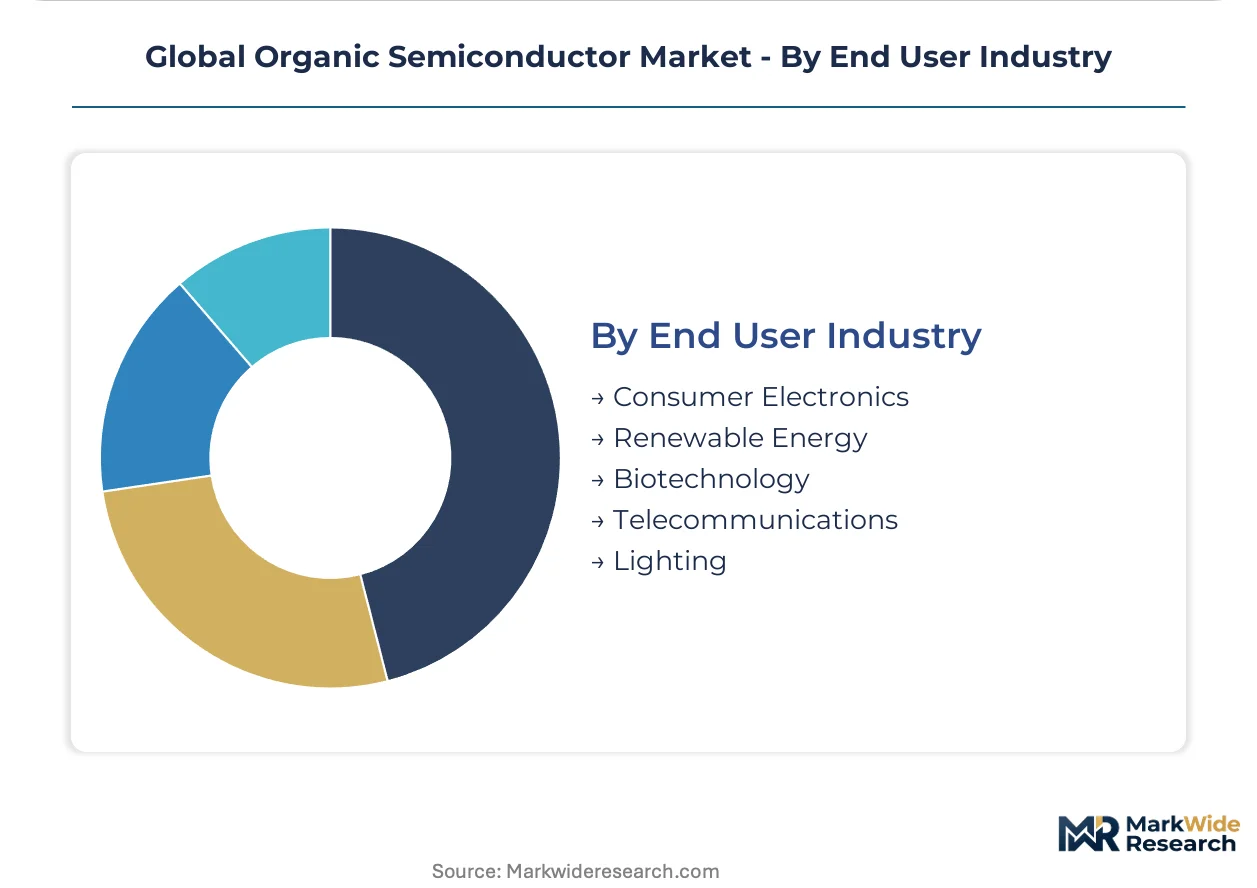
- Consumer Electronics:This sector integrates organic semiconductors into devices like smartphones, smartwatches, and high-definition televisions, leveraging OLED technology for superior visual quality. Demand is driven by continuous innovation in display performance and proliferation of portable smart devices.
- Renewable Energy:The industry utilizes organic photovoltaics for flexible and lightweight solar cells, enabling diverse applications from building-integrated solar to portable charging solutions. The global push for sustainable power generation propels demand in this sector.
- Biotechnology:Organic semiconductors facilitate advanced biosensors, flexible medical implants, and diagnostic tools, enhancing healthcare monitoring and research.
- Telecommunications:Organic materials are explored for high-speed data transmission, flexible antennas, and next-generation optical communication devices.
- Lighting:Organic light-emitting diodes offer energy-efficient and diffuse light sources for general illumination and specialized architectural lighting.
Consumer Electronics represents the largest end-user segment, while Renewable Energy is poised for substantial future expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry characterizes the global organic semiconductor market. Material suppliers in Europe and North America often command higher prices due to specialized intellectual property and complex purification processes. Conversely, display manufacturers in East Asia drive high-volume demand, negotiating for cost efficiencies.
South Korea
South Korean manufacturers continuously demand high-performance OLED materials for premium displays. The country's Ministry of Trade, Industry and Energy supports display technology development through various programs. Cities like Paju and Cheonan host major display panel fabrication plants, fostering advanced material integration.
China
Chinese electronics manufacturers seek cost-effective organic materials for expanding consumer electronics production. The national PLI scheme for electronics manufacturing stimulates domestic component production. Industrial hubs in Guangdong and Jiangsu provinces are rapidly scaling OLED panel manufacturing capabilities.
United States
Demand in the United States stems from intellectual property licensing and specialized material development for advanced applications. The US EPA's Toxic Substances Control Act (TSCA) governs new chemical substance introductions. Silicon Valley and research institutions in California drive innovation in organic semiconductor research and commercialization.
Germany
Germany's chemical industry provides foundational organic materials and advanced research for the sector. The EU's REACH regulation ensures stringent safety and environmental compliance for chemical substances. Research clusters in cities like Leverkusen and Darmstadt focus on novel polymer chemistry and material synthesis.
Japan
Japanese companies contribute significantly through material science expertise and advanced manufacturing equipment. METI initiatives often support R&D in next-generation electronic materials. Osaka and Kanagawa prefectures host key chemical and electronics firms, advancing organic material purity and processing.
Global Organic Semiconductor Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the organic semiconductor market. The competitive landscape bifurcates between specialized material developers and high-volume display manufacturers. Strategic archetypes include chemical giants focused on R&D, intellectual property licensors, and vertically integrated producers. Dominant competitive moves involve navigating complex intellectual property landscapes and scaling cost-effective manufacturing processes.
Chemical giants like BASF SE exemplify material innovation, anchoring the supply of novel organic compounds essential for high-performance devices. These entities often focus on fundamental research and complex synthesis. Universal Display Corporation represents a key intellectual property licensor, specializing in phosphorescent OLED technologies and enabling display manufacturers globally through patent portfolios. LG Chem Ltd. sits within the vertically integrated segment, covering the entire value chain from advanced material synthesis through to final panel production. These diverse firms collectively shape the material and technology trajectory of the organic semiconductor industry.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| DuPont de Nemours, Inc. |
| Heliatek GmbH |
| Cambridge Display Technology Ltd. |
| LG Chem Ltd. |
| Universal Display Corporation |
| Samsung Electronics |
| AU Optronics Corporation |
| Others |
Cost & Logistics Intelligence
The EU's REACH regulation gates supply qualification and price differentiation across the organic semiconductor market. This comprehensive chemical safety framework mandates extensive testing and documentation for materials, directly influencing market entry costs and the premium associated with compliant, high-purity compounds.
Pricing Analysis
Pricing for organic semiconductor materials exhibits a distinct geographic spread, with specialized compounds commanding higher prices in Europe and North America due to stringent regulatory compliance and advanced R&D. The dominant pricing model involves contract-based long-term offtake agreements for high-volume display materials. Price differentiation drivers include material purity grade and the intellectual property licensed for specific performance characteristics. Pricing softness emerges for commodity-like polymer materials due to increased production scale. High-end display manufacturers exhibit lower price sensitivity for critical small molecules, while emerging flexible electronics applications are highly price-sensitive.
Supply Chain Analysis
Inventory strategies in the organic semiconductor market lean towards just-in-time delivery for high-purity small molecules, reflecting their high cost and limited shelf life. Geographic supply concentration centers in Germany, Japan, and South Korea, key hubs for advanced material synthesis and purification. Raw material dependencies include specialized precursor chemicals and high-purity solvents. A structural risk involves single-source vulnerability for proprietary phosphorescent emitter materials. Distribution runs through direct supply channels from chemical firms to integrated display panel manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic semiconductor market is experiencing a platform-economics inflection, driven by the increasing interoperability between material science innovations and advanced manufacturing processes for flexible electronics.
For Market Incumbents:Secure long-term supply agreements for critical precursor chemicals to mitigate commodity price volatility. Invest in next-generation TADF material R&D to counter the threat of MicroLED substitution in premium displays. Consolidate intellectual property portfolios through strategic acquisitions, particularly in phosphorescent and TADF emitter technologies. Leverage existing relationships with major display manufacturers to co-develop bespoke materials optimized for their product roadmaps.
For New Entrants and Emerging Players:Anchor in underpenetrated application segments like organic photovoltaics or flexible sensors. Target the renewable energy sector in India and Southeast Asia, where government initiatives stimulate domestic electronics manufacturing. Focus on developing cost-effective, solution-processable polymer materials for large-area printable electronics. A viable go-to-market angle involves collaborating with original equipment manufacturers on integrated, low-cost solutions for smart textiles and IoT devices.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upward across advanced material synthesis and large-scale roll-to-roll manufacturing. Target acquisition archetypes include specialized chemical firms with deep expertise in novel organic compounds or intellectual property licensors with strong patent portfolios in next-generation display technologies. The signal to watch is the cost parity of organic photovoltaics with conventional solar cells. Long-term viability rests on material breakthroughs that extend operational lifetimes and enhance charge carrier mobility.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Roll-to-Roll Manufacturing Capacity | Enables cost-effective, high-volume production for flexible electronics and organic photovoltaics. |
| Invest in TADF Material Development | Reduces reliance on rare metals and improves OLED display efficiency for thinner panels. |
| Form Strategic IP Licensing Partnerships | Navigates complex patent landscapes and accelerates market access for innovative materials. |
| Develop Biocompatible Organic Sensors | Unlocks new applications in healthcare monitoring and wearable medical devices. |
| Standardize Material Purity Metrics | Simplifies material selection and accelerates adoption by device manufacturers globally. |
Research Approach
Findings reconcile primary fieldwork against secondary review of academic journals, patent databases, and regulatory filings. This included in-depth discussions with R&D chemists, display engineers, material procurement leads, and intellectual property attorneys across key regions. The analysis integrated both bottom-up market sizing and top-down validation approaches to ensure accuracy.
The analytical framework modeled market dynamics across the analysis window, segmenting by material type, device application, manufacturing technology, and end-user industry. An additional dimension included material purity grade, reflecting performance and cost drivers. Compound annual growth rates were derived through a weighted average of historical trends and projected future demand. Forecast inputs included OLED panel production forecasts and renewable energy investment trends.
Underlying assumptions cover material science advancements and regulatory stability, with deviation risk concentrated in disruptive display technologies or unforeseen IP litigation outcomes. Revision becomes warranted when MicroLED cost parity or new material degradation breakthroughs cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Semiconductor IP Market
Semiconductors
North America Semiconductor Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Global Computer Microchip Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Semiconductor Target Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Europe Semiconductor Market